
 Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market | 2026-2036
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market Foresight
Modular dosing regimens is repositioning patient adherence strategies across the EPI landscape. AbbVie Inc. leverages its established gastroenterology portfolio to sustain physician loyalty in enzyme replacement prescribing. Nordmark Arzneimittel GmbH & Co. KG anchors European supply chains with specialized porcine-derived enzyme extraction capabilities. First Wave BioPharma competes through differentiated acid-resistant capsule technologies designed for post-surgical pancreatic insufficiency populations.
Exocrine pancreatic insufficiency therapeutics and diagnostics encompass enzyme replacement formulations, fecal elastase immunoassays, and nutritional intervention protocols targeting maldigestion from diminished pancreatic enzyme secretion. Pancreatic enzyme replacement therapy dominates current prescription volumes due to established efficacy in cystic fibrosis and chronic pancreatitis management. Diagnostic kits represent the fastest-expanding segment as non-invasive fecal biomarker testing displaces invasive secretin-stimulated endoscopy in first-line evaluation. Nutritional supplements occupy a mature margin pool where reimbursement ambiguity constrains premium positioning despite growing dietitian-led intervention protocols.
FDA orphan drug incentives and EMA pediatric investigation plans jointly shape clinical trial investment and market access timelines for novel EPI therapeutics. The FDA's bioequivalence requirements for pancreatic enzyme products enforce stringent manufacturing standards that limit generic substitution and preserve originator pricing power. Stakeholders must monitor evolving NICE technology appraisals in the United Kingdom and Germany's G-BA benefit assessments, as these reimbursement gatekeepers increasingly demand head-to-head non-inferiority data against established porcine-derived standards before granting premium formulary placement.
Market Dynamics
Fecal elastase testing is compressing diagnostic timelines and redirecting patient volumes from invasive endoscopy toward point-of-care immunoassays, fundamentally restructuring how gastroenterology practices triage suspected EPI cases.
Growth Catalysts
- FDA orphan drug incentives:Accelerated approval pathways reduce clinical trial investment timelines for novel pancreatic enzyme formulations targeting rare genetic etiologies.
- Post-surgical pancreatic insufficiency populations:Rising Whipple procedure volumes and chronic pancreatitis case detection are expanding addressable patient pools for enzyme replacement therapy.
- Germany's G-BA benefit assessments:Favorable reimbursement frameworks for prescription-grade PERT products sustain premium pricing and physician prescribing loyalty.
Market Restraints
- Porcine-derived enzyme supply concentration:Nordmark Arzneimittel and limited European extraction facilities create single-source vulnerability for active pharmaceutical ingredient supply.
- FDA bioequivalence manufacturing standards:Stringent lot-to-lot variability requirements for pancreatic enzyme products block generic substitution and preserve originator pricing power.
- Reimbursement ambiguity for nutritional supplements:Dietitian-led intervention protocols lack consistent payer coverage, constraining premium positioning despite clinical utility.
Strategic Opportunities
- Underpenetrated India diagnostic infrastructure:Non-invasive fecal biomarker testing offers first-line evaluation capacity where endoscopy access remains limited.
- Acid-resistant capsule technology convergence:Enteric coating innovations combined with pH-targeted release profiles address post-surgical gastric pH variability.
- NICE technology appraisals in the United Kingdom:Head-to-head non-inferiority data requirements create pathway for differentiated formulations to secure premium formulary placement.
Industry Challenges
- Specialized gastroenterology talent scarcity:EPI diagnosis and enzyme titration protocols require advanced training that outpaces fellowship program output.
- EMA pediatric investigation plan compliance timelines:Extended juvenile toxicology studies delay market access for age-appropriate dosing formulations.
- Secretin-stimulated endoscopy infrastructure reconfiguration:Capital-intensive procedure suites face utilization pressure as non-invasive alternatives gain adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market |
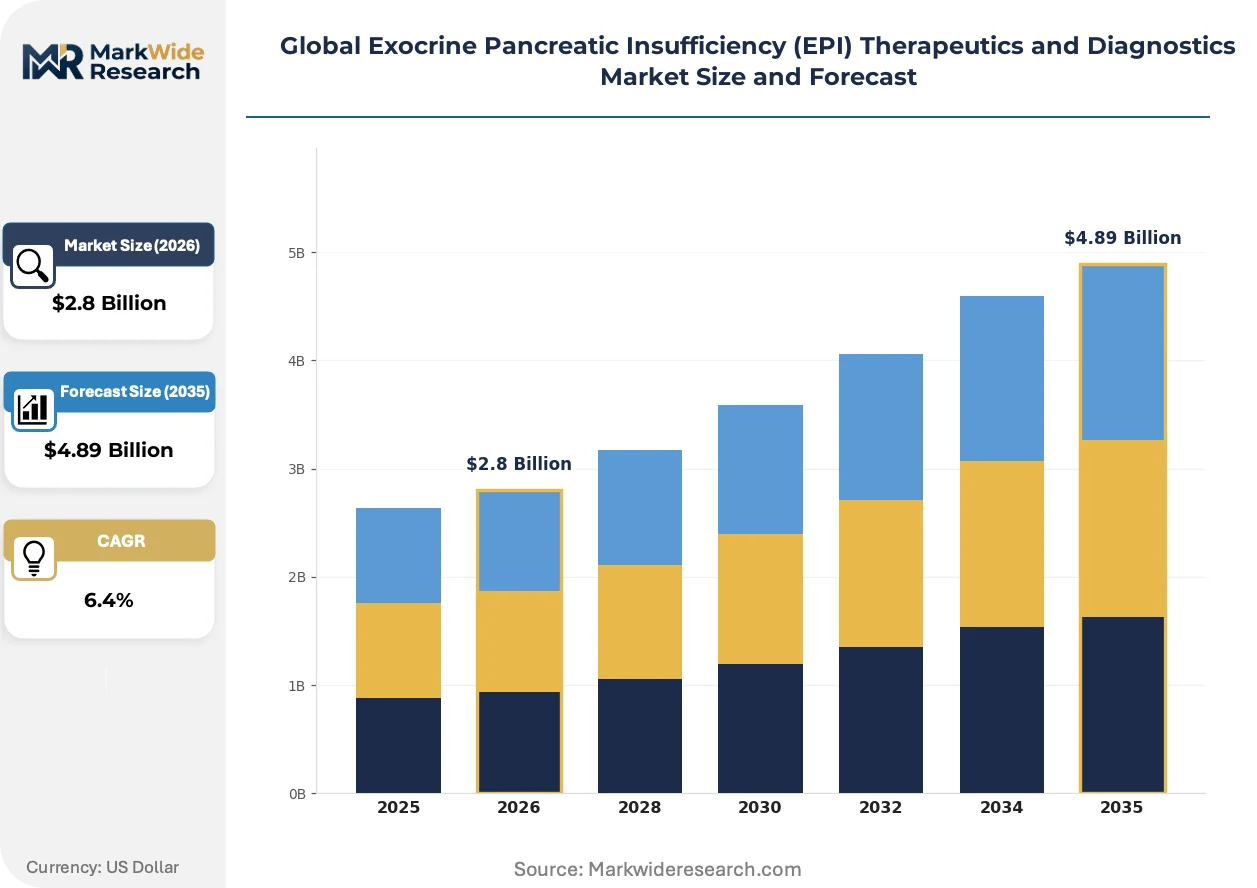
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
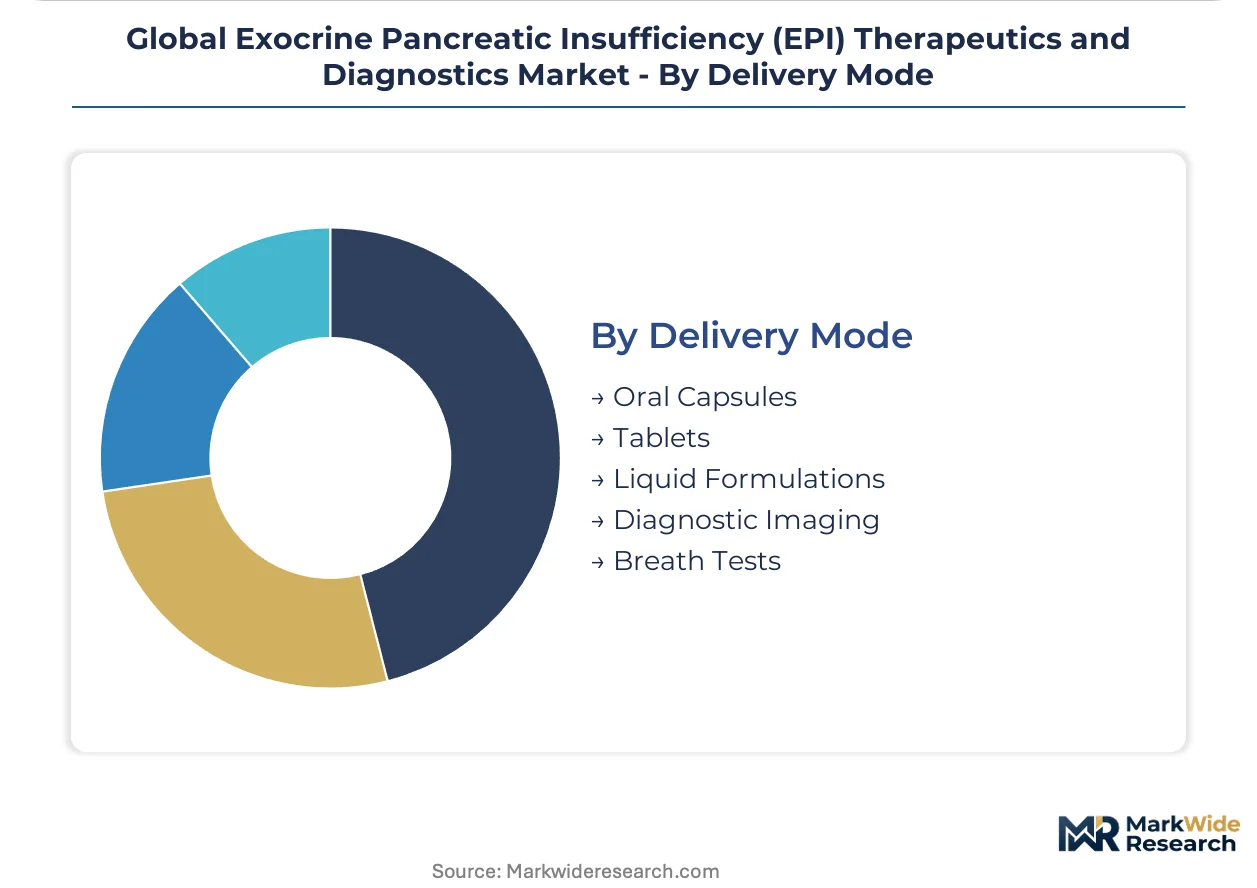
| Segmentation | Product Type: Pancreatic Enzyme Replacement Therapy, Diagnostic Kits, Nutritional Supplements, Acid Reducers Therapy Area: Cystic Fibrosis, Chronic Pancreatitis, Pancreatic Cancer, Post-surgical Conditions End User: Specialty Clinics, Diagnostic Laboratories, Pharmaceutical Companies, Nutrition Centers Delivery Mode: Oral Capsules, Tablets, Liquid Formulations, Diagnostic Imaging, Breath Tests |
| Companies Covered | AbbVie Inc., Nestlé Health Science, Abbott Laboratories, Nordmark Arzneimittel GmbH & Co. KG, Digestive Care Inc., Janssen Pharmaceuticals, Viatris Inc., First Wave BioPharma, Chiesi Farmaceutici, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market Shifts & Advancements
Diagnostic automation and personalized dosing algorithms are compressing the gap between symptom onset and therapeutic intervention, shifting competitive advantage toward integrated testing-to-treatment platforms.
Microencapsulated enzyme formulations with dual-release kinetics are integrating pH-responsive polymers and lipid-based coating systems to protect against gastric degradation while enabling proximal small bowel activation. Post-gastrectomy and pancreaticoduodenectomy patients are adopting these platforms at accelerating rates. The technology is integrating real-time dosing feedback from fecal fat quantification, enabling dynamic titration protocols that reduce steatorrhea persistence.
EMA's pediatric investigation plans and FDA's orphan drug designation pathway are jointly mandating age-stratified efficacy trials that extend development timelines but expand label claims. Formulation sponsors now face parallel juvenile toxicology requirements across both jurisdictions. Pediatric cystic fibrosis centers in Germany and the United Kingdom are responding by establishing dedicated enzyme monitoring protocols that align with regulatory endpoints.
Gastroenterology clinics are unbundling diagnostic testing from therapeutic prescribing, creating standalone fecal elastase service lines that compete with hospital laboratory networks. Independent reference laboratories in the United States are capturing outpatient volume through direct-to-physician result portals that bypass traditional pathology intermediaries. This channel fragmentation is most visible in metropolitan markets where gastroenterology group practices operate captive endoscopy centers.
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market Segmentation
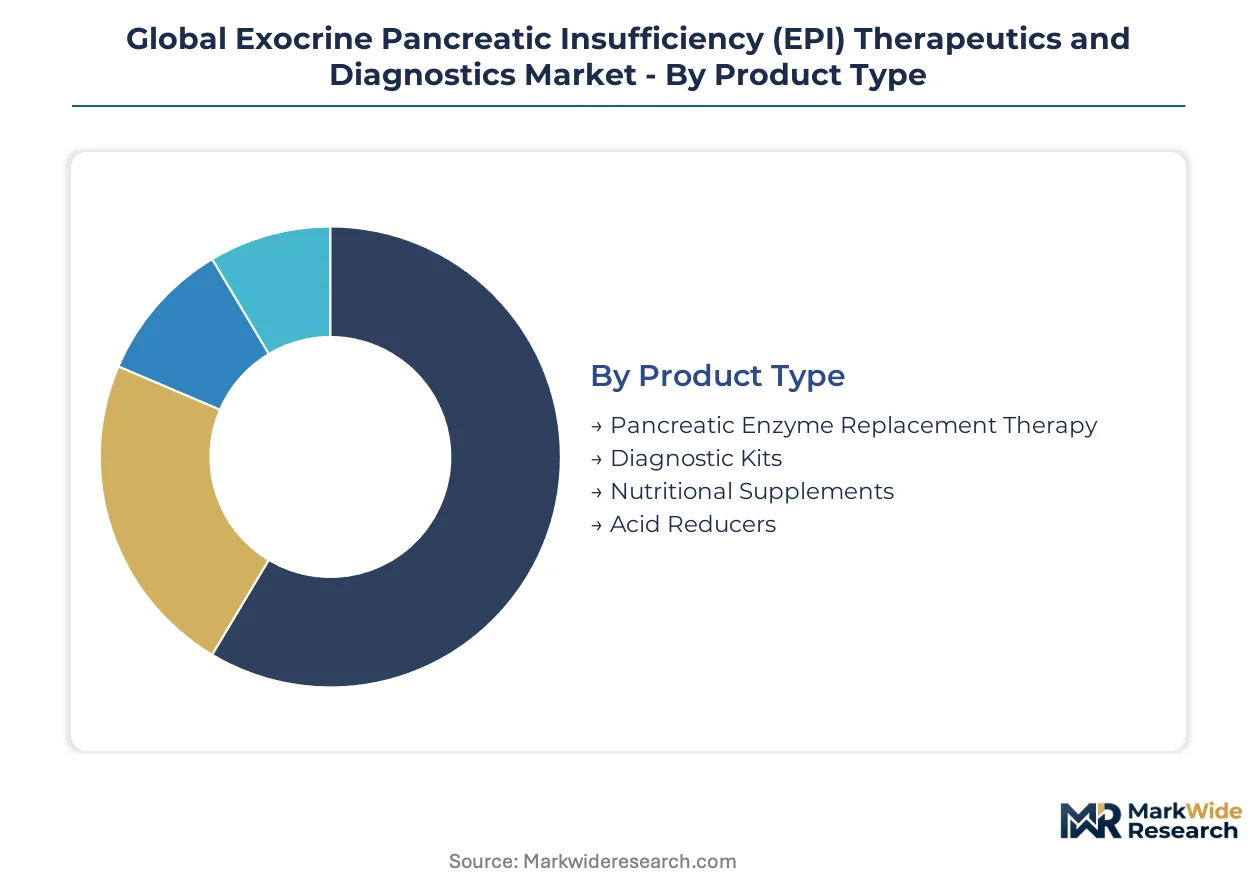
EPI market segmentation reflects divergent regulatory pathways across therapeutics and diagnostics. Product categories face distinct FDA bioequivalence and EMA pediatric investigation mandates. Therapy areas align with orphan drug incentives and specialized reimbursement frameworks.
Product Type:
FDA bioequivalence requirements apply most stringently to enzyme formulations, while diagnostic kits follow CLIA and IVDR pathways. Nutritional supplements occupy a regulatory gray zone with minimal premarket scrutiny.
- Pancreatic Enzyme Replacement Therapy:Porcine-derived lipase, protease, and amylase formulations require lot-to-lot variability controls under FDA guidance. Demand concentrates in Germany's G-BA reimbursement system and US cystic fibrosis centers where prescription-grade PERT maintains premium positioning against limited generic substitution.
- Diagnostic Kits:Fecal elastase immunoassays and 13C-mixed triglyceride breath tests carry CE marking under EU IVDR and FDA 510(k) clearance requirements. Point-of-care adoption is accelerating in metropolitan US gastroenterology practices seeking to bypass hospital laboratory networks.
- Nutritional Supplements:Dietitian-formulated enzyme adjuncts and medium-chain triglyceride products face minimal premarket approval but suffer reimbursement ambiguity across US commercial payers.
- Acid Reducers:Proton pump inhibitors and H2 antagonists prescribed alongside PERT require standard FDA NDA or ANDA pathways without specialized pancreatic indications.
Leading the category by volume: Pancreatic Enzyme Replacement Therapy. Growing fastest: Diagnostic Kits.
Therapy Area:
Orphan drug designation concentration varies sharply across indications, shaping clinical trial investment and label expansion strategies.
- Cystic Fibrosis:CFTR mutation-specific EPI manifestations command priority FDA breakthrough therapy and EMA PRIME designations. Pediatric investigation plan mandates from EMA extend development timelines but secure age-stratified labeling for pancreatic enzyme formulations.
- Chronic Pancreatitis:Alcohol-induced and idiopathic variants drive adult enzyme titration protocols in US gastroenterology clinics. Germany's Nordmark Arzneimittel anchors supply contracts for this volume-heavy segment.
- Pancreatic Cancer:Whipple procedure-related insufficiency creates post-surgical enzyme demand with distinct gastric pH challenges requiring acid-resistant capsule technologies.
- Post-surgical Conditions:Distal pancreatectomy and total pancreatectomy populations require lifelong enzyme support with dosing algorithms calibrated to residual pancreatic function.
Highest regulatory incentive capture: Cystic Fibrosis. Steepest procedure-volume expansion: Post-surgical Conditions.
End User:
Procurement authority fragmentation separates clinical decision-makers from purchasing agents across channel types.
- Specialty Clinics:US gastroenterology group practices with captive endoscopy centers control enzyme prescribing and fecal elastase ordering through integrated electronic health record systems.
- Diagnostic Laboratories:Independent reference laboratories in the United States compete with hospital networks through direct-to-physician result portals.
- Pharmaceutical Companies:Contract manufacturing organizations and formulation sponsors source porcine-derived active pharmaceutical ingredients from Nordmark Arzneimittel's European extraction facilities.
- Nutrition Centers:Dietitian-led intervention protocols in Germany and the United Kingdom face inconsistent payer coverage despite clinical utility in malabsorption management.
Dominant procurement authority: Specialty Clinics. Channel growth leader: Diagnostic Laboratories.
Delivery Mode:
Formulation technology differentiation centers on gastric protection and release kinetics rather than route of administration.
- Oral Capsules:Enteric-coated microspheres and mini-microspheres dominate prescription volumes with pH-targeted dissolution at pH 5.5-6.0 in the proximal small bowel.
- Tablets:Compressed enzyme formulations face bioavailability disadvantages against microencapsulated alternatives but retain cost-sensitive market presence.
- Liquid Formulations:Pediatric and gastrostomy-dependent populations require acid-stable liquid enzyme preparations with documented stability profiles.
- Diagnostic Imaging:Secretin-stimulated magnetic resonance cholangiopancreatography and endoscopic ultrasound face utilization pressure from non-invasive alternatives.
- Breath Tests:13C-mixed triglyceride and 13C-hiolein tests provide functional pancreatic exocrine assessment without stool collection requirements.
Volume concentration: Oral Capsules. Technology innovation focus: Breath Tests.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical manufacturing zones in Bavaria and North Rhine-Westphalia concentrate European enzyme extraction capacity. FDA-designated orphan drug zones in Massachusetts and North Carolina accelerate clinical trial infrastructure for rare disease indications. India's pharmaceutical special economic zones in Telangana and Gujarat incubate diagnostic kit manufacturing for export markets.
United States
Cystic fibrosis center density in Boston and Philadelphia drives prescription-grade PERT volumes. FDA orphan drug incentives compress approval timelines for novel pancreatic enzyme formulations. The Research Triangle Park corridor anchors diagnostic kit manufacturing for fecal elastase immunoassays.
Germany
G-BA reimbursement frameworks sustain premium pricing for prescription enzyme products. EMA pediatric investigation plans mandate age-stratified trials that extend development timelines. Nordmark Arzneimittel's Uetersen extraction facility anchors European porcine-derived active pharmaceutical ingredient supply.
United Kingdom
NICE technology appraisals demand head-to-head non-inferiority data for formulary placement. Pediatric cystic fibrosis centers in London and Manchester establish dedicated enzyme monitoring protocols. Independent reference laboratories in the Southeast compete through direct-to-physician result portals.
India
Underpenetrated diagnostic infrastructure creates demand for non-invasive fecal biomarker testing. CDSCO regulatory pathways for in vitro diagnostics streamline kit approval for domestic manufacturers. Hyderabad's pharmaceutical cluster incubates point-of-care immunoassay production for regional export.
Japan
PMDA consultation programs accelerate novel enzyme formulation reviews for post-surgical populations. METI funding for rare disease therapeutics supports domestic clinical trial infrastructure. The Kansai region's medical device cluster advances breath test technology for functional pancreatic assessment.
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the EPI therapeutics and diagnostics landscape. The market exhibits tiered concentration with established gastroenterology portfolios anchoring enzyme replacement prescribing. Three archetypes dominate: diversified pharmaceutical conglomerates with broad therapeutic portfolios, specialized enzyme extraction and formulation houses, and diagnostic-focused biotechnology ventures. Capacity expansion in porcine-derived active pharmaceutical ingredients and technology licensing for acid-resistant capsule formulations represent the dominant competitive moves.
Among diversified pharmaceutical conglomerates, AbbVie Inc. exemplifies portfolio breadth in gastroenterology therapeutics. Specialized enzyme extraction capabilities concentrate with Nordmark Arzneimittel GmbH & Co. KG, which occupies a position as the anchor European supplier. First Wave BioPharma represents the biotechnology archetype focused on differentiated delivery technologies for post-surgical patient populations.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Nestlé Health Science |
| Abbott Laboratories |
| Nordmark Arzneimittel GmbH & Co. KG |
| Digestive Care Inc. |
| Janssen Pharmaceuticals |
| Viatris Inc. |
| First Wave BioPharma |
| Chiesi Farmaceutici |
| Others |
Supply & Pricing Matrix
Microencapsulated enzyme formulations with dual-release kinetics are compressing manufacturing cost curves while concentrating production expertise among European extraction specialists, simultaneously reshaping cost economics and supply concentration across prescription-grade PERT markets. FDA bioequivalence requirements enforce lot-to-lot variability controls that preserve originator pricing power against generic substitution, embedding supply-chain rigidity directly into commercial terms.
Pricing Analysis
Short lead-time premiums for porcine-derived active pharmaceutical ingredients command contract-based long-term offtake structures with penalty clauses for delivery delays, while spot inventory trades at discounts reflecting single-source supply risk. Three-tier pricing structure across prescription-grade, hospital-contract, and institutional procurement levels differentiates by FDA certification tier and volume scale. Pricing pressure stems from Germany's G-BA reference pricing mechanisms and US formulary exclusion threats. Hospital procurement committees demonstrate highest price sensitivity; cystic fibrosis centers with dedicated enzyme monitoring protocols exhibit lowest sensitivity due to clinical protocol lock-in.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical special economic zones are reshaping diagnostic kit sourcing, incentivizing Hyderabad-based manufacturers to substitute imported assay components with locally validated alternatives. Porcine-derived enzyme extraction concentrates in Germany, Denmark, and the Netherlands, with Nordmark Arzneimittel's Uetersen facility anchoring European API supply. Raw material dependencies center on porcine pancreas sourcing, enteric coating polymers, and pH-responsive polymer feedstocks. Single-source vulnerability for specialized extraction capacity represents the dominant structural risk. Distribution runs through hospital pharmacy networks, specialty clinic direct purchasing, and independent reference laboratory procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into porcine sourcing and captive enzyme extraction capacity is emerging as the decisive competitive race, with formulation sponsors pursuing backward control over active pharmaceutical ingredient supply to defend margin structures against supply shocks.
For Market Incumbents: Lock in multi-year porcine pancreas supply contracts with Nordic abattoir networks before competitor offtake absorbs available feedstock. Expand captive extraction capacity in Germany's pharmaceutical manufacturing zones to insulate against Nordmark Arzneimittel's single-source vulnerability. Prioritize FDA bioequivalence certification investments for next-generation acid-resistant capsule platforms to extend originator pricing protection against emerging microencapsulation specialists.
For New Entrants and Emerging Players: Begin with India's underpenetrated diagnostic infrastructure, where CDSCO-streamlined IVD pathways and limited endoscopy access create first-mover positioning for fecal elastase point-of-care platforms. Target metropolitan US gastroenterology group practices with captive endoscopy centers, bypassing hospital laboratory network intermediaries through direct-to-physician result portals. Pursue licensing partnerships with established European enzyme extraction houses rather than greenfield capacity buildout.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking gastroenterology portfolio breadth, with valuation premia attaching to acid-resistant delivery technology IP and pediatric investigation plan completion status. Long-term viability across the analysis window hinges on regulatory exclusivity duration and reimbursement pathway security. Acquisition target archetype: specialized enzyme formulation houses with completed EMA pediatric investigation plans and differentiated pH-targeted release profiles. The signal to watch is FDA orphan drug designation grant velocity for novel genetic etiology targets, indicating pipeline competition intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Porcine Sourcing | Captive pancreas supply from Nordic abattoir networks secures API feedstock against competitor offtake. |
| Pediatric Investigation Plan Completion | EMA-mandated juvenile toxicology studies extend label claims to cystic fibrosis pediatric populations. |
| Point-of-Care Diagnostic Launch | Fecal elastase immunoassay platforms bypass hospital laboratory networks in US metropolitan markets. |
| Acid-Resistant Capsule Technology Licensing | pH-targeted release profiles address post-surgical gastric pH variability in Whipple procedure patients. |
| Orphan Drug Designation Pursuit | FDA accelerated approval pathways compress clinical trial timelines for rare genetic EPI etiologies. |
Research Methodology
Document review covered FDA orphan drug designation filings, EMA pediatric investigation plan submissions, and Germany's G-BA benefit assessment protocols, complemented by interviews with drug development executives at formulation sponsors, regulatory affairs leads managing bioequivalence submissions, hospital procurement managers overseeing PERT formularies, and payer access specialists navigating US commercial coverage determinations. Secondary validation drew from ClinicalTrials.gov enrollment data, CMS Medicare Part D utilization statistics, and hospital GPO contract databases. Bottom-up patient volume estimates triangulated against top-down prescription audit data across the analysis window.
Historical prescription volume trajectories cross-referenced against expert panel input from cystic fibrosis center directors and gastroenterology clinic administrators informed the analytical framework. Segmentation dimensions modeled include therapy area, delivery mode technology tier, end-user procurement channel, and regional regulatory cluster. CAGRs derived from log-linear trend fitting across the projection horizon, with EMA pediatric investigation plan compliance timelines and FDA bioequivalence lot-to-lot variability standards as industry-specific forecast inputs.
Underlying measurement precision varies by segment; diagnostic kit volume estimates carry tighter precision than nutritional supplement revenue projections due to reimbursement ambiguity. Forecasts reflect assumptions regarding G-BA pricing continuity, FDA generic substitution barriers, and porcine-derived enzyme supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Infectious Respiratory Disease Diagnostics Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Global Chlamydia Infection Diagnostics Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
In Vitro Diagnostic (IVD) Reagent Market
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
Multiplex Molecular Diagnostics Market