
 North America Negative Pressure Wound Therapy Market | 2026-2036
North America Negative Pressure Wound Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Negative Pressure Wound Therapy Market Analytics
A capital-intensity divergence between integrated manufacturers and device-assemblers is reorganizing competitive tiers in North America. Smith & Nephew leverages in-house foam dressing production to capture margin pools upstream of the pump unit. Cardinal Health sustains broad distribution reach across acute and post-acute channels, competing on logistics density rather than device innovation. Mölnlycke Health Care anchors its position through advanced wound care specialization, extending R&D focus beyond hardware to dressing interfaces.
Negative Pressure Wound Therapy applies sub-atmospheric pressure, typically negative 125 mmHg, through sealed foam or gauze dressings to accelerate granulation tissue formation and wound closure. The technology evacuates exudate, reduces edema, and stabilizes the wound environment for complex surgical wounds, diabetic foot ulcers, and pressure injuries. Traditional NPWT devices still occupy the largest installed base in hospitals, though single-use devices are expanding fastest as infection control protocols tighten and capital budgets shift toward disposable economics. Homecare settings represent the most concentrated demand growth vector, driven by Medicare reimbursement expansion for hospital-at-home wound management.
FDA 510(k) clearance requirements govern device safety and efficacy claims, while CMS reimbursement codes determine commercial viability across care settings. The Joint Commission accreditation standards for home medical equipment suppliers add a layer of operational compliance that shapes market access for new entrants. Stakeholders must monitor CMS proposed rulemaking on remote patient monitoring bundling, as payment architecture decisions will determine whether portable NPWT penetrates homecare at scale or remains concentrated in institutional settings.
Market Dynamics
Medicare reimbursement expansion for hospital-at-home programs is compressing the traditional acute-care channel for NPWT devices, forcing manufacturers to restructure distribution networks around durable medical equipment suppliers and home health agencies.
Growth Catalysts
- CMS Hospital-at-Home Waiver:The Centers for Medicare & Medicaid Services expanded reimbursement for acute-level wound care delivered in residential settings, directly reimbursing portable NPWT for diabetic foot ulcers and pressure injuries.
- Single-use disposable economics:Infection control protocols in ambulatory surgery centers are accelerating capital budget shifts toward disposable pump systems that eliminate cross-contamination risk and sterilization overhead.
- Chronic wound prevalence:Rising diabetic populations across the United States and Canada are expanding the addressable patient base for long-duration negative pressure therapy.
Market Restraints
- Pump unit cost concentration:Precision vacuum pump manufacturing concentrates in specialized medical device component suppliers, creating input cost vulnerability when semiconductor or battery supply tightens.
- Canister disposal regulation:EPA medical waste classification for exudate-containing canisters imposes hazardous material handling costs that inflate total cost of ownership for high-exudate wound applications.
- Advanced wound dressing substitutes:Bioactive dressings and enzymatic debridement products compete for reimbursement dollars in Stage III pressure injury protocols.
Strategic Opportunities
- Mexico manufacturing expansion:Nearshoring of pump assembly and canister molding to Baja California and Tamaulipas reduces landed cost for US distribution while maintaining FDA quality system compliance.
- Remote patient monitoring convergence:Integration of pressure sensors and cellular connectivity into portable NPWT units enables real-time adherence monitoring and predictive intervention by wound care nurses.
- Veterans Health Administration centralized procurement:The VA's national formulary standardization creates volume concentration opportunities for manufacturers qualifying under its competitive bidding framework.
Industry Challenges
- Home medical equipment supplier accreditation:The Joint Commission's evolving standards for durable medical equipment providers require operational investments that strain smaller regional distributors.
- Legacy EHR integration complexity:Wound documentation and device utilization tracking must interface with fragmented electronic health record systems across hospital, skilled nursing, and home health settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Negative Pressure Wound Therapy Market |
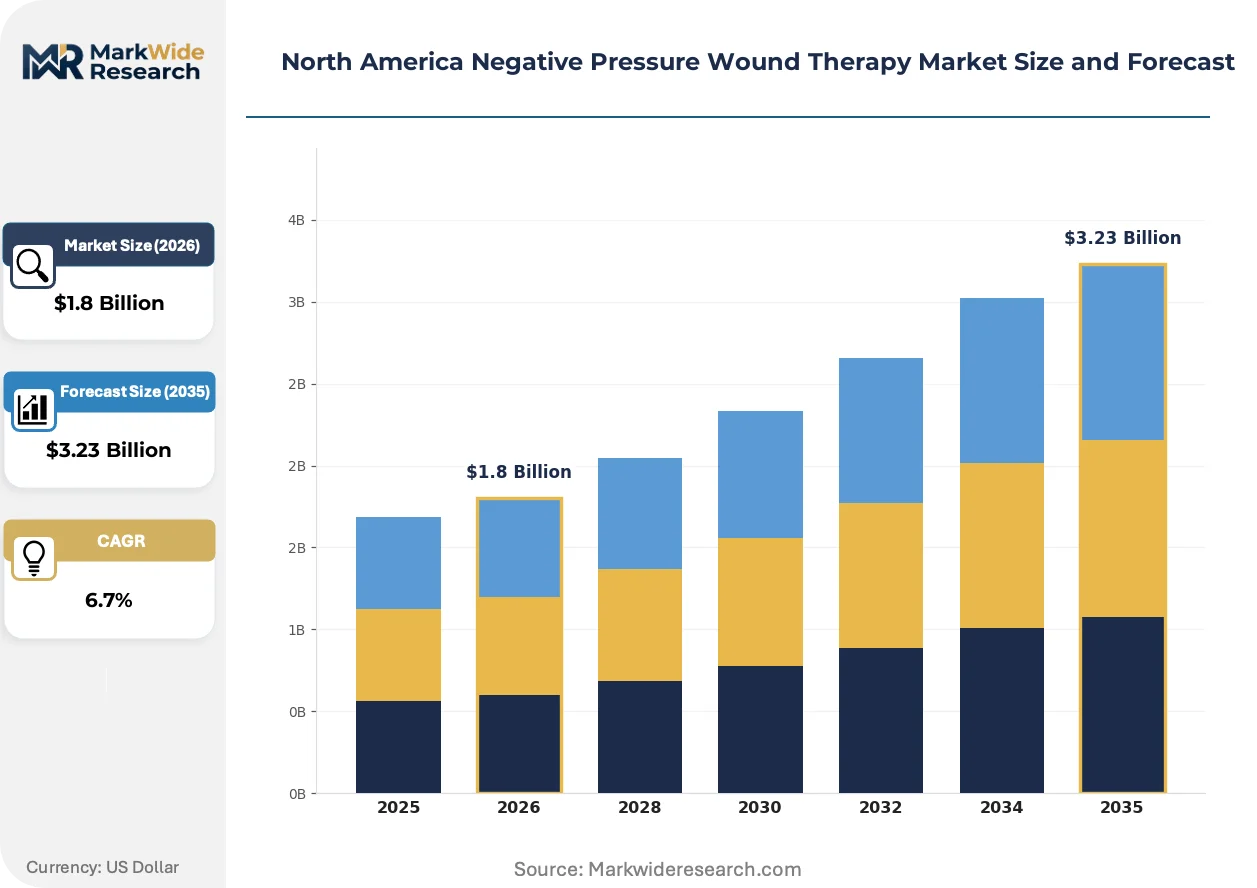
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional NPWT Devices, Single Use Devices, Automated NPWT Systems, Non-Mechanical Devices End User: Hospitals, Homecare Settings, Long-term Care Facilities, Outpatient Clinics Application: Burns, Surgical Wounds, Diabetic Foot Ulcers, Pressure Ulcers Technology: Vacuum-assisted Closure, Portable NPWT, Continuous NPWT, Intermittent NPWT |
| Companies Covered | Solventum, Smith & Nephew, Cardinal Health, Mölnlycke Health Care, ConvaTec, 3M, Medela, Talley Group, DeRoyal Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Negative Pressure Wound Therapy Market Evolving Landscape
Device miniaturization and disposable system architecture are collapsing the traditional distinction between institutional and homecare NPWT platforms, enabling care setting migration that was technically impractical five years ago.
Portable single-use negative pressure systems are fragmenting the installed base of reusable pump consoles. These battery-operated, canister-integrated devices deliver continuous or intermittent negative pressure without tethering patients to wall outlets. Home health agencies in Texas and Florida are deploying them for early hospital discharge of post-operative flap patients. The technology is fragmenting capital equipment revenue models toward per-procedure consumable economics that favor high-volume, low-margin manufacturing.
FDA 510(k) clearance pathway refinements for substantially equivalent portable devices are compressing time-to-market for mechanical modifications. The agency's evolving guidance on battery safety and electromagnetic compatibility testing is raising documentation burdens for software-controlled vacuum algorithms. Canadian manufacturers seeking US market access are responding by front-loading biocompatibility testing and predicate device analysis in their regulatory strategy.
Consolidated procurement through group purchasing organizations is compressing vendor margins and unbundling after-sales service from device pricing. Hospital systems in the Midwest are centralizing NPWT selection through standardized value analysis committees that prioritize interchangeability across dressing types. This concentration is most visible in integrated delivery networks where supply chain directors negotiate multi-year sole-source agreements covering pumps, canisters, and foam dressings.
North America Negative Pressure Wound Therapy Market Segmentation
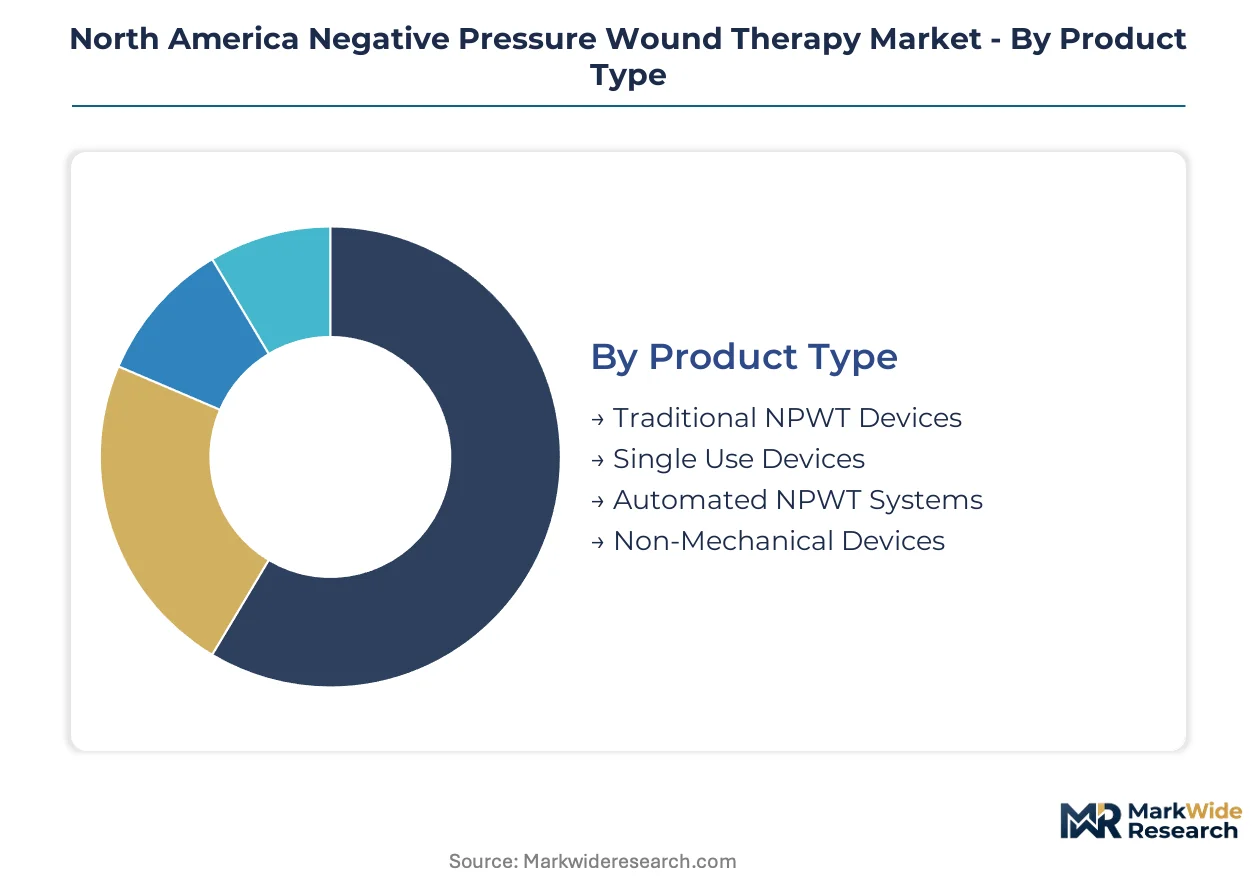
NPWT market segmentation reveals how reimbursement architecture and care setting migration reshape competitive positioning across device categories. Understanding these divisions exposes where FDA clearance pathways and CMS coding decisions concentrate commercial opportunity.
Product Type:
FDA 510(k) clearance requirements diverge sharply between reusable console systems and disposable pump architectures, creating distinct regulatory investment thresholds for manufacturers.
- Traditional NPWT Devices:Reusable pump consoles with detachable canisters deliver negative pressure through wall outlet power or rechargeable batteries. Hospital systems in the United States deploy these for high-exudate surgical wounds where extended therapy duration justifies capital equipment amortization across multiple patients.
- Single Use Devices:Fully integrated disposable pumps with sealed canisters eliminate cross-contamination protocols. Ambulatory surgery centers in Texas and Florida favor these for infection control compliance and reduced sterilization overhead.
- Automated NPWT Systems:Software-controlled vacuum algorithms with pressure feedback loops adjust therapy parameters without clinician intervention.
- Non-Mechanical Devices:Spring-based or elastomeric mechanisms generate negative pressure without electrical components for low-resource settings.
Established volume favors Traditional NPWT Devices; emerging adoption favors Single Use Devices.
End User:
Reimbursement density varies dramatically across institutional and residential settings, with Medicare hospital-at-home waivers redirecting device procurement toward durable medical equipment channels.
- Hospitals:Acute care facilities maintain the largest installed base of reusable pump consoles. Surgical departments in US academic medical centers standardize on specific device platforms to streamline nursing training and supply chain procurement.
- Homecare Settings:Medicare reimbursement expansion for residential wound management drives portable device deployment. Home health agencies in California and New York coordinate with durable medical equipment suppliers for patient discharge continuity.
- Long-term Care Facilities:Skilled nursing facilities balance pressure injury protocols with limited on-site wound specialist availability.
- Outpatient Clinics:Wound care centers require rapid patient turnover compatible with single-use disposable economics.
Procurement concentration tilts toward Hospitals; patient volume migration accelerates fastest in Homecare Settings.
Application:
Clinical evidence requirements and reimbursement coding specificity create divergent market access conditions across wound etiologies.
- Diabetic Foot Ulcers:CMS coverage determination explicitly authorizes NPWT for Wagner Grade III and IV lesions when standard care fails. Endocrinology practices in the US Southwest deploy portable systems for limb salvage programs serving high-prevalence diabetic populations.
- Surgical Wounds:Post-operative dehiscence and flap procedures command premium reimbursement under surgical global periods. Plastic surgery departments prioritize devices with precise pressure control for graft viability.
- Burns:Thermal and chemical injuries require specialized dressing interfaces for irregular wound topography.
- Pressure Ulcers:Stage III and IV injuries in long-term care trigger survey penalties under CMS quality metrics.
Surgical Wounds anchor premium pricing; Diabetic Foot Ulcers expand the addressable patient base fastest.
Technology:
Patent landscapes and component supply chains differentiate mechanical vacuum systems from emerging portable architectures.
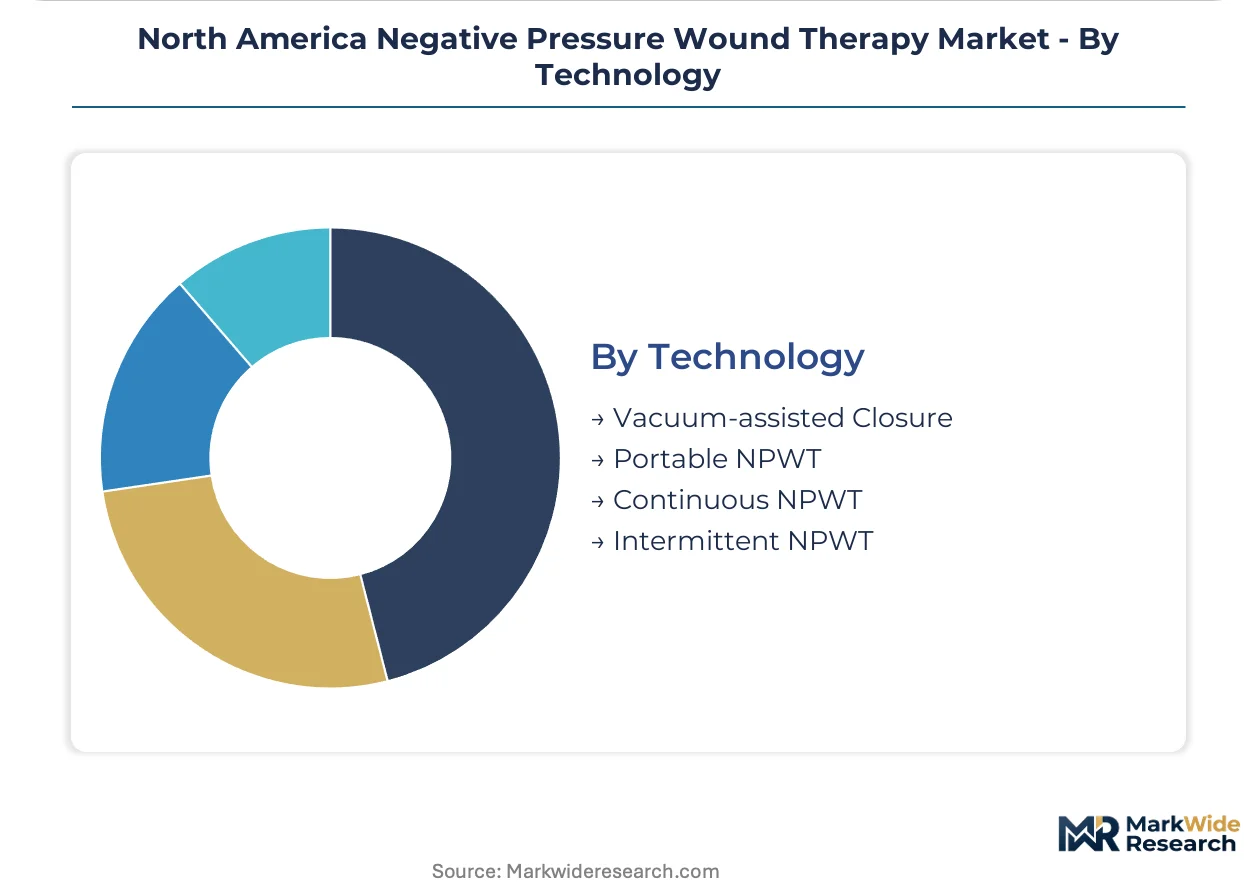
- Vacuum-assisted Closure:The foundational negative pressure mechanism using foam or gauze dressings with sealed film covers. Veterans Health Administration centralized procurement standardizes on these systems for formulary compliance.
- Portable NPWT:Battery-operated, wearable devices enable ambulatory patient mobility. Canadian home health programs in Ontario and British Columbia pilot these for rural patient access.
- Continuous NPWT:Uninterrupted negative pressure delivery dominates hospital protocols for acute wound stabilization.
- Intermittent NPWT:Cyclic pressure modulation promotes perfusion in ischemic wound beds.
Technology maturation centers on Vacuum-assisted Closure; miniaturization investment flows most aggressively into Portable NPWT.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the North American Negative Pressure Wound Therapy Market. US hospital systems negotiate aggressively on pump console pricing while Canadian provincial tenders emphasize total cost of ownership. Mexican private hospitals prioritize upfront device affordability over long-term service contracts.
United States
Hospital-at-home waiver expansion and chronic wound prevalence drive device procurement. FDA 510(k) clearance pathways govern portable NPWT market entry with evolving battery safety documentation requirements. Texas and Florida home health agencies deploy single-use systems for early surgical discharge programs.
Canada
Provincial health authorities consolidate NPWT procurement through centralized tender processes. Health Canada medical device licensing maintains alignment with FDA quality system standards for cross-border manufacturers. Ontario and British Columbia pilot portable NPWT programs targeting rural patient access gaps.
Mexico
Private hospital chains and medical tourism facilities anchor device demand in major metropolitan centers. COFEPRIS regulatory pathways for imported medical devices require local representation and Spanish-language labeling compliance. Baja California and Tamaulipas manufacturing clusters assemble pump components for US distribution under FDA quality agreements.
North America Negative Pressure Wound Therapy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America Negative Pressure Wound Therapy Market. The competitive structure organizes around three tiers: integrated wound care specialists controlling upstream dressing production, diversified health care conglomerates leveraging distribution density, and single-use device innovators capturing ambulatory surgery center volume. Dominant competitive moves include backward integration into foam dressing manufacturing and strategic partnerships with durable medical equipment suppliers for homecare channel access.
Among diversified health care suppliers, Cardinal Health and 3M exemplify scale-driven positioning through broad distribution reach across acute and post-acute channels. Smith & Nephew and Mölnlycke Health Care occupy specialist archetype positions, with the former representing integrated manufacturing control over dressing interfaces and the latter exemplifying advanced wound care R&D focus beyond hardware components. Solventum, as a recently independent entity, sits within the transitional tier between conglomerate scale and specialist depth.
| Leading Market Players |
|---|
| Solventum |
| Smith & Nephew |
| Cardinal Health |
| Mölnlycke Health Care |
| ConvaTec |
| 3M |
| Medela |
| Talley Group |
| DeRoyal Industries |
| Others |
Value Network & Pricing Analysis
Disposable pump systems replacing reusable console architectures are redrawing manufacturing footprints across Mexico and the United States while collapsing the service-revenue component that historically sustained margins. This substitution simultaneously compresses capital equipment pricing tiers and accelerates nearshoring investment to maintain cost competitiveness under FDA quality system requirements.
Pricing Analysis
After-sales service contracts and consumable canister replenishment generate the majority of lifetime customer value, though single-use devices are fragmenting this model toward per-procedure economics. Three-tier pricing structure across premium console systems, mid-range portable units, and economy disposable pumps reflects differentiation by pressure control precision and connectivity features. Cost compression in the disposable tier is intensifying because ambulatory surgery centers prioritize infection control compliance over device longevity. Group purchasing organizations exhibit the highest price sensitivity, while academic medical centers with standardized training protocols demonstrate lower elasticity.
Supply Chain Analysis
Inventory lead times for precision vacuum pumps and lithium-ion battery cells have extended due to semiconductor allocation constraints affecting medical device component suppliers. Pump assembly concentrates in Mexico's Baja California and Tamaulipas regions, with foam dressing production anchored in the United States and battery cells sourced from South Korea and Japan. Single-source vulnerability in specialized medical-grade polymer supply creates exposure to FDA material change notification requirements. Distribution runs through durable medical equipment suppliers for homecare channels and direct hospital system contracts for acute care procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against bioactive wound dressings and enzymatic debridement products competing for Stage III pressure injury reimbursement dollars. Incumbents must fortify their position against these advanced dressing substitutes while capturing the homecare migration enabled by CMS hospital-at-home waivers.
For Market Incumbents: Consolidate control over foam dressing supply through backward integration or captive supply agreements, as dressing interfaces differentiate pump systems beyond hardware specifications. Expand service infrastructure for remote patient monitoring integration to defend against portable device commoditization. The threat of reimbursement bundling with remote monitoring platforms makes software companion development a critical capability lever. For New Entrants and Emerging Players: Home medical equipment supplier accreditation gaps in rural Texas and Florida markets present white-space opportunity where incumbent coverage remains thin. Target these geographies through partnerships with regional durable medical equipment distributors rather than direct hospital system penetration. The most penetrable segment is single-use disposable deployment in ambulatory surgery centers seeking infection control compliance without capital equipment commitment. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors specialists with integrated dressing manufacturing over pure-play device assemblers. Long-term viability over the coming decade hinges on capturing the consumable revenue stream that single-use economics generate. Acquisition targets should demonstrate FDA 510(k) clearance capabilities and established durable medical equipment channel relationships. The signal to watch is CMS rulemaking on remote patient monitoring bundling, which would determine whether portable NPWT penetrates homecare at scale or remains institutionally concentrated.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance for portable devices with battery safety documentation accelerates time-to-market under evolving agency guidance. |
| Hospital System Partnership | Sole-source agreements with integrated delivery networks lock in multi-year pump, canister, and dressing procurement. |
| Software Companion Development | Pressure sensor integration with cellular connectivity enables real-time adherence monitoring for homecare reimbursement. |
| Reimbursement Strategy | Qualification under VA competitive bidding and CMS hospital-at-home waivers determines commercial viability across settings. |
| CE Marking Pathway | Canadian manufacturers leverage Health Canada alignment with FDA standards for cross-border market access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, CMS Medicare reimbursement filings, and hospital procurement contract records. The research incorporated structured interviews with wound care clinicians, biomedical engineers, GPO contracts managers, and durable medical equipment supplier executives. Secondary validation drew from The Joint Commission accreditation standards, EPA medical waste classification guidance, and Veterans Health Administration formulary documentation. Bottom-up patient volume modeling and top-down revenue triangulation ensured cross-verification of market sizing.
Segmentation dimensions modeled include product architecture, care setting, wound etiology, and technology type across the projection horizon. The analytical framework incorporated reimbursement code evolution, regulatory pathway refinement, and care setting migration patterns. CAGRs were derived from patient prevalence projections, procedure volume trends, and device replacement cycle analysis. Forecast inputs included diabetic population growth trajectories and hospital-at-home program expansion rates by state.
Forecasts assume regulatory continuity in FDA quality system requirements and CMS reimbursement architecture; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Wound Healing Supplement Market
Wound Care
Europe Wound Care Market
Wound Care
Global Wound Irrigation System Market
Wound Care
Australia Wound Care Management Devices Market
Wound Care
Maggot Debridement Market
Wound Care
Wound Retractor Market
Wound Care
Wound Closure Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Wound Care Biologics Market
Wound Care
Wound Skin Care Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Venous Ulcer Treatment Market
Wound Care
Negative Pressure Wound Therapy Market
Wound Care
Smart Bandages and Smart Wound Dressings Market