
 Global Wound Dressings Market | 2026-2036
Global Wound Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wound Dressings Market Intelligence
A transition from single-source contracts to multi-vendor procurement models within large hospital networks is recalibrating the competitive landscape. Smith & Nephew leverages its extensive portfolio in advanced wound management to secure these multi-product tenders. ConvaTec Group specializes in solutions for chronic conditions, differentiating on clinical evidence for specific applications like pressure ulcers. Mölnlycke Health Care competes on product innovation, particularly with its proprietary silicone adhesion technologies for sensitive skin applications.
Wound dressings are materials designed for direct contact with a wound to facilitate healing. They protect the site, manage exudate, and maintain a moist environment, with performance often defined by moisture vapor transmission rate (MVTR). Foam dressings lead in the advanced wound care space, addressing moderate to heavy exudate from surgical wounds and pressure ulcers. Alginate dressings are essential for highly exuding wounds, while hydrocolloids are preferred for drier chronic ulcers.
Market access is governed by stringent regulatory approvals, including the FDA's 510(k) pathway in the United States and the CE marking under the EU's Medical Device Regulation (MDR). These frameworks mandate rigorous testing for biocompatibility, sterility, and clinical efficacy before a product can be commercialized. Future success for manufacturers depends on demonstrating superior clinical outcomes while navigating increasingly cost-conscious healthcare reimbursement systems.
Market Dynamics
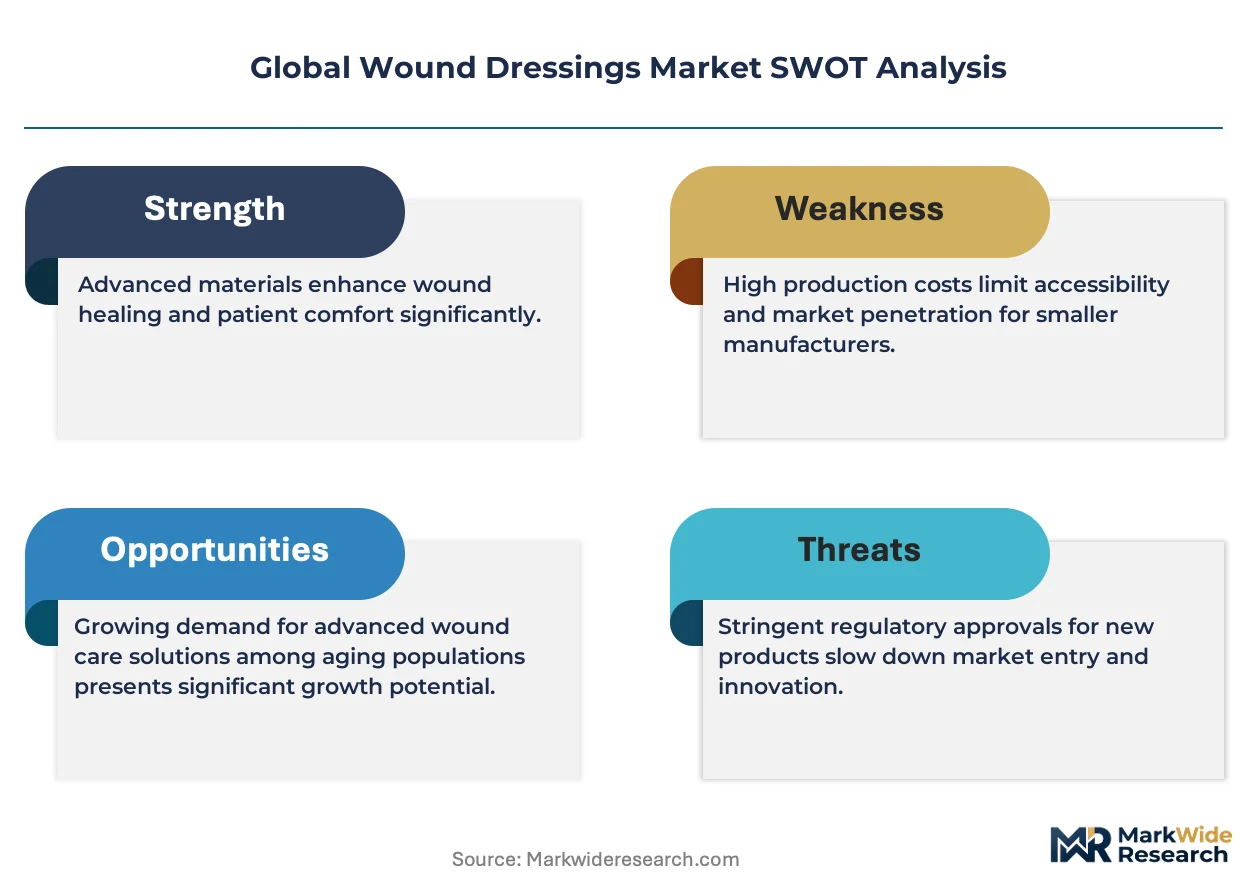
The market's primary dynamic is the tension between innovation in active healing technologies and the intensifying cost-containment pressures from healthcare reimbursement systems. This forces manufacturers to demonstrate not just clinical efficacy but also economic value through reduced healing times or lower complication rates.
Growth Catalysts
- Aging Global Demographics:The rising prevalence of chronic conditions such as diabetes and vascular diseases in aging populations, particularly in countries like Japan, directly increases the incidence of hard-to-heal wounds requiring advanced care.
- Shift to Home Healthcare:Policy and reimbursement changes encouraging treatment in home care and outpatient settings expand the market for dressings that are easy for patients or non-specialist caregivers to apply and manage.
- Advanced Material Science:Innovations in polymers, bioactive compounds, and fabric structures enable the development of dressings with superior exudate management, antimicrobial properties, and patient comfort, driving adoption over traditional gauze.
Market Restraints
- Stringent Reimbursement Policies:In many national healthcare systems, such as in Germany, reimbursement formularies for advanced wound dressings are restrictive, often favoring lower-cost traditional options unless a clear clinical necessity is proven.
- Intensified Regulatory Scrutiny:The EU's Medical Device Regulation (MDR) has elevated the requirements for clinical evidence and post-market surveillance, increasing the cost and time-to-market for new and existing products.
- Threat from Alternative Therapies:The adoption of capital equipment-based treatments like negative pressure wound therapy (NPWT) and advanced bio-therapeutics for complex wounds can displace the use of certain high-end dressings.
Strategic Opportunities
- Antimicrobial Dressing Innovation:Developing dressings with non-antibiotic antimicrobial agents, such as medical-grade honey or silver ions, addresses the critical need to prevent and manage wound infections without contributing to antibiotic resistance.
- Emerging Market Expansion:Significant unmet needs in large, developing economies like India and Brazil present long-term growth opportunities as healthcare infrastructure improves and access to advanced wound care expands.
- Digital Health Integration:There is a clear opportunity for smart dressings with embedded sensors that can monitor wound characteristics like pH or temperature and wirelessly communicate data to clinicians, enabling remote patient monitoring.
Industry Challenges
- Clinical Education Gap:The rapid pace of product innovation creates a continuous need to train clinicians on the appropriate selection and application of a wide array of specialized dressings to ensure optimal patient outcomes.
- Sterilization and Logistics:Maintaining sterility and managing the complex global logistics for products with varying shelf-lives and environmental sensitivities poses a significant operational challenge for manufacturers.
- Evidence Generation Costs:The high cost and complexity of conducting robust, large-scale randomized controlled trials required to prove the cost-effectiveness of premium products is a major barrier for smaller innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wound Dressings Market |
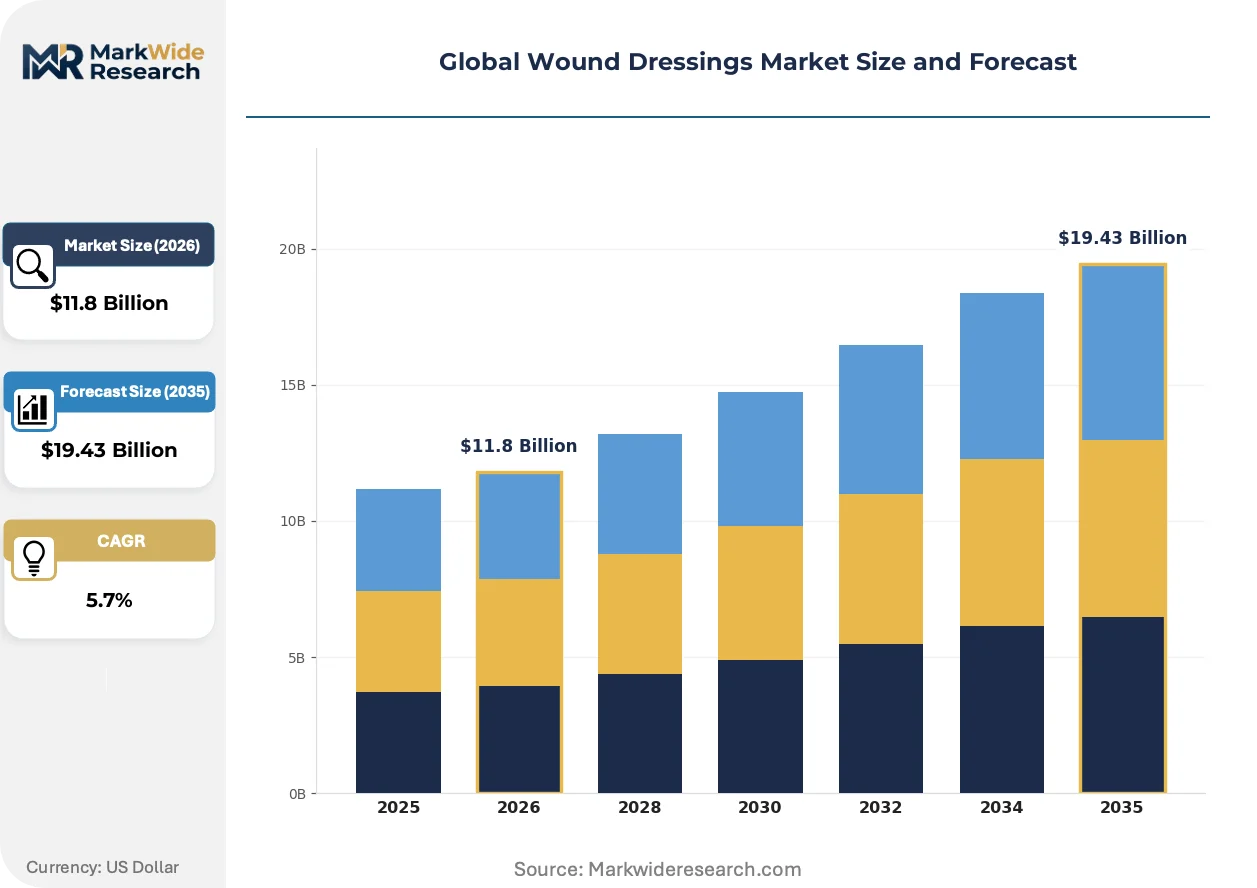
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid, Alginate, Foam, Film, Gauze Application: Burns Care, Surgical Wounds, Chronic Ulcers, Traumatic Injuries, Pressure Ulcers End User: Hospitals, Ambulatory Surgical Centers, Home Care, Specialty Clinics Material: Polyurethane, Silicone, Calcium Alginate, Hydrogel, Cotton |
| Companies Covered | Solventum Corporation, Smith & Nephew, ConvaTec Group, Mölnlycke Health Care, Coloplast, 3M, Cardinal Health, Integra LifeSciences, PAUL HARTMANN AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wound Dressings Market Strategic Shifts & Innovations
The convergence of material science and data connectivity is transforming wound dressings from passive coverings into active components of a therapeutic and monitoring system. This evolution prioritizes real-world evidence and integration into broader clinical workflows.
Bio-integrative scaffolds represent a significant technological leap. These dressings are engineered from materials like collagen or hyaluronic acid to provide a temporary matrix that supports cellular growth and tissue regeneration. Specialized surgical and chronic wound care centers are the primary adopters, though adoption is deliberate due to cost. This technology is unifying the functional roles of a medical device and a biologic therapy, creating a new class of regenerative wound care products.
Regulatory frameworks are increasingly emphasizing post-market data collection. The FDA's focus on Real-World Evidence (RWE) in the United States compels manufacturers to systematically gather and analyze data from routine clinical practice to validate long-term performance. Advanced wound dressings for chronic conditions such as diabetic foot ulcers are most affected, as RWE becomes a key differentiator for securing formulary access and supporting value-based contracts with providers.
A notable behavioral shift is occurring in how large healthcare organizations acquire wound care supplies. The traditional model of clinician-preference-driven purchasing is ceding ground to system-level procurement based on total cost of care and supply chain efficiency. This change favors vendors who can offer a broad portfolio, clinical education support, and inventory management solutions. This pattern is most pronounced within integrated delivery networks in the U.S. and national health systems like the UK's NHS.
Global Wound Dressings Market Segmentation
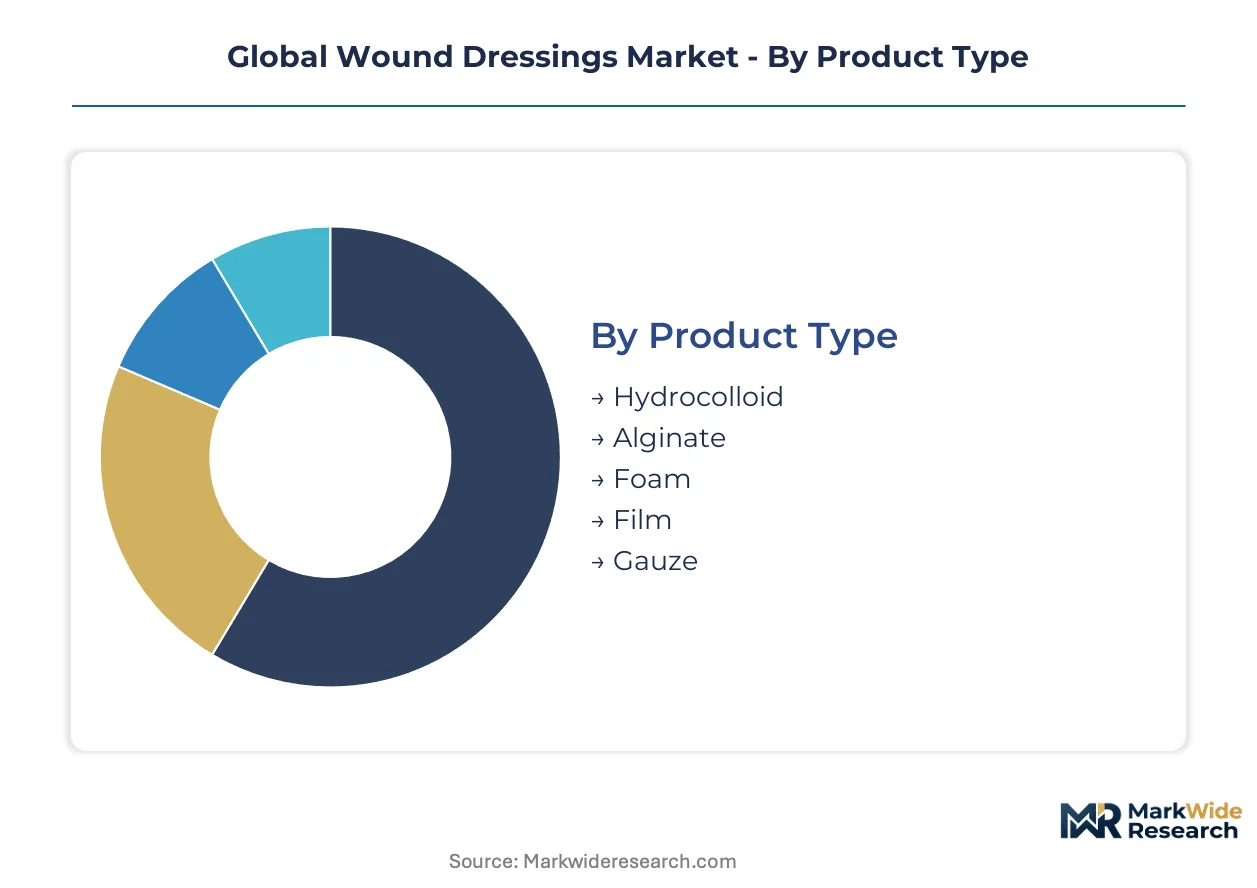
The Global Wound Dressings Market operates across diverse product types, applications, end-users, and materials, each influenced by distinct technological advancements and clinical requirements. Understanding these segments provides a granular view of demand patterns and competitive dynamics within the global healthcare landscape. Manufacturers strategically align their portfolios with specific segment needs to optimize market penetration and address varied patient populations.
Product Type:
The technological specifications of wound dressings define their primary function and suitability for different wound types and exudate levels.
- Foam:These dressings utilize highly absorbent polymer structures, effectively managing moderate to heavy exudate from surgical wounds and pressure ulcers. Their conformability and cushioning properties enhance patient comfort, driving adoption in hospital settings.
- Alginate:Derived from seaweed, alginate dressings form a gel upon contact with wound exudate, creating a moist healing environment and absorbing high volumes of fluid. They are essential for highly exuding wounds, particularly in chronic ulcer management in developed economies like Germany.
- Hydrocolloid:Hydrocolloid dressings contain gel-forming agents that maintain a moist wound environment, promoting autolytic debridement and protecting the wound from external contamination. They are preferred for drier chronic ulcers and superficial wounds.
- Film:Transparent polyurethane films provide a bacterial barrier and maintain a moist environment, allowing for visual inspection of the wound without removal. These dressings are frequently used for IV sites and superficial wounds.
- Gauze:Traditional gauze dressings offer basic wound coverage and absorption, serving as a cost-effective option for a wide range of minor wounds or as secondary dressings.
Mature deployment sits with Gauze. Newer deployment is concentrated in Foam.
Application:
The specific clinical use cases for wound dressings dictate product design and therapeutic focus, ranging from acute injuries to complex chronic conditions.
- Chronic Ulcers:This segment includes diabetic foot ulcers, venous leg ulcers, and pressure ulcers, which require prolonged and specialized wound care due to their complex pathology. Advanced dressings that manage exudate, prevent infection, and promote tissue regeneration are critical for these conditions, especially in aging populations in Japan.
- Surgical Wounds:Dressings for surgical wounds focus on protecting the incision site, managing post-operative exudate, and preventing infection to facilitate optimal healing. Hospitals and ambulatory surgical centers are primary demand drivers for these products.
- Burns Care:Specialized dressings for burns aim to protect damaged tissue, manage fluid loss, prevent infection, and facilitate epithelialization. Hydrocolloids and film dressings find application in superficial burns.
- Pressure Ulcers:Also known as bedsores, pressure ulcers necessitate dressings that provide cushioning, absorb exudate, and promote healing in vulnerable patients with limited mobility. Foam and alginate dressings are commonly used.
- Traumatic Injuries:This category encompasses dressings for cuts, lacerations, and abrasions, focusing on immediate protection, bleeding control, and infection prevention.
The market volume is dominated by Surgical Wounds. The fastest expansion trajectory is within Chronic Ulcers.
End User:
The care setting determines the purchasing patterns, product requirements, and logistical considerations for wound dressings, from institutional to individual patient use.
- Home Care:This segment involves dressings designed for easy application by patients or non-specialist caregivers, supporting the shift towards outpatient treatment. The aging global population significantly drives demand for home care wound management solutions.
- Hospitals:Hospitals represent a major end-user segment, procuring a broad spectrum of wound dressings for acute care, surgical procedures, and complex wound management. Large hospital networks increasingly adopt multi-vendor procurement models.
- Ambulatory Surgical Centers:These facilities primarily use wound dressings for post-surgical care in an outpatient setting, requiring efficient and effective products for rapid patient turnover.
- Specialty Clinics:Wound care clinics and dermatology clinics utilize advanced and specialized dressings for chronic and complex wounds, often requiring products with specific therapeutic properties.
The largest share of procurement resides with Hospitals. The segment gaining share fastest is Home Care.
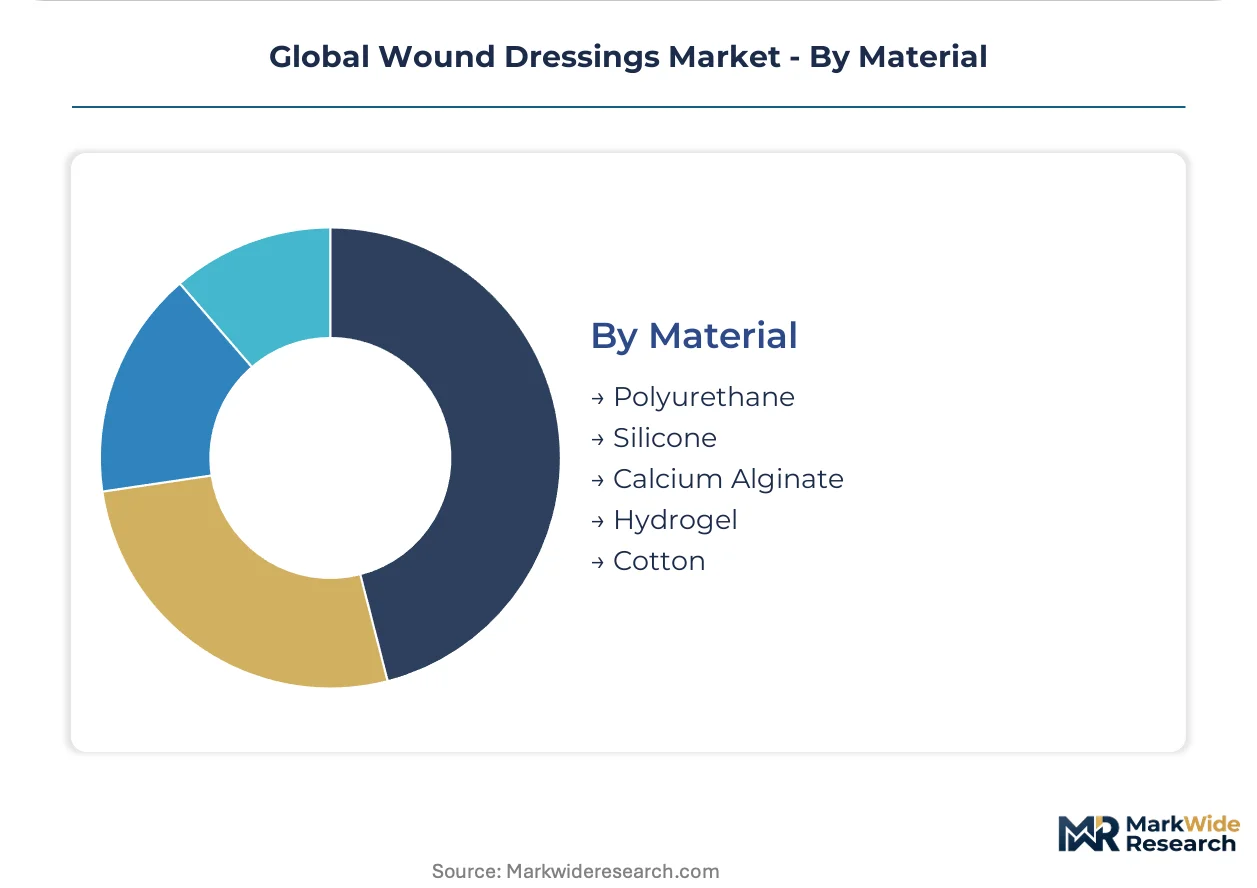
Material:
The raw materials used in wound dressings dictate their physical properties, performance characteristics, and biocompatibility, influencing clinical efficacy and patient outcomes.
- Silicone:Silicone-based dressings offer gentle adhesion, minimizing trauma upon removal and reducing skin irritation, making them ideal for sensitive skin. Innovations in silicone adhesive technologies improve patient comfort.
- Polyurethane:Polyurethane is a versatile polymer used in foam and film dressings, providing excellent fluid handling capabilities and a bacterial barrier. It is a common material in advanced wound care products.
- Calcium Alginate:Derived from brown seaweed, calcium alginate fibers absorb large amounts of exudate and form a gel, promoting a moist wound environment. This material is crucial for highly exuding wounds.
- Hydrogel:Hydrogel dressings consist primarily of water or glycerin, providing moisture to dry wounds and facilitating autolytic debridement. They are suitable for wounds with minimal exudate.
- Cotton:Cotton is a traditional and cost-effective material used in gauze dressings, offering basic absorption and protection.
Traditional material applications are dominated by Cotton. Innovation in material science is concentrated in Silicone.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced material science, particularly in regions with strong chemical and polymer industries, underpins global wound dressings market development. This is evident in countries driving innovation and demand for sophisticated wound care solutions. The market exhibits varied growth patterns influenced by demographic shifts and healthcare policies.
Germany
Germany's aging population and high prevalence of chronic conditions drive demand for advanced wound care products. Reimbursement formularies under the German healthcare system are stringent, favoring cost-effective options. The Bavaria medical technology cluster actively develops specialized wound care solutions, integrating digital health technologies.
Japan
Japan's rapidly aging population significantly increases the need for sophisticated wound dressings, particularly for diabetic foot ulcers. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous product evaluation before market entry. Tokyo's numerous research institutions collaborate on bio-integrative scaffold technologies for regenerative wound care.
United States
The United States market is characterized by large hospital networks and a growing shift towards home healthcare settings. The FDA's 510(k) pathway and emphasis on Real-World Evidence shape product commercialization and market access. Boston's prominent biotech hub fosters innovation in advanced material science for wound dressings.
United Kingdom
United Kingdom's National Health Service (NHS) procurement patterns increasingly favor system-level purchasing based on total cost of care. The UK's Medicines and Healthcare products Regulatory Agency (MHRA) oversees medical device approvals. London's health innovation ecosystem explores digital health integration for remote wound monitoring solutions.
India
India presents significant long-term growth opportunities due to its large population and improving healthcare infrastructure. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, including wound dressings, ensuring product quality. Bengaluru's burgeoning medical device industry focuses on cost-effective, accessible wound care solutions.
Global Wound Dressings Market Key Industry Players
Portfolio diversification dominates the current landscape, driven by the shift from single-source contracts to multi-vendor procurement models within large hospital networks. The market structure is recalibrating into a tiered system, featuring global players with extensive product lines and specialized innovators. Strategic archetypes include broad advanced wound management providers, chronic condition specialists, and product innovation leaders. Companies engage in portfolio diversification and strategic partnerships to secure comprehensive multi-product tenders, influencing competitive positioning significantly.
Within the advanced wound management sector, Smith & Nephew exemplifies a global player leveraging an extensive portfolio to secure multi-product tenders from large hospital networks. ConvaTec Group, a UK-based company, represents a specialist in solutions for chronic conditions, differentiating its offerings through clinical evidence for specific applications like pressure ulcers. Mölnlycke Health Care, a Swedish-headquartered entity, occupies a position as a product innovation leader, particularly with its proprietary silicone adhesion technologies designed for sensitive skin applications. These entities collectively anchor competitive dynamics by addressing diverse clinical needs and procurement strategies across the market.
| Leading Market Players |
|---|
| Solventum Corporation |
| Smith & Nephew |
| ConvaTec Group |
| Mölnlycke Health Care |
| Coloplast |
| 3M |
| Cardinal Health |
| Integra LifeSciences |
| PAUL HARTMANN AG |
| Others |
Cost & Logistics Intelligence
Polymer resin prices, a key input for advanced wound dressings, cascade through the supply chain, influencing the cost structure and ultimately shaping pricing tiers for finished products. This dynamic interaction balances raw material costs with market demand and regulatory compliance.
Pricing Analysis
Warranty and service bundling often differentiate premium advanced wound care products, influencing their perceived value. The dominant pricing structure for wound dressings is value-based, particularly for specialized products targeting chronic conditions. Price differentiation stems from proven clinical efficacy and stringent regulatory approvals like the FDA's 510(k) pathway. Cost-containment pressures from national healthcare systems, such as the UK's NHS, drive pricing softness, especially for traditional options. Hospitals exhibit high price sensitivity for commodity dressings, while specialty clinics prioritize advanced product performance for complex cases.
Supply Chain Analysis
Single-source vulnerability sits with specialized adhesive components, often sourced from specific chemical manufacturers in Germany and the United States. The supply chain relies heavily on polymers like polyurethane and silicone, alongside natural materials such as calcium alginate. Regulatory restrictions, particularly the EU's Medical Device Regulation (MDR), pose a structural risk by increasing compliance costs and time-to-market. Distribution for advanced wound dressings runs through established medical distributors to hospitals and increasingly, direct-to-consumer channels for home care products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with smart dressings incorporating embedded sensors gradually replacing passive traditional coverings. This shift demands strategic adaptation from all market participants.
For Market Incumbents:To counter intensifying cost-containment pressures, large incumbents must diversify portfolios across both premium advanced and cost-effective basic wound care solutions. Generating robust real-world evidence for clinical and economic value is critical for securing formulary access in markets like Germany. Investing in digital health integration for remote monitoring solutions can extend product utility and improve patient outcomes.
For New Entrants and Emerging Players:Launch via specialized clinic networks or direct-to-home care channels can effectively target underpenetrated segments like chronic ulcer management in emerging economies. Focusing on niche applications, such as non-antibiotic antimicrobial dressings, offers a clear differentiation strategy. Developing novel bio-integrative scaffolds with superior regenerative properties presents a high-value entry point, particularly in regions with strong research ecosystems like Tokyo.
For Investors and Strategic Acquirers:Distressed-cycle entries favor mid-cap specialists with proprietary material science or digital health integration capabilities in regions with strong regulatory frameworks. The long-term viability of advanced wound care depends on solutions that reduce healing times and complication rates. A key signal to watch is the successful commercialization of smart dressings that demonstrate clear clinical utility and secure favorable reimbursement pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Health Integration | Embedding sensors into dressings enables remote monitoring and improves patient management for chronic wounds. |
| Bio-integrative Scaffold Development | These advanced materials promote tissue regeneration, unifying medical device and biologic therapy functions. |
| Emerging Market Expansion | Accessing large, underserved populations in countries like India unlocks substantial long-term growth opportunities. |
| Real-World Evidence Generation | Systematic data collection validates long-term product performance and secures formulary access for advanced dressings. |
| Multi-Vendor Tender Specialization | Offering broad product portfolios and support services secures comprehensive contracts with large hospital networks. |
Research Approach
The FDA's 510(k) pathway, EU's Medical Device Regulation (MDR), and academic literature on wound healing formed the secondary backbone for this analysis. This was complemented by primary interviews with wound care clinicians, hospital procurement managers, R&D directors, and regulatory affairs leads. The combined insights informed a comprehensive understanding of market dynamics, triangulating both bottom-up and top-down data points.
The analytical framework employed a bottom-up approach, building market size estimates from granular product type, application, end-user, and material segments. This was then validated against top-down industry-level data across the analysis window. Compound annual growth rates were derived through a combination of regression analysis and expert consensus, incorporating inputs such as global demographic shifts and the rising prevalence of chronic conditions.
Reimbursement policy changes, new regulatory frameworks, and material science breakthroughs are the dominant revision risks for market projections. Forecasts reflect assumptions documented through extensive primary and secondary research. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
US Burn Care Centers Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Maggot Debridement Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
North America Wound Care Management Market
Wound Care
Wound Care Market
Wound Care
Global Active Wound Care Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Wound Irrigation Devices Market
Wound Care
Bioactive Wound Care Market
Wound Care
Wound Retractor Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Wound Measurement Devices Market
Wound Care
Next Generation Wound Closure Device Market