
 Vascular Dressings Market | 2026-2036
Vascular Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Dressings Market Analysis
The capability gap between capital-intensive advanced wound care manufacturers and commodity dressing suppliers is collapsing as antimicrobial and moisture management technologies become table stakes. BD leverages integrated supply chains across hospital and ambulatory channels to sustain pricing power in transparent film segments. Mölnlycke Health Care anchors its position through specialized foam dressing portfolios optimized for surgical wound applications. Smith & Nephew competes by extending its R&D footprint in biodegradable material platforms that address EU regulatory timelines.
Vascular dressings are sterile barrier systems applied over catheter insertion sites, arterial punctures, and vascular access points, typically incorporating polyurethane films, hydrocolloid matrices, or silicone adhesive layers to maintain moisture balance while preventing bacterial infiltration. Their primary purpose is to secure access devices, absorb exudate, and reduce bloodstream infection risk during indwelling periods. Foam dressings and transparent film categories lead current revenue pools due to established hospital procurement contracts, while antimicrobial solutions represent the fastest-growing technology segment as clinicians prioritize infection prevention in catheter-related bloodstream infection protocols. Alginate dressings occupy a narrower margin position concentrated in burn care and heavy exudate applications where specialized absorption properties justify premium positioning.
The FDA enforces biocompatibility and sterility standards under 21 CFR Part 820 quality system regulations, while the EU MDR requires enhanced clinical evidence and post-market surveillance for vascular dressings marketed in Europe. The EPA regulates antimicrobial claims in silver-impregnated and iodine-based dressing formulations, creating compliance complexity for manufacturers with cross-border portfolios. Stakeholders must monitor evolving reimbursement pathways for advanced wound care in Medicare and commercial payer systems, as coverage determinations increasingly tie product selection to demonstrated reductions in hospital-acquired infection rates.
Market Dynamics
The EU MDR framework is compressing competitive timelines by forcing manufacturers to rebuild clinical evidence portfolios for antimicrobial vascular dressings, collapsing the historical advantage held by legacy suppliers with grandfathered certifications.
Growth Catalysts
- Catheter-Related Bloodstream Infection Protocols:Hospital infection control committees in the United States are mandating antimicrobial dressing coverage for all central line insertions, creating standardized demand pull across acute care networks.
- Silver-Ion Release Engineering:Advances in controlled-release kinetics for silver sulfadiazine matrices are extending effective antimicrobial windows from 72 hours to 7 days, reducing nursing change frequency and labor costs.
- REACH Compliance Migration:European manufacturers are reformulating adhesive chemistries to eliminate phthalate plasticizers ahead of 2025 substance restrictions, capturing early-mover positioning in premium hospital procurement channels.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Five specialty chemical producers in Germany and Japan control 78% of platinum-cured silicone supply for breathable adhesive layers, exposing dressing manufacturers to input volatility.
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies face 14-18 month queues at accredited laboratories, freezing product pipeline velocity for mid-tier suppliers without captive testing capacity.
- Transparent Film Commoditization:Polyurethane film dressings without antimicrobial loading face substitution pressure from private-label hospital contract manufacturers, eroding margin pools in standard-of-care segments.
Strategic Opportunities
- Home Infusion Therapy Expansion:Untapped demand in Medicare Advantage plans for patient-applied vascular dressings is opening direct-to-consumer channels previously locked behind hospital formulary gates.
- Biodegradable Polymer Convergence:Integration of polylactic acid backings with hyaluronic acid hydrogel layers enables single-material compostability, aligning with NHS England's single-use plastics reduction targets.
- AI-Assisted Wound Monitoring:Smartphone-compatible dressing substrates with colorimetric infection indicators are creating data-capture value propositions that transcend commodity pricing.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemists with dual expertise in medical adhesives and antimicrobial elution kinetics command premium compensation that mid-cap manufacturers struggle to match.
- Legacy Sterilization Revalidation:Transition from ethylene oxide to gamma irradiation for moisture-sensitive hydrocolloid dressings requires full stability restudies, consuming 18-24 month certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Dressings Market |
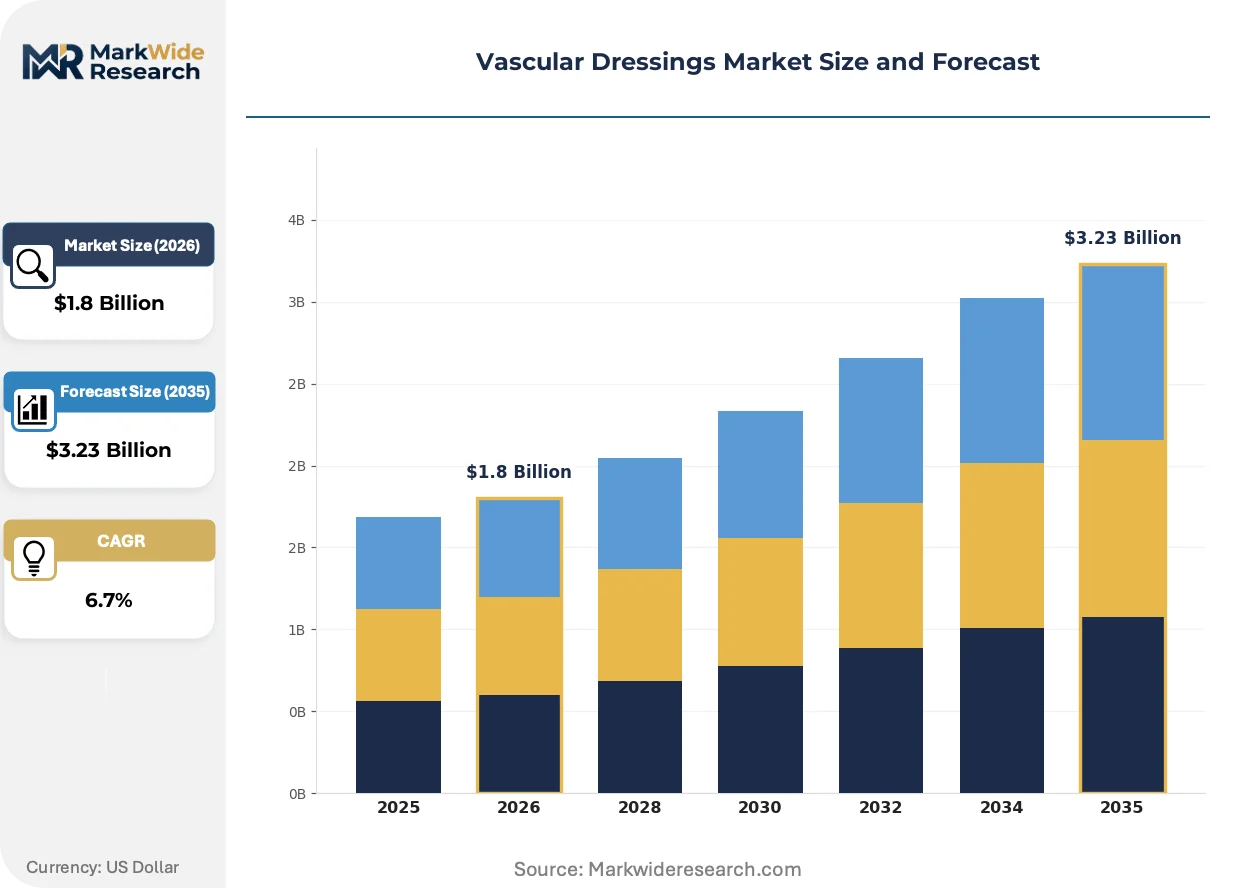
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Film, Foam Dressings, Hydrocolloid Dressings, Alginate Dressings End User: Hospitals, Homecare Settings, Ambulatory Surgical Centers, Rehabilitation Centers Application: Trauma, Surgical Wounds, Burn Care, Diabetic Ulcers Technology: Advanced Wound Care, Moisture Management, Biodegradable Materials, Antimicrobial Solutions |
| Companies Covered | BD, Smith & Nephew, Mölnlycke Health Care, 3M, B Braun, Vancive Medical Technologies, BSN Medical, Richardson Healthcare, Derma Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Dressings Market Emerging Trajectories
Antimicrobial functionality is migrating from premium tier to baseline expectation, forcing manufacturers to differentiate through sensor integration, biodegradability, and ambulatory care workflow optimization rather than infection prevention alone.
Silicone adhesive technology is decomposing the traditional trade-off between securement strength and skin integrity. Soft silicone atraumatic adhesives now enable 7-day wear times on fragile geriatric skin, allowing hospital systems in Germany to extend indwelling catheter protocols while reducing medical adhesive-related skin injuries. This capability is compressing the addressable market for traditional acrylic-based transparent films in post-acute settings.
The EU MDR's enhanced clinical evidence requirements for Class IIa medical devices are restructuring submission strategies for vascular dressing portfolios. Manufacturers must now generate prospective clinical data on infection rate reduction rather than relying on predicate equivalence, favoring larger competitors with dedicated health economics teams. Smaller suppliers are responding through strategic partnerships with academic medical centers in France and the Netherlands to share trial costs.
Hospital procurement committees are consolidating vendor relationships around full-line wound care suppliers capable of meeting standardized formulary requirements across film, foam, and antimicrobial categories. This behavior concentrates contract awards with manufacturers offering integrated moisture management portfolios, squeezing single-product specialists in the United States acute care channel.
Vascular Dressings Market Segmentation
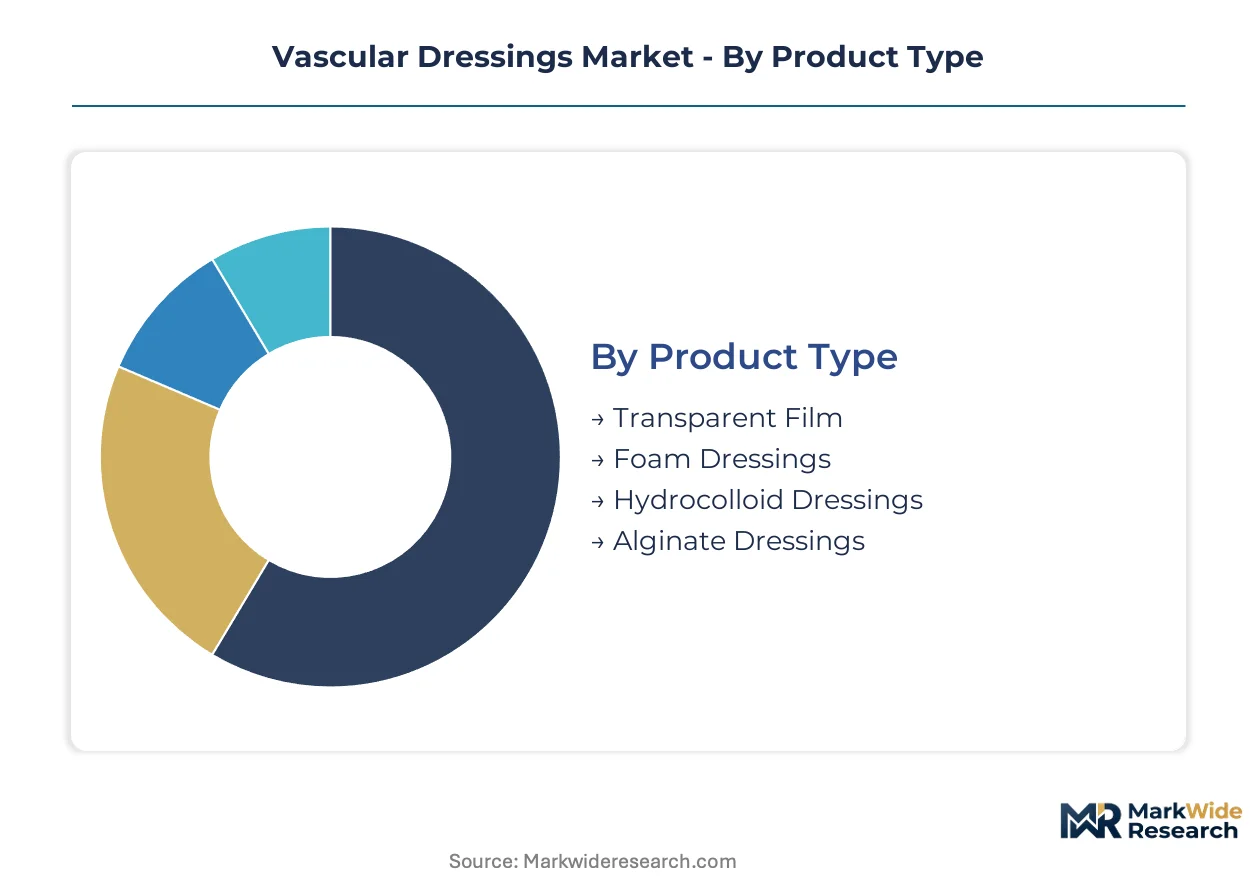
Vascular dressing manufacturers configure product portfolios around infection prevention hierarchies and care setting workflows. Segmentation reveals where polyurethane films dominate procurement contracts versus where silver-impregnated foams command premium positioning.
Product Type:
FDA 21 CFR Part 820 quality system regulations and EU MDR Class IIa device classifications impose divergent sterilization and biocompatibility burdens across material platforms.
- Transparent Film:Polyurethane membranes with silicone or acrylic adhesive layers provide securement for peripheral IV sites and arterial punctures. Hospital procurement committees in the United States standardize on transparent films for short-dwell catheters under 72 hours, though antimicrobial loading increasingly differentiates contract tiers.
- Foam Dressings:Hydrophilic polyurethane or silicone foam matrices absorb moderate-to-heavy exudate while maintaining moist wound environments. German hospital systems extend foam dressing protocols to post-catheterization care, driven by moisture management requirements in extended indwelling protocols.
- Hydrocolloid Dressings:Carboxymethylcellulose and pectin matrices form gel upon exudate contact, suited for low-to-moderate drainage vascular access sites.
- Alginate Dressings:Calcium-sodium alginate fibers derived from brown seaweed deliver hemostatic properties for bleeding puncture sites in interventional radiology.
Established volume favors Transparent Film; emerging adoption favors Foam Dressings.
End User:
Reimbursement pathway complexity separates acute care formulary gatekeeping from direct-to-consumer channel economics.
- Hospitals:Infection control committees mandate antimicrobial dressing coverage for central line insertions, consolidating purchasing around full-line suppliers capable of meeting standardized formulary requirements across film, foam, and antimicrobial categories.
- Homecare Settings:Medicare Advantage plans unlock direct-to-consumer channels for patient-applied vascular dressings, bypassing traditional hospital procurement gates.
- Ambulatory Surgical Centers:Same-day discharge protocols favor low-profile transparent films with rapid application characteristics.
- Rehabilitation Centers:Extended wear requirements on fragile geriatric skin drive soft silicone adhesive specifications.
Contract concentration favors Hospitals; channel expansion favors Homecare Settings.
Application:
Clinical outcome metrics and payer coverage determinations segment demand by wound etiology and complication risk.
- Trauma:Emergency department protocols for penetrating vascular injuries require rapid-application hemostatic dressings with barrier properties.
- Surgical Wounds:Post-operative catheter sites in cardiac and orthopedic procedures generate sustained demand for antimicrobial-impregnated foam portfolios optimized for surgical wound applications.
- Burn Care:Heavy exudate management and infection prevention in thermal injury patients concentrate alginate and silver-loaded dressing utilization.
- Diabetic Ulcers:Chronic wound management in diabetic populations drives moisture-balanced dressing specifications with extended wear intervals to reduce dressing change trauma.
Procedure volume favors Surgical Wounds; complication cost avoidance favors Diabetic Ulcers.
Technology:
Material science capabilities determine competitive positioning as antimicrobial functionality becomes baseline expectation.
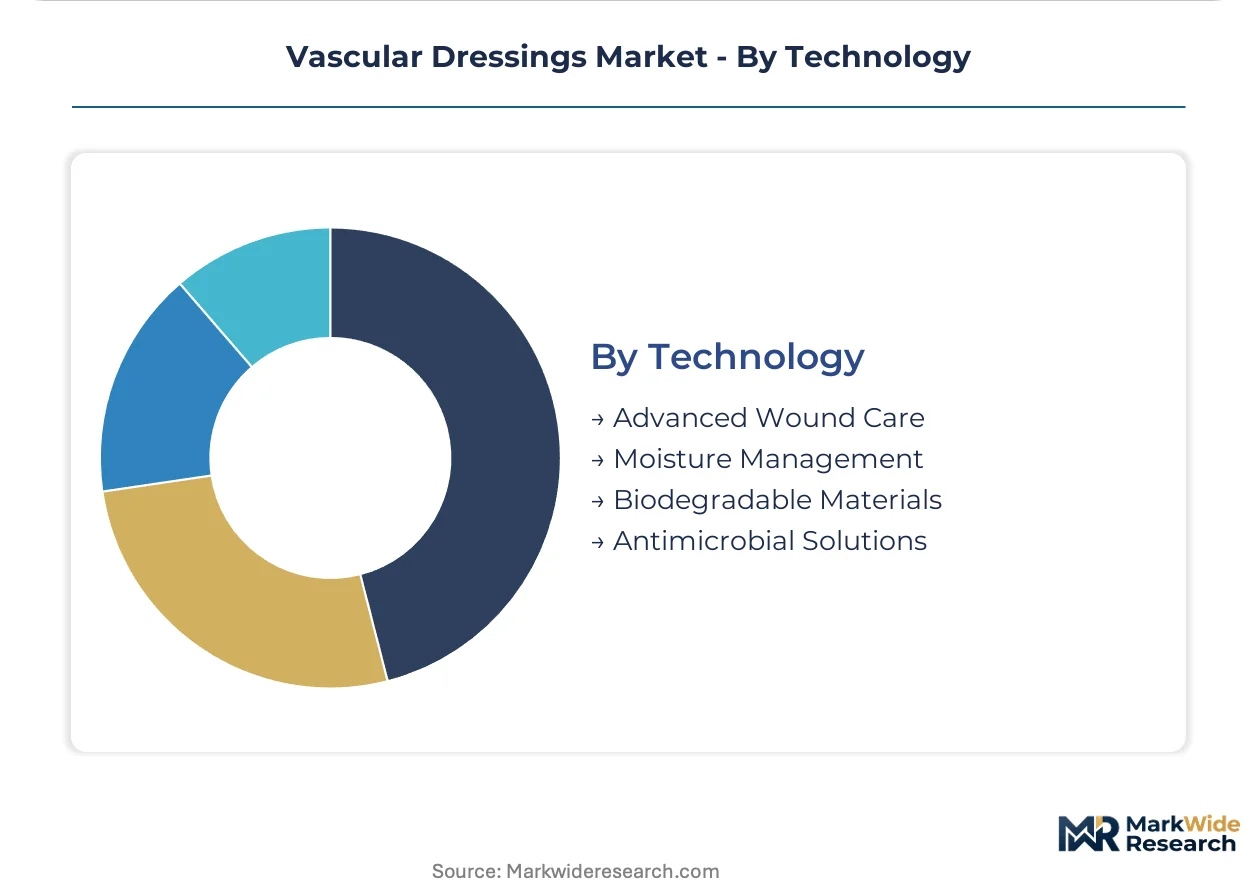
- Advanced Wound Care:Integrated moisture management systems combining semi-permeable films with absorbent layers address multiple healing parameters simultaneously.
- Moisture Management:Hydrogel and hydrocolloid technologies balance exudate absorption with hydration maintenance, critical for epithelialization at vascular access sites.
- Biodegradable Materials:Polylactic acid backings with hyaluronic acid hydrogel layers enable single-material compostability, aligning with NHS England single-use plastics reduction targets.
- Antimicrobial Solutions:Silver-ion release engineering extends effective antimicrobial windows from 72 hours to 7 days, climbing the fastest as clinicians prioritize catheter-related bloodstream infection prevention protocols.
Procurement standardization favors Moisture Management; regulatory tailwinds favor Biodegradable Materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for medical-grade silicone adhesives tilts the trade balance toward Germany and Japan, while finished dressing exports concentrate in the United States and Switzerland. Hospital procurement consolidation across OECD markets is reshaping regional manufacturing footprints.
United States
Aging demographics and diabetes prevalence drive chronic wound management demand through Medicare Advantage expansion. The FDA enforces biocompatibility standards under 21 CFR Part 820 quality system regulations. Boston and Minneapolis medical device clusters anchor antimicrobial dressing R&D for catheter-related bloodstream infection protocols.
Germany
Hospital systems extend moisture management protocols for post-catheterization care amid extended indwelling device use. REACH substance restrictions force adhesive chemistry reformulation ahead of 2025 phthalate plasticizer deadlines. The Rhine-Ruhr and Bavarian chemical corridors concentrate platinum-cured silicone supply for breathable adhesive layers.
Japan
Geriatric skin fragility drives soft silicone adhesive specifications for 7-day wear protocols. METI oversees medical device quality frameworks aligned with international harmonization. The Kansai region around Osaka hosts specialty chemical producers controlling medical-grade silicone feedstock.
United Kingdom
NHS England single-use plastics reduction targets accelerate biodegradable polymer adoption in vascular dressing procurement. The MHRA implements EU MDR-aligned post-market surveillance for Class IIa devices. The Cambridge-Oxford-London triangle concentrates health economics research partnerships for clinical evidence generation.
France
ANSM regulatory oversight tightens clinical evidence requirements for antimicrobial dressing market authorization. Academic medical centers in Paris and Lyon host shared trial infrastructure for mid-tier manufacturers seeking EU MDR compliance. Hospital procurement consolidation favors full-line wound care suppliers.
Vascular Dressings Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates and specialized wound care suppliers. The vendor base stratifies across three tiers: integrated hospital supply chains, dedicated advanced wound care portfolios, and regional private-label fabricators. Dominant competitive moves include portfolio diversification into antimicrobial-loaded segments and strategic partnerships with academic medical centers for EU MDR clinical evidence generation.
Within the integrated supply chain tier, BD exemplifies hospital and ambulatory channel leverage, while Mölnlycke Health Care occupies a position as a specialized foam dressing supplier. Smith & Nephew represents the biodegradable materials vector addressing regulatory timelines in European markets. These three anchors illustrate how competitive positioning now hinges on infection prevention technology, moisture management specialization, and regulatory compliance infrastructure rather than commodity manufacturing scale.
| Leading Market Players |
|---|
| BD |
| Smith & Nephew |
| Mölnlycke Health Care |
| 3M |
| B Braun |
| Vancive Medical Technologies |
| BSN Medical |
| Richardson Healthcare |
| Derma Sciences |
| Others |
Supply Flow & Price Mechanics
FDA 21 CFR Part 820 quality system regulations and EU MDR Class IIa device classifications simultaneously gate supplier qualification and stratify price tiers, forcing manufacturers to absorb certification costs that translate into antimicrobial-loaded premium positioning against commodity transparent films.
Pricing Analysis
Configured-to-order pricing for silver-ion release engineered dressings commands substantial premiums over standard polyurethane transparent films. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by antimicrobial loading density and wear-time certification. Cost compression in standard transparent film segments intensifies because private-label hospital contract manufacturers erode margin pools. Homecare Settings exhibit highest price sensitivity due to direct-to-consumer channel economics, while Hospitals demonstrate lowest sensitivity through formulary consolidation around infection prevention outcomes.
Supply Chain Analysis
Platinum-cured silicone feedstock concentration in Germany and Japan creates a chokepoint exposing dressing manufacturers to input volatility. Medical-grade silicone supply rests on five specialty chemical producers controlling breathable adhesive layer production. Raw material dependencies include polyurethane resins, silver sulfadiazine matrices, and hyaluronic acid hydrogel precursors. Single-source vulnerability in silicone adhesive supply concentrates pricing power with upstream chemical specialists. Distribution runs through hospital procurement committees consolidating vendor relationships around full-line wound care suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as home infusion therapy expansion and biodegradable polymer convergence create specialized niches outside consolidated hospital formulary channels.
For Market Incumbents: Shield antimicrobial dressing portfolios from transparent film commoditization by accelerating biodegradable material R&D ahead of NHS England single-use plastics mandates. Capture vertical integration into platinum-cured silicone supply through strategic partnerships with Rhine-Ruhr chemical corridor producers. Consolidate channel control by extending full-line wound care contracts into Medicare Advantage homecare networks before mid-tier suppliers establish direct-to-consumer positioning. For New Entrants and Emerging Players: Home infusion therapy patient-applied dressing services represent an under-served service layer where hospital formulary gatekeeping weakens. Penetrate Medicare Advantage direct-to-consumer channels with smartphone-compatible colorimetric infection indicator substrates. Deploy AI-assisted wound monitoring as a go-to-market wedge that transcends commodity pricing through data-capture value propositions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biodegradable polymer convergence segments as EU MDR clinical evidence requirements demand dedicated health economics teams. Five-to-ten year viability favors manufacturers with captive ISO 10993 biocompatibility testing capacity to bypass 14-18 month laboratory queues. Acquisition targets should demonstrate existing academic medical center partnerships in France or the Netherlands for shared trial cost structures. Monitor AI-assisted wound monitoring patent filings as inflection signal for sensor integration capability gaps.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Partnership | Shared trial infrastructure with Paris and Lyon academic centers accelerates Class IIa device authorization timelines. |
| Biodegradable Polymer Platform Development | Polylactic acid-hyaluronic acid integration aligns procurement positioning with NHS England plastics reduction mandates. |
| Home Infusion Direct-to-Consumer Channel | Medicare Advantage plan bypass of hospital formulary gates unlocks patient-applied dressing revenue pools. |
| Silver-Ion Release Engineering Scale-Up | Controlled-release kinetics extension from 72 hours to 7 days reduces nursing labor costs and change frequency. |
| AI-Assisted Wound Monitoring Integration | Smartphone-compatible colorimetric substrates create data-capture value propositions beyond commodity pricing tiers. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement database records preceded structured interviews with infection control committee directors, biomedical engineers, GPO contracts managers, and formulation chemists at adhesive suppliers. Primary fieldwork combined with secondary validation from SEC 10-K disclosures of listed medical device manufacturers and CMS Medicare reimbursement pathway documentation. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from trade flow analysis.
Variance-decomposition framing separated volume growth drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, application setting, and technology platform. CAGRs were derived from logistic diffusion curves fitted to antimicrobial adoption rates and extended indwelling protocol penetration. Industry-specific forecast inputs incorporated REACH substance restriction compliance timelines and ISO 10993 testing queue durations.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820 and EU MDR regimes; material policy shifts would require re-modeling of certification cycle impacts and clinical evidence thresholds. Forecasts reflect assumptions of stable medical-grade silicone supply concentration and unaltered Medicare Advantage reimbursement pathways for advanced wound care. Practitioners should keep alternative scenarios live as EPA antimicrobial claim enforcement and NHS England single-use plastics targets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Asia Pacific Advanced Wound Care Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Wound Care Biologics Market
Wound Care
Wound Biologics Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Next Generation Wound Closure Device Market
Wound Care
France Wound Care Market
Wound Care
Burn Care Centers Market
Wound Care
Biopatches Market
Wound Care
Dental Wound Dressings Market
Wound Care
Anti-Biofilm Wound Dressing Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Foam Dressing Market
Wound Care
Advanced Wound Management Market
Wound Care
Bioactive Wound Dressing Market