
 Wound Management Market | 2026-2036
Wound Management Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Management Market Outlook
Modular dressing kits is pivoting how procurement teams evaluate wound care suppliers. Smith & Nephew leverages integrated negative-pressure platforms to anchor its acute-care presence. Solventum specializes in separating advanced biologics from commodity bandages, creating distinct pricing tiers. Mölnlycke Health Care dominates silicone-adhesive portfolios across European hospital networks.
Wound management encompasses dressings, bandages, topical agents, and advanced wound care systems engineered from hydrocolloid, foam, hydrogel, or alginate substrates to maintain moist healing environments, manage exudate, and prevent infection across chronic wounds, surgical wounds, burns, and ulcers. The primary commercial purpose centers on reducing healing time, minimizing complication rates, and lowering total cost of care across hospitals, home care settings, clinics, and long-term care facilities. Advanced wound care commands the deepest margin pools due to bioactive ingredient costs and specialized application training. Hydrocolloid and foam technologies lead volume shipment while alginate segments attract premium positioning in heavy-exudate cases.
The FDA governs 510(k) premarket notification for wound care devices while the EPA regulates antimicrobial claims on topical agents, creating dual compliance pathways that shape product development cycles and market entry timelines. The EU Medical Device Regulation imposes stricter clinical evidence requirements on advanced wound care classifications, elevating documentation burdens for alginate and hydrogel innovators seeking CE marking. Stakeholders must monitor evolving reimbursement codes for home-based wound care as payors recalibrate post-acute spending authority.
Market Dynamics
Post-acute care decentralization is compressing hospital length-of-stay targets while forcing wound care procurement toward ambulatory and home settings. This structural shift rewards manufacturers with integrated logistics capabilities and penalizes acute-only suppliers.
Growth Catalysts
- FDA 510(k) Acceleration:The streamlined premarket notification pathway for antimicrobial wound products shortens commercialization cycles. Manufacturers leverage this to bring advanced dressings to market faster than under full PMA review.
- Silicone-Adhesive Platforms:Hospital networks in Germany and France are standardizing silicone-based gentle removal protocols for fragile skin populations. This material specification drives upgrade cycles across long-term care facilities.
- Home Care Expansion:Medicare's post-acute spending authority recalibration favors outpatient wound management. Home health agencies now procure advanced dressing kits previously reserved for inpatient settings.
Market Restraints
- Silver Input Volatility:Antimicrobial dressings depend on silver nanoparticle supply concentrated in Chinese refining operations. Price swings in this raw material compress margins on premium alginate segments.
- EU MDR Documentation Burden:The Medical Device Regulation's stricter clinical evidence requirements for hydrogel and alginate classifications delay CE marking timelines. Smaller innovators face disproportionate compliance costs.
- Commodity Bandage Substitution:Basic woven gauze and adhesive strips retain volume share in price-sensitive emerging markets. This limits addressable market expansion for advanced substrate technologies.
Strategic Opportunities
- Underpenetrated Indian Home Care:India's fragmented post-operative care network lacks standardized wound protocols. First movers establishing distribution through Apollo and Max hospital networks capture untapped chronic wound incidence.
- Digital Wound Monitoring Convergence:Smartphone-enabled measurement tools combined with AI-powered healing prediction algorithms create subscription revenue streams. Telehealth providers embed these into remote patient monitoring bundles.
- Brazilian ANVISA Fast-Track:Priority review pathways for antimicrobial innovations accelerate market entry timelines. Manufacturers with existing FDA clearance leverage mutual recognition to preempt local competitors.
Industry Challenges
- Specialized Wound Care Nurse Shortage:Negative-pressure therapy and bioactive dressing application require certified clinical training. Health systems in Texas and Florida report unfilled specialist positions delaying protocol adoption.
- Legacy EHR Integration Friction:Advanced wound care documentation systems must interface with Cerner and Epic installations. Custom API development stretches implementation timelines for integrated dressing platforms.
- Reimbursement Code Lag:CMS updates to home-based wound care billing codes trail product innovation cycles. Manufacturers absorb commercial risk while awaiting coding committee decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Management Market |
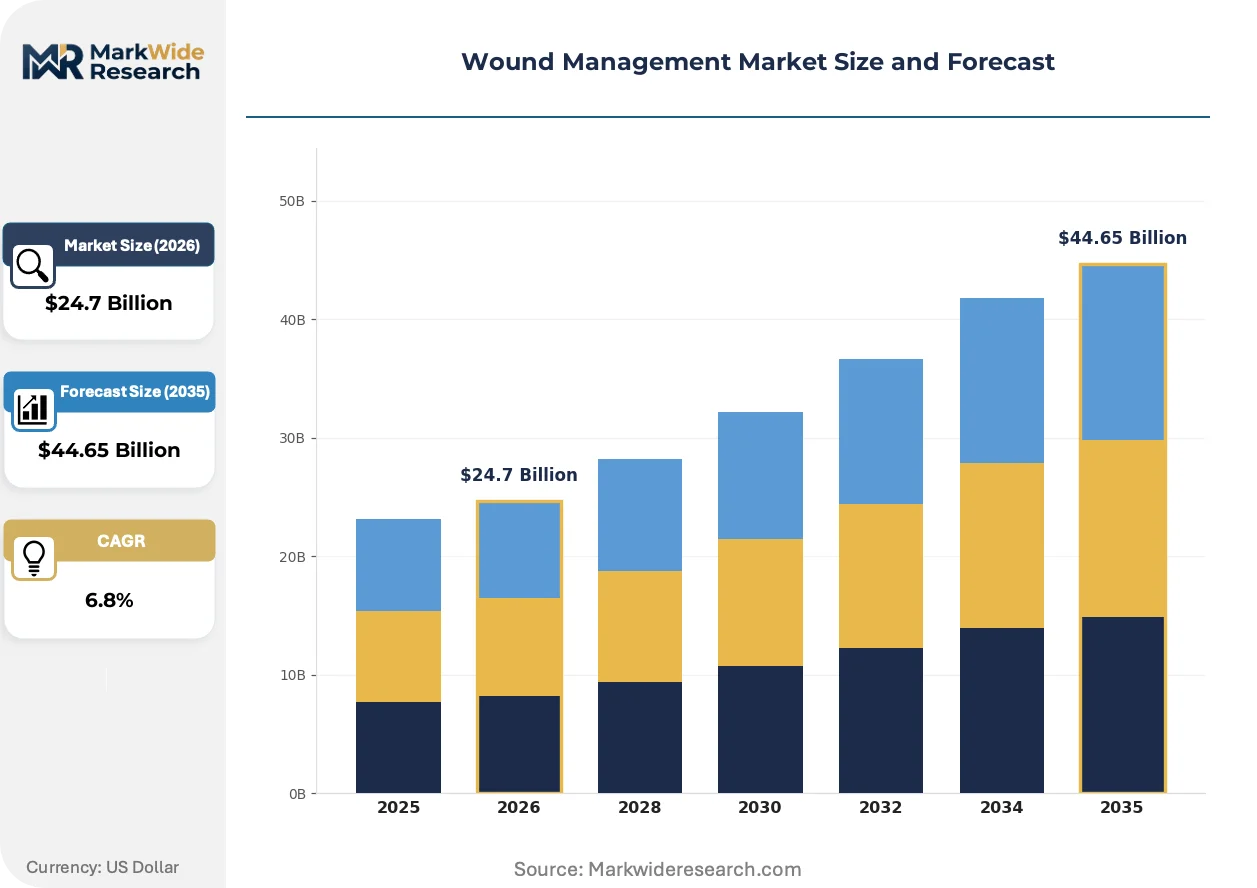
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Bandages, Topical Agents, Advanced Wound Care Application: Chronic Wounds, Surgical Wounds, Burns, Ulcers End User: Hospitals, Home Care, Clinics, Long-term Care Facilities Technology: Hydrocolloid, Foam, Hydrogel, Alginate |
| Companies Covered | Smith & Nephew, Solventum, 3M, ConvaTec Group, Mölnlycke Health Care, Johnson & Johnson Services, Cardinal Health, B. Braun, Coloplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Management Market Strategic Shifts
Active healing substrates are displacing passive moisture management as the dominant technical paradigm. This evolution demands new manufacturing capabilities and reshapes competitive positioning around bioactive ingredient sourcing.
Electrical stimulation dressings is absorbing clinical attention in diabetic foot ulcer protocols. These bioelectronic platforms deliver microcurrent therapy through conductive hydrogel layers. Veterans Affairs medical centers in California and Texas are piloting standardized order sets. The technology is absorbing market share from growth factor therapies by demonstrating comparable closure rates at lower per-application cost.
REACH antimicrobial substance restrictions are forcing reformulation of silver and iodine-based topical agents. The European Chemicals Agency's candidate list expansion triggers supply chain audits for wound care manufacturers. Alginate producers with EU manufacturing footprints are accelerating PHMB and polyhexamethylene biguanide alternatives. German hospital procurement committees now require full substance disclosure documentation.
Hospital-at-home programs are fragmenting traditional acute-care purchasing concentration. Large health systems in Pennsylvania and Ohio are unbundling wound care supplies from central supply contracts. Home infusion companies now negotiate direct manufacturer relationships for negative-pressure canisters and foam dressings. This channel shift is most visible in Medicare Advantage populations where capitated payments incentivize site-of-care migration.
Wound Management Market Segmentation
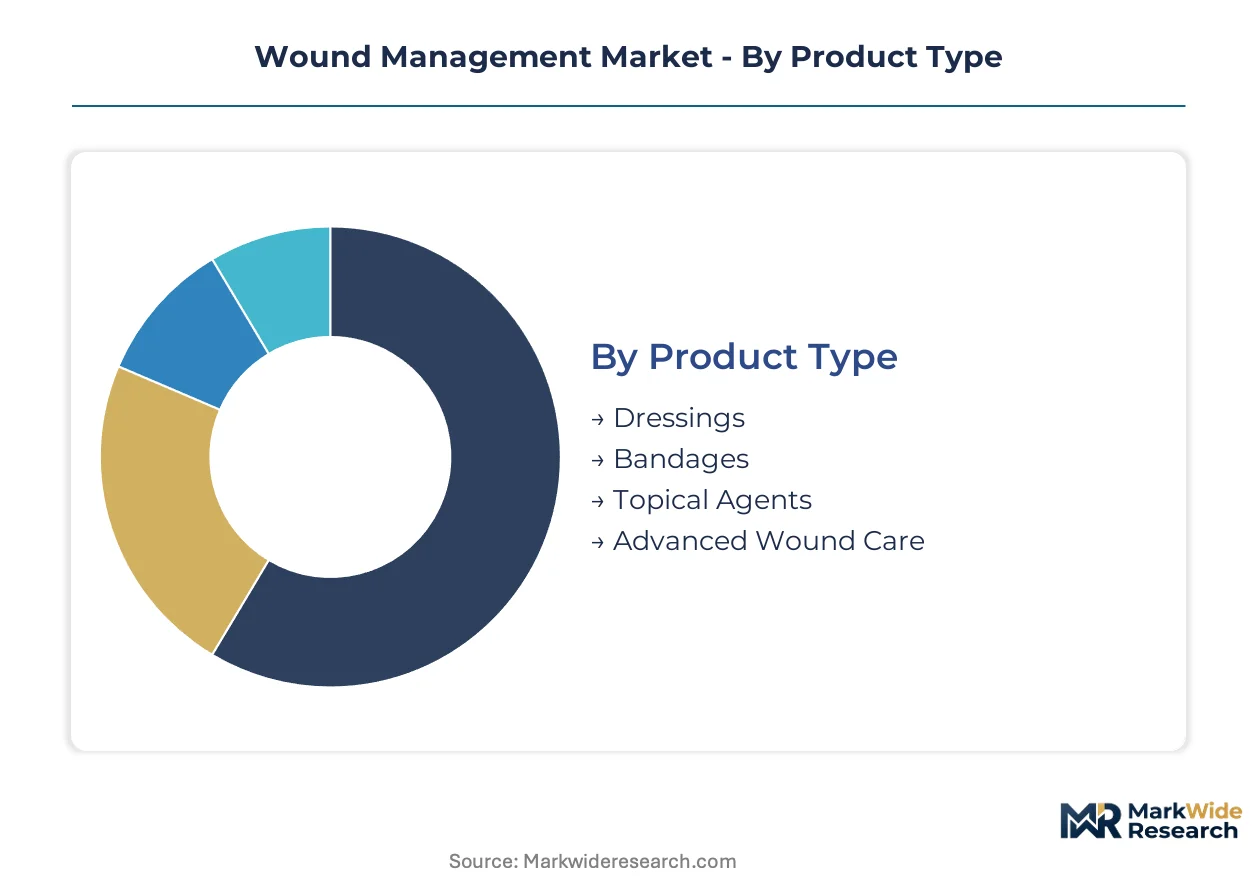
Wound management procurement teams segment demand by clinical severity and reimbursement pathway. Technology substrate selection determines margin structure and regulatory classification. End-user channel fragmentation is accelerating as site-of-care migration reshapes distribution economics.
Product Type:
Capital intensity concentrates in advanced wound care manufacturing, where bioactive ingredient synthesis and sterile fill-finish infrastructure demand eight-figure facility investments. Commodity bandage production runs on depreciated assets with minimal barrier to entry.
- Advanced Wound Care:Bioengineered skin substitutes, growth factor therapies, and negative-pressure systems require GMP-certified cleanrooms and specialized sterilization protocols. Veterans Affairs medical centers in California and Texas are standardizing these products for diabetic foot ulcer protocols.
- Dressings:Hydrocolloid and foam substrates dominate hospital procurement volumes, with silicone-adhesive variants commanding premium positioning in fragile-skin populations across German and French long-term care networks.
- Bandages:Woven gauze and adhesive strips retain volume share in price-sensitive emerging markets where basic wound coverage suffices.
- Topical Agents:Antimicrobial creams and enzymatic debriders face REACH substance restrictions in Europe, forcing reformulation toward PHMB alternatives.
Most installed capacity flows through Dressings. Expansion is steepest in Advanced Wound Care.
Application:
Clinical outcome requirements vary sharply by wound etiology, dictating technology selection and reimbursement intensity. Chronic wounds sustain recurring revenue streams while surgical wounds concentrate purchasing in acute-care procurement committees.
- Chronic Wounds:Diabetic foot ulcers and venous leg ulcers generate recurring dressing consumption over 12-24 month healing trajectories. Medicare Advantage capitation in Florida and Texas is shifting these cases toward home-based management.
- Surgical Wounds:Post-operative incision care demands absorbable hemostats and antimicrobial barrier films. Hospital-at-home programs in Pennsylvania and Ohio are unbundling these supplies from central supply contracts.
- Burns:Silver-impregnated dressings and biosynthetic skin substitutes require specialized burn center formulary approval.
- Ulcers:Pressure injury prevention protocols in US nursing homes drive foam overlay and hydrocolloid demand.
Chronic Wounds absorb the highest per-patient lifetime value. Surgical Wounds are gaining share fastest as ambulatory procedure volumes climb.
End User:
Procurement authority is fragmenting as integrated delivery networks delegate purchasing to site-of-care managers. Home health agencies now negotiate direct manufacturer relationships previously reserved for hospital supply chain executives.
- Home Care:Medicare's post-acute spending recalibration is transferring advanced dressing procurement from inpatient to outpatient settings. Home infusion companies in the United States now stock negative-pressure canisters and foam dressings for wound vac therapy.
- Hospitals:Acute-care procurement committees concentrate purchasing power for bioactive dressings and integrated negative-pressure platforms.
- Clinics:Ambulatory wound centers in Germany standardize silicone-adhesive protocols for fragile-skin populations.
- Long-term Care Facilities:Pressure injury prevention mandates drive volume demand for basic moisture management products.
Hospitals retain the deepest contract values. Home Care is climbing the fastest as site-of-care migration accelerates.
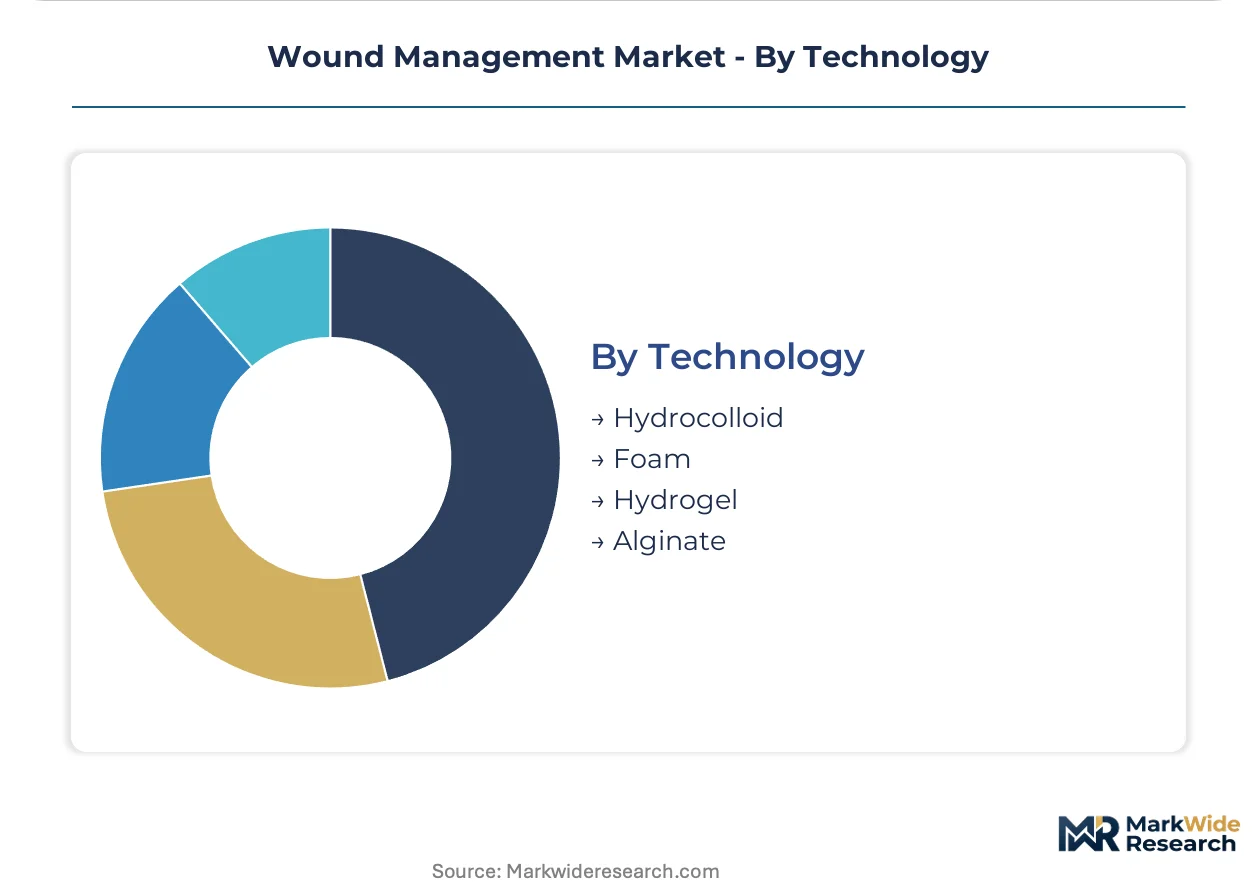
Technology:
Substrate manufacturing sophistication determines regulatory pathway and pricing tier. Hydrogel and alginate production requires specialized biopolymer sourcing and cross-linking expertise that concentrates supplier bases.
- Foam:Polyurethane foam dressings with variable pore structures manage exudate across moderate-to-heavy wound presentations. German hospital networks are standardizing these for surgical incision care.
- Alginate:Calcium-sodium alginate fibers derived from brown seaweed form gel matrices upon contact with wound fluid. EU MDR documentation burdens are delaying CE marking for new alginate entrants.
- Hydrocolloid:Carboxymethylcellulose and gelatin matrices provide self-adherent moisture management for low-to-moderate exudate wounds.
- Hydrogel:Cross-linked polymer networks deliver cooling hydration to dry necrotic wounds. Electrical stimulation dressings are embedding conductive hydrogel layers for bioelectronic therapy delivery.
Foam commands the broadest installed base. Alginate is expanding most quickly in heavy-exudate and infected wound protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wound management industrialization traces to post-war surgical advances in the United States and subsequent European standardization of sterile dressing protocols. Regional demand patterns now diverge sharply between aging Western populations requiring chronic wound protocols and emerging markets building basic care infrastructure.
United States
Diabetic foot ulcer incidence in Florida and Texas sustains Medicare Advantage spending on advanced negative-pressure systems. FDA 510(k) clearance pathways accelerate antimicrobial dressing commercialization for manufacturers targeting Veterans Affairs medical centers. Hospital-at-home programs in Pennsylvania and Ohio fragment procurement authority toward home infusion companies.
Germany
Silicone-adhesive gentle removal protocols dominate hospital network standardization for fragile-skin populations in long-term care. EU MDR documentation burdens delay CE marking for alginate innovators seeking hydrogel classification upgrades. Medical device clusters in Baden-Württemberg concentrate sterile fill-finish capacity for bioactive substrate manufacturing.
China
Silver nanoparticle refining concentration exposes antimicrobial dressing manufacturers to raw material price volatility from domestic smelting operations. NMPA regulatory harmonization with international standards accelerates market entry for foreign hydrogel and foam substrate producers. Yangtze River Delta medical device zones scale polyurethane foam dressing output for export markets.
India
Fragmented post-operative care networks in Apollo and Max hospital systems lack standardized chronic wound protocols. CDSCO priority review pathways for antimicrobial innovations attract manufacturers with existing FDA clearances seeking mutual recognition. Maharashtra and Karnataka medical device manufacturing zones expand basic gauze and adhesive strip capacity for price-sensitive domestic demand.
Brazil
ANVISA fast-track pathways for antimicrobial wound products compress market entry timelines for alginate and hydrogel entrants. Pressure injury prevention mandates in São Paulo and Rio de Janeiro long-term care facilities drive foam overlay procurement. Local distributors in Minas Gerais build logistics networks to capture decentralized home care expansion.
Wound Management Market Competitive Environment
Premium-margin players sit above commodity-margin players across substrate sophistication and sterile manufacturing certification tiers. The vendor base stratifies between GMP-certified cleanroom operators capturing bioactive dressing value and depreciated-asset producers of woven gauze serving price-sensitive channels. Three archetypes dominate: integrated negative-pressure platform specialists, silicone-adhesive material science leaders, and diversified medical supply conglomerates with wound care divisions. M&A activity concentrates on alginate and hydrogel technology acquisitions, while capacity expansion targets EU MDR-compliant sterile fill-finish infrastructure.
Within the integrated platform tier, Smith & Nephew and Solventum exemplify divergent strategic positioning. Smith & Nephew anchors acute-care presence through negative-pressure system integration. Solventum occupies a position separating advanced biologics from commodity bandages to create distinct pricing tiers. Mölnlycke Health Care represents the silicone-adhesive specialization archetype across European hospital procurement networks.
| Leading Market Players |
|---|
| Smith & Nephew |
| Solventum |
| 3M |
| ConvaTec Group |
| Mölnlycke Health Care |
| Johnson & Johnson Services |
| Cardinal Health |
| B. Braun |
| Coloplast |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up wound care specialists have consolidated sterile fill-finish capacity across Midwestern United States manufacturing zones, tightening pricing discipline on advanced alginate and hydrogel substrates while compressing procurement leverage for independent distributors serving long-term care networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs wound management procurement, with FDA 510(k) clearance tier and GMP certification grade driving spreads between negative-pressure systems and commodity gauze. Cost compression in silver-impregnated alginate segments is intensifying because Chinese refining volatility feeds raw material price swings. Home health agencies exhibit highest price sensitivity due to Medicare reimbursement lag, while Veterans Affairs medical centers tolerate premium positioning for bioactive dressing protocols.
Supply Chain Analysis
Direct-to-hospital-GPO channels handle acute-care demand for integrated negative-pressure platforms, while home infusion distributors manage decentralized post-acute procurement. Manufacturing concentrates in United States, Germany, and China, with Yangtze River Delta zones supplying polyurethane foam substrates and Baden-Württemberg clusters specializing in silicone-adhesive sterile fill-finish. Silver nanoparticle refining rests on Chinese smelting operations, creating single-source vulnerability for antimicrobial dressing producers. Distribution runs through Cardinal Health and McKesson networks for hospital systems, with regional distributors capturing long-term care and home care fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in wound management hinges on bioactive ingredient cost-down curves and the shift toward premium electrical stimulation dressing tiers absorbing diabetic foot ulcer protocol share from growth factor therapies.
For Market Incumbents: Extend negative-pressure platform integration into home care channels before hospital-at-home programs unbundle supply contracts entirely. Backward integration into alginate biopolymer sourcing mitigates EU MDR documentation delays threatening CE marking timelines for hydrogel classification upgrades. For New Entrants and Emerging Players: Telehealth-embedded wound monitoring apps offer the most penetrable white-space route, combining smartphone measurement tools with AI healing prediction for remote patient monitoring bundles. Target Indian home care networks through Apollo and Max hospital distribution partnerships, leveraging CDSCO priority review for antimicrobial innovations with existing FDA clearances. For Investors and Strategic Acquirers: Integrated medical device conglomerates with wound care divisions are the most active acquirer in this space, seeking alginate and hydrogel technology to fill substrate sophistication gaps. Long-term viability centers on EU MDR-compliant sterile manufacturing certification as the scarcity signal distinguishing premium-tier targets from commodity bandage producers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks German and French hospital network procurement for alginate innovators. |
| Hospital System Partnership | Direct contracts with Pennsylvania and Ohio hospital-at-home programs secure negative-pressure canister volume. |
| Backward Integration | In-house brown seaweed alginate sourcing insulates margins from Chinese silver nanoparticle volatility. |
| Software Companion Development | AI-powered healing prediction algorithms create subscription revenue streams for telehealth providers. |
| Reimbursement Strategy | CMS home-based wound care code advocacy reduces commercial risk for advanced dressing manufacturers. |
Study Parameters
Multiple input streams — wound care procurement managers at integrated delivery networks, biomedical engineers specializing in negative-pressure therapy, GPO contracts managers, and home health agency supply chain directors — were reconciled against FDA 510(k) clearance databases, CMS Medicare reimbursement filings, EU MDR submission records, and hospital procurement database extracts. Bottom-up segmentation modeling across product type, application, end user, and technology dimensions was triangulated with top-down macro validation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with CAGRs derived from trend extrapolation of diabetic foot ulcer incidence, post-acute site-of-care migration rates, and antimicrobial dressing adoption curves. Segmentation dimensions modeled include wound severity tier, substrate technology sophistication, reimbursement pathway intensity, and regional regulatory cluster alignment.
Silver price volatility, EU MDR documentation timeline extensions, and CMS reimbursement code revision delays are the dominant revision risks to forecast trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
LAMEA Surgical Dressing Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Wound Healing Nutrition Market
Wound Care
South Korea Wound Care Management Market
Wound Care
Wound Irrigation Devices Market
Wound Care
Surgical Wound Care Market
Wound Care
Burn Care Centers Market
Wound Care
Chronic Wound Care Market
Wound Care
Wound Skin Care Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Wound Debridement Products Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
Post-Operative Wound Treatment Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Global Traditional Wound Management Market
Wound Care
United States Negative Pressure Wound Therapy Market