
 Wound Closure Strips Market | 2026-2036
Wound Closure Strips Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Closure Strips Market Analysis
China is fragmenting as domestic manufacturers expand sterile strip capacity for regional hospital supply chains. 3M leverages its materials science portfolio to sustain premium positioning across North American and European channels. Johnson & Johnson anchors its wound closure franchise through broad distribution in acute care settings, while Smith & Nephew competes on advanced adhesive formulations for surgical applications.
Wound closure strips are sterile adhesive banding devices, typically constructed from porous non-woven substrates coated with hypoallergenic acrylate adhesives, designed to approximate wound edges without suture penetration. Their primary commercial purpose centers on reducing infection risk, minimizing scar formation, and accelerating healing in superficial lacerations and surgical incisions. The adhesive strips segment dominates hospital procurement due to lower unit costs and established clinical familiarity, while waterproof variants represent the fastest-expanding category as home care and post-discharge protocols proliferate. Material-grade polyester commands margin concentration because of superior tensile strength and breathability in extended-wear applications.
The FDA oversees medical device classification and 510(k) clearance pathways for adhesive wound closure products in the United States, while the EMA and MDR framework govern biocompatibility and sterilization validation standards across European markets. These regulatory structures elevate barriers for uncertified suppliers and redirect procurement toward documented quality systems. Stakeholders must monitor evolving sterilization requirements and adhesive biocompatibility testing protocols to maintain market access across jurisdictions.
Market Dynamics
The FDA's updated medical device classification guidelines for adhesive wound closure products are tightening quality benchmarks and reshaping supplier qualification requirements across hospital procurement channels.
Growth Catalysts
- Outpatient Surgical Expansion:Hospitals are expanding procurement of sterile and waterproof variants for outpatient surgical procedures, driving volume concentration in acute care settings.
- MDR Biocompatibility Standards:The EMA's MDR framework elevates sterilization validation requirements, redirecting procurement toward documented quality systems and certified suppliers.
- Post-Acute Protocol Standardization:Health systems in the United States are standardizing post-acute wound care protocols and reducing reliance on sutures for minor closures.
Market Restraints
- Polyester Raw Material Volatility:Material-grade polyester commands margin concentration, creating input cost exposure for manufacturers dependent on petrochemical supply chains.
- China Supply Fragmentation:Domestic Chinese manufacturers are expanding sterile strip capacity, creating regional oversupply pressure and price compression in Asian markets.
- Technical Limitation in Deep Tissue:Adhesive strips cannot approximate wound edges in deep lacerations or high-tension surgical sites, limiting addressable procedure types.
Strategic Opportunities
- Home Care Channel Expansion:Waterproof variants represent the fastest-expanding category as post-discharge protocols proliferate and patients manage wound care outside clinical settings.
- Extended-Wear Material Innovation:Breathable polyester substrates with superior tensile strength enable multi-day wear applications in chronic wound management.
- 510(k) Pathway Optimization:The FDA's streamlined clearance pathways for adhesive wound closure products create regulatory tailwinds for documented quality systems.
Industry Challenges
- Sterilization Validation Timelines:Biocompatibility testing protocols for hypoallergenic acrylate adhesives extend certification cycles, compressing product launch windows.
- Legacy Suture Integration:Surgical workflows retain embedded suture techniques, requiring clinical education investment to shift established closure habits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Closure Strips Market |
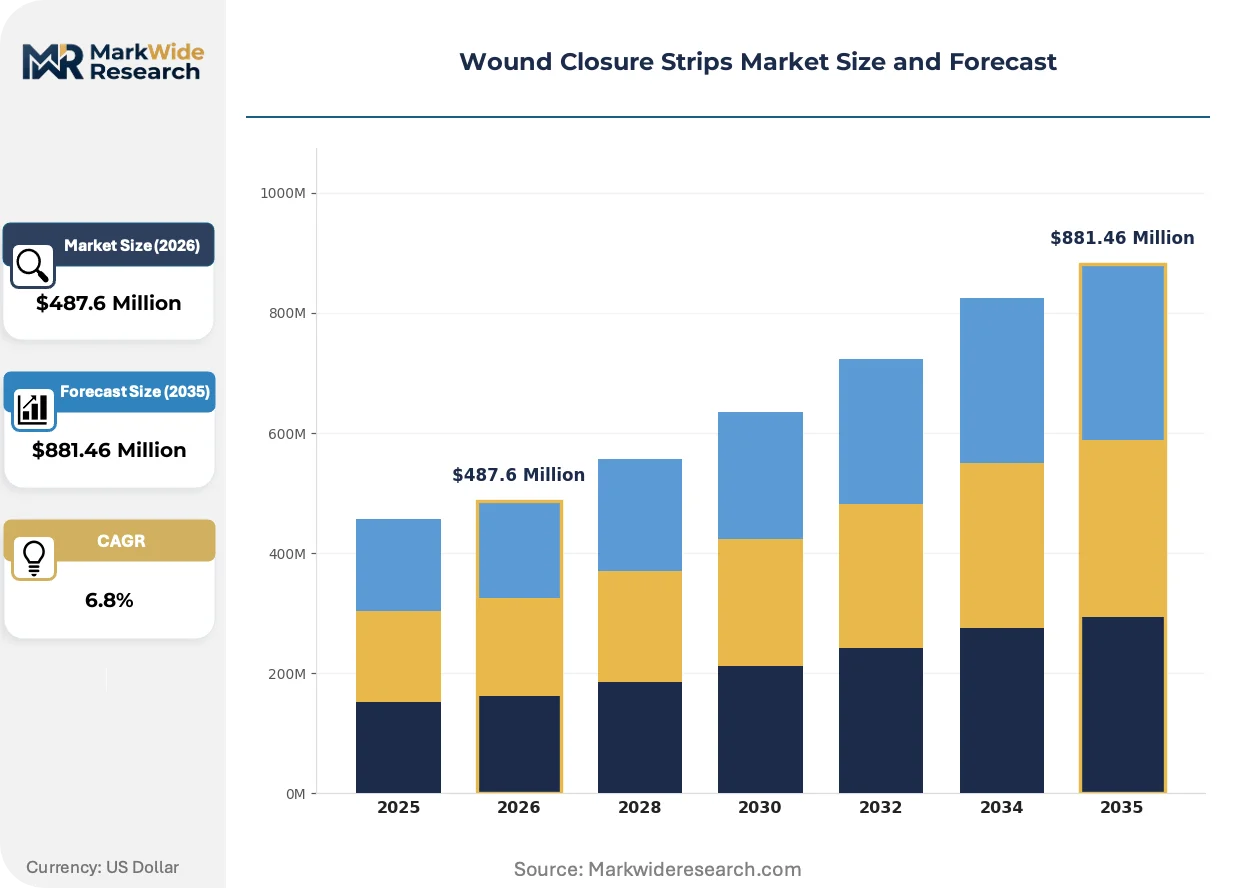
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Strips, Sterile Strips, Waterproof Strips, Surgical Strips Material: Polyester, Polypropylene, Cotton, Elastomer End User: Hospitals, Clinics, Home Care, Emergency Services Application: Trauma Care, Surgical Procedures, Wound Management, Aesthetic Closure |
| Companies Covered | 3M, Johnson & Johnson, Medtronic, Smith & Nephew, B. Braun Melsungen AG, Mölnlycke Health Care, DeRoyal Industries, Inc., Medline Industries, LP, ConvaTec Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Closure Strips Market Emerging Trajectories
Advanced adhesive formulations and substrate engineering are compressing healing timelines and expanding the clinical utility of non-invasive wound closure beyond superficial applications.
Silicone-based medical adhesives with controlled tack and peel properties are rendering obsolete traditional acrylate formulations in extended-wear applications. Hospital procurement teams are prioritizing these materials for post-surgical discharge kits. The shift is compressing margins for commodity adhesive suppliers while concentrating premium positioning among materials science specialists.
REACH compliance requirements for chemical substance registration are elevating documentation burdens for European market entry. Manufacturers must demonstrate biocompatibility traceability across adhesive supply chains. Waterproof strip categories face the steepest compliance cost escalation, forcing portfolio rationalization toward validated formulations.
Hospital buying consortiums are consolidating vendor relationships around single-source contracts for standardized wound care protocols. Group purchasing organizations are displacing fragmented supplier networks in the United States. This concentration rewards manufacturers with broad sterile product portfolios and documented quality systems.
Wound Closure Strips Market Segmentation
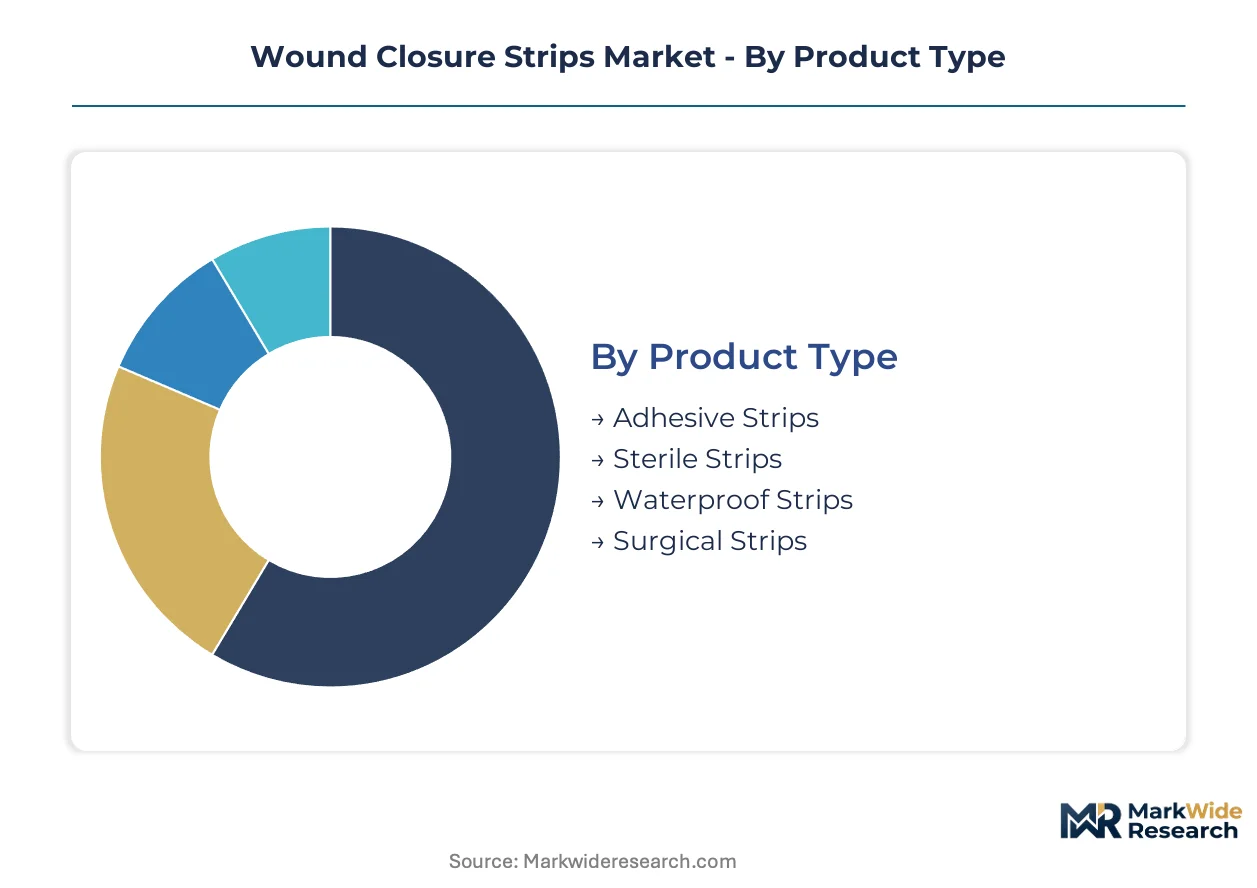
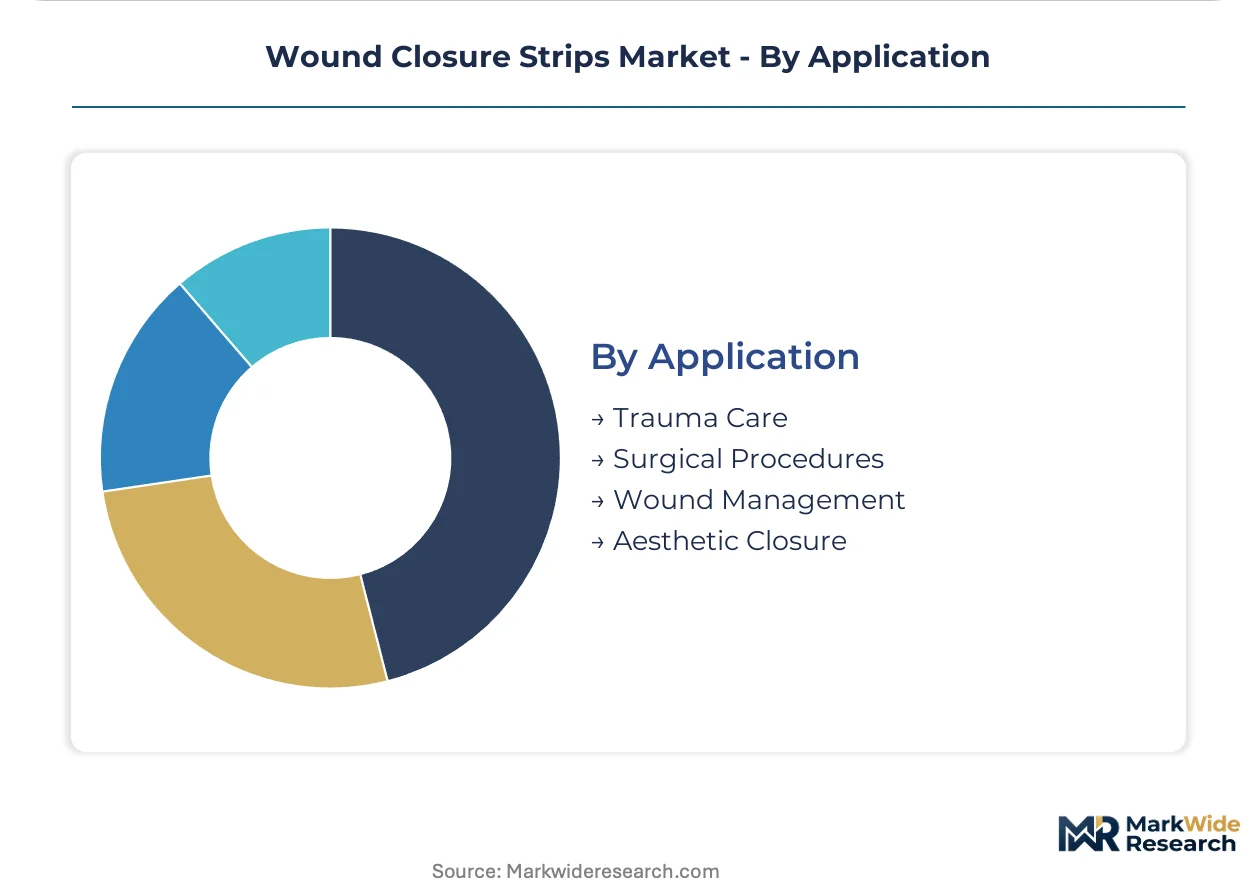
Wound closure strips fragment across four intersecting dimensions that determine procurement cadence and margin structure. Product type and material composition drive replenishment velocity, while end-user channel and application setting dictate pricing power and regulatory burden.
Product Type:
Cycle times vary sharply across product types, with sterile variants turning fastest due to expiration-sensitive hospital contracts while waterproof formats sit in inventory longer before home care deployment.
- Adhesive Strips:Non-sterile porous strips coated with hypoallergenic acrylate adhesives serve superficial lacerations in primary care. United States health systems standardize these for minor closures, reducing suture dependency in outpatient protocols.
- Sterile Strips:Gamma-sterilized variants packaged in individual peel pouches meet surgical site infection protocols. Hospital procurement in the United States concentrates volume here, driven by Joint Commission audit requirements and bundled payment incentives.
- Waterproof Strips:Occlusive polyurethane film barriers enable showering and mobility in post-discharge recovery. Home care channel expansion accelerates turnover as patients manage wounds outside clinical settings.
- Surgical Strips:High-tensile reinforced formats for operative incision closure. Acute care settings in the United States anchor demand, though adoption faces resistance from embedded suture workflows.
Adhesive strips anchor the volume base while waterproof strips gain share at the steepest rate.
Material:
Cost tiers separate commodity substrates from performance-engineered alternatives, with petrochemical-linked inputs exposing margin volatility.
- Polyester:Woven or non-woven polyethylene terephthalate substrates deliver superior tensile strength and breathability for multi-day wear. Extended-wear applications in chronic wound management concentrate demand in the United States post-acute sector.
- Polypropylene:Lightweight olefin-based non-wovens offer moisture resistance at lower unit cost. Mass-market hospital contracts in the United States favor this grade for high-volume disposable protocols.
- Cotton:Natural fiber substrates provide skin-friendly alternatives for pediatric and geriatric populations with adhesive sensitivity. Niche positioning limits scale.
- Elastomer:Stretch-recovery formulations accommodate joint mobility and contoured anatomical sites. Sports medicine and emergency services applications drive intermittent demand.
Polypropylene dominates procurement tonnage while polyester commands the premium tier expansion.
End User:
Customer type determines contract structure, with institutional buyers consolidating around single-source agreements while home care fragments across retail and direct-to-patient channels.
- Hospitals:Integrated delivery networks in the United States consolidate purchasing through group buying organizations, favoring suppliers with broad sterile portfolios and documented FDA quality systems.
- Clinics:Ambulatory surgery centers and urgent care facilities drive spot purchasing of mixed sterile and non-sterile formats. Turnover accelerates with procedure volume seasonality.
- Home Care:Patients and caregivers manage post-discharge wound care through retail pharmacy and e-commerce channels. Waterproof and extended-wear variants expand fastest here.
- Emergency Services:First responder kits require compact, sterile, multi-purpose formats with extended shelf stability. Government procurement cycles create lumpy demand patterns.
Hospitals concentrate revenue volume while home care climbs the fastest as site-of-care shifts accelerate.
Application:
Clinical setting dictates performance requirements, with acute interventions demanding validated sterility while chronic management prioritizes wear comfort and cost efficiency.
- Trauma Care:Emergency department and field applications require rapid-application formats for hemorrhage control and temporary wound approximation. Sterile strip demand concentrates in United States Level I trauma centers.
- Surgical Procedures:Operating room protocols specify sterile, high-tensile strips for incision closure in low-tension sites. Bundled payment models in the United States drive standardization away from sutures for eligible procedures.
- Wound Management:Chronic and post-acute settings employ breathable, extended-wear formats for diabetic ulcers and pressure injuries. Home care protocols proliferate across United States Medicare Advantage networks.
- Aesthetic Closure:Cosmetic surgery and dermatology applications prioritize low-visibility, hypoallergenic adhesives to minimize scar formation. Private pay dynamics sustain premium pricing.
Surgical procedures anchor institutional procurement while wound management expands most quickly through post-acute protocol proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA quality system requirements anchor procurement concentration in the United States, while EMA MDR frameworks reshape European supplier qualification. Hospital buying consortiums and post-acute protocol standardization drive divergent regional demand patterns.
United States
Integrated delivery networks consolidate purchasing through group buying organizations, prioritizing suppliers with documented FDA quality systems and broad sterile portfolios. The Joint Commission audit requirements and bundled payment incentives accelerate standardization away from sutures for eligible outpatient procedures. Medical device manufacturing clusters in Minnesota and Massachusetts concentrate materials science capabilities for next-generation adhesive substrates.
Germany
EMA MDR biocompatibility standards elevate sterilization validation requirements, redirecting hospital procurement toward certified suppliers with REACH-compliant adhesive formulations. The country's statutory health insurance system reimburses waterproof and extended-wear variants for post-discharge wound management. Industrial concentrations in Baden-Württemberg and North Rhine-Westphalia host precision coating and non-woven substrate engineering facilities.
China
Domestic manufacturers expand sterile strip capacity for regional hospital supply chains, creating price compression pressure across Asian markets. NMPA medical device registration requirements tighten quality benchmarks for imported adhesive wound closure products. Manufacturing clusters in Jiangsu and Zhejiang provinces scale polyester substrate production for both domestic consumption and export markets.
Japan
PMDA regulatory frameworks emphasize biocompatibility traceability and extended-wear performance validation for elderly patient populations. The country's aging demographic concentrates demand in chronic wound management and home care applications. Medical device engineering capabilities in the Kansai and Chubu regions advance silicone-based adhesive formulations with controlled tack properties.
United Kingdom
NHS supply chain consolidation favors single-source contracts for standardized wound care protocols, displacing fragmented supplier networks. MHRA post-Brexit regulatory autonomy maintains alignment with MDR sterilization standards while streamlining 510(k)-equivalent clearance pathways. Life sciences clusters in Cambridge and the Golden Triangle concentrate advanced materials development for breathable, high-tensile substrates.
Wound Closure Strips Market Vendor Landscape
Diversified health care conglomerates and specialized wound management firms split the market along premium-standard-economy tiers. Materials science capabilities and regulatory documentation quality determine positioning within hospital procurement channels. Three archetypes dominate: integrated medical device manufacturers with broad sterile portfolios, adhesive substrate specialists leveraging polymer chemistry expertise, and regional fabricators competing on unit cost for high-volume disposable contracts. Competitive moves concentrate on portfolio diversification into waterproof and extended-wear formats, plus geographic expansion through distributor partnerships in fragmented Asian markets.
Among diversified health care manufacturers, 3M, Johnson & Johnson, and Smith & Nephew occupy positions across premium adhesive formulation and substrate engineering tiers. These entities exemplify strategic archetypes built on materials science depth, acute care distribution scale, and surgical application specialization respectively. Their collective presence anchors procurement consolidation in North American and European hospital systems, while their regulatory documentation capabilities create qualification barriers for secondary competitors.
| Leading Market Players |
|---|
| 3M |
| Johnson & Johnson |
| Medtronic |
| Smith & Nephew |
| B. Braun Melsungen AG |
| Mölnlycke Health Care |
| DeRoyal Industries, Inc. |
| Medline Industries, LP |
| ConvaTec Group |
| Others |
Supply Flow & Price Mechanics
China's polyester substrate manufacturing clusters anchor global raw material supply for wound closure strips, concentrating margin capture upstream while downstream pricing power fragments across hospital buying consortiums and retail pharmacy channels. Petrochemical-linked input costs transmit volatility through the value chain, compressing margins for converters lacking backward integration into non-woven substrate production.
Pricing Analysis
United States hospital contracts command 40-60% premiums over Asian spot pricing for sterile strip formats validated to FDA quality systems. Three-tier pricing structure across premium silicone-adhesive, standard acrylate, and economy polypropylene grades separates procurement tiers by certification depth and wear duration. Pricing pressure stems from Chinese domestic manufacturers expanding sterile capacity and undercutting import landed costs. Ambulatory surgery centers exhibit highest price sensitivity due to thin procedure margins, while integrated delivery networks prioritize total cost of ownership including infection risk reduction.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for wound closure strip importers, prompting dual-sourcing strategies across Southeast Asian substrate converters. Manufacturing concentrates in China, Germany, and the United States for medical-grade non-wovens, with adhesive formulation expertise clustering in Minnesota and Baden-Württemberg. Raw material dependencies span petroleum-derived polyester chips, medical-grade silicone polymers, and gamma-sterilization services. Distribution runs through group purchasing organizations in North America and statutory health insurance procurement frameworks in Germany, with e-commerce platforms gaining share in home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wound closure strips market functions as a service-attach opportunity where waterproof extended-wear formats and post-discharge patient education subscriptions expand recurring revenue faster than commodity adhesive strip hardware sales.
For Market Incumbents: Harden regulatory documentation moats by accelerating 510(k) pathway submissions for silicone-adhesive formulations before FDA classification guidelines tighten further. Deepen backward integration into polyester substrate production to offset petrochemical cost volatility and defend margin position against Chinese import price compression. Prioritize hospital system partnership contracts that bundle sterile strip supply with clinician training programs on suture-reduction protocols. For New Entrants and Emerging Players: Pursue white-space positioning in home care waterproof segments where brand recognition remains undeveloped and direct-to-patient e-commerce channels bypass entrenched GPO relationships. Target Medicare Advantage network wound management protocols as the most penetrable reimbursement pathway, leveraging extended-wear performance claims to differentiate from commodity alternatives. Deploy telehealth-integrated patient support services as the primary go-to-market angle, capturing recurring revenue through subscription-based wound monitoring. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale adhesive substrate specialists with documented FDA quality systems and existing sterile strip capacity, positioned for consolidation into hospital buying consortium vendor lists. Long-term viability across the analysis window hinges on materials science capabilities in silicone polymer formulation and REACH-compliant supply chain traceability. Watch NMPA registration timelines for imported products as the inflection signal indicating when Chinese domestic oversupply begins compressing export pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Early clearance capture ahead of tightened classification guidelines secures hospital procurement qualification. |
| Silicone-Adhesive Formulation R&D | Controlled-tack polymer chemistry enables extended-wear premium positioning against acrylate commoditization. |
| Hospital System Partnership Contracting | Single-source agreements with integrated delivery networks lock out fragmented competitors through bundled training. |
| Backward Integration into Substrate Production | In-house polyester non-woven manufacturing insulates margin from petrochemical price volatility. |
| Home Care Channel E-Commerce Launch | Direct-to-patient waterproof strip sales bypass GPO concentration and capture post-discharge protocol expansion. |
Methodological Framework
The analysis maps adhesive strip, sterile strip, waterproof strip, and surgical strip sub-sectors, each validated through hospital procurement managers, GPO contracts specialists, biomedical engineers, and wound care clinicians. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement contract disclosures, and customs trade data. Bottom-up segment sizing and top-down market triangulation cross-checked volume assumptions against operating metrics reported across medical device manufacturer disclosures.
Fixed assumptions across the modeling period include continued FDA quality system enforcement, stable REACH compliance frameworks in Europe, and sustained Medicare Advantage wound management reimbursement. Segmentation dimensions modeled span product type, material substrate, end-user channel, and application setting, with regional regulatory clusters treated as distinct demand environments. CAGRs derived from procedure volume elasticity to outpatient surgical expansion and suture substitution rates, with silicone-adhesive adoption curves and home care channel penetration serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in petroleum feedstock pricing, trade tariff schedules, or hospital capital expenditure cycles would shift the trajectory of substrate cost structures and procurement volume. Forecasts reflect assumptions held fixed across the projection horizon, with sterilization validation timeline extensions and Chinese domestic capacity additions representing specific risk factors warranting continuous validation against operating reality.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Closure Devices Market
Wound Care
Advanced Wound Care Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Advanced Wound Care Management Market
Wound Care
United States Negative Pressure Wound Therapy Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Moist Wound Dressings Market
Wound Care
Global Compression Bandages Market
Wound Care
Dental Wound Dressings Market
Wound Care
Animal Wound Care Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Global Silver Wound Dressing Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Europe Compression Bandages Market