
 Wound Drainage Devices Market | 2026-2036
Wound Drainage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Drainage Devices Market Analytics
Malaysia is rewriting regional supply dynamics for wound drainage components through expanded cleanroom manufacturing parks in Penang. BD leverages its integrated catheter production network across North America and Asia to sustain cost advantages in closed drainage systems. Medtronic anchors its position through deep R&D investment in negative pressure wound therapy platforms. Stryker competes aggressively in the trauma wound segment with specialized suction canister designs.
Wound drainage devices are closed or open catheter-suction systems, typically constructed from medical-grade silicone or polyvinyl chloride with 100-800 mL collection capacity, designed to evacuate fluid from surgical sites and prevent hematoma or seroma formation. The primary commercial purpose centers on reducing postoperative infection rates and accelerating tissue healing timelines. Closed drainage systems dominate hospital procurement budgets due to established reimbursement codes and lower infection risk profiles, while negative pressure wound therapy represents the fastest-expanding category as home care protocols extend beyond acute settings. Silicone materials command premium positioning in chronic wound applications where biocompatibility and extended dwell times determine clinical outcomes.
FDA 510(k) clearance pathways and the EU MDR classification rules for Class IIa medical devices shape product development timelines and market access costs for manufacturers. The EPA regulates medical waste handling standards that influence disposable drainage system design, while ISO 13485 quality management certification functions as a baseline procurement filter for hospital supply chains. Stakeholders must monitor evolving reimbursement thresholds for outpatient negative pressure therapy as payer policies increasingly determine whether device innovation translates to commercial volume.
Market Dynamics
EU MDR compliance deadlines are compressing product development cycles for wound drainage manufacturers, forcing simultaneous redesigns of silicone catheter portfolios and sterilization validation protocols ahead of 2027 renewal thresholds.
Growth Catalysts
- ASC Surgical Volume Expansion:Ambulatory surgical centers in the United States are replacing inpatient procedures for orthopedic and cosmetic interventions, creating pull-through demand for compact closed drainage systems with rapid discharge protocols.
- EU MDR Classification Alignment:Reclassification of active drainage devices under Class IIa rules is accelerating documentation investments that improve traceability and reduce post-market surveillance liabilities for compliant manufacturers.
- Silicone Biocompatibility Premium:Chronic wound applications favor medical-grade silicone over PVC for extended dwell times, with Japan's aging patient population driving preference for hypoallergenic materials in home care settings.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Specialty silicone elastomer production clusters in Germany and Japan expose device manufacturers to input cost volatility when semiconductor and automotive sectors compete for polymer allocation.
- MDR Technical Documentation Burden:EU notified body capacity constraints extend product recertification timelines by 14-22 months, freezing portfolio refreshes for manufacturers without legacy CE mark grandfathering.
- Negative Pressure Therapy Substitution:Advanced NPWT platforms for surgical incisions capture cases previously managed with passive closed drainage, compressing addressable volume in acute care segments.
Strategic Opportunities
- Home Care Reimbursement Expansion:CMS and private payers in the United States are extending coverage for outpatient negative pressure therapy, enabling device manufacturers to capture 30-day post-discharge revenue streams previously lost to home health agencies.
- Malaysia Cleanroom Manufacturing:Penang's expanded medical device parks offer tariff-advantaged production bases for silicone component assembly serving ASEAN hospital procurement networks.
- Smart Drainage Sensor Integration:Convergence of microfluidic sensors with Bluetooth telemetry enables real-time output monitoring that reduces nursing workload and supports early discharge protocols in German and Japanese hospital systems.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies face 6-9 month queue times at accredited laboratories, delaying 510(k) and MDR submission timelines for new silicone formulations.
- Legacy ERP Integration Friction:Hospital supply chains in the United States and Germany require UDI-compliant labeling and electronic inventory tracking that forces mid-tier manufacturers to replace obsolete manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Drainage Devices Market |
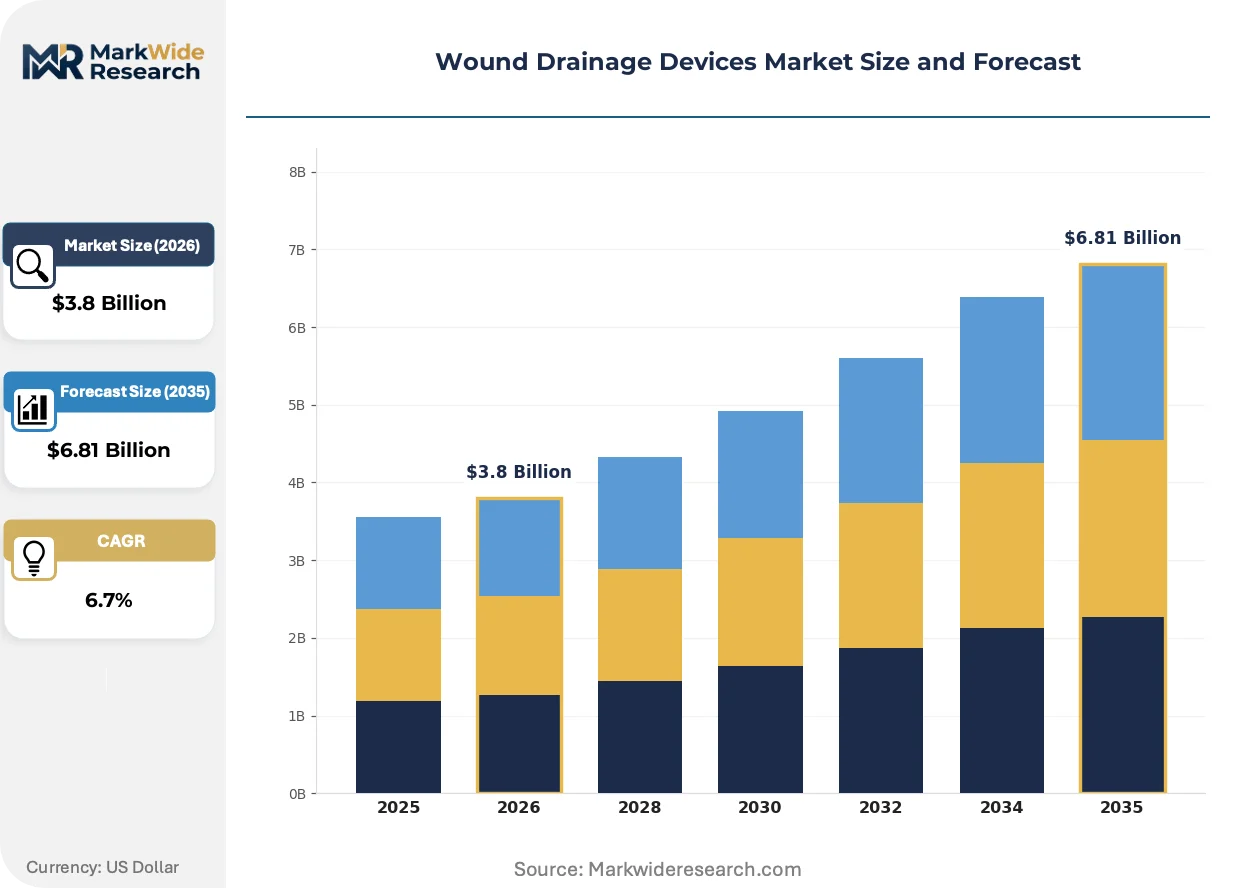
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Closed Drainage Systems, Open Drainage Systems, Negative Pressure Wound Therapy, Others Application: Surgical Wounds, Trauma Wounds, Chronic Wounds, Burns End User: Hospitals, Ambulatory Surgical Centers, Home Care, Clinics Material: Silicone, Polyvinyl Chloride, Polyethylene, Others |
| Companies Covered | BD, Medtronic, Stryker, Cook Medical, B. Braun Melsungen, Cardinal Health, ConvaTec, Zimmer Biomet, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Drainage Devices Market Evolving Landscape
Digital connectivity and materials science are converging to transform wound drainage from passive fluid removal into monitored therapeutic interventions, with sensor integration and bioresorbable alternatives commanding disproportionate R&D allocation.
Antimicrobial-impregnated silicone catheters incorporating silver-ion or chlorhexidine coatings are collapsing infection risk differentials between closed drainage and more expensive negative pressure systems. Academic medical centers in Germany and Japan are piloting these devices for cardiac and spinal procedures where surgical site infection carries catastrophic cost. The technology is compressing the premium positioning of active suction alternatives in prophylactic applications.
EU MDR Article 10 technical documentation requirements are forcing manufacturers to reconstruct clinical evidence packages for devices marketed pre-2021. The regulation demands systematic literature reviews and post-market clinical follow-up protocols that favor large portfolios with existing registry data. Small and mid-sized manufacturers without historical trial investment are exiting the European market or seeking acquisition by compliant strategics.
Hospital value analysis committees in the United States are unbundling drainage device procurement from surgical pack contracts, creating direct purchasing relationships with manufacturers that bypass distributor markups. This pattern concentrates volume with suppliers offering transparent pricing and consignment inventory models. The shift is most visible in integrated delivery networks across Texas and Florida where standardization mandates override surgeon preference cards.
Wound Drainage Devices Market Segmentation
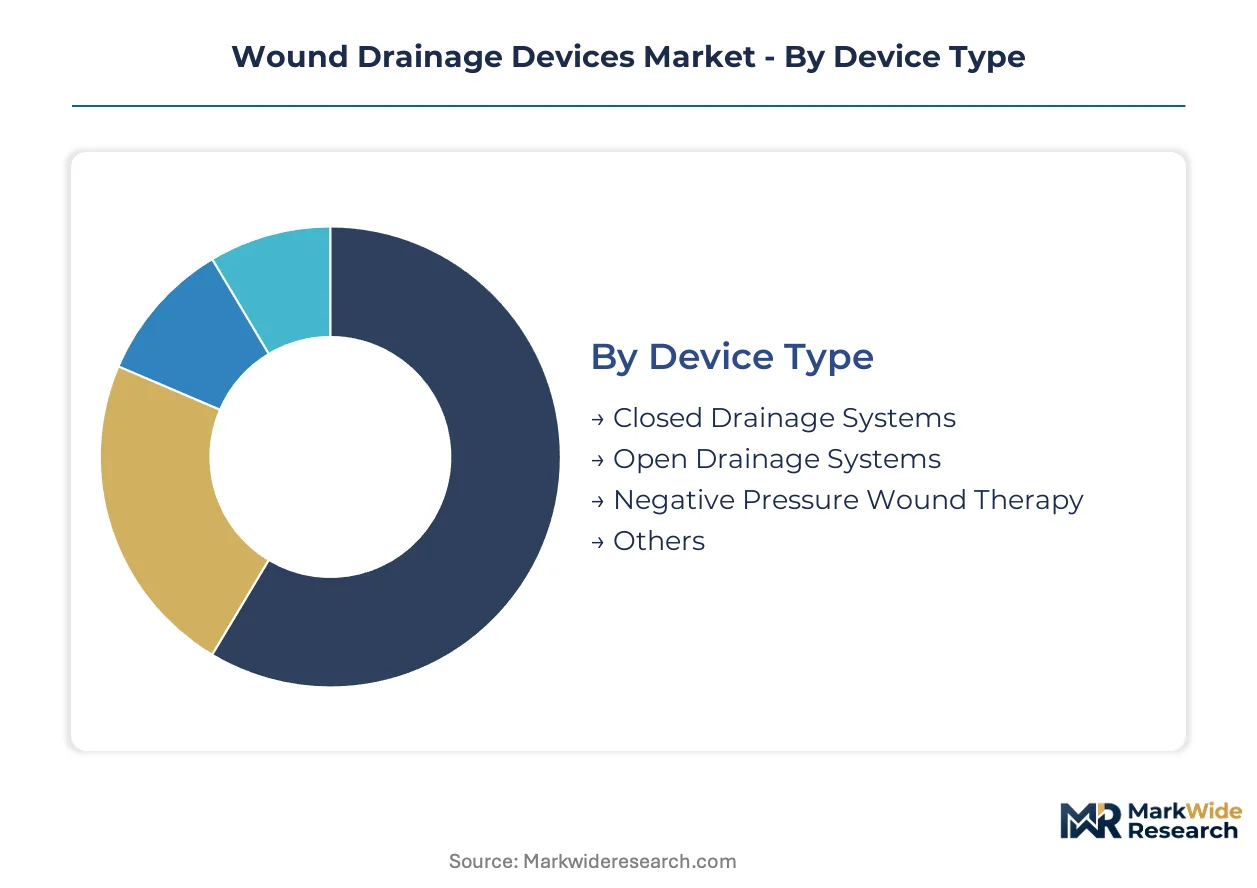
Wound drainage device segmentation reflects divergent clinical workflows across acute and post-acute settings. Procurement patterns split between hospital standardization mandates and ambulatory center preferences for compact disposable systems.
Device Type:
Mature closed systems dominate hospital budgets while emerging active technologies capture expansion in outpatient protocols.
- Closed Drainage Systems:Catheter-suction assemblies with 100-800 mL collection reservoirs constructed from medical-grade silicone or PVC. United States hospital procurement networks favor these systems for established reimbursement codes and lower surgical site infection rates in orthopedic procedures.
- Negative Pressure Wound Therapy:Portable suction platforms delivering sub-atmospheric pressure to incision sites through foam or gauze interfaces. Ambulatory surgical centers in Germany and Japan deploy these for rapid discharge protocols in cardiac and spinal interventions.
- Open Drainage Systems:Passive gravity-dependent configurations without active suction mechanisms.
- Others:Specialty configurations including sump drains and Penrose drains for specific anatomical applications.
Closed Drainage Systems retain volume leadership; Negative Pressure Wound Therapy holds the steepest expansion curve.
Application:
Cost tier stratification separates prophylactic surgical deployment from complex chronic wound management requiring extended dwell times.
- Surgical Wounds:Prophylactic placement in orthopedic, cardiac, and abdominal procedures to prevent hematoma and seroma accumulation. United States integrated delivery networks standardize these devices across surgeon preference cards in Texas and Florida systems.
- Chronic Wounds:Diabetic foot ulcers and pressure injuries requiring biocompatible materials for multi-week indwelling periods. Japan's aging demographic drives preference for hypoallergenic silicone formulations in home care transitions.
- Trauma Wounds:High-volume suction applications for penetrating injuries and fracture-related soft tissue damage.
- Burns:Specialized evacuation systems for exudate management in partial and full-thickness thermal injuries.
Surgical Wounds command the largest installed base; Chronic Wounds are climbing the fastest as population aging extends treatment durations.
End User:
Customer type fragmentation splits procurement authority between centralized hospital supply chains and decentralized ambulatory purchasing.
- Hospitals:High-volume purchasers operating through value analysis committees that unbundle drainage devices from surgical packs. German hospital systems require UDI-compliant labeling and electronic inventory tracking for traceability.
- Ambulatory Surgical Centers:Rapid-discharge facilities in the United States replacing inpatient orthopedic and cosmetic procedures. These centers prioritize compact closed drainage systems with simplified disposal protocols.
- Home Care:Post-acute settings where CMS reimbursement expansion enables 30-day negative pressure therapy coverage.
- Clinics:Outpatient wound care centers managing debridement and dressing changes without overnight stays.
Hospitals retain volume leadership; Ambulatory Surgical Centers hold the steepest expansion curve.
Material:
Supply concentration in specialty polymer production creates margin pressure across the cost tier spectrum.
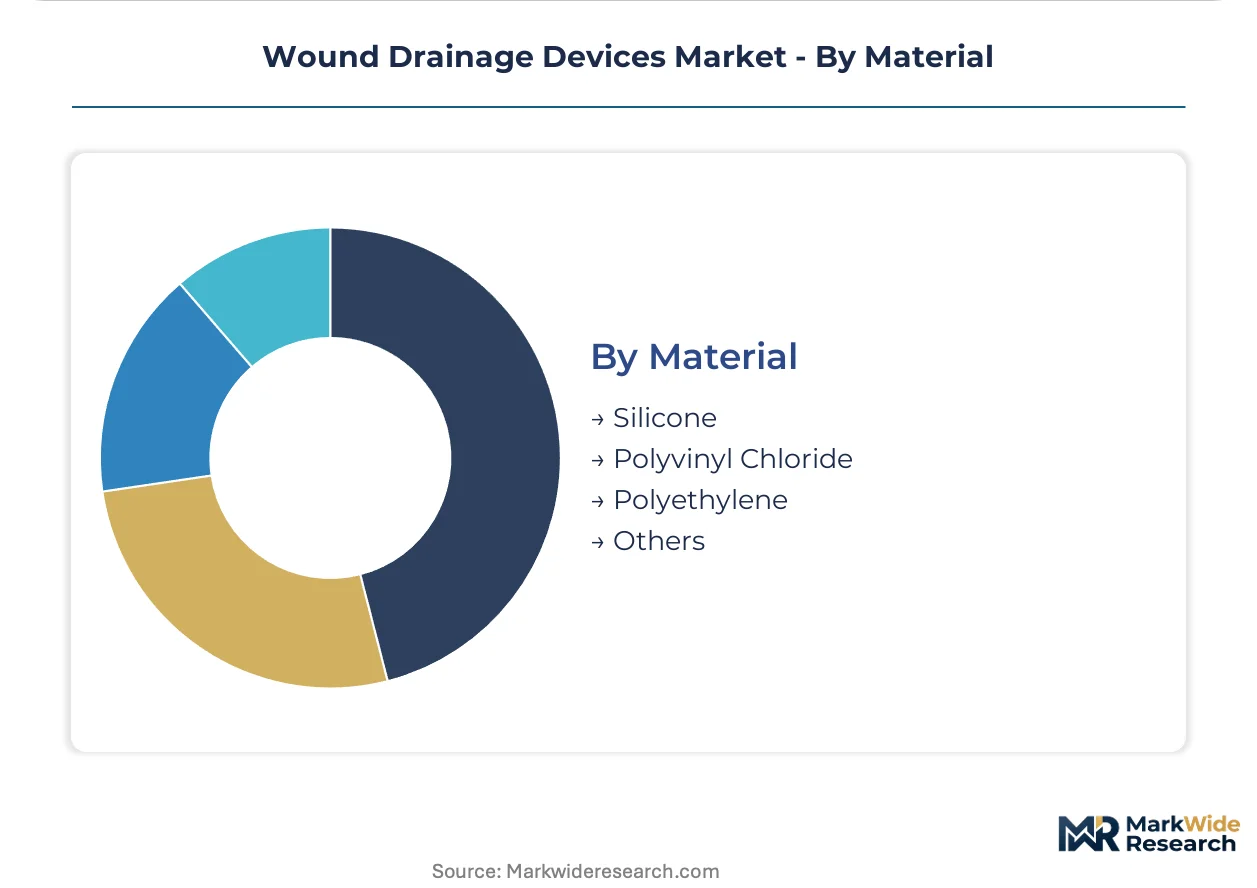
- Silicone:Medical-grade elastomers offering superior biocompatibility and extended dwell tolerance for chronic applications. Production clusters in Germany and Japan expose device manufacturers to input cost volatility when semiconductor and automotive sectors compete for polymer allocation.
- Polyvinyl Chloride:Cost-effective thermoplastic dominating acute care disposable applications with shorter indwelling requirements.
- Polyethylene:Alternative polymer for specific catheter shaft constructions and collection chamber components.
- Others:Emerging bioresorbable materials and antimicrobial-impregnated formulations under development.
Silicone retains premium positioning; Polyvinyl Chloride holds the steepest expansion curve in cost-sensitive procurement environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways in the United States anchor regulatory influence across wound drainage device markets, while EU MDR deadlines and Japan's PMDA frameworks create parallel compliance architectures that manufacturers must navigate simultaneously.
United States
Ambulatory surgical centers in Texas and Florida are replacing inpatient orthopedic procedures with rapid-discharge protocols that favor compact closed drainage systems. CMS reimbursement expansion for outpatient negative pressure therapy extends coverage to 30-day post-discharge periods. Integrated delivery networks in the Southeast unbundle drainage procurement from surgical packs, creating direct manufacturer relationships.
Germany
Hospital value analysis committees mandate UDI-compliant labeling and electronic inventory tracking for traceability across Baden-Württemberg and Bavaria health systems. EU MDR Article 10 technical documentation requirements compress product recertification timelines ahead of 2027 renewal thresholds. Specialty silicone elastomer production clusters in the Rhine-Ruhr region expose device manufacturers to input cost volatility from competing industrial sectors.
Japan
An aging patient population drives preference for hypoallergenic silicone formulations in home care transitions for chronic wound management. PMDA regulatory frameworks govern biocompatibility testing protocols for extended-dwell catheter applications. The Kansai region hosts concentrated medical device manufacturing infrastructure serving domestic hospital procurement networks.
Malaysia
Expanded cleanroom manufacturing parks in Penang offer tariff-advantaged production bases for silicone component assembly targeting ASEAN hospital procurement networks. The country's national medical device regulator aligns quality management certification with ISO 13485 baselines required by institutional buyers. Penang's medical device ecosystem attracts contract manufacturers seeking cost-competitive positions for closed drainage system assembly.
United Kingdom
NHS supply chain standardization mandates concentrate procurement authority through centralized frameworks that favor established CE-marked portfolios. MHRA post-Brexit regulatory divergence creates parallel conformity assessment requirements for devices accessing both UK and EU markets. The Midlands region maintains medical device manufacturing infrastructure serving domestic and export demand.
Wound Drainage Devices Market Competitive Landscape
Diversified medical technology conglomerates and specialized wound care manufacturers split the market across distinct capability tiers. Consolidation pressures favor portfolios with existing clinical evidence packages and MDR-compliant documentation. Three archetypes dominate: integrated surgical device suppliers with catheter manufacturing networks, dedicated wound management specialists with negative pressure platforms, and regional contract manufacturers with cleanroom assembly capacity. Competitive moves center on M&A activity targeting MDR-ready portfolios and strategic partnerships for sensor-integrated drainage systems.
Among diversified medical technology suppliers, BD exemplifies integrated catheter production capabilities spanning North American and Asian manufacturing footprints. Medtronic occupies a position representing deep R&D investment in active suction platforms. Stryker anchors the trauma wound segment archetype with specialized collection system designs. These three companies collectively illustrate how scale, specialization, and surgical workflow integration define competitive positioning in procurement environments shifting toward value-based contracting.
| Leading Market Players |
|---|
| BD |
| Medtronic |
| Stryker |
| Cook Medical |
| B. Braun Melsungen |
| Cardinal Health |
| ConvaTec |
| Zimmer Biomet |
| Teleflex Incorporated |
| Others |
Value Network & Pricing Analysis
Penang's cleanroom manufacturing parks are expanding silicone component assembly capacity faster than ASEAN hospital procurement networks can absorb volume, compressing unit economics for closed drainage systems while concentrating pricing power with integrated catheter producers.
Pricing Analysis
Price spreads between German-manufactured silicone catheters and Malaysian-assembled PVC alternatives run three-to-one across hospital procurement networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared silicone devices from CE-marked standard lines and unbranded economy disposables. Cost compression in the economy tier is intensifying because contract manufacturers in Penang are absorbing tariff advantages into volume discounts. Ambulatory surgical centers exhibit the highest price sensitivity due to rapid-discharge protocols that prioritize disposal cost over dwell-time performance.
Supply Chain Analysis
Specialty silicone elastomer production draws from concentrated chemical processing clusters in Germany, Japan, and the United States. Medical-grade polymer feedstocks, precision-molded catheter components, and sterilization packaging constitute the critical input stack. Single-source vulnerability in Rhine-Ruhr silicone supply exposes device manufacturers to allocation competition from semiconductor and automotive sectors. Distribution runs through hospital group purchasing organizations in the United States and centralized NHS frameworks in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Negative pressure wound therapy platforms are displacing passive closed drainage in acute surgical applications, forcing incumbent manufacturers to defend substitution risk through sensor integration and home care reimbursement capture.
For Market Incumbents: Harden portfolio defensibility by acquiring MDR-ready documentation packages from distressed mid-tier manufacturers ahead of 2027 renewal thresholds. Deepen backward integration into medical-grade silicone compounding to insulate margin structures from polymer allocation shocks in German and Japanese feedstock markets. For New Entrants and Emerging Players: Build out consignment inventory partnerships with Texas and Florida integrated delivery networks where value analysis committees have unbundled drainage procurement from surgical packs. Target ambulatory surgical center expansion corridors with compact closed systems optimized for rapid-discharge protocols and simplified disposal workflows. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with installed bases of negative pressure platforms eligible for CMS 30-day post-discharge reimbursement. Acquisition candidates with existing FDA 510(k) clearances and EU MDR technical documentation offer the cleanest integration profiles. Watch for inflection when smart drainage sensor integration achieves Bluetooth telemetry standardization across German and Japanese hospital systems.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Reconstruction | EU notified body capacity constraints favor portfolios with pre-assembled clinical evidence packages. |
| Smart Sensor Integration Partnership | Microfluidic Bluetooth telemetry reduces nursing workload in German hospital discharge protocols. |
| Malaysian Cleanroom Capacity Expansion | Penang medical device parks offer tariff-advantaged assembly for ASEAN procurement networks. |
| Home Care Reimbursement Strategy | CMS outpatient negative pressure coverage extension captures 30-day post-discharge revenue streams. |
| Antimicrobial Coating Development | Silver-ion silicone catheters collapse infection risk differentials with active suction alternatives. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and wound care clinicians. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body registration records, CMS Medicare reimbursement filings, and hospital procurement contract disclosures. Bottom-up volume estimates from catheter-suction assembly lines were triangulated against top-down expenditure flows from integrated delivery network capital budgets.
Calibration against historical adoption curves for negative pressure wound therapy and closed drainage system replacements anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include device type, application workflow, end-user procurement authority, material grade tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand functions incorporating surgical volume expansion rates and reimbursement policy shifts. Industry-specific inputs captured EU MDR recertification timeline delays and silicone polymer allocation competition from adjacent industrial sectors.
Stress conditions across EU notified body capacity constraints, medical-grade silicone supply volatility, and CMS reimbursement threshold adjustments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory deadline adherence and polymer feedstock availability. Cross-checking against hospital capital expenditure surveys and medical device import customs records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Topical Wound Agents Market
Wound Care
Global Wound Dressings Market
Wound Care
Global Antimicrobial Dressings Market
Wound Care
Foam Dressing Market
Wound Care
Bioactive Wound Care Market
Wound Care
Moist Wound Dressings Market
Wound Care
South Korea Wound Care Market
Wound Care
US Burn Care Centers Market
Wound Care
Wound Care Market
Wound Care
Wound Closure Strips Market
Wound Care
France Wound Care Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Burn Care Centers Market
Wound Care
Asia Pacific Advanced Wound Care Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market