
 Placental Protein Market | 2026-2036
Placental Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Placental Protein Market Analysis
Capital-intensity divergence between contract manufacturers and vertically integrated biotech firms is redrawing competitive boundaries in placental protein supply. Takara Bio Inc. leverages its recombinant expression platforms to occupy premium research-grade segments. MIMEDX Group, Inc. anchors the therapeutics channel through its proprietary amniotic tissue processing infrastructure. Lee BioSolutions competes on catalog breadth and same-day fulfillment for diagnostic assay developers.
Placental protein comprises bioactive peptides, growth factors, and extracellular matrix proteins extracted from human or animal placental tissue, typically processed through cold-chain homogenization, chromatographic purification, and sterile filtration to preserve cytokine activity for cell culture supplementation and wound healing formulations. Human placental protein leads the product type hierarchy due to superior bioactivity in stem cell expansion protocols, while recombinant placental protein is displacing native extracts in pharmaceutical manufacturing as regulators tighten adventitious agent controls. Therapeutics commands the largest application value pool, though nutraceuticals and cosmetic products are expanding fastest in Asian consumer markets where placental-derived collagen peptides carry premium positioning.
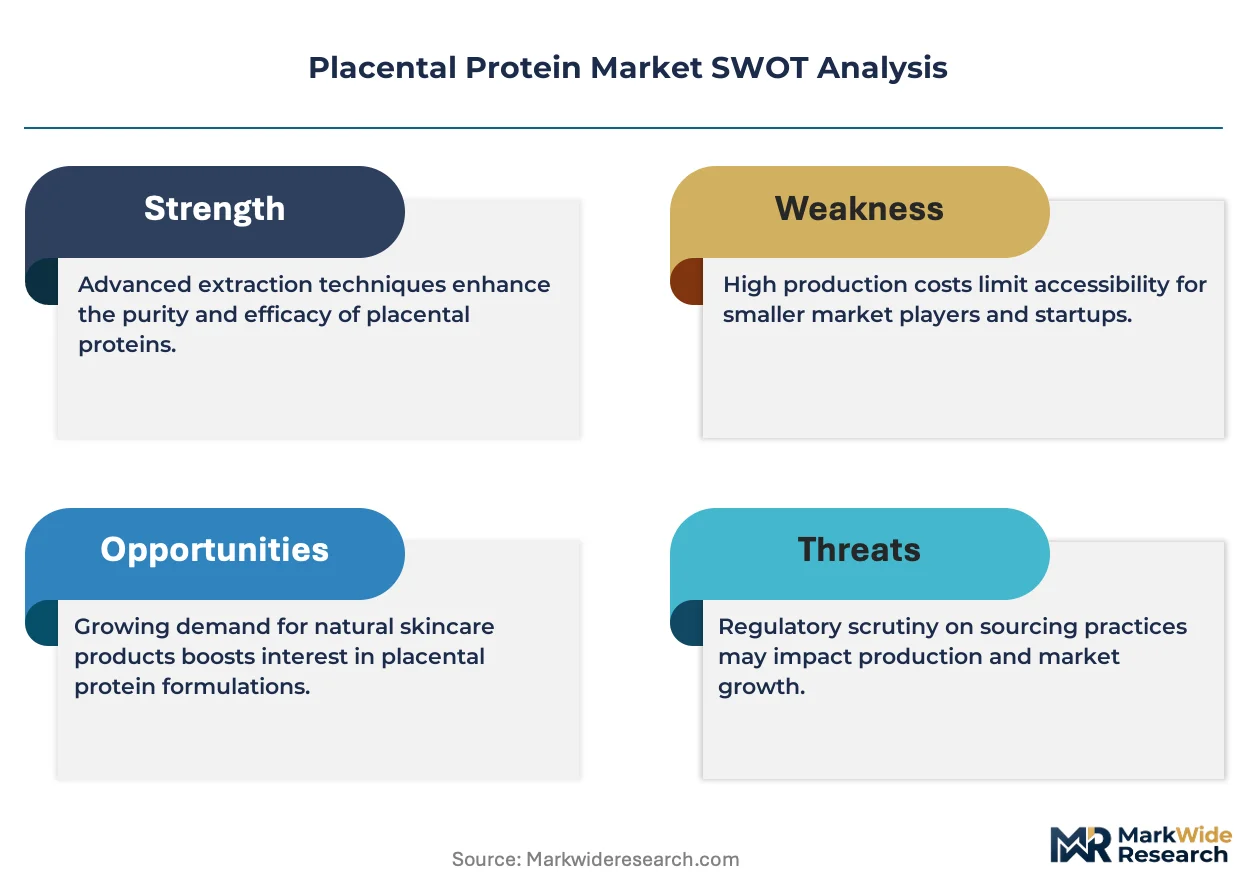
FDA biologics guidance and EMA human tissue directives impose stringent donor eligibility, traceability, and pathogen reduction mandates that elevate compliance costs for native placental processors. ISO 13485 and GMP certification requirements for therapeutic-grade material are forcing smaller suppliers toward contract manufacturing partnerships or exit. Stakeholders must monitor evolving FDA guidance on regenerative medicine advanced therapy designations and decide whether to build in-house viral clearance capacity or outsource to qualified contract testing organizations.
Market Dynamics
Regulatory bifurcation between human-derived and recombinant sourcing standards is fragmenting supplier capabilities and reshaping capital allocation across the placental protein value chain.
Growth Catalysts
- Regenerative medicine clusters:Boston and San Diego research hubs are expanding cell therapy manufacturing capacity, driving procurement of GMP-grade human placental protein for stem cell expansion protocols.
- FDA regenerative medicine advanced therapy designations:Expedited regulatory pathways for cell therapies are shortening development timelines and accelerating demand for qualified raw material suppliers.
- Chromatographic purification advances:Improved downstream processing technology is reducing viral clearance burden and enabling smaller processors to meet therapeutic-grade specifications.
Market Restraints
- Donor tissue scarcity:Stringent FDA and EMA donor eligibility criteria are constraining qualified placental supply, elevating raw material costs for native extract processors.
- Recombinant displacement pressure:Animal-free expression systems are substituting for human-derived material in pharmaceutical applications, compressing addressable market for traditional extractors.
- ISO 13485 certification burden:Therapeutic-grade quality system requirements are forcing smaller catalog suppliers toward contract manufacturing partnerships or market exit.
Strategic Opportunities
- Asian nutraceutical markets:Premium positioning of placental-derived collagen peptides in Japan and South Korea consumer channels offers expansion beyond regulated therapeutics.
- Viral clearance outsourcing:Contract testing organizations are capturing value from processors lacking in-house validation capacity under tightened FDA guidance.
- CE marking harmonization:EU MDR convergence on human tissue-derived device standards is creating consolidated certification pathways for European market entry.
Industry Challenges
- Cell therapy manufacturing talent:Scarce expertise in aseptic processing and viral validation is constraining operational scale-up for emerging suppliers.
- Cold-chain infrastructure investment:Preservation of cytokine activity requires continuous temperature-controlled logistics, elevating working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Placental Protein Market |
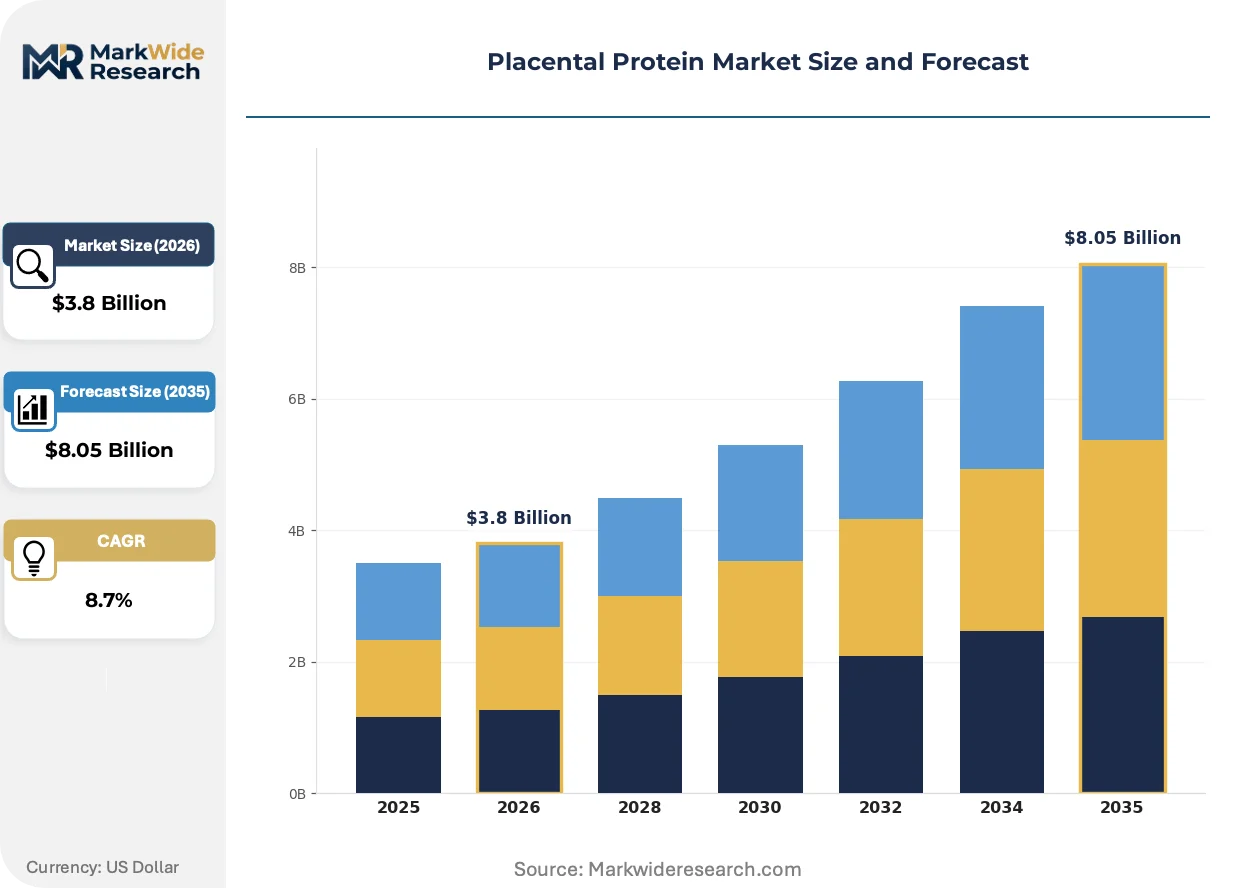
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Human Placental Protein, Animal Placental Protein, Recombinant Placental Protein, Purified Placental Protein End User: Pharmaceutical Companies, Research Institutes, Hospitals, Biotechnology Firms Application: Therapeutics, Diagnostics, Nutraceuticals, Cosmetic Products Form: Liquid, Powder, Lyophilized, Gel |
| Companies Covered | Takara Bio Inc., Lee BioSolutions, Japan Bio Products Co., Ltd., Cargill, Vital Proteins, Gelita AG, Scripps Laboratories, Amgen, MIMEDX Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Placental Protein Market Emerging Trajectories
Technology substitution, regulatory stringency escalation, and buyer consolidation are converging to restructure competitive positioning and sourcing relationships across the placental protein landscape.
Recombinant expression technology is bifurcating the market into premium human-derived and scalable biosynthetic supply tiers. Pharmaceutical manufacturers facing FDA adventitious agent controls are accelerating adoption of animal-free platforms. This technology split is compressing margins for native extract suppliers while enabling premium pricing for qualified human material in cell therapy applications.
EMA human tissue directives and FDA biologics guidance are tightening traceability mandates across European and American supply chains. Processors must now demonstrate chain-of-custody documentation from donor consent through final filtration. Therapeutic-grade material suppliers are responding by investing in dedicated donor recruitment networks and redundant pathogen screening protocols.
Diagnostic assay developers are consolidating supplier relationships around same-day fulfillment capabilities and expanded catalog breadth. Large reference laboratories are displacing fragmented purchasing across multiple vendors with single-source contracts. This concentration pattern is most visible in the United States, where centralized procurement functions at Quest Diagnostics and LabCorp are reshaping competitive dynamics for research-grade material.
Placental Protein Market Segmentation
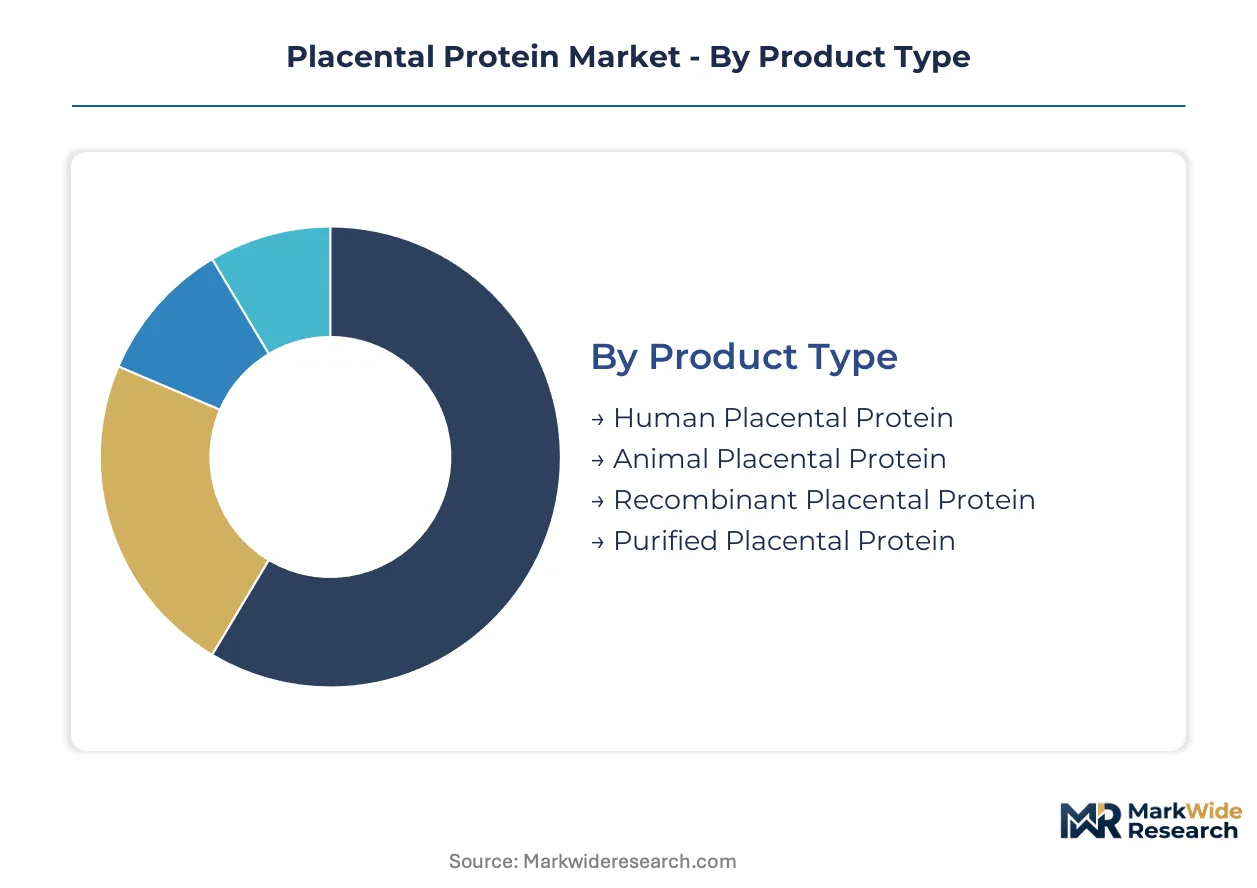
Segmentation in placental protein markets reveals divergent sourcing requirements across therapeutic and research channels. FDA and EMA regulatory frameworks apply differential stringency by product type, while end-user procurement patterns separate GMP-certified supply from research-grade catalog purchasing.
Product Type:
Domestic production dominates human-derived sourcing through hospital collection networks, while recombinant supply chains extend across international bioproduction hubs in Switzerland, Singapore, and Germany.
- Human Placental Protein:Native bioactive peptides and growth factors extracted through cold-chain homogenization retain superior cytokine activity for stem cell expansion. Demand concentrates in Boston and San Diego regenerative medicine clusters where GMP-grade material commands qualification premiums under FDA regenerative medicine advanced therapy pathways.
- Recombinant Placental Protein:Animal-free expression systems in CHO and HEK293 cells deliver batch-to-batch consistency with simplified viral clearance validation. Pharmaceutical manufacturers in Germany and Switzerland are accelerating substitution for native extracts as EMA adventitious agent controls tighten.
- Animal Placental Protein:Porcine and ovine extracts serve veterinary therapeutics and cost-sensitive research applications with reduced regulatory documentation.
- Purified Placental Protein:Chromatographically fractionated cytokine concentrates target diagnostic assay developers requiring defined protein specifications.
Human placental protein holds the largest share; momentum sits with recombinant alternatives.
End User:
Procurement scale separates enterprise pharmaceutical buyers from fragmented research laboratory purchasing, with biotechnology firms occupying the fastest-expanding middle tier.
- Pharmaceutical Companies:Integrated drug developers source GMP-grade human placental protein for cell therapy manufacturing under FDA biologics license applications. Viral invalidation protocols and donor traceability documentation consume substantial qualification resources.
- Biotechnology Firms:Emerging cell therapy developers lack internal viral clearance capacity and rely on contract testing organizations for regulatory submission support.
- Research Institutes:Academic laboratories prioritize catalog breadth and same-day fulfillment over certification grade, consolidating purchasing around distributors with cold-chain logistics.
- Hospitals:Tissue procurement networks in the United States supply raw placental material to processors under hospital-based collection protocols.
Pharmaceutical companies anchor volume procurement; biotechnology firms are climbing the fastest.
Application:
Therapeutic applications demand the most stringent quality systems, while Asian consumer markets are expanding fastest in less regulated channels.
- Therapeutics:Wound healing formulations and cell culture supplementation require ISO 13485 certification and redundant pathogen screening. FDA and EMA guidance on human-derived biological materials elevates compliance costs for commercial supply.
- Cosmetic Products:Placental-derived collagen peptides carry premium positioning in Japan and South Korea consumer channels with reduced regulatory burden compared to therapeutic-grade material.
- Diagnostics:Immunoassay developers source defined protein fractions for calibrator and control manufacturing with emphasis on lot-to-lot consistency.
- Nutraceuticals:Dietary supplement applications in Asian markets leverage traditional medicine positioning with functional claims around skin and joint health.
Therapeutics commands the dominant value pool; cosmetic products are expanding most quickly.
Form:
Cold-chain requirements separate liquid formulations from ambient-stable alternatives, with lyophilized products bridging storage flexibility and activity preservation.
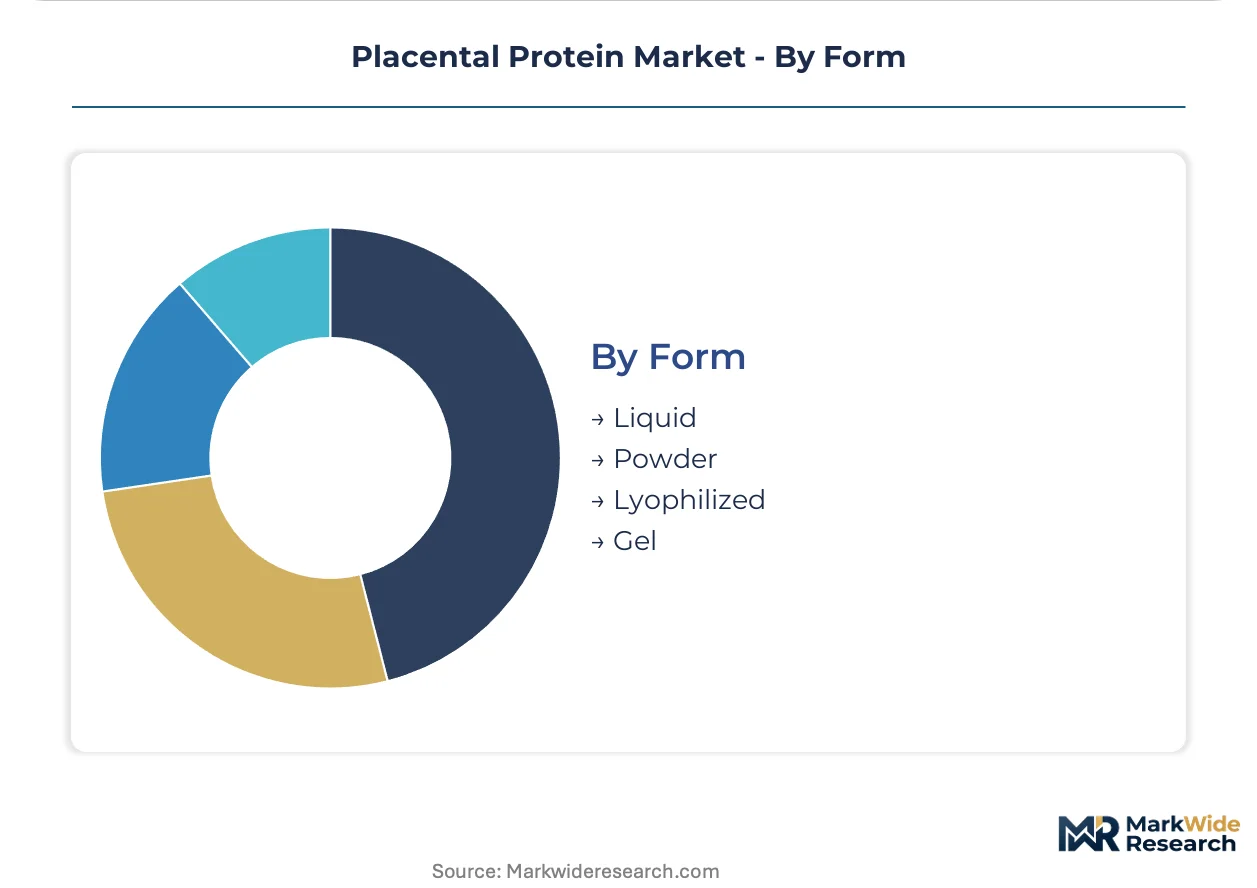
- Liquid:Ready-to-use solutions for cell culture media require continuous cold-chain logistics from manufacture through point-of-use, elevating working capital requirements for distributors.
- Lyophilized:Freeze-dried powders enable ambient shipping with reconstitution at point of use, preferred by international research customers in Australia and Canada.
- Powder:Spray-dried preparations serve nutritional and cosmetic compounding with extended shelf stability.
- Gel:Topical wound healing formulations incorporate extracellular matrix proteins in hydrogel carriers for controlled release.
Liquid formulations hold the largest share; lyophilized products are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Japanese and South Korean processors commanding premium multiples in cosmetic-grade collagen peptides, while United States suppliers absorb elevated compliance costs under FDA biologics guidance without equivalent price recovery.
United States
Boston and San Diego regenerative medicine clusters drive GMP-grade human placental protein procurement for stem cell expansion protocols. FDA regenerative medicine advanced therapy designations expedite cell therapy development timelines and accelerate demand for qualified raw material suppliers. Hospital-based tissue collection networks in Massachusetts and California supply raw placental material to processors under stringent donor eligibility criteria.
Japan
Consumer demand for placental-derived collagen peptides in nutraceutical and cosmetic channels anchors premium positioning. PMDA oversight of human-derived biological materials maintains stringent donor screening and viral inactivation standards. Tokyo-Osaka industrial corridors concentrate processing capacity for export-grade peptide fractions.
Germany
Pharmaceutical manufacturers accelerate recombinant placental protein adoption as EMA adventitious agent controls tighten. Heidelberg and Munich bioproduction hubs leverage CHO and HEK293 expression platforms for batch-to-batch consistency. ISO 13485 certification requirements for therapeutic-grade material elevate compliance costs for native extract processors.
South Korea
Functional beauty markets expand fastest for placental-derived ingredients with traditional medicine positioning around skin and joint health claims. MFDS regulates cosmetic and nutraceutical applications with differential stringency versus therapeutic channels. Seoul metropolitan area concentrates formulation and packaging operations for Asian consumer export.
Switzerland
Basel and Zurich pharmaceutical clusters source recombinant placental protein for cell culture supplementation in biologics manufacturing. Swissmedic guidance on human-derived materials aligns with EMA directives while permitting earlier-stage therapeutic development. Contract manufacturing partnerships proliferate as smaller processors lack in-house viral clearance validation capacity.
Placental Protein Market Vendor Landscape
Concentration sits with vertically integrated biotech firms and specialized contract manufacturers occupying distinct supply tiers. The vendor base separates into three strategic archetypes: recombinant expression platform operators, native tissue processors with proprietary collection networks, and catalog distributors competing on fulfillment velocity. Dominant competitive moves include ISO 13485 certification investments for therapeutic-grade positioning and chromatographic purification capacity expansion to reduce viral clearance burden.
Within the recombinant platform tier, Takara Bio Inc. and Japan Bio Products Co., Ltd. exemplify geography-anchored specialization in biosynthetic supply chains. MIMEDX Group, Inc. occupies a position representing native tissue processors with hospital-based collection infrastructure. Lee BioSolutions exemplifies catalog distributors competing on same-day fulfillment for diagnostic assay developers.
| Leading Market Players |
|---|
| Takara Bio Inc. |
| Lee BioSolutions |
| Japan Bio Products Co., Ltd. |
| Cargill |
| Vital Proteins |
| Gelita AG |
| Scripps Laboratories |
| Amgen |
| MIMEDX Group, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between GMP-grade human placental protein processors and Boston cell therapy manufacturers lock in supply access and price visibility across multi-year procurement cycles. These contracts insulate qualified suppliers from spot-market volatility while embedding viral clearance validation costs into negotiated unit economics.
Pricing Analysis
The customization-premium spread separates configured-to-order GMP-grade human placental protein from standard research-grade catalog items. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and donor traceability documentation depth. Pricing pressure stems from recombinant displacement in pharmaceutical manufacturing as EMA adventitious agent controls tighten. Biotechnology firms exhibit highest price sensitivity due to constrained capital reserves, while integrated pharmaceutical buyers absorb premiums for qualified supply security.
Supply Chain Analysis
Inbound logistics costs for cold-chain placental tissue collection elevate working capital requirements for processors dependent on hospital-based donor networks in Massachusetts and California. Supply concentrates in the United States, Japan, and Germany, with raw material dependencies on qualified donor recruitment, chromatographic purification resins, and sterile filtration membranes. Single-source vulnerability runs through contracted tissue collection agreements with limited redundant hospital networks. Distribution runs through specialized biologics distributors with temperature-controlled logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where recombinant expression interoperability is fragmenting procurement relationships and enabling new supplier archetypes to capture value from traditional extract processors.
For Market Incumbents: Secure proprietary donor recruitment networks in Boston and San Diego regenerative medicine clusters to defend against recombinant displacement pressure. Invest in redundant viral clearance validation capacity to maintain GMP-grade positioning as FDA guidance tightens. For New Entrants and Emerging Players: Differentiate on animal-free recombinant platforms for pharmaceutical manufacturers facing EMA adventitious agent mandates. Target Asian nutraceutical channels in Japan and South Korea where cosmetic-grade collagen peptides carry reduced regulatory burden and premium positioning. For Investors and Strategic Acquirers: Contract testing organizations with validated viral clearance capabilities represent the most attractive acquisition archetype as outsourcing demand accelerates under tightened FDA guidance. Monitor FDA regenerative medicine advanced therapy designation velocity as the signal to watch for raw material demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Therapeutic-grade positioning unlocks GMP procurement channels with Boston cell therapy developers. |
| Recombinant Platform Scale-Up | Animal-free CHO expression systems capture pharmaceutical manufacturing demand as EMA controls tighten. |
| Asian Distribution Partnership | Japan and South Korea cosmetic channel access leverages premium collagen peptide positioning. |
| Viral Clearance Outsourcing Agreement | Contract testing relationships enable smaller processors to meet FDA submission requirements. |
| Cold-Chain Logistics Expansion | Temperature-controlled infrastructure preserves cytokine activity for cell culture applications. |
Methodological Framework
A standing panel of cell therapy manufacturing executives, regulatory affairs leads at placental protein processors, hospital tissue procurement coordinators, and diagnostic assay developers provided ongoing calibration across the study period. Primary interview findings were cross-validated against FDA biologics guidance documents, EMA human tissue directives, ISO 13485 certification databases, and hospital procurement records. Bottom-up segment sizing was reconciled with top-down industry expenditure estimates to ensure analytical consistency.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for placental-derived biological materials and SEC filings from publicly traded regenerative medicine firms. The analytical framework modeled product type, end user, application, and form dimensions across the projection horizon. CAGRs were derived from trend extrapolation of procurement patterns and regulatory trajectory analysis, with specific inputs from cell therapy clinical trial advancement rates and chromatographic purification technology diffusion curves.
The analysis sits within stated boundaries; outcomes outside sustained FDA regenerative medicine advanced therapy designation velocity or recombinant platform substitution rates would require recalibration. Forecasts reflect documented assumptions regarding donor eligibility criteria stability and cold-chain infrastructure investment continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Analgesics Market
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
Oral Thin Film Drugs Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Schizophrenia Drugs Market