
 Alginate Dressing Market | 2026-2036
Alginate Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Alginate Dressing Market Intelligence
EU Green Deal carbon-neutrality targets for healthcare supply chains is decoupling procurement from conventional sourcing patterns. ConvaTec leverages vertically integrated seaweed harvesting operations to secure raw material traceability. Smith & Nephew anchors its position through specialized R&D centers focused on antimicrobial alginate formulations.
Alginate dressing comprises biodegradable fibers derived from brown seaweed, primarily composed of calcium or sodium salts of alginic acid, forming hydrophilic gels upon contact with exudate to maintain moist wound environments conducive to granulation tissue formation. Calcium alginate dominates hospital procurement due to established hemostatic properties and superior gel strength during fluid absorption. Chronic wounds application represents the fastest-expanding segment as diabetic foot ulcer incidence rises among aging demographics across developed healthcare systems.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) CE marking framework govern product safety and clinical performance claims, directly influencing market access timelines and reimbursement eligibility. The WHO Essential Medicines List inclusion criteria for wound care products shape procurement guidelines in emerging healthcare systems. Stakeholders must monitor evolving biodegradable material standards and exudate-management performance benchmarks as regulators tighten environmental impact assessments for single-use medical devices.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously elevating performance benchmarks for exudate management and antimicrobial efficacy. This buyer-side concentration forces manufacturers to restructure R&D priorities around demonstrable clinical outcomes rather than commodity positioning.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:Expedited premarket notification reviews for alginate dressings with predicate device claims accelerate commercialization timelines for manufacturers targeting US hospital systems.
- Chronic Wound Prevalence:Diabetic foot ulcer incidence among aging populations in Germany, Japan, and the United States expands the addressable patient pool requiring advanced moisture-retentive dressings.
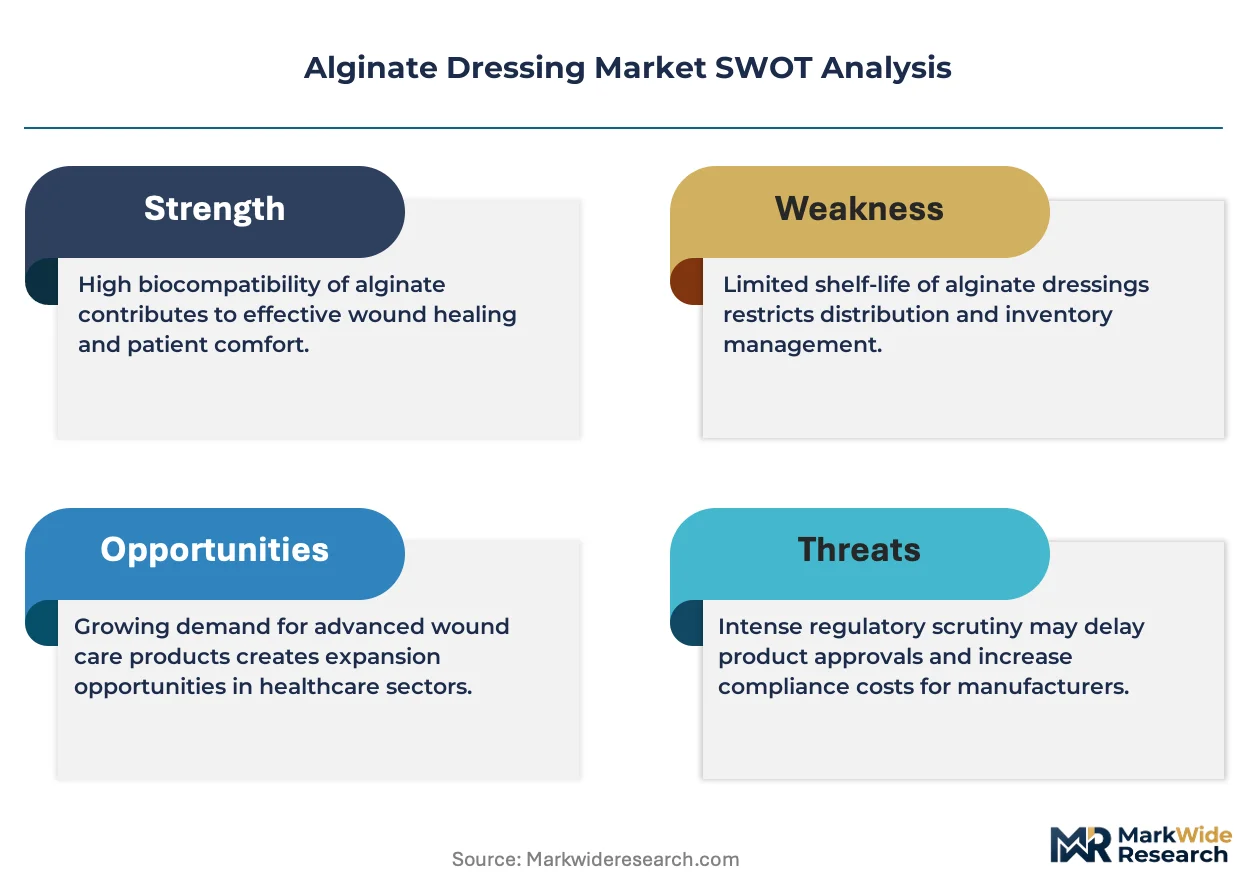
- Brown Seaweed Bioavailability:Sustainable harvesting operations along Atlantic and Pacific coastlines secure raw material traceability demanded by EU Green Deal procurement mandates.
Market Restraints
- Seaweed Supply Concentration:Dependence on coastal harvesting regions in Norway, Chile, and China exposes manufacturers to climate-related yield volatility and geopolitical export restrictions.
- Silver Sulfadiazine Substitution:Established antimicrobial burn dressings retain preference in emergency departments despite alginate superiority in exudate absorption.
- EU MDR Compliance Burden:Enhanced clinical evidence requirements for CE marking under the Medical Device Regulation extend certification timelines and elevate documentation costs for market entrants.
Strategic Opportunities
- Veterinary Wound Care:Companion animal surgery and equine trauma applications remain substantially underpenetrated relative to human healthcare spending on advanced dressings.
- Home Healthcare Transition:Post-acute care discharge protocols in the United States and Germany create demand for patient-applied alginate systems with simplified application mechanisms.
- Antimicrobial Ion Convergence:Integration of zinc, copper, or PHMB into alginate matrices addresses multidrug-resistant organism concerns without silver-associated cytotoxicity.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 14-18 month completion cycles, delaying product iterations for competitive positioning.
- Legacy EHR Integration:Wound documentation systems in US hospital networks lack standardized alginate-specific outcome metrics, complicating value-based reimbursement demonstrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alginate Dressing Market |
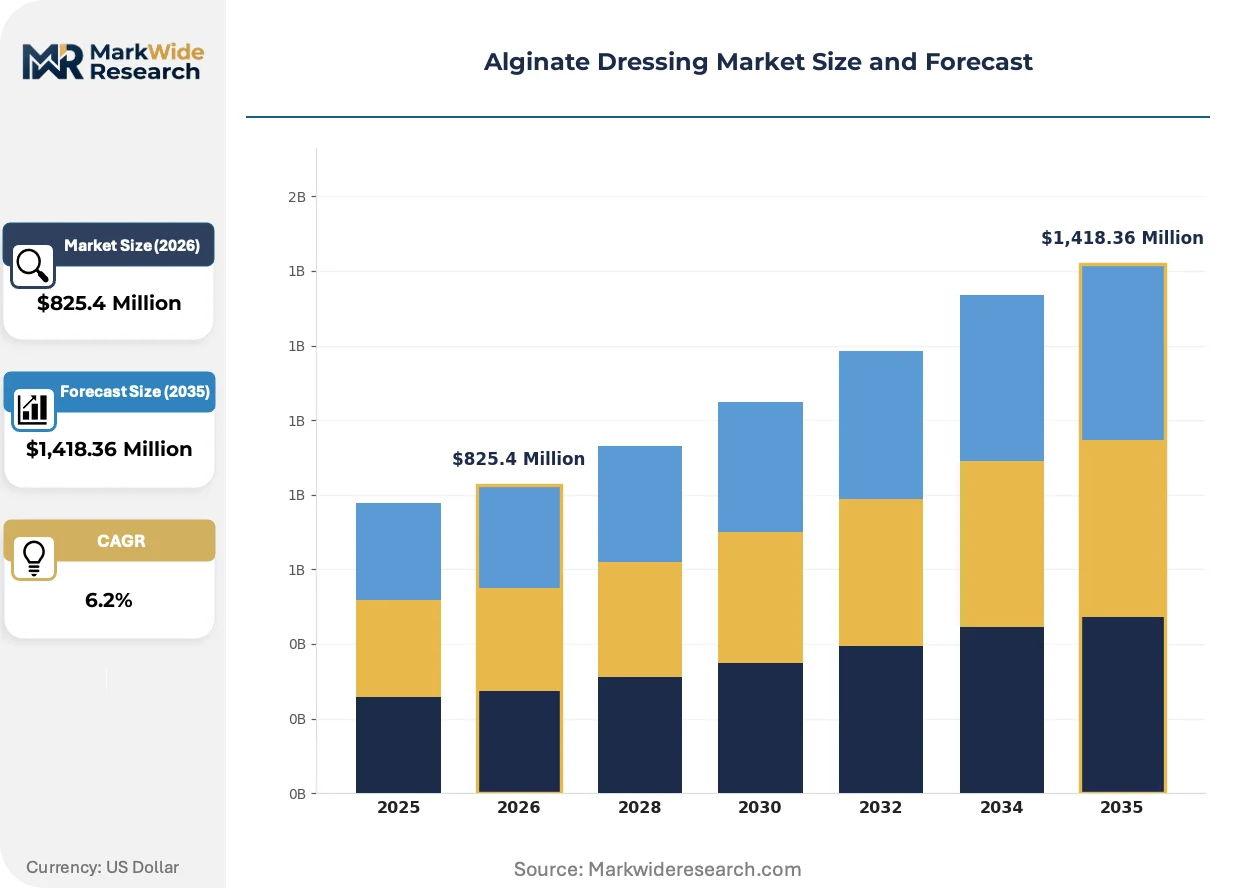
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,418.36 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Alginate, Sodium Alginate, Alginate Gel, Alginate Foam End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Application: Surgical Wounds, Chronic Wounds, Burn Care, Ulcer Treatment Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | ConvaTec, Molnlycke Health Care, 3M, B. Braun, Hartmann Group, Smith & Nephew, Coloplast, Medline Industries, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alginate Dressing Market Strategic Shifts & Innovations
Material science advances are dissolving the boundary between passive moisture management and active therapeutic intervention. Manufacturers now engineer alginate matrices as programmable delivery vehicles rather than absorptive substrates alone.
Electrospun nanofiber alginate scaffolds are converging with 3D bioprinting workflows for patient-specific wound bed preparation. Academic medical centers in South Korea and Switzerland pilot these systems for complex diabetic foot reconstruction. The structural compression of conventional foam dressing applications is accelerating as hospitals consolidate supplier contracts around multi-functional platforms.
REACH restrictions on persistent organic pollutants are forcing reformulation of alginate dressing adjuvants and packaging materials. Manufacturers serving EU member states now substitute bio-based plasticizers for phthalate-containing alternatives. Calcium alginate variants with modified gelation kinetics represent the product category most affected, with reformulation timelines extending 24-36 months for full compliance.
Hospital value analysis committees now mandate total cost-of-care documentation rather than unit price comparison for dressing selection. Group purchasing organizations in the United States consolidate vendor panels around suppliers demonstrating reduced dressing change frequency and nursing labor allocation. This behavioral pivot is most visible in integrated delivery networks across Texas, California, and Florida, where standardized formularies displace individual physician preference.
Alginate Dressing Market Segmentation
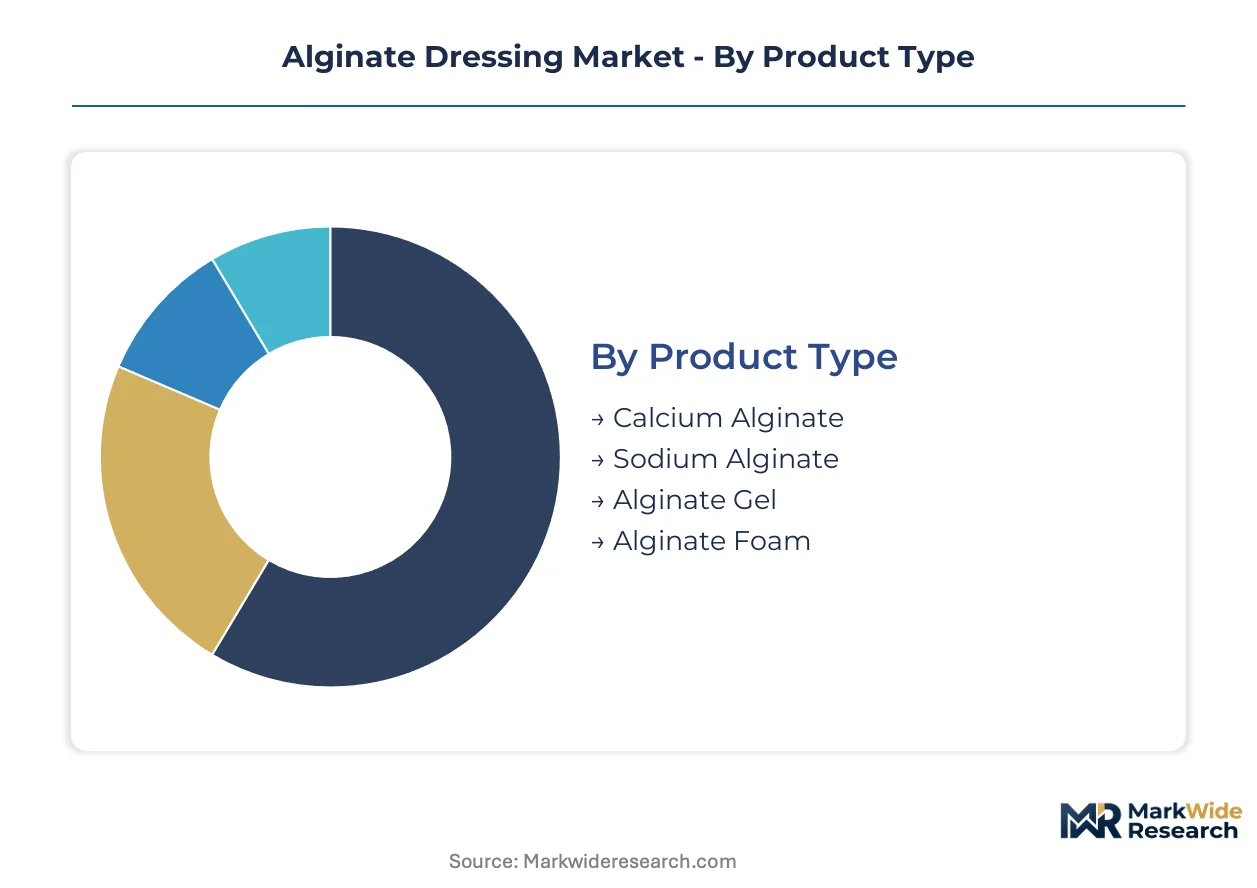
Alginate dressing procurement patterns diverge sharply across clinical settings and wound etiologies. Hospital formulary committees evaluate segments through distinct performance lenses: hemostatic efficacy for surgical suites, exudate capacity for chronic wound clinics, and ease of application for post-acute transitions.
Product Type:
Upgrade cycles in alginate dressing portfolios track gelation kinetics and structural integrity under fluid load. Facilities replace legacy formulations when modified calcium-sodium ratios demonstrate superior wound bed conformity.
- Calcium Alginate:Ionic crosslinking with calcium ions produces rigid gel structures upon sodium exchange with wound exudate. Hospital surgical departments in the United States and Germany specify this variant for operative sites requiring immediate hemostasis and controlled absorption. Procurement specifications prioritize gel strength retention during dressing removal to prevent trauma to granulating tissue.
- Sodium Alginate:Pre-gelled sodium salts offer immediate hydrophilic response without the ionic activation delay of calcium variants. Wound care clinics managing highly exuding venous leg ulcers in Japan favor sodium alginate for rapid fluid lock and reduced maceration risk. Reformulation toward hybrid calcium-sodium matrices is accelerating as manufacturers balance gel stability against absorption speed.
- Alginate Gel:Amorphous formulations enable cavity packing and tunneled wound management where sheet conformability limits efficacy.
- Alginate Foam:Composite structures integrating alginate fibers with polyurethane foam substrates address shear stress protection in pressure injury protocols.
Volume placements concentrate in Calcium Alginate; the faster expansion belongs to Alginate Foam.
End User:
Cost tier stratification separates capital-intensive hospital procurement from price-sensitive homecare channels. Reimbursement coding density and nursing labor economics determine segment profitability.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements bundling alginate dressings with negative pressure wound therapy systems. Value analysis committees in Texas and Florida health systems mandate clinical outcome documentation linking dressing selection to reduced length-of-stay metrics. FDA 510(k) predicate device portfolios weigh heavily in vendor qualification.
- Clinics:Outpatient wound centers operate on episode-based reimbursement where dressing change frequency directly impacts margin. Specialized clinics in Germany manage diabetic foot ulcer populations through alginate protocols integrated with arterial revascularization workflows.
- Homecare:Patient-applied systems with color-change indicators or bordered constructions reduce skilled nursing visit requirements.
- Long-term Care Facilities:Pressure injury prevention protocols drive bulk purchasing of cost-optimized alginate variants with shorter wear times.
Revenue concentration sits with Hospitals; Homecare climbs the fastest as discharge acceleration protocols expand.
Application:
Application segmentation maps directly to wound healing physiology and exudate production rates. Clinical guidelines from the WHO and national wound care societies shape product positioning within each indication.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries generate sustained exudate requiring alginate dressings with extended wear capacity. Aging demographics in Japan and the United States expand the addressable population for moisture-retentive chronic wound management. Biofilm disruption claims increasingly influence formulary inclusion as antimicrobial alginate variants gain protocol adoption.
- Surgical Wounds:Post-operative incision sites with moderate drainage utilize alginate sheets as primary or secondary dressings. Surgical departments prioritize low-adherence constructions that minimize pain and tissue disruption during dressing changes.
- Burn Care:Partial-thickness thermal injuries require alginate dressings with conformability to irregular body surfaces and cooling properties during initial fluid resuscitation phases.
- Ulcer Treatment:Arterial and neuropathic ulcer protocols specify alginate variants with modified absorption profiles matched to perfusion-limited exudate production.
Procedure volumes favor Surgical Wounds; Chronic Wounds gains share fastest on diabetic population expansion.
Distribution Channel:
Channel structure reflects procurement centralization versus clinical immediacy requirements. Group purchasing organization consolidation reshapes vendor access patterns.
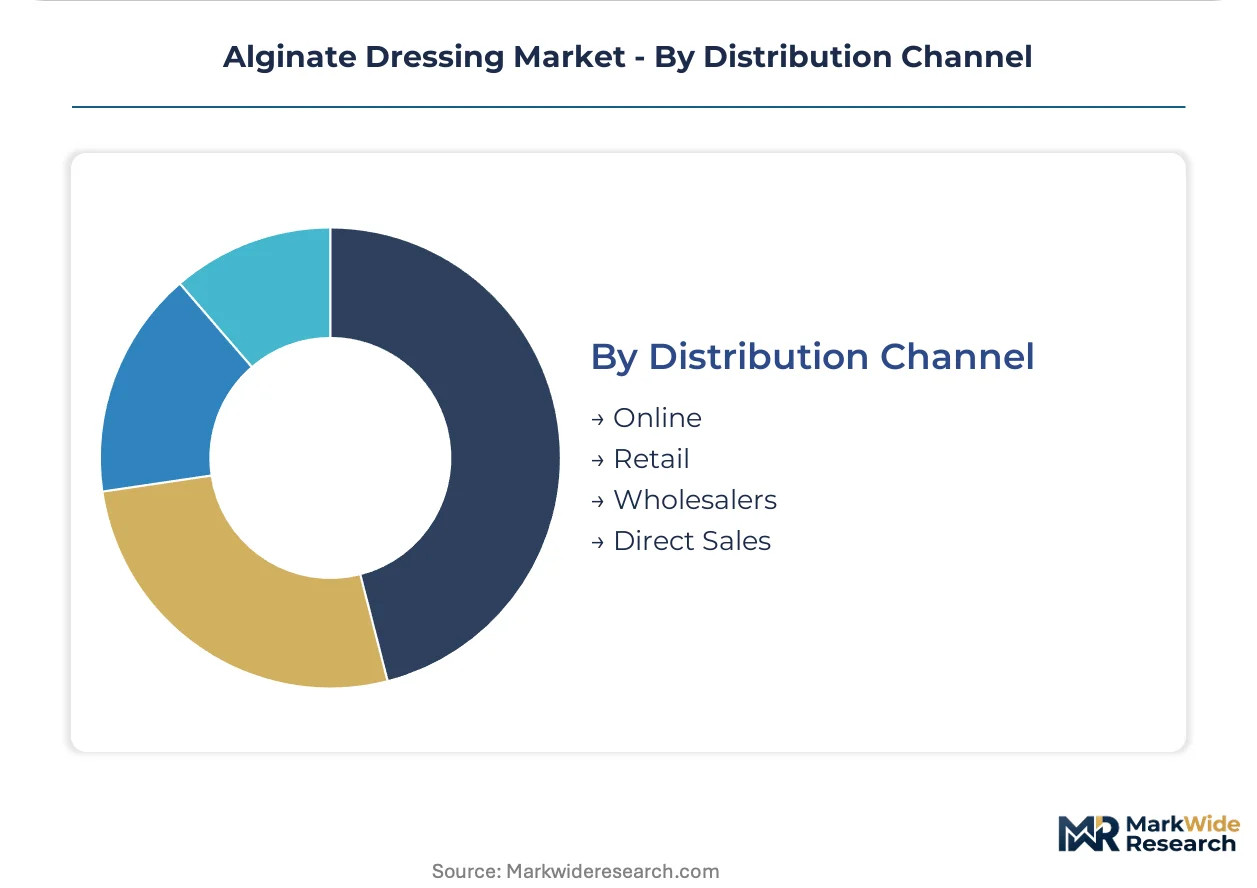
- Wholesalers:Cardinal Health and McKesson distribution networks dominate hospital system fulfillment with just-in-time inventory management and consignment stocking arrangements.
- Direct Sales:Manufacturer field representatives secure sole-source contracts through clinical education programs and outcome guarantee structures.
- Online:E-commerce platforms serve homecare patients and small clinic practices with transparent pricing and automated replenishment.
- Retail:Pharmacy chains stock limited alginate SKUs for cash-pay wound care consumers.
Wholesalers capture the highest volume throughput; Direct Sales expands most quickly on integrated delivery network consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American alginate dressing commercialization through clustered wound care research institutes and FDA premarket notification processing centers.
United States
Integrated delivery networks in Texas and Florida drive hospital formulary consolidation around alginate protocols with outcome documentation requirements. FDA 510(k) clearance pathways govern market access timelines for moisture-retentive dressing commercialization. The Minneapolis medical device corridor hosts manufacturing operations serving domestic hospital procurement.
Germany
Outpatient wound centers in Bavaria manage diabetic foot ulcer populations through alginate protocols integrated with arterial revascularization workflows. EU Medical Device Regulation CE marking mandates shape certification documentation burdens for market entrants. The North Rhine-Westphalia healthcare logistics hub distributes alginate products across Central European hospital systems.
Japan
Wound care clinics in Tokyo and Osaka specify sodium alginate variants for rapid fluid lock in venous leg ulcer management. PMDA medical device registration requirements align with international standards while maintaining distinct clinical evidence thresholds. The Kansai region concentrates alginate dressing distribution infrastructure serving aging demographic demand.
United Kingdom
NHS procurement frameworks prioritize alginate dressings with demonstrated reduction in dressing change frequency and nursing labor allocation. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while developing UKCA conformity assessment pathways. The Cambridge medical technology cluster advances antimicrobial alginate formulation research.
South Korea
Academic medical centers in Seoul pilot electrospun nanofiber alginate scaffolds converged with 3D bioprinting workflows for diabetic foot reconstruction. MFDS medical device approval processes accelerate for predicate device claims with established safety profiles. The Songdo biomedical district hosts advanced wound care technology development facilities.
Alginate Dressing Market Key Industry Players
Premium-margin players sit above commodity-margin players across clinical outcome documentation and antimicrobial formulation sophistication. Hospital value analysis committees now consolidate vendor panels around suppliers demonstrating reduced length-of-stay metrics rather than unit price comparison. Three archetypes dominate: vertically integrated seaweed harvesters with captive raw material security, specialized wound care divisions of diversified medical device conglomerates, and private-label manufacturers serving group purchasing organization contracts. M&A activity concentrates on antimicrobial technology licensing and direct sales force expansion into integrated delivery networks.
Within the integrated harvesting tier, ConvaTec anchors raw material traceability demanded by EU Green Deal procurement mandates. Smith & Nephew exemplifies the R&D-specialized archetype through dedicated formulation centers. 3M occupies a position bridging industrial scale with clinical education infrastructure.
| Leading Market Players |
|---|
| ConvaTec |
| Molnlycke Health Care |
| 3M |
| B. Braun |
| Hartmann Group |
| Smith & Nephew |
| Coloplast |
| Medline Industries |
| Cardinal Health |
| Others |
Cost & Logistics Intelligence
Performance-grade divergence between antimicrobial-enhanced alginate formulations and commodity calcium-sodium variants manifests in both procurement premiums and raw material sourcing configurations. Hospital value analysis committees in Texas and Florida award sole-source contracts to suppliers demonstrating reduced dressing change frequency, while EU Green Deal traceability mandates force backward integration into captive seaweed harvesting operations.
Pricing Analysis
Value-based pricing anchors to documented reductions in nursing labor allocation and length-of-stay metrics rather than unit cost. Three-tier pricing structure across premium antimicrobial, standard calcium alginate, and economy unbranded levels separates vendors by clinical outcome documentation depth. Cost compression in standard-tier hospital procurement intensifies as group purchasing organizations consolidate vendor panels around integrated delivery networks. Long-term care facilities exhibit highest price sensitivity; surgical departments within academic medical centers show least sensitivity due to outcome-guarantee contracting.
Supply Chain Analysis
EU Medical Device Regulation local-content requirements and FDA 510(k) manufacturing site inspections are reshaping sourcing toward qualified facilities in the United States, Germany, and Japan. Brown seaweed biomass draws from Atlantic coastal harvesting in Norway and Chile, with Pacific sourcing from China. Single-source vulnerability concentrates in Norwegian kelp beds exposed to climate-related yield volatility. Distribution runs through Cardinal Health and McKesson just-in-time networks serving hospital system consignment arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seaweed supply concentration in coastal harvesting regions props pricing power for vertically integrated manufacturers controlling raw material security. Brown seaweed yield volatility represents the binding capacity constraint sustaining margin premiums across the analysis window.
For Market Incumbents: Extend antimicrobial formulation R&D pipelines to address multidrug-resistant organism concerns without silver-associated cytotoxicity. Secure captive harvesting operations along Atlantic and Pacific coastlines to satisfy EU Green Deal traceability mandates. Lock in multi-year supply agreements with integrated delivery networks in Texas and Florida through outcome-guarantee structures that preempt commodity substitution. For New Entrants and Emerging Players: Begin with veterinary wound care applications for companion animal surgery and equine trauma, segments remaining substantially underpenetrated relative to human healthcare spending. Target homecare channels with patient-applied alginate systems featuring color-change indicators and bordered constructions that reduce skilled nursing visit requirements. Pursue direct-to-clinic distribution bypassing wholesaler markups through specialized wound care education programs. For Investors and Strategic Acquirers: Re-rating potential sits with antimicrobial technology licensing platforms given FDA 510(k) pathway streamlining for predicate device claims. Five-to-ten year viability favors targets with established hospital formulary inclusion and backward integration into sustainable seaweed harvesting. Monitor FDA premarket notification clearance timelines as the inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Formulation Development | Integration of zinc, copper, or PHMB addresses multidrug-resistant organism concerns in hospital surgical departments. |
| Backward Integration into Seaweed Harvesting | Captive Atlantic and Pacific coastal operations secure raw material traceability demanded by EU Green Deal procurement mandates. |
| Hospital System Partnership | Sole-source contracts with Texas and Florida integrated delivery networks lock in multi-year revenue through outcome guarantees. |
| CE Marking Pathway Investment | Enhanced clinical evidence documentation accelerates EU Medical Device Regulation certification timelines for market access. |
| Homecare Product Line Extension | Patient-applied systems with simplified application mechanisms capture discharge acceleration protocol demand in Germany and the United States. |
Research Approach
Independent corroboration across hospital procurement databases, FDA 510(k) premarket notification filings, and GPO contract records underwrites the qualitative findings. Primary interviews with wound care clinicians, hospital value analysis committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from EMA submissions, customs trade data, and hospital supply chain disclosures. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Rate-of-change decomposition across product type, end user, application, and distribution channel dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth trajectories weighted by procurement volume concentration in hospital systems versus homecare channels. Forecast inputs incorporated diabetic foot ulcer incidence projections, EU MDR compliance timeline assumptions, and seaweed biomass yield volatility scenarios.
Underlying measurement precision varies by segment; hospital procurement data carries tighter precision than homecare patient-applied system estimates. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement coding density. Seaweed supply disruption, FDA review backlog expansion, or silver sulfadiazine substitution acceleration in emergency departments could revise trajectory expectations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Europe Advanced Wound Care Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Advanced Wound Care Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Global Compression Bandages Market
Wound Care
Belgium and Netherlands Advanced Wound Care Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Wound Closure Strips Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Wound Measurement Devices Market
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Global Surgical Drains/Wound Drainage Market
Wound Care
Advanced Wound Management Market