
 Dermal Allograft Market | 2026-2036
Dermal Allograft Market Size, Share, and Industry Trends Forecast 2026-2036
Dermal Allograft Market Outlook
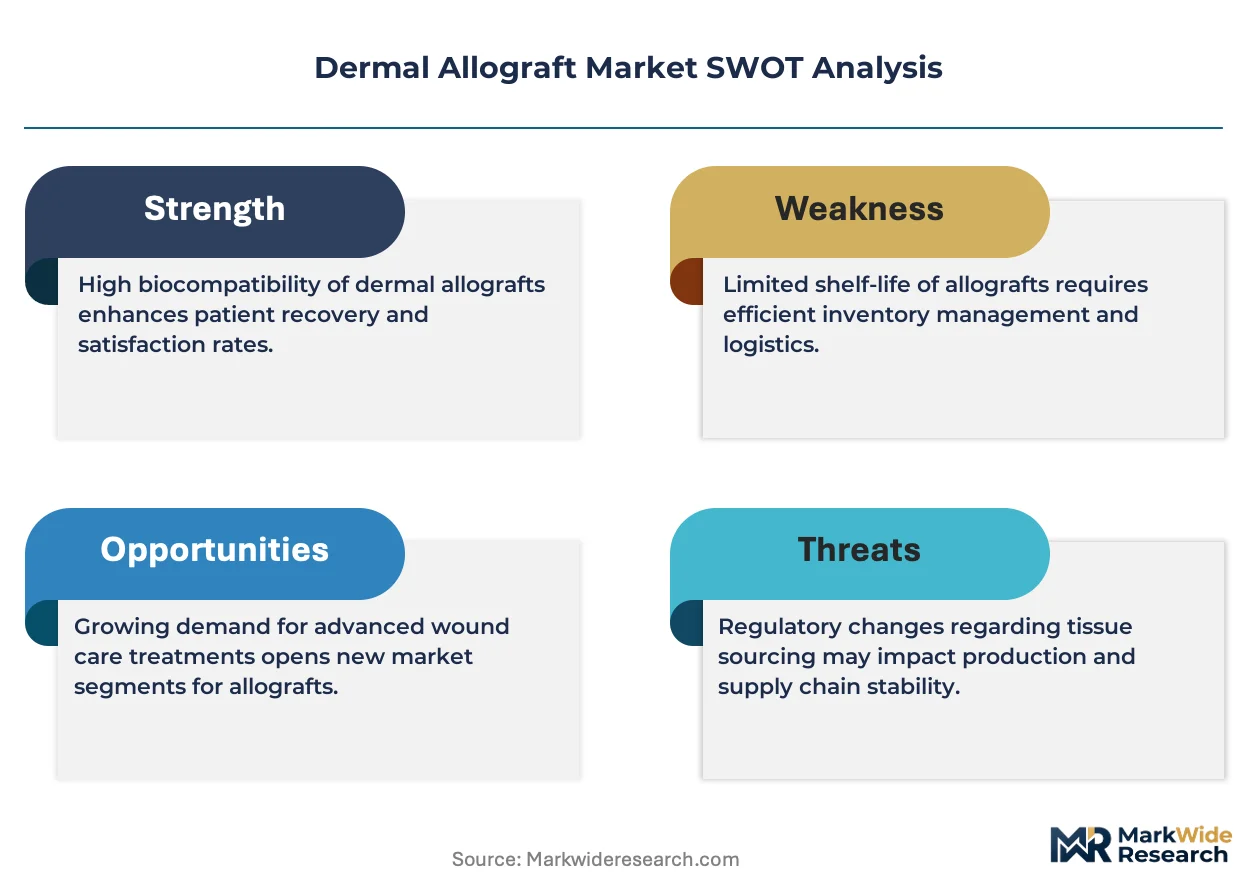
Decellularization protocols with preserved extracellular matrix architecture are reshaping manufacturing standards for advanced wound care products. Organogenesis leverages proprietary perfusion technology to sustain competitive differentiation in cellular dermal matrices. MiMedx Group anchors its position through placental-derived biologics, while RTI Surgical competes on sterilization innovation for non-processed tissue preservation.
Dermal allograft comprises human donor skin processed to remove cellular components while retaining collagen, elastin, and glycosaminoglycan scaffolding for wound bed integration and revascularization. Acellular dermal matrix dominates hospital procurement due to established reimbursement pathways and reduced immune response risk, whereas cellular dermal matrix occupies higher-margin aesthetic procedures where viable fibroblasts accelerate healing outcomes. Burn treatment commands the largest application volume, while surgical reconstruction generates premium pricing through customized graft sizing.
The FDA enforces Current Good Tissue Practice rules alongside the American Association of Tissue Banks standards, requiring full chain-of-custody documentation that elevates compliance costs for smaller distributors. EMA's Medical Device Regulation reclassifies certain processed allografts, forcing manufacturers to navigate notified body certification timelines. Stakeholders must monitor evolving reimbursement thresholds for outpatient wound care facilities as Medicare adjusts bundled payment models.
Market Dynamics
FDA's tightened donor screening protocols and chain-of-custody mandates are elevating compliance costs and consolidating procurement toward vertically integrated manufacturers with captive tissue recovery networks.
Growth Catalysts
- Reimbursement pathway expansion:Medicare's adjusted bundled payment models for outpatient wound care facilities are accelerating hospital adoption of acellular dermal matrices for complex wound coverage.
- Specialized clinical infrastructure:University hospitals in Germany are constructing dedicated reconstructive surgery units, concentrating demand for customized graft sizing in surgical reconstruction applications.
- Processing technology maturation:Perfusion-based decellularization protocols that preserve extracellular matrix architecture are standardizing manufacturing quality for advanced wound care products.
Market Restraints
- Input supply volatility:Donor tissue availability fluctuates with demographic shifts and public health events, constraining production planning for non-processed tissue preservation methods.
- Regulatory friction:EMA's Medical Device Regulation reclassification of certain processed allografts imposes notified body certification timelines that delay product launches by 18-24 months.
- Technical limitation:Cellular dermal matrices require cryogenic logistics infrastructure that remains underdeveloped in secondary hospital networks, limiting addressable market expansion.
Strategic Opportunities
- Underpenetrated outpatient channels:Ambulatory surgical centers in the United States lack standardized allograft procurement frameworks, creating first-mover advantages for distributors building direct relationships.
- Technology convergence:Integration of 3D bioprinting with decellularized scaffolds enables patient-specific graft geometries for burn reconstruction applications.
- Regulatory tailwind:India's PLI scheme for medical device manufacturing offers cost offsets for domestic production of placental-derived biologics serving South Asian markets.
Industry Challenges
- Specialized workforce scarcity:Tissue bank technicians with expertise in aseptic processing and quality systems command premium compensation, constraining operational scaling for mid-tier distributors.
- Certification timeline compression:Dual-track compliance with FDA Current Good Tissue Practice and AATB standards requires parallel documentation systems that extend product validation cycles.
- Supply chain reconfiguration friction:Transitioning from broker-mediated tissue sourcing to direct hospital-based recovery partnerships demands capital investment in cold-chain infrastructure and relationship management capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermal Allograft Market |
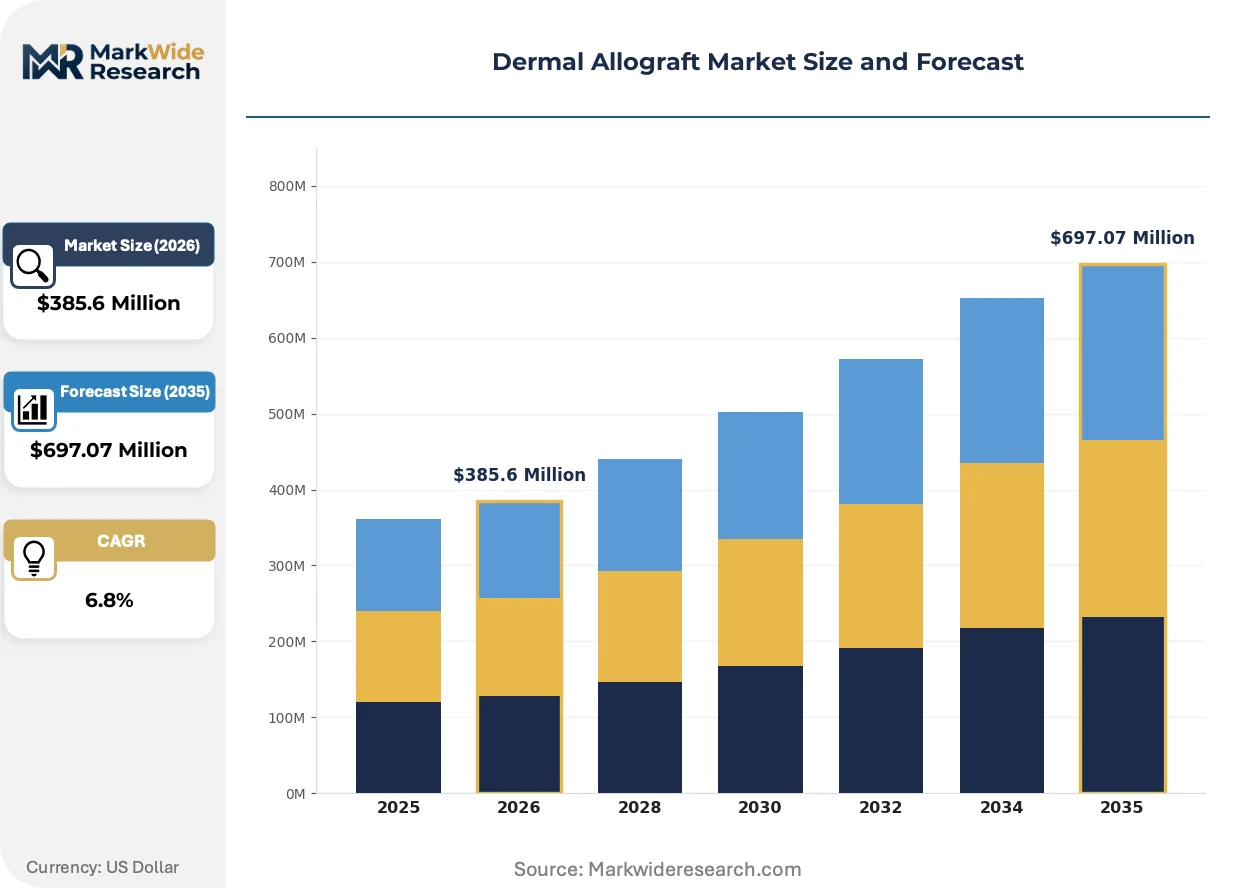
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acellular Dermal Matrix, Cellular Dermal Matrix, Non-Processed Tissue, Processed Tissue End User: Hospitals, Clinics, Cosmetic Surgery Centers, Wound Care Facilities Application: Burn Treatment, Surgical Reconstruction, Trauma Repair, Aesthetic Procedures Distribution Channel: Direct Sales, Online Sales, Distributor Channels, Medical Supply Stores |
| Companies Covered | Organogenesis, LifeNet Health, MiMedx Group, RTI Surgical, Zimmer Biomet, AlloSource, MTF Biologics, Stryker Corporation, Integra LifeSciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermal Allograft Market Strategic Shifts
Processing methodologies and procurement architectures are converging to reshape competitive differentiation, with preservation technology and regulatory positioning determining margin capture across hospital and aesthetic segments.
Lyophilization technology for ambient-stable allograft storage is migrating from niche military and disaster-response applications toward mainstream hospital inventory management. Burn treatment centers in the United States are piloting room-temperature supply chains to reduce cryogenic infrastructure dependency. This migration from cold-chain logistics is compressing distribution costs and enabling same-day graft availability for emergency reconstruction procedures.
EMA's Medical Device Regulation implementation is reclassifying processed allografts as Class III devices, forcing manufacturers to submit clinical evidence packages for notified body review. German university hospitals are delaying procurement decisions pending CE marking clarity, while Swiss manufacturers pursue dual-track FDA-CE certification to maintain cross-border supply continuity. Cellular dermal matrices face the steepest compliance burden due to viability preservation claims requiring biocompatibility studies.
Hospital purchasing cooperatives are consolidating procurement authority for dermal allografts under centralized tissue review boards, displacing individual surgeon preference-based ordering. These committees evaluate graft performance data, supplier audit results, and total cost-of-care metrics before contract awards. The concentration of buying power is most visible in United States health systems with employed physician models, where standardized graft formularies now cover 60-70% of reconstructive procedures.
Dermal Allograft Market Segmentation
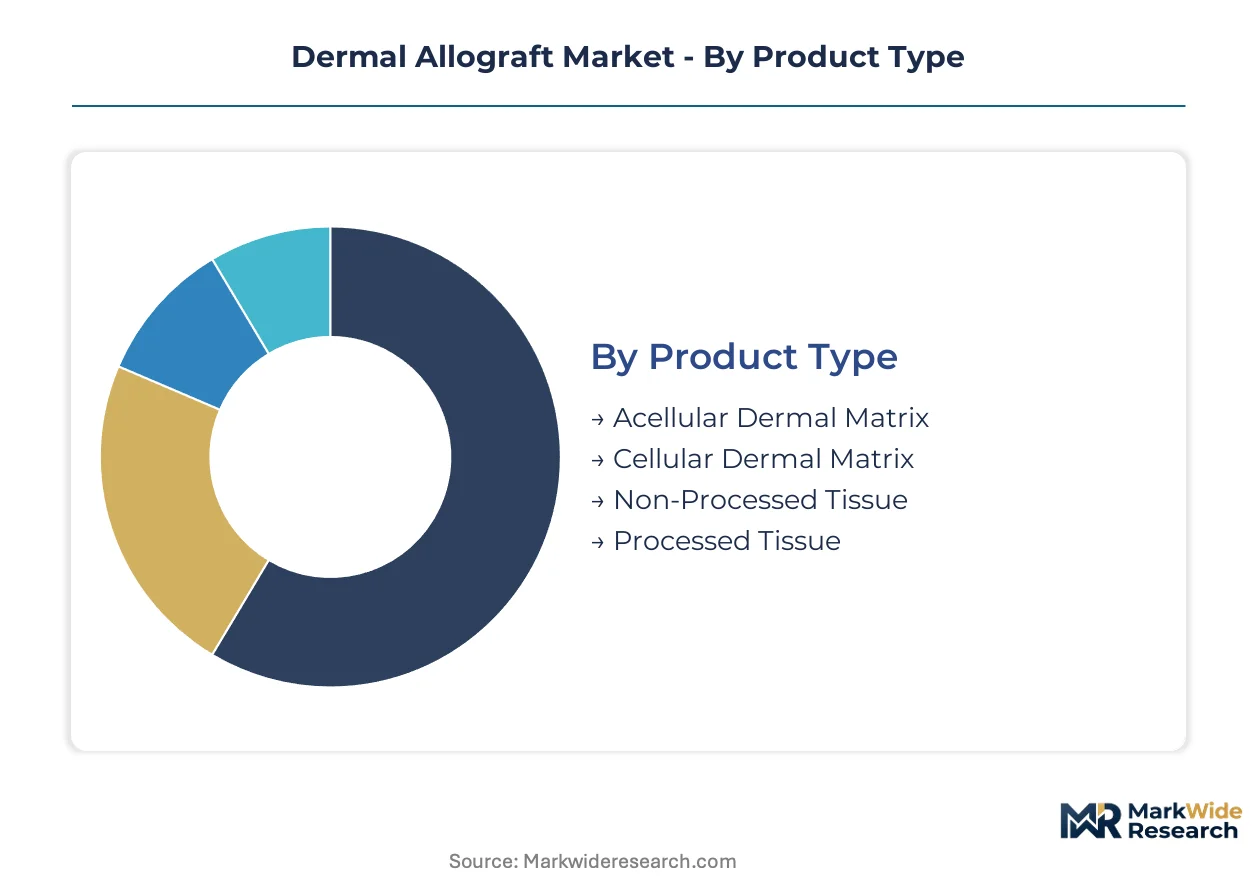
Dermal allograft procurement varies sharply by clinical setting and reimbursement pathway. Product form determines cold-chain requirements, while application type dictates margin capture and regulatory scrutiny intensity.
Product Type:
Clinical use-cases span from emergency burn coverage to elective aesthetic enhancement, with processing depth determining immune response risk and storage infrastructure needs.
- Acellular Dermal Matrix:Human donor skin stripped of cellular material retains collagen-elastin scaffolding for wound bed integration. Hospital procurement concentrates in United States burn treatment centers where Medicare bundled payments favor established reimbursement codes.
- Cellular Dermal Matrix:Viable fibroblast populations accelerate healing in aesthetic applications. German university hospitals drive demand for customized graft sizing in reconstructive surgery units, though cryogenic logistics constrain expansion into secondary networks.
- Non-Processed Tissue:Fresh allograft for immediate implantation requires rapid donor-recipient matching through captive tissue recovery networks.
- Processed Tissue:Sterilized preservation extends shelf life for ambulatory surgical center inventory management.
Established volume favors acellular dermal matrix; emerging adoption favors cellular dermal matrix.
End User:
Facility type determines procurement authority structure and graft formularies.
- Hospitals:Centralized tissue review boards in United States health systems now govern 60-70% of reconstructive procedures through standardized formularies evaluating performance data and total cost-of-care metrics.
- Clinics:Outpatient wound care facilities accelerate adoption as Medicare adjusts bundled payment models for complex wound coverage.
- Cosmetic Surgery Centers:Premium pricing tolerance supports higher-margin cellular matrices with viable fibroblast content.
- Wound Care Facilities:Specialized infrastructure targets diabetic ulcer and pressure injury management.
Procurement consolidation favors hospitals; reimbursement expansion favors wound care facilities.
Application:
Procedure urgency and customization depth segment the demand landscape.
- Burn Treatment:Volume leader commanding largest graft consumption with room-temperature lyophilization pilots reducing cryogenic dependency in United States trauma centers.
- Surgical Reconstruction:Customized sizing generates premium pricing through patient-specific graft geometries enabled by 3D bioprinting convergence.
- Trauma Repair:Emergency protocols demand same-day graft availability through streamlined distributor relationships.
- Aesthetic Procedures:Elective scheduling accommodates longer lead times for specialized cellular matrices.
Volume concentration favors burn treatment; margin capture favors surgical reconstruction.
Distribution Channel:
Channel selection reflects cold-chain capabilities and relationship depth.
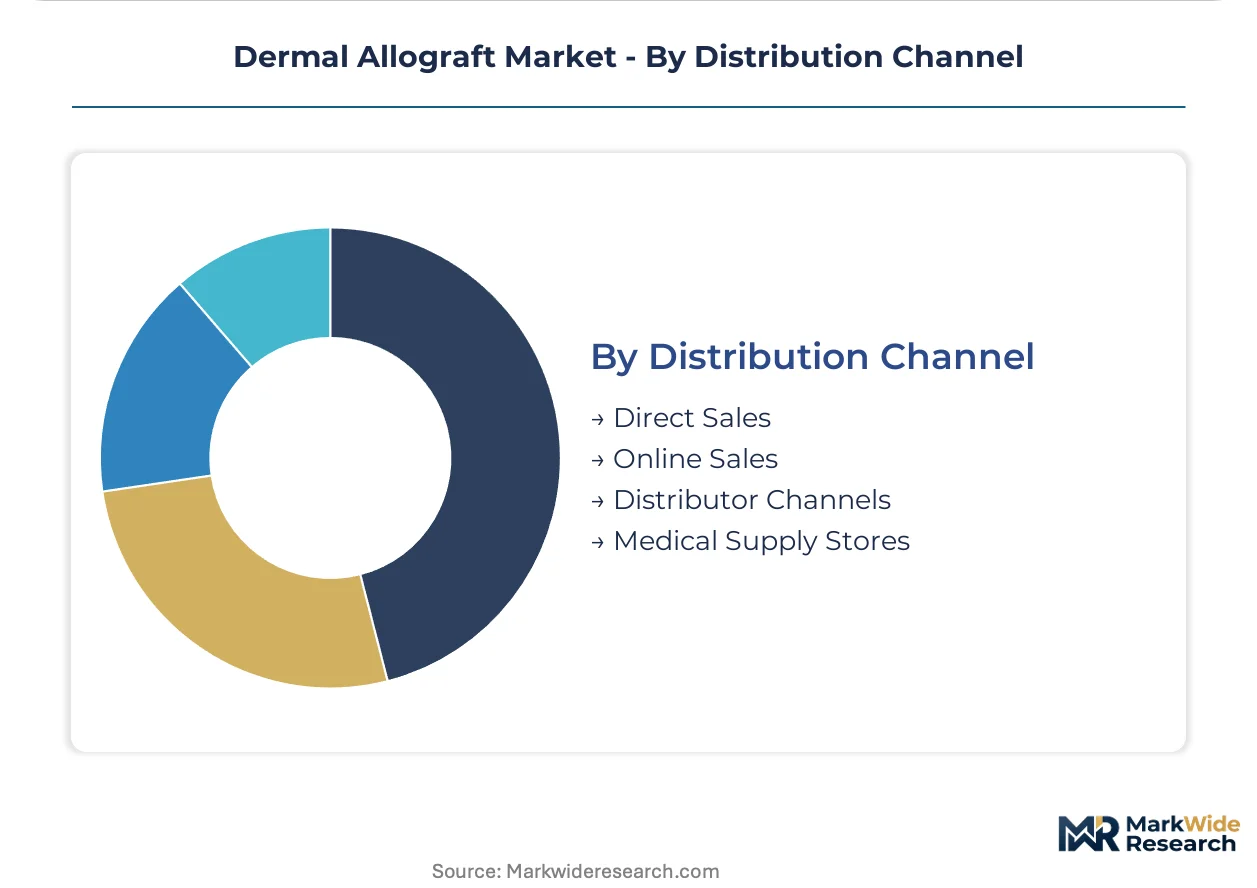
- Direct Sales:Vertically integrated manufacturers with captive tissue recovery networks bypass broker intermediaries to control chain-of-custody documentation for FDA compliance.
- Distributor Channels:Regional specialists dominate mid-tier hospital access where capital constraints limit direct cold-chain infrastructure investment.
- Online Sales:Digital procurement platforms emerge for standardized acellular products with ambient-stable lyophilization.
- Medical Supply Stores:Retail channels serve smaller clinics with limited inventory requirements.
Compliance scale favors direct sales; geographic reach favors distributor channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and specialized burn centers concentrate demand in markets with established tissue banking infrastructure and favorable reimbursement frameworks. Regulatory stringency varies sharply across jurisdictions, shaping competitive entry costs and supply chain architectures.
United States
Burn treatment centers in Texas and California are expanding acellular dermal matrix procurement for complex wound coverage under Medicare's adjusted bundled payment models. The FDA enforces Current Good Tissue Practice rules requiring full chain-of-custody documentation that elevates compliance costs for smaller distributors. Boston and Baltimore medical corridors host vertically integrated manufacturers with captive tissue recovery networks.
Germany
University hospitals in Munich and Heidelberg are constructing dedicated reconstructive surgery units, concentrating demand for customized graft sizing in surgical reconstruction applications. The EMA's Medical Device Regulation reclassifies certain processed allografts as Class III devices, imposing notified body certification timelines that delay product launches. The Rhine-Ruhr industrial corridor anchors sterilization technology development for non-processed tissue preservation.
India
Specialized wound care facilities in Mumbai and Delhi are accelerating adoption of placental-derived biologics for diabetic ulcer management. The PLI scheme for medical device manufacturing offers cost offsets for domestic production serving South Asian markets. The Bangalore biotechnology cluster is incubating decellularization protocol startups targeting regional hospital networks.
Switzerland
Swissmedic maintains dual-track FDA-CE certification requirements that preserve cross-border supply continuity for cellular dermal matrices. Basel and Zurich university hospitals are piloting room-temperature lyophilization supply chains to reduce cryogenic infrastructure dependency. Alpine medical technology corridors specialize in perfusion-based manufacturing equipment for extracellular matrix preservation.
Japan
PMDA oversight of processed allografts emphasizes biocompatibility studies for cellular matrices with viability preservation claims. Tokyo and Osaka medical centers are standardizing graft formularies through centralized tissue review boards that evaluate total cost-of-care metrics. The Kansai region hosts cryogenic logistics infrastructure development for secondary hospital network expansion.
Dermal Allograft Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement consolidation and technology differentiation vectors. Vertically integrated manufacturers with captive tissue recovery networks bypass broker intermediaries to satisfy FDA chain-of-custody mandates, while mid-tier distributors rely on regional cold-chain specialists for geographic reach. Two strategic archetypes dominate: perfusion-technology platform owners and placental-derived biologic specialists. Competitive moves center on backward integration into donor tissue sourcing and sterilization innovation for ambient-stable preservation formats.
Among perfusion-technology platform owners, Organogenesis and LifeNet Health occupy positions exemplifying manufacturing-scale competitive differentiation. MiMedx Group anchors the placental-derived biologic specialist archetype, while RTI Surgical represents sterilization innovation positioning for non-processed tissue preservation. These three companies illustrate the strategic segmentation between cellular matrix premium pricing and acellular matrix volume procurement pathways.
| Leading Market Players |
|---|
| Organogenesis |
| LifeNet Health |
| MiMedx Group |
| RTI Surgical |
| Zimmer Biomet |
| AlloSource |
| MTF Biologics |
| Stryker Corporation |
| Integra LifeSciences Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in cryogenic logistics infrastructure across United States secondary hospital networks is compressing margins for cellular dermal matrix suppliers while elevating pricing power for ambient-stable lyophilization providers. This utilization asymmetry is bifurcating procurement contracts between premium cold-chain-dependent products and standard room-temperature alternatives.
Pricing Analysis
Cost-plus contracts indexed to tissue recovery and processing labor costs dominate hospital procurement agreements for acellular dermal matrices. Price differentiation rests on FDA Current Good Tissue Practice certification tier and graft customization depth, with burn treatment centers showing lowest price sensitivity due to emergency procurement protocols while ambulatory surgical centers negotiate hardest on per-unit costs. Pricing pressure intensifies in the standard tier as Medicare bundled payment adjustments squeeze outpatient wound care facility margins.
Supply Chain Analysis
Contract manufacturing concentration for decellularization equipment sits with perfusion technology specialists in Germany, Switzerland, and the United States. Raw material flows draw from captive tissue recovery networks in Texas and California, processed placental biologics from Georgia manufacturing clusters, and sterilization packaging from the Rhine-Ruhr corridor. Single-source vulnerability in cryogenic logistics infrastructure poses structural risk. Distribution runs through vertically integrated manufacturer direct sales for compliance-heavy hospital contracts and regional cold-chain specialists for mid-tier clinic access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as hospital purchasing cooperatives consolidate procurement authority under centralized tissue review boards, creating interoperability requirements between graft performance databases and supplier audit systems.
For Market Incumbents: Harden chain-of-custody documentation systems against FDA audit intensity while capturing donor tissue recovery networks in Texas and California to secure input supply. Invest in lyophilization capacity to exploit ambient-stable product tier expansion as burn treatment centers pilot room-temperature supply chains. For New Entrants and Emerging Players: Pursue white-space positioning in Indian outpatient wound care facilities where PLI scheme cost offsets reduce domestic production barriers. Target ambulatory surgical center procurement frameworks in the United States that lack standardized allograft sourcing, leveraging direct distributor relationships as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cellular dermal matrix manufacturing due to cryogenic infrastructure requirements and dual-track FDA-CE certification timelines. Long-term viability favors acquisition targets with captive tissue recovery networks and perfusion-based processing platforms. Monitor EMA notified body certification backlog clearance as the critical inflection signal for European market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA Medical Device Regulation reclassification demands clinical evidence packages for processed allograft launches. |
| Hospital System Partnership | Centralized tissue review boards in United States health systems govern 60-70% of reconstructive procurement decisions. |
| Backward Integration into Tissue Recovery | Captive donor networks satisfy FDA chain-of-custody mandates while reducing broker-dependent supply volatility. |
| Lyophilization Manufacturing Scale-Up | Ambient-stable storage formats reduce cryogenic dependency and enable same-day graft availability for emergency procedures. |
| Reimbursement Strategy | Medicare bundled payment model adjustments for outpatient wound care facilities accelerate acellular matrix adoption. |
Study Parameters
Initial hypotheses were tested against primary input from tissue bank operations directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EMA Medical Device Regulation guidance documents, CMS Medicare reimbursement databases, and American Association of Tissue Banks compliance audits. Bottom-up procurement volume estimates were triangulated with top-down market sizing derived from manufacturer revenue disclosures.
Demand-supply balance modeling across the analysis window incorporated segmentation by product type, application urgency, end-user facility tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to hospital admission data for burn and trauma cases, reconstructive surgery procedure volumes, and Medicare reimbursement rate trajectories. Forecast inputs included tissue donor availability demographics, lyophilization technology adoption curves, and notified body certification timeline distributions.
Sensitivities concentrate around EMA certification backlog resolution, cryogenic logistics infrastructure buildout rates, and Medicare bundled payment model adjustments. Forecasts reflect documented assumptions regarding donor tissue availability stability and regulatory pathway continuity. Quarterly review of hospital procurement committee contract awards and tissue bank technician compensation trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Airway Management Tubes Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Global Angiography Devices Market
Medical Devices
Spine Positioning Devices Market
Medical Devices
Intravenous Line Connectors Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Baby Thermometer Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Foot Suction Unit Market
Medical Devices
Left Atrial Appendage Devices Market
Medical Devices
Medical Thermometer Market
Medical Devices
Radiofrequency-Based Aesthetic Devices Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Acellular Dermal Matrix Market