
 Wound Healing Supplement Market | 2026-2036
Wound Healing Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Healing Supplement Market Analytics
Single-source ingredient procurement is restructuring into multi-source supply networks across the wound healing supplement value chain. Nestle Health Science leverages its clinical nutrition infrastructure to anchor hospital formulary contracts. Abbott Nutrition sustains R&D intensity in amino acid modulation for tissue repair applications. DSM Firminich competes through captive supply of bioactive collagen peptides.
Wound healing supplements comprise orally administered or topically applied nutritional formulations containing collagen, honey, aloe vera, gelatin, or amino acid complexes that modulate inflammatory response and extracellular matrix deposition during tissue repair. These products typically deliver 10–15 grams of protein equivalent per serving with added micronutrients such as zinc, vitamin C, and arginine to support fibroblast proliferation and angiogenesis. Collagen-based oral powders dominate current revenue pools due to established reimbursement codes and physician familiarity. Honey segments in topical delivery show accelerated growth trajectories driven by antimicrobial resistance concerns and natural product positioning. Hospital application channels capture the largest margin concentration through institutional purchasing power and protocol-driven compliance.
FDA medical food regulations, EFSA health claim frameworks, and WHO wound care guidelines collectively shape product formulation standards and market access requirements across jurisdictions. Compliance with FDA's 21 CFR 101.9(j) medical food criteria determines whether products qualify for physician-directed dispensing outside standard supplement retail channels. Stakeholders must monitor evolving reimbursement decisions from CMS and parallel agencies in Europe and Asia-Pacific as these will determine whether clinical adoption translates into sustainable revenue models.
Market Dynamics
Hospital formulary consolidation is compressing vendor margins while elevating clinical evidence requirements for wound healing supplement procurement. Abbott Nutrition and Nestle Health Science leverage longitudinal outcome data to secure multi-year institutional contracts.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage for medical foods under Part B accelerates physician-directed dispensing in US post-acute care facilities. Hospital procurement teams now prioritize products with established billing codes.
- Antimicrobial resistance protocols:Clinical guidelines from WHO and CDC elevate medical-grade honey as first-line topical therapy for chronic wounds. This displaces silver sulfadiazine in burn and diabetic ulcer protocols.
- Japan's super-aging demographics:METI targets nutritional interventions for pressure ulcer prevention in institutional long-term care. Government procurement volumes for collagen peptides concentrate in Tokyo-Osaka hospital networks.
Market Restraints
- Collagen raw material concentration:Bovine and marine collagen supply clusters in Brazil and Southeast Asia expose formulators to veterinary disease outbreak risks and export permit volatility.
- FDA medical food compliance friction:21 CFR 101.9(j) criteria require disease-specific formulation rationale that extends product development timelines by 18-24 months versus standard dietary supplements.
- Plant protein substitution threat:Pea and rice protein isolates gain traction in vegan-positioned wound care nutrition, though clinical equivalence data for collagen-specific proline-hydroxyproline content remains incomplete.
Strategic Opportunities
- India outpatient chronic wound clinics:CDSCO streamlined medical device and food category convergence creates first-mover advantage for honey-aloe hybrid topicals in tier-2 city dermatology chains.
- EFSA Article 13.5 health claims:Successful collagen peptide dossiers for skin and connective tissue repair would unlock pharmacy channel positioning across Germany, France, and Netherlands.
- Telehealth wound monitoring integration:Remote patient monitoring platforms in US home health agencies create subscription revenue models for supplement-automated replenishment tied to healing trajectory data.
Industry Challenges
- Clinical trialist recruitment bottlenecks:Diabetic foot ulcer studies require specialized podiatry investigators; principal investigator availability constrains pivotal trial initiation timelines.
- Multi-jurisdiction label harmonization:Divergent medical food, supplement, and cosmetic classifications across FDA, EFSA, and Health Canada force SKU proliferation and inventory fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Healing Supplement Market |
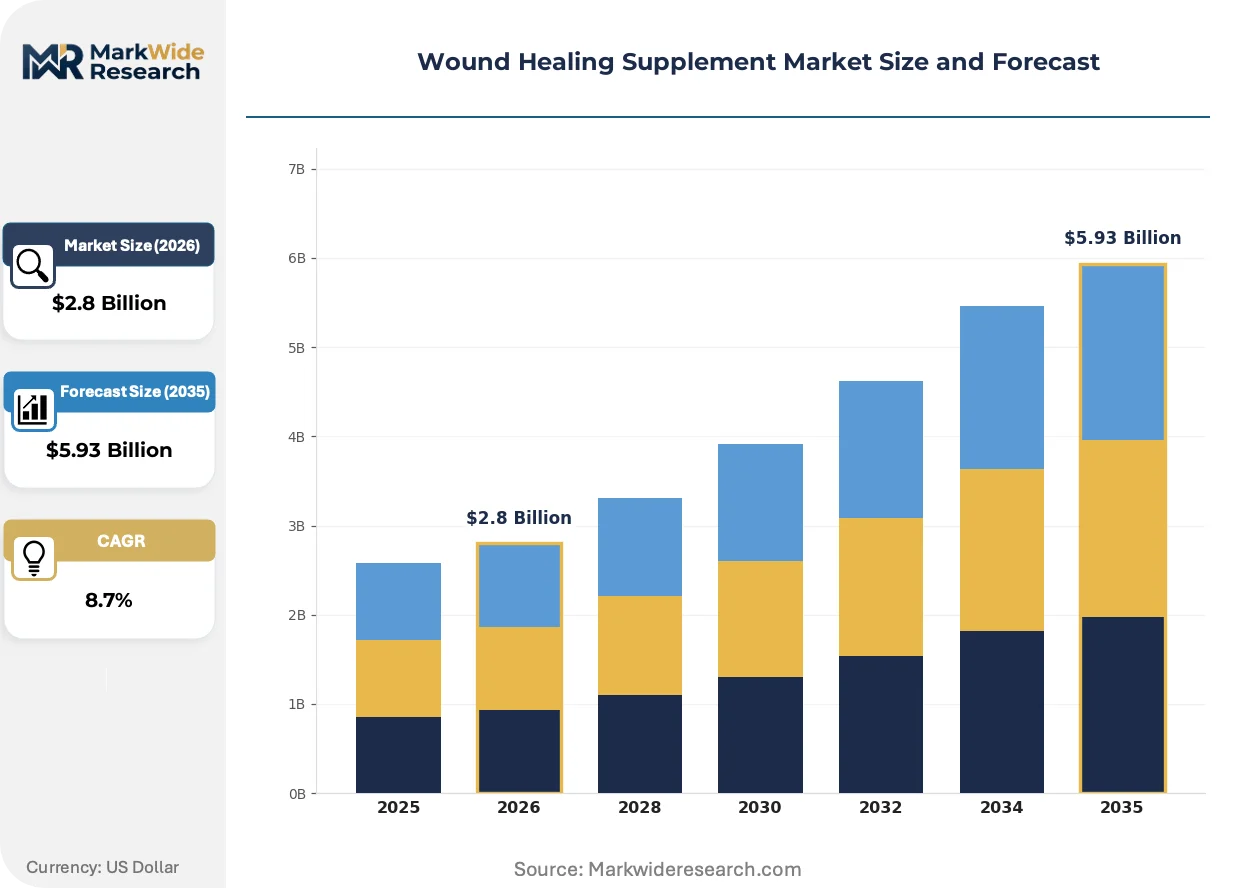
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen, Honey, Aloe Vera, Gelatin Application: Hospital, Homecare, Clinical, Telemedicine Delivery Mode: Topical, Oral, Injectable, Transdermal End User: Patients, Healthcare Professionals, Caregivers, Pharmacies |
| Companies Covered | Nestle Health Science, Abbott Nutrition, Nutricia, Baxter, DSM Firminich, Juven, MiMedx, Organogenesis, Integra Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Healing Supplement Market Evolving Landscape
Digital biomarker integration and precision fermentation are restructuring how wound healing supplements demonstrate efficacy and source bioactive ingredients. Manufacturers now compete on real-world evidence generation speed.
Precision fermentation of recombinant human collagen is modularizing supply chain architecture for pharmaceutical-grade wound healing applications. Biotech suppliers in South Korea and California now deliver batch-consistent triple-helix collagen without animal origin constraints. Hospital formularies in Germany and Switzerland are piloting these inputs for patients with religious or allergy-based restrictions on conventional sources.
EFSA's 2023 updated guidance on health claim substantiation for collagen peptides tightens biomarker requirements for dermal and connective tissue effects. Manufacturers must now demonstrate measurable changes in skin elasticity or wound closure rates versus placebo. French and Italian brands with existing clinical portfolios are accelerating dossier resubmissions, while newer entrants face extended development timelines.
Direct-to-clinician sampling platforms are displacing traditional medical representative models for wound care nutrition adoption. US-based telemedicine wound care networks now curate supplement formularies for affiliated nurse practitioners. This channel concentrates purchase authority with platform operators rather than individual physician preference, compressing brand loyalty cycles.
Wound Healing Supplement Market Segmentation
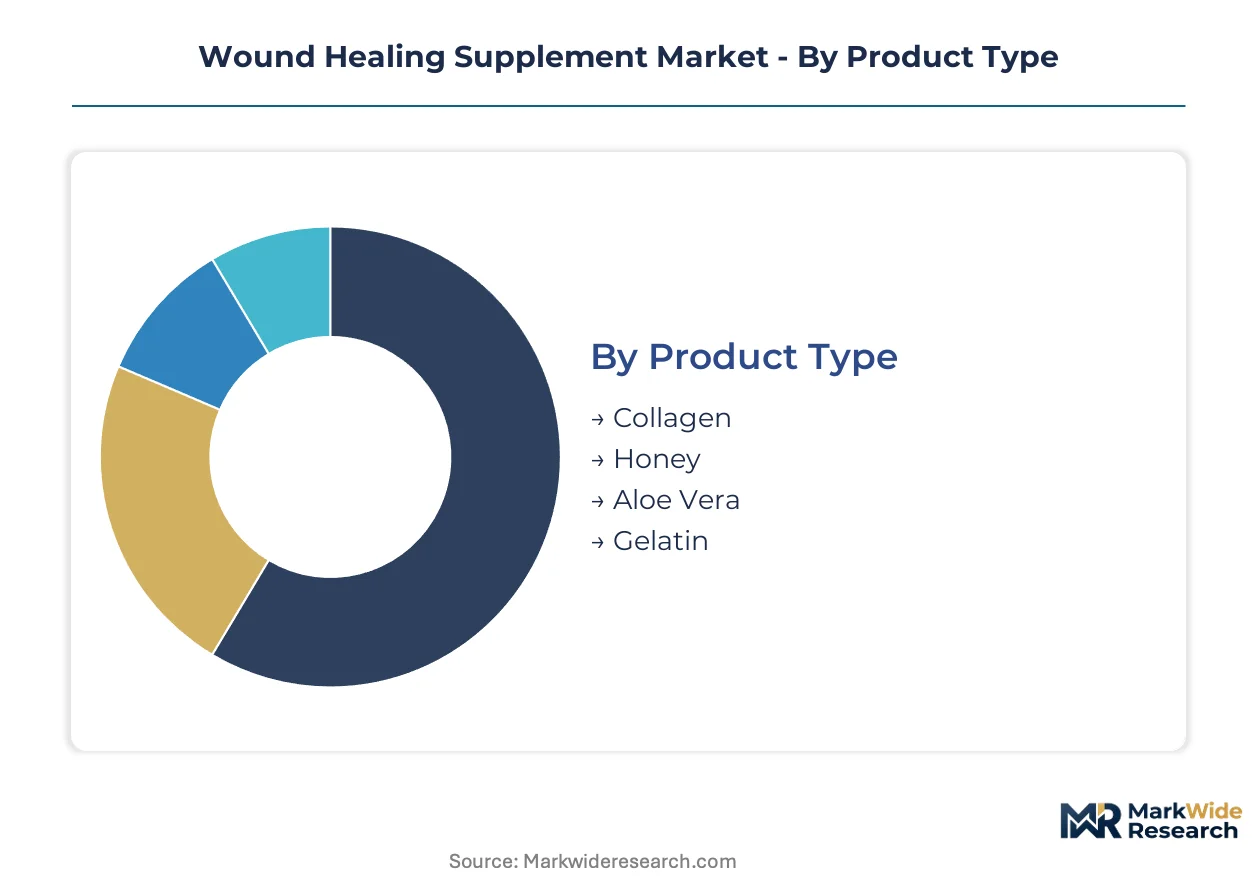
Wound healing supplement segmentation reveals distinct procurement patterns across institutional and consumer channels. Product formulation requirements diverge sharply between hospital formulary compliance and direct-to-patient retail positioning.
Product Type:
Standalone oral powders dominate hospital procurement through established reimbursement pathways, while topical formats embed into wound care kits for integrated therapy protocols.
- Collagen:Oral collagen peptides deliver 10–15 grams protein equivalent per serving with proline-hydroxyproline amino acid profiles specific to extracellular matrix synthesis. Hospital procurement in the United States concentrates on bovine-derived formulations with established CMS billing codes, though marine collagen gains traction in coastal markets with religious dietary restrictions.
- Honey:Medical-grade Manuka and Leptospermum honeys carry standardized methylglyoxal ratings for antimicrobial efficacy against resistant wound pathogens. Demand clusters in burn centers and diabetic foot clinics across Germany and Australia where WHO protocols displace silver sulfadiazine.
- Aloe Vera:Polysaccharide-rich gel extracts modulate inflammatory cytokine response in topical applications.
- Gelatin:Partially hydrolyzed collagen provides cost-effective amino acid substrates for oral nutrition support.
Collagen leads volumes today; honey is gaining share fastest.
Application:
Cost tier separation distinguishes capital-intensive institutional contracts from lower-margin consumer-direct channels with minimal clinical oversight requirements.
- Hospital:Acute care settings mandate FDA 21 CFR 101.9(j) medical food compliance for physician-directed dispensing. Formulary consolidation in US health systems favors vendors with longitudinal outcome data and multi-year contracting capability.
- Homecare:Post-acute facilities operate under Medicare Part B reimbursement with lower evidence thresholds than inpatient protocols.
- Clinical:Outpatient wound centers in India and Brazil blend topical and oral protocols for diabetic ulcer management.
- Telemedicine:Remote monitoring platforms curate automated replenishment tied to healing trajectory data.
Hospital channels capture premium pricing; telemedicine is expanding most quickly.
Delivery Mode:
Volume concentration favors oral formats with manufacturing scale advantages, while topical and injectable segments serve specialized therapeutic niches with higher per-unit margins.
- Topical:Hydrogel and ointment carriers deliver honey, aloe, and collagen peptides directly to wound beds. German and Swiss hospital networks pilot recombinant human collagen from precision fermentation for patients with bovine allergies.
- Oral:Powders and ready-to-drink formats dominate procurement volumes through established supply chains and patient compliance familiarity.
- Injectable:Parenteral amino acid solutions serve critical care settings with compromised gastrointestinal function.
- Transdermal:Microneedle and patch technologies remain developmental with limited commercial penetration.
Oral delivery leads volumes today; topical formats show steepest expansion trajectory.
End User:
Customer type determines regulatory pathway complexity, with healthcare professional intermediation enabling medical food status versus patient self-selection limiting claims scope.
- Patients:Direct purchasers respond to EFSA Article 13.5 health claim visibility in European pharmacy channels.
- Healthcare Professionals:Physicians and nurse practitioners drive formulary decisions through protocol development authority.
- Caregivers:Institutional long-term care staff in Japan execute government procurement for pressure ulcer prevention programs.
- Pharmacies:Retail and hospital dispensaries intermediate between manufacturers and end users with inventory and counseling functions.
Healthcare professionals dominate procurement authority; pharmacy channel positioning is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States hospital procurement networks anchor wound healing supplement volumes through Medicare Part B reimbursement infrastructure and aging demographic concentration. Japan's super-aging institutional care systems and India's emerging outpatient wound clinic chains complete the tripolar demand structure alongside German precision fermentation pilots.
United States
Hospital formulary consolidation and CMS medical food billing codes drive institutional procurement volumes. FDA 21 CFR 101.9(j) compliance determines physician-directed dispensing eligibility outside retail channels. The Texas Medical Center and Mayo Clinic networks anchor multi-year vendor contracts with longitudinal outcome data requirements.
Germany
Burn centers and diabetic foot clinics elevate medical-grade honey protocols per WHO antimicrobial resistance guidelines. EFSA Article 13.5 health claim substantiation tightens collagen peptide biomarker requirements. The Baden-Württemberg hospital network pilots recombinant human collagen from precision fermentation for allergy-restricted patients.
Japan
METI targets nutritional interventions for pressure ulcer prevention in institutional long-term care facilities. Government procurement volumes concentrate in Tokyo-Osaka hospital networks with standardized collagen peptide protocols. The Chubu region's medical device manufacturing clusters supply wound monitoring integration hardware.
India
Tier-2 city dermatology chains expand outpatient chronic wound clinic capacity for diabetic ulcer management. CDSCO streamlined medical device and food category convergence enables honey-aloe hybrid topical positioning. Maharashtra's pharmaceutical formulation hubs and Karnataka's biotech corridors anchor regional manufacturing scale.
Australia
Medical-grade Leptospermum honey demand clusters in specialized wound care centers with standardized methylglyoxal ratings. TGA regulatory alignment with WHO protocols accelerates antimicrobial therapy substitution. Sydney and Melbourne hospital networks drive procurement standardization across public health jurisdictions.
Wound Healing Supplement Market Competitive Landscape
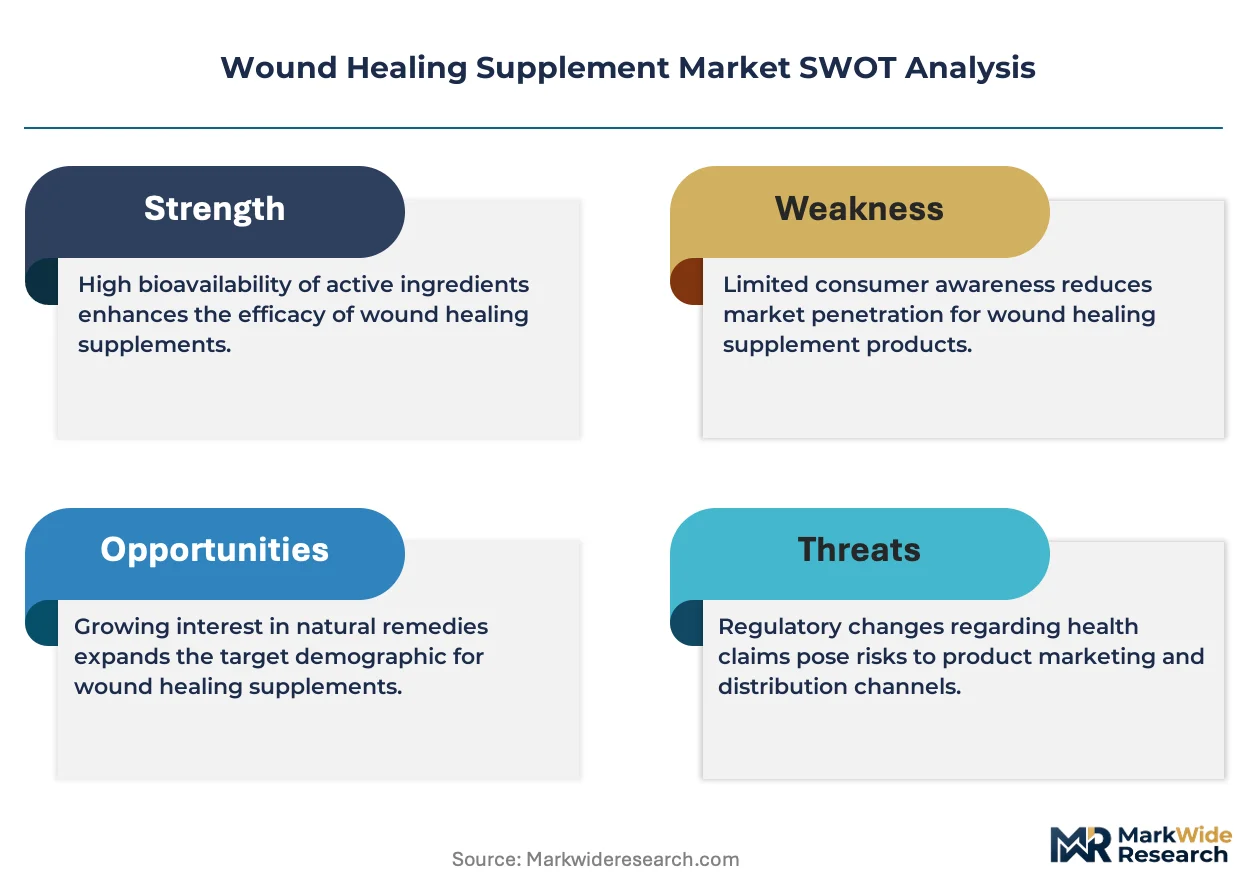
Global majors compete with regional champions across hospital formulary contracting and clinical evidence generation capabilities. The vendor base stratifies into three tiers: multinational clinical nutrition conglomerates with longitudinal outcome databases, mid-scale specialists with captive bioactive ingredient supply, and regional distributors with localized regulatory navigation expertise. Dominant competitive moves include backward integration into collagen peptide manufacturing and strategic partnerships with telehealth wound monitoring platforms.
Within the multinational clinical nutrition tier, Nestle Health Science and Abbott Nutrition exemplify scale-driven formulary anchoring through hospital infrastructure leverage. DSM Firminich occupies a position within the captive supply archetype through bioactive collagen peptide manufacturing integration. These three entities represent the spectrum from clinical protocol development authority to upstream ingredient control.
| Leading Market Players |
|---|
| Nestle Health Science |
| Abbott Nutrition |
| Nutricia |
| Baxter |
| DSM Firminich |
| Juven |
| MiMedx |
| Organogenesis |
| Integra Life Sciences |
| Others |
Value Network & Pricing Analysis
EU Green Deal sustainable sourcing mandates gate both qualified collagen supply and premium-tier pricing access for wound healing supplement manufacturers. Compliance with deforestation-free supply chain requirements from EUDR and parallel US EPA guidance separates contract-eligible vendors from spot-market suppliers. Hospital procurement teams in Germany and the United States now embed sustainability certification into technical evaluation criteria alongside clinical efficacy documentation.
Pricing Analysis
Input-cost pass-through from bovine and marine collagen raw materials drives contract renegotiation cycles for hospital formulary suppliers. Pricing stratifies across pharmaceutical-grade, medical food, and dietary supplement tiers based on FDA 21 CFR 101.9(j) compliance status and batch-specific proline-hydroxyproline assay results. Cost compression in standard-grade oral powders intensifies as Brazilian tannery byproduct supply faces veterinary disease outbreak disruptions. Homecare channels exhibit highest price sensitivity due to direct patient out-of-pocket exposure versus institutional Medicare Part B reimbursement coverage.
Supply Chain Analysis
Collagen peptide supply rests on Brazilian bovine hide processing clusters, Southeast Asian marine capture fisheries, and emerging South Korean precision fermentation bioreactors. Raw material dependencies span veterinary health certificates, methylglyoxal-standardized Manuka honey monofloral sourcing, and aloe vera polysaccharide extraction capacity. Single-source vulnerability concentrates in Brazilian export permit volatility following foot-and-mouth disease surveillance protocols. Distribution runs through hospital GPO contracts, direct-to-clinician telehealth platforms, and retail pharmacy chains with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in wound healing supplements stems from precision fermentation cost curves flattening recombinant collagen production economics. Premium-tier positioning accelerates as hospital formularies prioritize batch-consistent, animal-origin-free inputs for allergy-restricted patient protocols.
For Market Incumbents: Cement hospital formulary anchoring through longitudinal diabetic foot ulcer outcome databases that satisfy CMS medical food evidence requirements. Deepen backward integration into recombinant collagen manufacturing via South Korean biotech partnerships before precision fermentation capacity tightens. Defensive patent filings around honey-aloe hybrid topical formulations preempt CDSCO-registered entrants in Indian outpatient wound clinic chains. For New Entrants and Emerging Players: Outpatient telemedicine wound care platforms represent the most penetrable buyer archetype for subscription-based oral collagen replenishment models. Tier-2 Indian dermatology chains offer white-space positioning for honey-aloe topicals under streamlined CDSCO convergence pathways. Japanese institutional long-term care facilities present government-procurement volume concentration for pressure ulcer prevention protocols. Go-to-market execution should prioritize direct-to-clinician sampling through curated platform formularies rather than traditional medical representative networks. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale collagen peptide specialists with captive bioactive manufacturing because hospital formulary consolidation favors vendors with in-house supply control and multi-jurisdiction regulatory dossiers. Acquisition target archetypes include European collagen brands with EFSA Article 13.5 skin elasticity claim substantiation and Indian honey-aloe topical formulators with CDSCO medical device category registrations. Watch for EFSA health claim approval velocity as inflection indicator for pharmacy channel premium pricing power across Germany, France, and Netherlands.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | South Korean and California bioreactor capacity expansion delivers batch-consistent recombinant collagen for German hospital allergy protocols. |
| EFSA Article 13.5 Dossier Submission | French and Italian manufacturers with skin elasticity biomarker data unlock pharmacy channel positioning across Benelux markets. |
| Telehealth Platform Partnership | US remote wound monitoring networks consolidate purchase authority through curated supplement formulary control. |
| Backward Integration into Collagen Manufacturing | DSM Firminich and comparable specialists secure margin protection against Brazilian raw material export volatility. |
| CDSCO Regulatory Convergence Navigation | First-mover honey-aloe hybrid topicals capture tier-2 Indian dermatology chain procurement before category saturation. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region's hospital procurement networks and regulatory filing databases. Primary interviews incorporated formulary directors at US health systems, EFSA regulatory affairs specialists, CDSCO registration consultants, and METI procurement officers in Japanese long-term care institutions. Secondary validation drew from FDA 21 CFR guidance documents, EFSA health claim registers, CMS Medicare Part B reimbursement determinations, and WHO wound care protocol updates. Bottom-up demand modeling from hospital procurement volumes triangulated against top-down market sizing from clinical nutrition manufacturer disclosures.
Rate-of-change decomposition structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type hierarchy, application channel, delivery mode format, and end-user procurement authority. CAGRs derived from weighted average of historical volume trajectories and forward-looking protocol adoption curves. Industry-specific forecast inputs incorporated CMS medical food coverage expansion timelines and EFSA collagen peptide biomarker guidance evolution.
Underlying measurement precision varies by segment; hospital formulary contract values carry tighter precision than direct-to-consumer retail estimates due to disclosed GPO pricing. Forecasts reflect assumptions regarding regulatory pathway stability and reimbursement code maintenance. Material deviation in FDA medical food enforcement posture or EFSA health claim rejection rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Moist Wound Dressings Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Global Silver Wound Dressing Market
Wound Care
Autologous Wound Patches Market
Wound Care
Animal Wound Care Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Collagen Dressings Market
Wound Care
Wound Evacuators Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Next Generation Wound Closure Device Market
Wound Care
Bioactive Wound Management Market
Wound Care
South Korea Wound Care Market
Wound Care
US Wound Care Management Devices Market
Wound Care
Wound Care Centers Market
Wound Care
Global Active Wound Care Market
Wound Care
Wound Irrigation Devices Market