
 Venous Leg Ulcer (VLU) Treatment Market | 2026-2036
Venous Leg Ulcer (VLU) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Venous Leg Ulcer (VLU) Treatment Market Intelligence
The scarcity of specialized wound care nurses and clinicians is unwinding traditional hospital-centric care models. This shift creates opportunities for products that simplify treatment protocols for non-specialists and general practitioners. Smith & Nephew leverages its extensive portfolio in advanced wound management to capture this transition. Coloplast Corp specializes in chronic care solutions suitable for home use, while 3M competes through material science innovation in its dressing and medical adhesive products.
Venous leg ulcer treatment encompasses medical interventions designed to manage chronic wounds on the lower leg resulting from venous insufficiency. The core therapeutic goal is to control wound exudate and promote granulation tissue formation, often using multi-layer compression systems to address underlying venous hypertension. Compression Dressings form the foundational product category, though Foam and Alginate Dressings are gaining share due to superior moisture management. While Wound Care Centers remain a primary end-user channel, care delivery is rapidly moving towards Home Healthcare Providers.
Market access is governed by medical device regulations such as the US FDA's 510(k) clearance pathway and the European Union's Medical Device Regulation (MDR). These frameworks require manufacturers to provide clinical data demonstrating the safety and efficacy of wound care products, influencing design and material choice. Future competitive advantage will depend on developing products that can prove superior healing outcomes and overall cost-effectiveness to both regulators and healthcare payers.
Market Dynamics
The decentralization of care from traditional hospital settings to home healthcare environments, accelerated by a persistent scarcity of specialized wound care clinicians, is the primary force shaping the market. This transition elevates demand for VLU treatment products that feature simplified application protocols suitable for general practitioners and patients themselves.
Growth Catalysts
- Bioactive Dressings:The adoption of advanced dressings containing elements like collagen, silver, or honey is rising in home healthcare settings. These materials actively promote wound healing and reduce infection risk, aligning with the need for effective, simplified care.
- Aging Demographics:Countries with rapidly aging populations, such as Germany and Japan, exhibit a higher prevalence of chronic venous insufficiency. This demographic trend directly translates into a larger patient base requiring long-term VLU management.
- Regulatory Mandates for Efficacy:Frameworks like the European Union's MDR require manufacturers to provide robust clinical evidence of product effectiveness. This favors advanced wound care products over traditional gauze, as they can better demonstrate superior healing outcomes.
Market Restraints
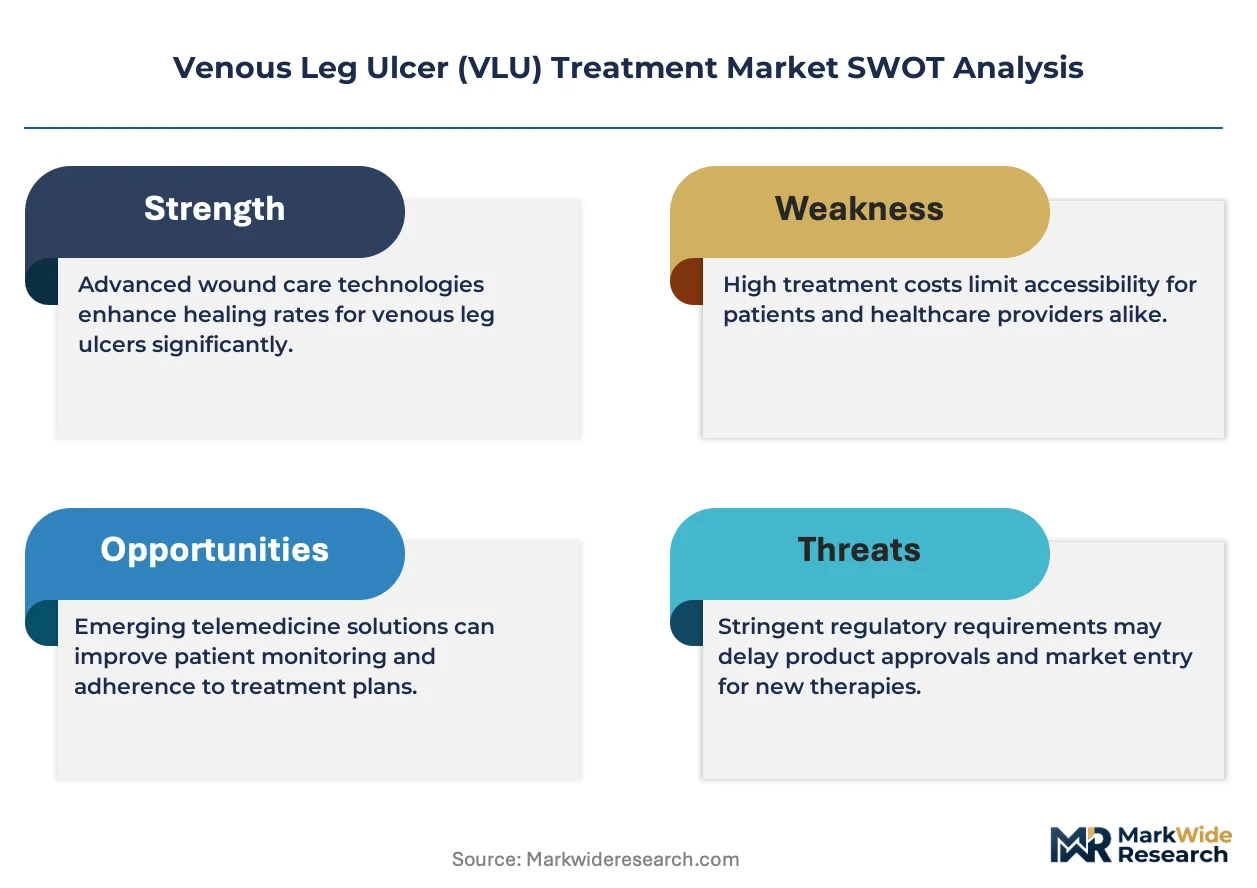
- Reimbursement Hurdles:Healthcare payers and national health systems often have restrictive reimbursement policies for advanced wound dressings. This creates a cost barrier that can favor the use of less effective, but cheaper, traditional treatment options.
- Specialist Labor Shortage:The limited availability of vascular surgeons and certified wound care nurses constrains the proper application and management of complex treatments like multi-layer compression therapy, particularly in rural areas.
- Threat from Alternative Modalities:For severe or non-healing ulcers, advanced therapies such as negative pressure wound therapy (NPWT), ultrasound devices, and bioengineered skin substitutes present a significant substitution threat to conventional dressing-based treatments.
Strategic Opportunities
- Digital Health Integration:There is a clear opportunity to embed sensor technology into dressings for remote monitoring of wound status. This creates value by enabling telehealth consultations and timely interventions, improving outcomes in home care settings.
- Emerging Market Penetration:Markets in Latin America and Southeast Asia, where chronic disease incidence is growing alongside healthcare expenditure, represent significant untapped regions for VLU treatment product manufacturers.
- Patient-Centric Product Design:Developing products focused on patient comfort, ease of self-application, and reduced dressing change frequency can create strong brand loyalty and differentiation, especially within the home healthcare channel.
Industry Challenges
- Practitioner Training Deficit:A widespread training gap exists among general practitioners and home care nurses regarding the correct diagnostic and application techniques for multi-layer compression systems, leading to suboptimal patient outcomes.
- Clinical Data Generation Costs:Meeting the heightened evidentiary requirements of regulators like the FDA and competent authorities under the EU MDR demands substantial investment in clinical trials, lengthening product development timelines and increasing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venous Leg Ulcer (VLU) Treatment Market |
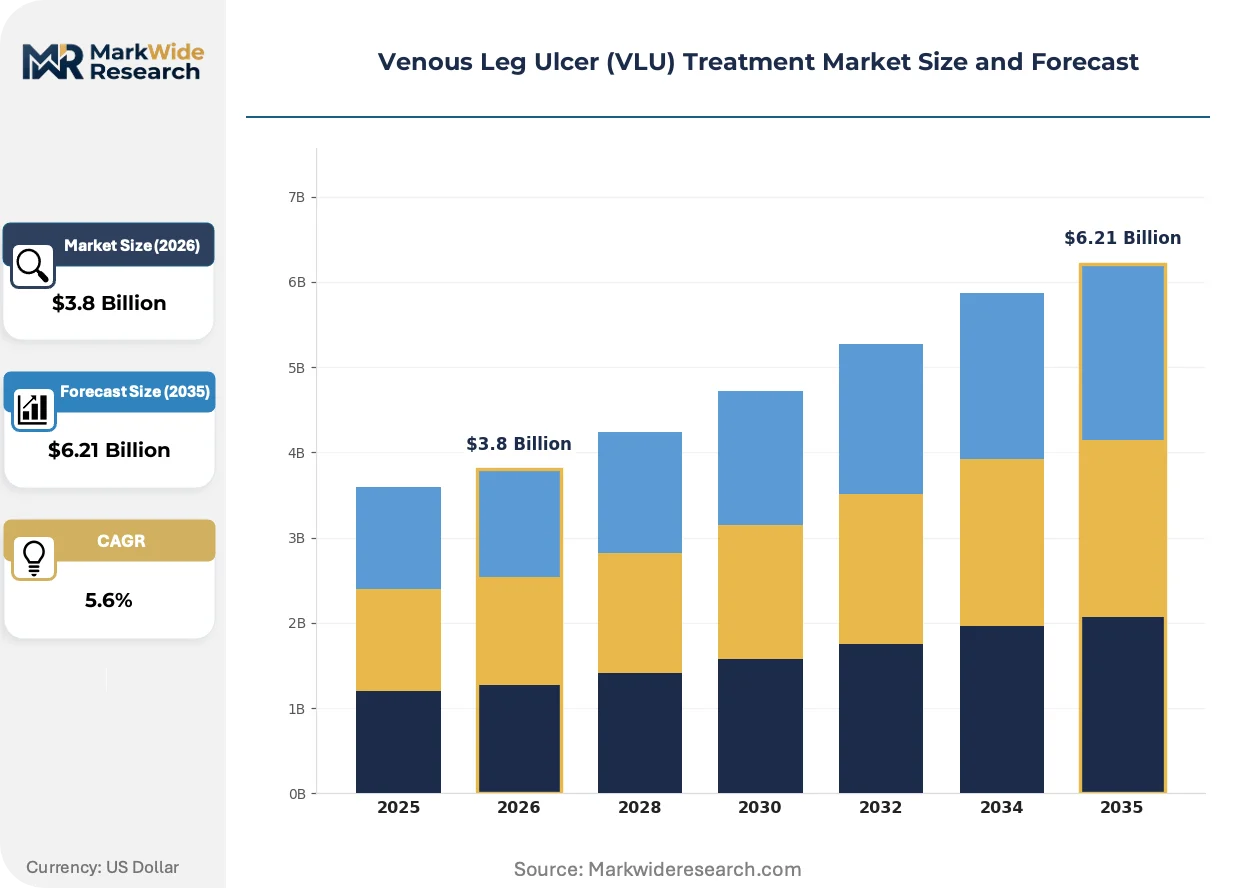
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Dressings, Hydrocolloid Dressings, Foam Dressings, Alginate Dressings, Active Dressings Therapy Area: Wound Cleansing, Debridement, Infection Control, Pain Management, Skin Grafting End User: Wound Care Centers, Home Healthcare Providers, Dermatology Clinics, Long-Term Care Facilities, Ambulatory Surgery Centers Delivery Mode: Topical Application, Negative Pressure Therapy, Surgical Intervention, Injectable Treatment, Laser Therapy |
| Companies Covered | Smith & Nephew, Integra Lifesciences, Coloplast Corp, 3M, ConvaTec Group Plc, Sigvaris Group, URGO, Mölnlycke Health Care AB, Paul Hartmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venous Leg Ulcer (VLU) Treatment Market Strategic Shifts & Innovations
Product development is converging on solutions that integrate advanced material science with digital monitoring capabilities. This evolution is driven by the need to demonstrate superior clinical efficacy and overall cost-effectiveness to both regulators and healthcare providers operating in increasingly decentralized care environments.
Smart dressings incorporating sensor technology are gaining traction in clinical evaluations. These products are designed to monitor wound biomarkers such as pH, temperature, and moisture levels in real-time without disturbing the wound bed. Wound care centers and home healthcare agencies are the primary adopters. This technology is displacing traditional passive dressings by providing data that enables proactive intervention, reduces unnecessary dressing changes, and lowers the total cost of care.
The European Union's Medical Device Regulation (MDR) is forcing a significant shift in compliance strategy. It imposes a higher burden of proof for clinical safety and performance, requiring more extensive clinical data and continuous post-market surveillance. This regulation impacts all device classes, compelling manufacturers targeting key markets like Germany and France to invest heavily in robust quality management systems and clinical evaluation reports to maintain market access.
A shift toward value-based procurement models is altering purchasing decisions within large healthcare networks. This approach de-emphasizes simple unit price and instead prioritizes products that can demonstrate improved clinical outcomes, such as faster healing times or reduced infection rates. This trend is most visible in integrated health systems in the United States and the UK's National Health Service, favoring suppliers with strong clinical evidence for their portfolios.
Venous Leg Ulcer (VLU) Treatment Market Segmentation
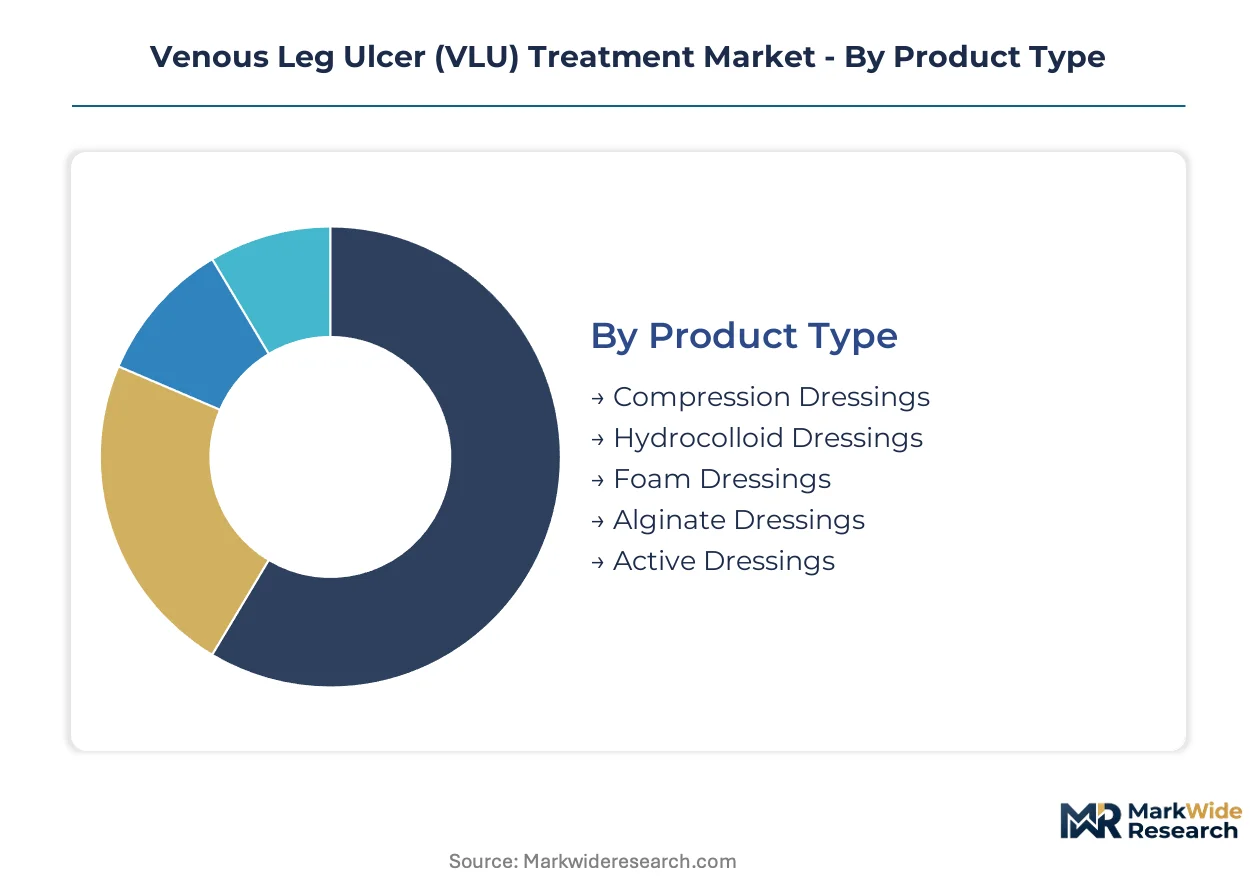
The Venous Leg Ulcer (VLU) Treatment Market segments reflect diverse therapeutic approaches and product innovations addressing chronic wound care. Understanding these distinct categories provides clarity on product development priorities and end-user channel dynamics. Manufacturers tailor solutions for specific wound characteristics and care settings, optimizing treatment outcomes.
Product Type:
Margin pools within product types are shifting towards advanced bioactive dressings, driven by their superior clinical efficacy and value proposition. These specialized dressings command higher price points due to their active components and advanced healing properties.
- Compression Dressings:These products apply sustained pressure to the lower leg, reducing edema and improving venous return in VLU patients. Demand remains foundational in both hospital and home care settings for managing underlying venous hypertension.
- Hydrocolloid Dressings:Composed of gel-forming agents, these dressings create a moist wound environment conducive to healing and autolytic debridement. They are frequently used for shallow wounds with light to moderate exudate in long-term care facilities.
- Foam Dressings:Highly absorbent foam dressings manage moderate to heavy exudate while providing cushioning and thermal insulation to the wound bed. Their superior moisture management capabilities increase their share in home healthcare provider applications.
- Alginate Dressings:Derived from seaweed, alginate dressings absorb large amounts of exudate and form a gel that promotes a moist healing environment. These are gaining share in wound care centers for highly exuding wounds due to their effective fluid handling.
- Active Dressings:These advanced dressings incorporate elements such as collagen, silver, or honey to actively promote healing, reduce infection risk, and manage bioburden. Adoption is rising in home healthcare settings where simplified, effective care is paramount.
Compression Dressings holds installed capacity. Active Dressings is rotating up the share rankings.
Therapy Area:
The application focus across therapy areas emphasizes comprehensive wound management, from initial cleansing to advanced healing interventions. Each area targets specific challenges in the VLU treatment pathway, influencing product design and clinical protocols.
- Wound Cleansing:This involves irrigating and decontaminating the wound surface to remove debris, bacteria, and non-viable tissue, preparing the wound bed for subsequent treatments. It is a critical initial step performed across all care settings, including home care.
- Debridement:The process of removing dead, damaged, or infected tissue from the wound to promote healing and reduce infection risk. Various methods, including surgical, mechanical, enzymatic, and autolytic debridement, are employed by specialized wound care centers.
- Infection Control:Strategies and products aimed at preventing and managing microbial contamination within the wound, often utilizing antimicrobial dressings or topical agents. Effective infection control is paramount in preventing complications and accelerating healing, particularly in patients with compromised immune systems.
- Pain Management:Interventions focused on alleviating pain associated with VLU, which can range from mild discomfort to severe, chronic pain. These include pain-reducing dressings and systemic analgesics prescribed by general practitioners.
- Skin Grafting:A surgical procedure involving transplanting healthy skin to cover large or non-healing VLU defects. This advanced therapy is typically performed in hospital settings for severe, chronic cases.
Wound Cleansing remains a foundational practice. Skin Grafting represents the most complex intervention.
End User:
Customer type defines distinct procurement patterns and service delivery models within the VLU treatment market. Each end-user segment requires tailored product features and support services to meet their operational demands.
- Wound Care Centers:Specialized facilities providing comprehensive VLU diagnosis, treatment, and management by multidisciplinary teams. These centers are primary adopters of advanced therapies and require sophisticated product portfolios for complex cases.
- Home Healthcare Providers:Agencies delivering medical care to patients in their residences, often for chronic conditions like VLU. The demand here is for user-friendly, effective products suitable for application by non-specialists or patients themselves, aligning with decentralization trends.
- Dermatology Clinics:Medical practices specializing in skin conditions, including the diagnosis and initial management of VLUs. These clinics often refer complex cases but utilize basic wound care products for less severe presentations.
- Long-Term Care Facilities:Residential care settings for individuals requiring ongoing medical or personal care, where VLU prevalence is often higher among elderly residents. Products here prioritize ease of use and cost-effectiveness for routine care by nursing staff.
- Ambulatory Surgery Centers:Facilities where surgical procedures not requiring overnight hospitalization are performed, including some debridement or minor surgical interventions for VLUs. They focus on efficient, high-quality, single-use products.
Home Healthcare Providers are gaining strategic importance. Wound Care Centers maintain critical expertise.
Delivery Mode:
Innovation in delivery mode focuses on enhancing therapeutic efficacy and patient convenience, ranging from traditional topical applications to advanced interventional procedures. Each mode addresses specific clinical needs and disease severities.
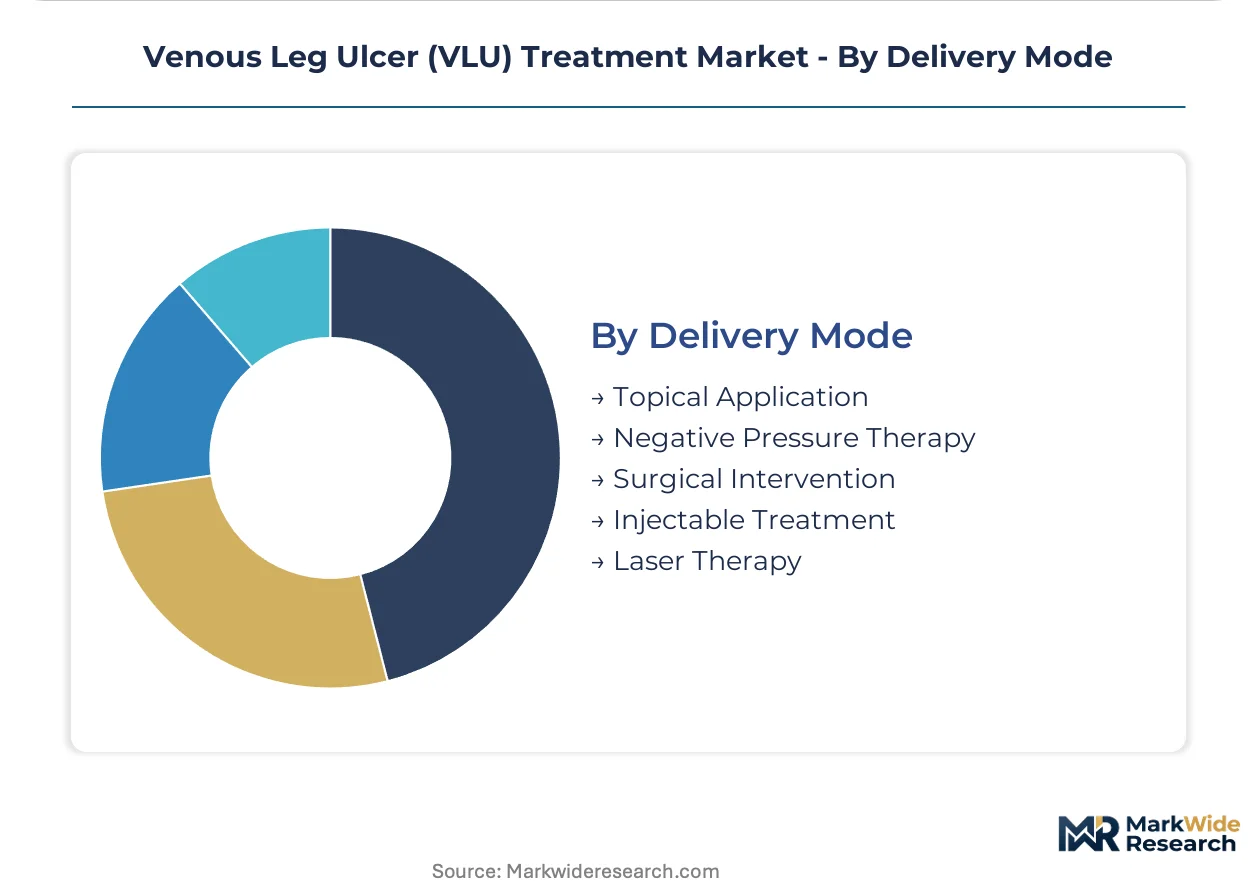
- Topical Application:The direct application of dressings, ointments, or creams onto the wound surface to promote healing, manage exudate, or control infection. This is the most common and accessible delivery mode, prevalent in home care settings.
- Negative Pressure Therapy:A medical device application that uses a vacuum pump to create negative pressure over a wound, drawing out fluid and promoting blood flow. This advanced therapy accelerates healing for complex or non-healing VLUs, primarily in hospital and specialized wound care centers.
- Surgical Intervention:Procedures such as vein ligation, stripping, or bypass surgery to address underlying venous insufficiency causing VLUs. These interventions are typically reserved for severe cases where conservative treatments have failed.
- Injectable Treatment:Involves the administration of sclerosing agents or other therapeutic substances directly into incompetent veins to close them. This minimally invasive approach manages venous reflux, a root cause of VLUs.
- Laser Therapy:Utilizes focused light to ablate or seal incompetent veins, improving venous circulation and aiding VLU healing. This modern technique offers a less invasive alternative to traditional surgery.
Topical Application remains the most widely adopted method. Negative Pressure Therapy exhibits a steep expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's Medical Device Regulation (MDR) significantly influences the Venous Leg Ulcer (VLU) treatment market by demanding rigorous clinical evidence. This regulatory framework drives innovation towards products demonstrating superior efficacy and safety. Demand for VLU management solutions is particularly concentrated in countries with aging populations.
Germany
Germany exhibits substantial demand for VLU treatments due to its rapidly aging population and high prevalence of chronic venous insufficiency. The European Union's MDR mandates robust clinical data for medical devices, influencing product development and market access. Medical technology clusters in Bavaria and North Rhine-Westphalia focus on developing advanced wound care solutions.
United States
The United States market is driven by a strong emphasis on home healthcare delivery and advanced wound care technologies. The US FDA's 510(k) clearance pathway governs market entry for VLU treatment products, ensuring safety and effectiveness. Major medical device innovation hubs in California and Massachusetts foster the development of smart dressings and digital health integration.
Japan
Japan faces a growing need for VLU therapies due to its advanced aging demographics and associated increase in chronic venous diseases. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates VLU treatment products, emphasizing clinical performance and patient safety. Tokyo and Osaka serve as centers for medical technology research and the adoption of innovative wound care techniques.
United Kingdom
The United Kingdom's National Health Service (NHS) procurement shifts towards value-based models, favoring VLU treatments that demonstrate superior clinical outcomes and cost-effectiveness. Health technology assessments guide the adoption of advanced dressings and compression systems. London and Cambridge are key hubs for medical research and the integration of digital health solutions in chronic care.
Brazil
Brazil represents a significant emerging market for VLU treatments, propelled by increasing chronic disease incidence and expanding healthcare expenditure. ANVISA, the national health surveillance agency, regulates medical devices, requiring local registration and compliance. São Paulo's robust healthcare infrastructure supports the adoption of both foundational and advanced wound care products.
Venous Leg Ulcer (VLU) Treatment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the Venous Leg Ulcer (VLU) treatment market. The market structure exhibits consolidation among established players with extensive product portfolios. Key archetypes include diversified medical technology giants and specialized wound care solution providers. Strategic partnerships and portfolio diversification are dominant competitive moves.
Specialists in advanced wound management, such as Smith & Nephew, leverage extensive portfolios to address evolving care models, particularly the shift towards home healthcare. Coloplast Corp, a Danish company, exemplifies a focus on chronic care solutions suitable for home use, aligning with decentralization trends and patient-centric product design. The US-based 3M Company occupies a position through material science innovation, applying its expertise to dressing and medical adhesive products that support effective wound healing. These companies collectively represent the drive towards more effective and user-friendly VLU treatment options.
| Leading Market Players |
|---|
| Smith & Nephew |
| Integra Lifesciences |
| Coloplast Corp |
| 3M |
| ConvaTec Group Plc |
| Sigvaris Group |
| URGO |
| Mölnlycke Health Care AB |
| Paul Hartmann |
| Others |
Cost & Logistics Intelligence
Value-based procurement contracts, prevalent across integrated healthcare systems, lock in both supply access and price visibility for Venous Leg Ulcer (VLU) treatment products. This contracting approach encourages manufacturers to demonstrate superior clinical efficacy and cost-effectiveness, influencing product development and market access strategies.
Pricing Analysis
Geographic pricing spreads for VLU treatment products vary significantly, reflecting diverse healthcare systems and regulatory landscapes. Value-based procurement models and tiered pricing structures dominate, with advanced bioactive dressings commanding higher price points. Product differentiation stems from demonstrated clinical efficacy under stringent regulatory frameworks like the EU MDR and US FDA 510(k) clearance. Pricing pressure intensifies due to restrictive reimbursement policies from national health systems, favoring cheaper, traditional options. Home Healthcare Providers and Long-Term Care Facilities exhibit higher price sensitivity compared to specialized Wound Care Centers.
Supply Chain Analysis
Specialized raw material sourcing, particularly for advanced bioactive components, anchors the supply chain for VLU treatment products. Manufacturing concentrates in developed economies, including the United States, Germany, and Denmark, where established medical device industries reside. Key dependencies include collagen, silver, alginate, and sensor technologies for smart dressings. A significant structural risk involves the high cost and lengthy timelines for clinical data generation required by regulators, impacting product availability. Distribution runs through direct sales to large hospital networks and specialized medical distributors serving home healthcare providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Venous Leg Ulcer treatment market presents an early-cycle expansion story, driven by the increasing penetration of advanced wound care solutions into home healthcare settings.
For Market Incumbents: Compound R&D investments in advanced material science and digital health integration to maintain a competitive edge against emerging alternative therapies. Diversify product portfolios with patient-centric designs that simplify application for non-specialists, addressing the persistent specialist labor shortage. Leverage existing regulatory expertise to navigate stringent frameworks like the EU MDR, ensuring continued market access and product differentiation.
For New Entrants and Emerging Players: Anchor in underserved market segments by developing user-friendly, cost-effective VLU solutions tailored for general practitioners and home healthcare environments. Target emerging markets in Latin America and Southeast Asia, where chronic disease incidence is rising and healthcare expenditure is expanding. A strong go-to-market angle involves demonstrating clear value proposition through simplified treatment protocols and superior healing outcomes for payers.
For Investors and Strategic Acquirers: Specialized technology developers focusing on sensor-integrated dressings and advanced biomaterials represent attractive acquisition targets for long-term portfolio growth. The market exhibits sustained viability over a 5-10 year window, supported by aging demographics and the decentralization of care. A critical signal to watch is the evolution of reimbursement policies, particularly for innovative digital health solutions in wound care.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance | Ensures market entry and regulatory compliance for new VLU products in the United States. |
| Digital Health Integration | Enables remote monitoring of wound status, improving patient outcomes in home care settings. |
| Partnership with Home Healthcare Agencies | Expands product reach and adoption among non-specialist care providers for VLU management. |
| Investment in Bioactive Material R&D | Drives innovation in advanced dressings, offering superior healing properties for complex wounds. |
| Value-Based Contracting Adoption | Aligns product pricing with clinical outcomes, securing preferred status with large healthcare payers. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings regarding the VLU treatment market. Primary insights were gathered from wound care nurses, hospital procurement managers, regulatory affairs specialists, and home healthcare agency directors. Secondary research involved analysis of US FDA 510(k) clearances, EU MDR compliance documents, national health system procurement data, and medical device industry reports. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy and comprehensive market understanding.
Sensitivity analysis informed the forecast framework, assessing market dynamics under varying adoption rates and regulatory scenarios across the modeling period. Segmentation dimensions modeled included product type, therapy area, end-user, delivery mode, and patient ulcer severity. Compound Annual Growth Rates were derived through regression analysis, incorporating historical trends and expert consensus. Key forecast inputs included the incidence of chronic venous insufficiency and the prevalence of aging populations.
Decision-makers should treat outputs as directional under current macroeconomic conditions and established regulatory frameworks; material deviation would warrant model refresh. Forecasts reflect assumptions regarding technological advancements and healthcare expenditure growth. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Australia Wound Care Management Devices Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Wound Closure Devices Market
Wound Care
Philippines Wound Care Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Wound Care Biologics Market
Wound Care
Wound Care Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Global Burn Care Market
Wound Care
Belgium and Netherlands Advanced Wound Care Market