
 Combat Dressing Market | 2026-2036
Combat Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Combat Dressing Market Outlook
Specialized trauma medicine training capacity is rotating toward combat medic certification programs, tightening the labor pipeline for advanced dressing deployment. North American Rescue leverages its vertical integration across military distribution channels to sustain contract visibility with U.S. defense logistics. Z-Medica differentiates through hemostatic technology leadership in kaolin-based formulations, while PerSys Medical anchors its position in junctional tourniquet-integrated dressing systems for tactical medicine applications.
Combat dressings are sterile, pressure-applicable wound coverings engineered with hemostatic agents, absorbent substrates, and adhesive or elastic retention mechanisms designed to control hemorrhage and prevent infection in pre-hospital trauma scenarios. Trauma dressings incorporating active clotting technology command premium positioning due to battlefield mortality reduction requirements, while antimicrobial dressings are gaining fastest in emergency medical services where infection control protocols have tightened. Gauze dressings remain the volume baseline across defense force procurement, though hydrocolloid and silicone material variants are carving margin pools in sports team and civilian first aid segments where comfort and removability drive replacement cycles.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern hemostatic dressing commercialization, with the FDA requiring clinical validation of time-to-hemorrhage-control claims that extend development timelines. The U.S. Department of Defense mandates compliance with military specification MIL-DTL-3643 for field dressings, creating a dual-track certification burden that favors established suppliers with regulatory affairs infrastructure. Stakeholders must monitor evolving NATO standardization agreements for trauma care equipment, as interoperability requirements will reshape procurement eligibility and testing protocols for cross-alliance suppliers.
Market Dynamics
Hemostatic material innovation is compressing development cycles as chitosan and kaolin formulations displace conventional gauze in NATO trauma protocols, forcing suppliers to rebuild manufacturing lines around active clotting chemistry rather than passive absorbency.
Growth Catalysts
- MIL-DTL-3643 Compliance Mandates:U.S. Department of Defense specifications for field dressings create captive demand volumes that stabilize procurement pipelines for qualified suppliers.
- Chitosan Chemistry Advances:Marine-derived biopolymers demonstrate superior clotting kinetics in hypothermic conditions, expanding addressable indications beyond standard trauma.
- Tactical Emergency Medicine Training:Civilian first responder certification programs in the United States are embedding combat dressing protocols into standard curricula.
Market Restraints
- FDA 510(k) Clinical Validation Burden:Time-to-hemorrhage-control evidentiary requirements extend regulatory timelines by 18-24 months for novel hemostatic claims.
- Raw Material Concentration:Medical-grade chitosan supply concentrates among Southeast Asian crustacean processing clusters, exposing cost volatility to fishery yield fluctuations.
- Synthetic Hemostat Substitution:Recombinant thrombin and fibrin sealants compete for surgical applications with superior precision dosing.
Strategic Opportunities
- Junctional Hemorrhage Applications:Axillary and inguinal wound sites lack tourniquet compatibility, creating white space for integrated dressing-tourniquet hybrid systems.
- EU MDR Transition Window:Stricter clinical evidence requirements for CE marking are clearing marginal competitors, consolidating shelf access for dossier-ready suppliers.
- Sports Medicine Channel Expansion:Professional athletic training staffs are adopting military-grade trauma dressings for pitch-side hemorrhage control.
Industry Challenges
- Combat Medic Certification Bottlenecks:Specialized trauma medicine training capacity constraints limit deployment velocity for advanced dressing systems.
- Dual-Track Certification Complexity:Simultaneous FDA and military specification compliance demands redundant quality systems and documentation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combat Dressing Market |
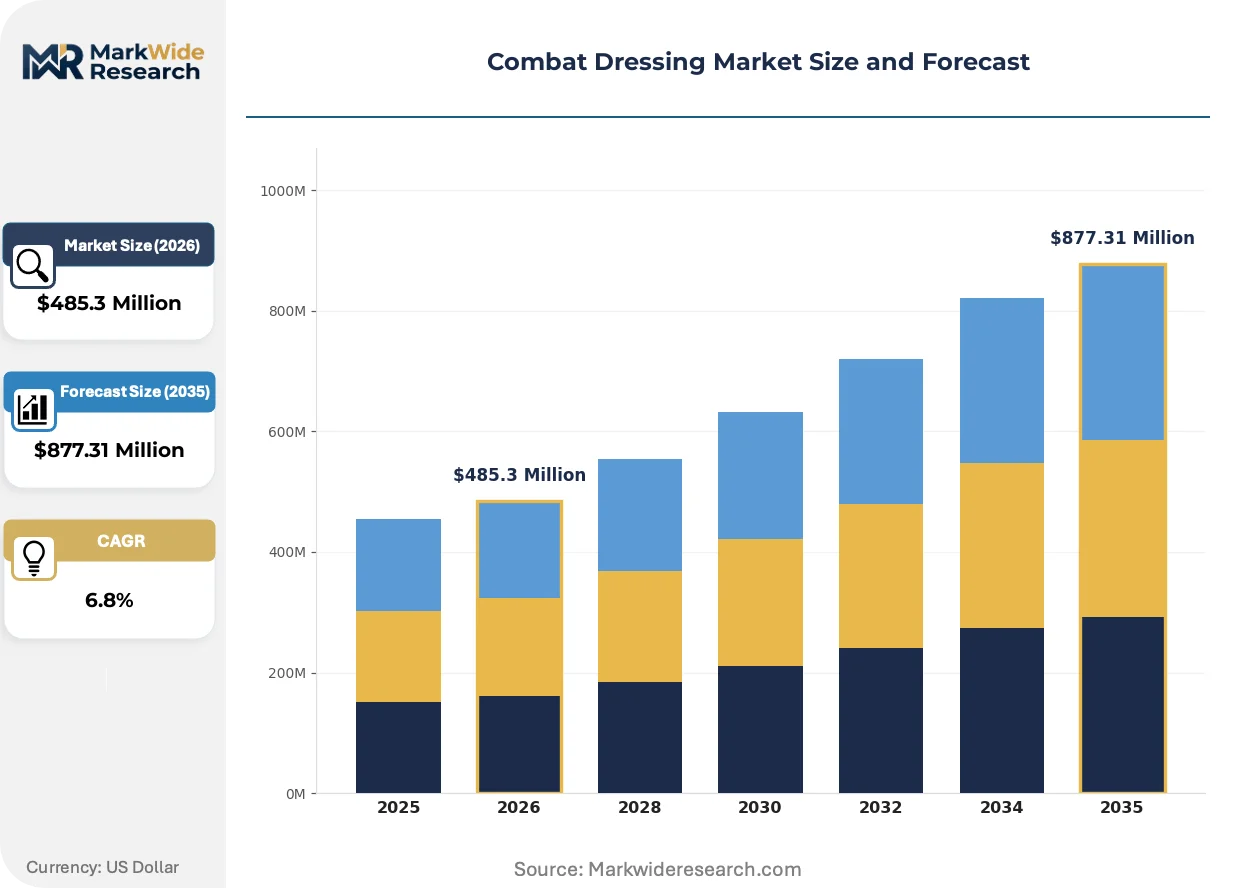
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Bandages, Gauze Dressings, Trauma Dressings, Antimicrobial Dressings Application: Military Operations, Emergency Medical Services, Civilian First Aid, Tactical Medicine Material: Cotton, Hydrocolloid, Foam, Silicone End User: Defense Forces, Hospitals, First Responders, Sports Teams |
| Companies Covered | Z-Medica, PerSys Medical, North American Rescue, TyTek Medical, H&H Medical Corporation, First Care Products, Celox Medical, 3M, Bound Tree Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combat Dressing Market Strategic Shifts
Active clotting chemistry is displacing passive absorbency as the primary performance vector, with material science convergence and regulatory harmonization pressures rewriting competitive requirements across defense and civilian channels.
Chitosan-based hemostatic dressings is miniaturizing into compact, single-use configurations for individual soldier carry. Special operations units are field-testing palm-sized variants that retain full clotting efficacy at one-third the pack volume of standard issue. This compression is enabling distributed casualty care models where every warfighter carries hemorrhage control capability rather than relying solely on medic attachment.
EU MDR clinical evidence requirements are elevating barrier-to-entry thresholds for hemostatic dressing commercialization. The regulation now mandates post-market surveillance data and biocompatibility testing that many legacy suppliers lack. European emergency medical services are responding by consolidating vendor lists around established CE-marked portfolios, reducing procurement fragmentation.
Civilian tactical medicine programs are absorbing military trauma protocols at accelerated rates. Urban emergency medical services in the United States are replacing standard gauze with hemostatic-impregnated alternatives in ambulance inventories. This behavioral shift concentrates demand among municipal procurement offices that previously prioritized cost minimization over performance specifications.
Combat Dressing Market Segmentation
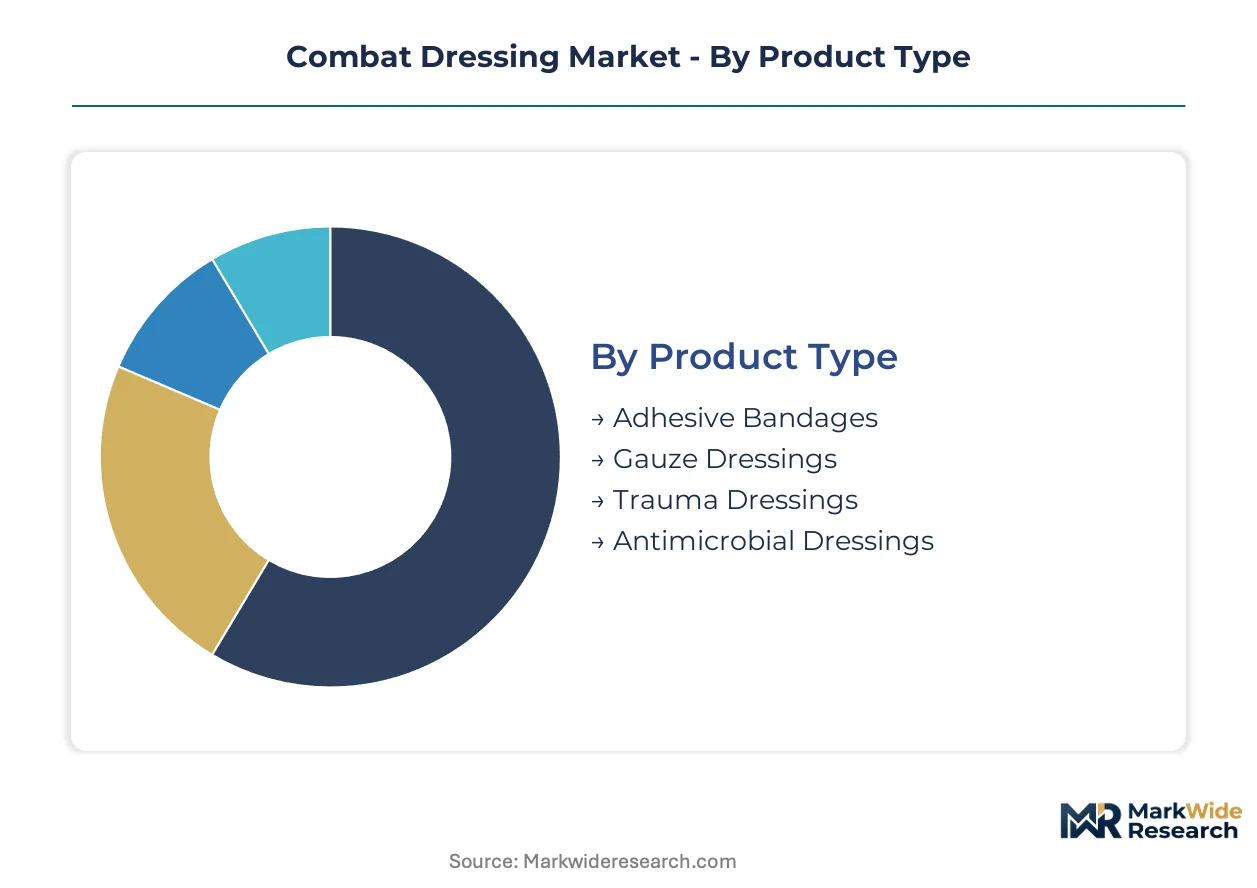
Combat dressing segmentation reveals divergent margin economics across military specification compliance and civilian convenience requirements. Product type and application dimensions show the sharpest pricing spreads, while material chemistry and end-user certification demands reshape procurement eligibility.
Product Type:
Premium margins concentrate in active hemostatic formulations where military specification compliance creates pricing power.
- Trauma Dressings:These incorporate chitosan or kaolin hemostatic agents with pressure-elastic retention systems engineered for junctional hemorrhage control. U.S. defense logistics and NATO trauma protocols are standardizing procurement around MIL-DTL-3643 qualified variants, compressing vendor pools to established military suppliers.
- Antimicrobial Dressings:Silver-impregnated or iodine-releasing substrates target infection prevention in extended field care scenarios. Emergency medical services in the United States are embedding these into ambulance standard inventories as civilian tactical medicine protocols tighten.
- Gauze Dressings:Plain woven cotton or synthetic mesh remains the volume baseline across defense force field kits due to cost minimization mandates and universal compatibility with existing training curricula.
- Adhesive Bandages:Sterile strip configurations with hypoallergenic adhesives serve minor wound closure in individual soldier first aid kits and civilian retail channels.
Gauze dressings hold installed capacity. Antimicrobial dressings are rotating up the share rankings.
Application:
Volume concentration tracks defense procurement cycles, while civilian channels show steepest expansion trajectory in certification program adoption.
- Military Operations:Battlefield casualty care protocols under NATO standardization agreements drive specification-heavy procurement with multi-year contract visibility. Hemostatic performance claims require FDA 510(k) clearance alongside military qualification testing.
- Tactical Medicine:Special operations and law enforcement units demand compact, individual-carry configurations with junctional tourniquet integration. Urban SWAT teams and federal tactical units in the United States are expanding inventory depth.
- Emergency Medical Services:Municipal ambulance services are replacing passive gauze with hemostatic alternatives as trauma training curricula absorb military protocols.
- Civilian First Aid:Retail and institutional channels prioritize cost efficiency and shelf stability over active clotting chemistry, though sports medicine applications are absorbing military-grade specifications.
Military operations anchor procurement volume. Tactical medicine is climbing the fastest in segment share.
Material:
Supply chain geography and biocompatibility testing burdens segment margin structure.
- Hydrocolloid:Gel-forming carboxymethylcellulose matrices maintain moist wound environments for burn and abrasion management. Sports team medical staffs and hospital outpatient clinics favor these for patient comfort and reduced dressing change frequency.
- Silicone:Soft-adhesion polymers enable atraumatic removal for fragile skin populations. Long-term care facilities and pediatric units specify these to minimize tissue trauma during dressing changes.
- Cotton:Woven and nonwoven cellulose substrates dominate defense procurement due to established supply chains and compatibility with legacy sterilization infrastructure.
- Foam:Polyurethane absorbent layers manage exudate in moderate-to-heavy drainage wounds, finding placement in hospital settings where fluid management protocols are standardized.
Cotton maintains production scale. Hydrocolloid is gaining share fastest among non-military applications.
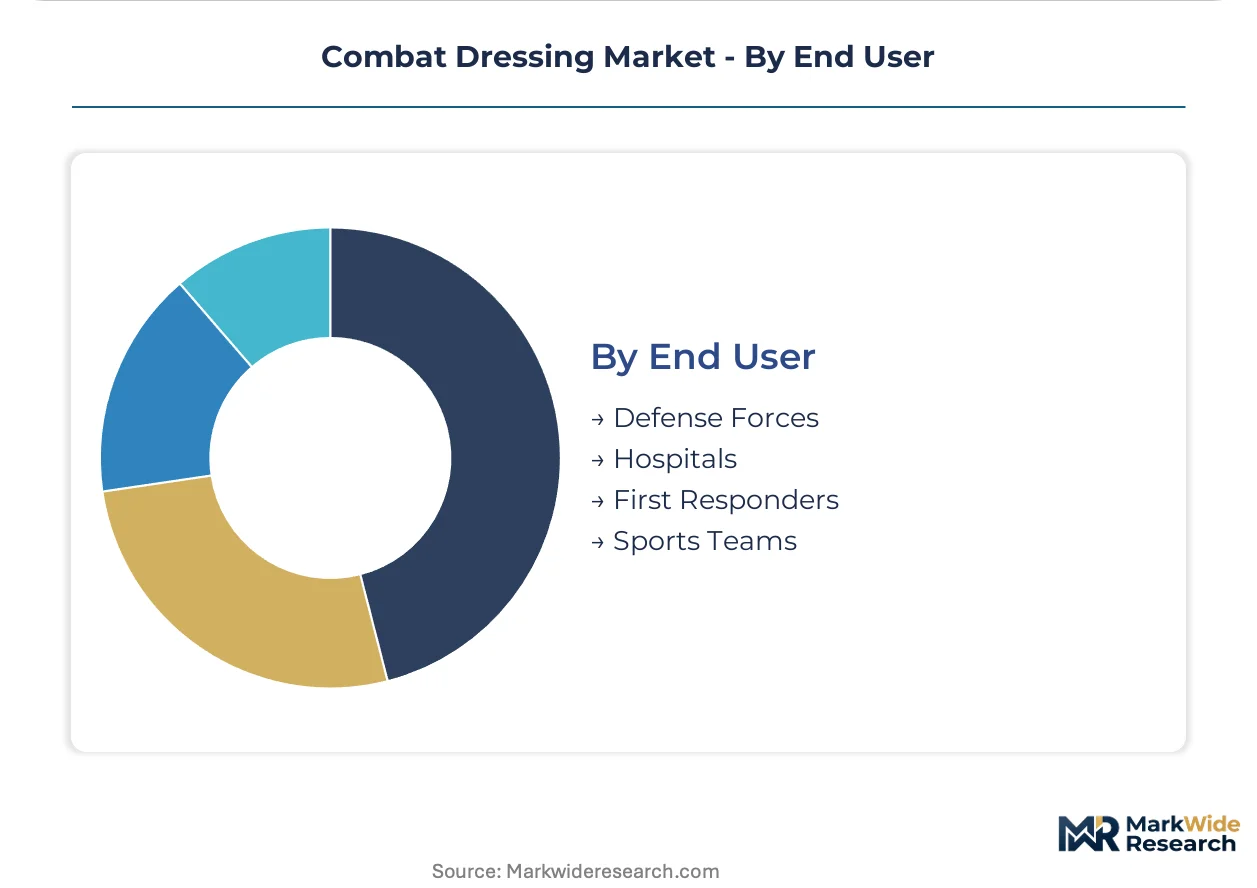
End User:
Certification requirements and procurement authority concentration determine competitive access.
- Defense Forces:U.S. Department of Defense and NATO member state military medical logistics operations mandate dual-track FDA and military specification compliance. Contract visibility extends across multi-year defense appropriation cycles.
- First Responders:Fire departments, police tactical units, and civilian emergency medical technician programs are absorbing combat dressing protocols through certification curriculum updates.
- Hospitals:Surgical and emergency department procurement prioritizes reimbursement compatibility and supply chain integration with existing wound care formularies.
- Sports Teams:Professional athletic training staffs are field-testing military-grade trauma dressings for pitch-side hemorrhage control, creating demand for compact, rapid-deployment configurations.
Defense forces control specification authority. First responders are expanding most quickly as training capacity scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Combat dressing procurement patterns diverge sharply by geography. The United States concentrates hemostatic dressing deployment through defense logistics channels, while European markets emphasize CE-marked interoperability standards, and Asian procurement clusters around fishery-derived chitosan supply chains.
United States
U.S. Department of Defense medical logistics operations drive the largest single-country procurement volume through MIL-DTL-3643 specification contracts. FDA 510(k) clearance requirements for time-to-hemorrhage-control claims filter supplier eligibility. San Antonio's military medical complex anchors trauma protocol development and field testing for next-generation dressing configurations.
Germany
Bundeswehr medical service modernization programs are expanding advanced trauma dressing inventories under NATO standardization agreement STANAG 2122. EU MDR clinical evidence requirements for CE marking are elevating barrier-to-entry thresholds. Munich's medical technology cluster hosts regulatory affairs infrastructure serving cross-border defense procurement.
United Kingdom
UK Ministry of Defence joint medical command is updating battlefield casualty care protocols following recent operational experience. Medicines and Healthcare products Regulatory Agency (MHRA) post-Brexit regulatory alignment creates dual-track compliance considerations. Bristol's defense procurement hub manages multi-year trauma equipment contracts.
Israel
Israel Defense Forces combat medicine units field-test junctional hemorrhage control systems under operational conditions before NATO adoption. Ministry of Health medical device registration requirements emphasize biocompatibility documentation. Tel Aviv's defense technology corridor concentrates dressing innovation alongside trauma simulation training facilities.
Australia
Australian Defence Force health services are standardizing hemostatic dressing inventories through ADF Medical Equipment Catalogue updates. Therapeutic Goods Administration (TGA) conformity assessment pathways align with EU MDR evidence standards. Melbourne's defense medical research institute coordinates Pacific alliance trauma protocol harmonization.
Combat Dressing Market Competitive Environment
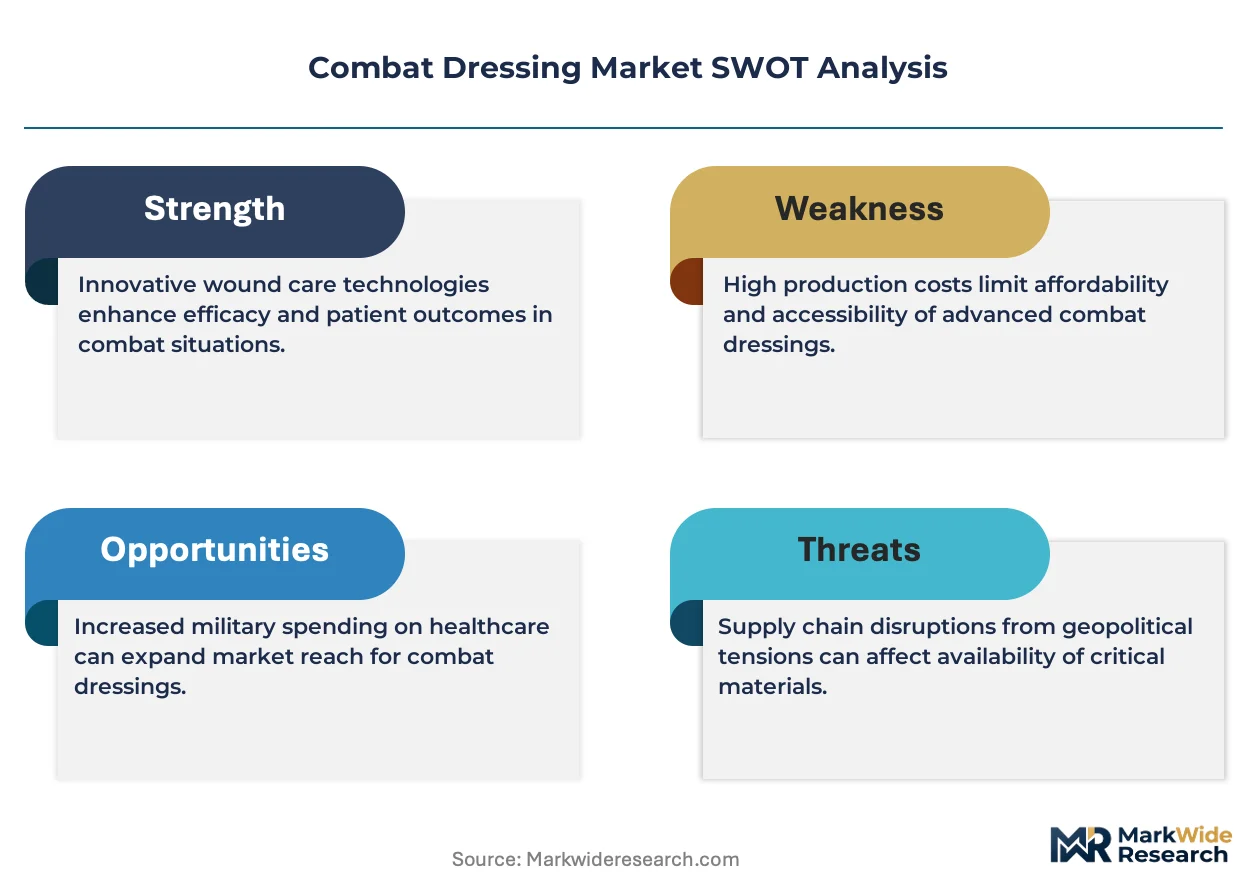
A small set of integrated leaders sits above a broader specialist tier in combat dressing supply. Three structural archetypes dominate: vertically integrated military contractors controlling distribution channels, hemostatic technology specialists commanding material science premiums, and diversified medical device conglomerates leveraging regulatory scale. Competitive moves concentrate on dual-track certification capacity building and military specification qualification testing.
Within the military contractor archetype, North American Rescue exemplifies channel-integrated positioning through U.S. defense logistics relationships. Z-Medica occupies a specialist tier position representing kaolin-based hemostatic formulation expertise. PerSys Medical anchors the junctional trauma system segment, reflecting integrated dressing-tourniquet hybrid development. These three entities collectively illustrate competitive positioning across technology specialization, distribution control, and protocol integration vectors.
| Leading Market Players |
|---|
| Z-Medica |
| PerSys Medical |
| North American Rescue |
| TyTek Medical |
| H&H Medical Corporation |
| First Care Products |
| Celox Medical |
| 3M |
| Bound Tree Medical |
| Others |
Value Chain & Pricing Dynamics
Multi-year defense logistics contracts lock in supply access and price visibility for combat dressing suppliers, insulating qualified vendors from spot market volatility while creating barriers for unqualified competitors seeking entry into U.S. Department of Defense procurement channels.
Pricing Analysis
Contract-based long-term offtake dominates combat dressing procurement, with MIL-DTL-3643 qualification serving as the primary price differentiation driver alongside FDA 510(k) clearance tier. Three-tier pricing structure across premium hemostatic, standard antimicrobial, and economy gauze levels reflects certification burden and performance claims. Pricing pressure stems from raw material concentration in Southeast Asian chitosan processing clusters, squeezing margins on marine-derived formulations. Defense forces show lowest price sensitivity due to specification mandates, while civilian first aid retail channels prioritize cost minimization over active clotting chemistry.
Supply Chain Analysis
Port congestion on Southeast Asian trade lanes elevates inbound logistics costs for medical-grade chitosan shipments destined for hemostatic dressing manufacturers. Supply concentrates in Thailand, Vietnam, and Indonesia for crustacean-derived biopolymers, while cotton substrates source from India and the United States. Raw material dependencies include marine chitosan, pharmaceutical-grade kaolin, and woven cellulose. Single-source vulnerability in Southeast Asian fishery processing exposes cost volatility to seasonal yield fluctuations. Distribution runs through military medical logistics depots and defense contractor channels for qualified suppliers, with civilian emergency medical services procurement consolidating around established vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combat dressing procurement is approaching a platform-economics inflection as NATO standardization agreements and FDA-EU MDR regulatory convergence reshape vendor interoperability requirements and consolidate procurement authority around protocol-integrated suppliers.
For Market Incumbents: Fortify dual-track certification infrastructure against emerging entrants lacking FDA 510(k) and military specification compliance depth. Deepen backward integration into chitosan raw material sourcing to offset Southeast Asian supply volatility. Secure long-term offtake agreements with U.S. defense logistics before EU MDR transition windows close vendor pools. For New Entrants and Emerging Players: Differentiate on junctional hemorrhage applications where tourniquet-dressing hybrid systems lack established incumbents. Target sports medicine channels adopting military-grade trauma protocols for pitch-side deployment. Pursue municipal emergency medical services procurement offices consolidating vendor lists around hemostatic alternatives. For Investors and Strategic Acquirers: Kaolin-based hemostatic technology specialists with FDA-cleared time-to-hemorrhage-control claims represent priority acquisition targets given regulatory barrier sustainability. Long-term viability hinges on NATO interoperability certification depth rather than civilian retail scale. Monitor EU MDR post-market surveillance data submissions as inflection indicator for European shelf access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Track Certification Investment | Simultaneous FDA 510(k) and MIL-DTL-3643 qualification locks in defense procurement eligibility against marginal competitors. |
| Chitosan Supply Agreement | Long-term offtake with Southeast Asian crustacean processors insulates manufacturing costs from fishery yield volatility. |
| Junctional Trauma System Development | Integrated dressing-tourniquet hybrids address axillary and inguinal wound sites lacking conventional tourniquet compatibility. |
| EU MDR Dossier Preparation | Post-market surveillance data and biocompatibility documentation secure CE marking ahead of competitor clearance windows. |
| Tactical Medicine Training Partnership | Certification program integration embeds product protocols into civilian first responder curricula and standard inventories. |
Study Parameters
Initial hypotheses were tested against primary input from combat medicine program directors, defense logistics procurement officers, biomedical engineers at military medical research institutes, and regulatory affairs specialists at hemostatic dressing manufacturers and refined through secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation, NATO standardization agreement texts, and U.S. Department of Defense contract award records. Bottom-up demand modeling across end-user segments triangulated with top-down market sizing from defense appropriation data and emergency medical services procurement disclosures.
Variance decomposition across product type, application, material chemistry, and end-user certification requirements structured the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling calibrated to defense procurement cycle visibility and civilian training program adoption curves. Forecast inputs included military specification qualification timelines, EU MDR clinical evidence requirements, and chitosan supply chain yield projections.
Material uncertainties — regulatory timeline extensions for novel hemostatic claims, NATO interoperability protocol revisions, and Southeast Asian fishery output disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification pathway efficiency and defense budget continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cryotubes Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
Casting and Splinting Market
Medical Supplies
Luer Plug Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Finger Splint Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Europe Hospital Supplies Market
Medical Supplies
Ostomy Drainage Bags Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Trauma Products Market