
 US Urgent Care Center Software Market | 2026-2036
US Urgent Care Center Software Market Size, Share, and Industry Trends Forecast 2026-2036
US Urgent Care Center Software Market Insights
HIPAA is decoupling legacy system viability from new market access, forcing urgent care operators to replace non-compliant infrastructure. Athenahealth leverages cloud-native architecture to sustain multi-state clinic networks. eClinicalWorks anchors its position through integrated practice management tools. Experity differentiates via purpose-built urgent care workflows.
Urgent care center software encompasses clinical documentation, scheduling, billing, and patient engagement platforms engineered for episodic, walk-in care delivery. Systems typically integrate HL7 FHIR APIs for health information exchange and support real-time eligibility verification for same-day encounters. Cloud-based deployment leads the product type landscape due to lower capital requirements and faster implementation cycles. Telemedicine functionality represents the fastest-growing segment as hybrid care models expand. Fully integrated solutions command premium positioning by unifying EHR, billing, and practice management in single platforms.
FDA oversight of clinical decision support tools intersects with ONC certification requirements for interoperability under the 21st Century Cures Act. CMS reimbursement policies directly shape software purchasing timelines for Medicare-accepting urgent care operators. Stakeholders must monitor evolving information blocking penalties and state-level telehealth parity laws to anticipate compliance-driven replacement cycles.
Market Dynamics
The 21st Century Cures Act's interoperability mandates are forcing urgent care operators to replace legacy EHR systems with FHIR-compliant platforms, compressing replacement cycles and reshaping vendor competitive positions.
Growth Catalysts
- Texas and Florida clinic expansion:Multi-site urgent care chains in these states are deploying integrated EHR-practice management suites across new locations, driving platform standardization demand.
- ONC certification requirements:Federal mandates for certified health IT are disqualifying non-compliant vendors from new procurement cycles, accelerating market consolidation toward qualified suppliers.
- Telemedicine integration:Hybrid care models combining virtual and in-person visits require software platforms with embedded video capabilities and synchronous documentation workflows.
Market Restraints
- Cloud migration costs:Capital-constrained independent urgent care centers face prohibitive upfront expenses for data migration and staff retraining when exiting on-premise systems.
- Vendor concentration risk:Dominance by a handful of national EHR platforms creates single-point-of-failure exposure for multi-state clinic networks dependent on unified data architectures.
- Interoperability implementation gaps:Incomplete HL7 FHIR adoption across hospital systems and payers forces urgent care operators to maintain costly custom interfaces.
Strategic Opportunities
- Southeast corridor penetration:Underserved markets in Georgia, Alabama, and Tennessee present whitespace for purpose-built urgent care software targeting mid-sized regional chains.
- Information blocking penalty enforcement:CMS and ONC monetary penalties for data blocking create compliance-driven demand for certified interoperability modules.
- AI-assisted documentation convergence:Integration of ambient clinical intelligence with EHR workflows promises to reduce provider documentation burden in high-volume episodic care settings.
Industry Challenges
- Health informatics talent scarcity:Urgent care operators struggle to recruit analysts capable of configuring FHIR APIs and managing health information exchange protocols.
- Legacy system integration complexity:Proprietary data formats in aging practice management systems resist clean extraction, inflating implementation timelines and costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Urgent Care Center Software Market |
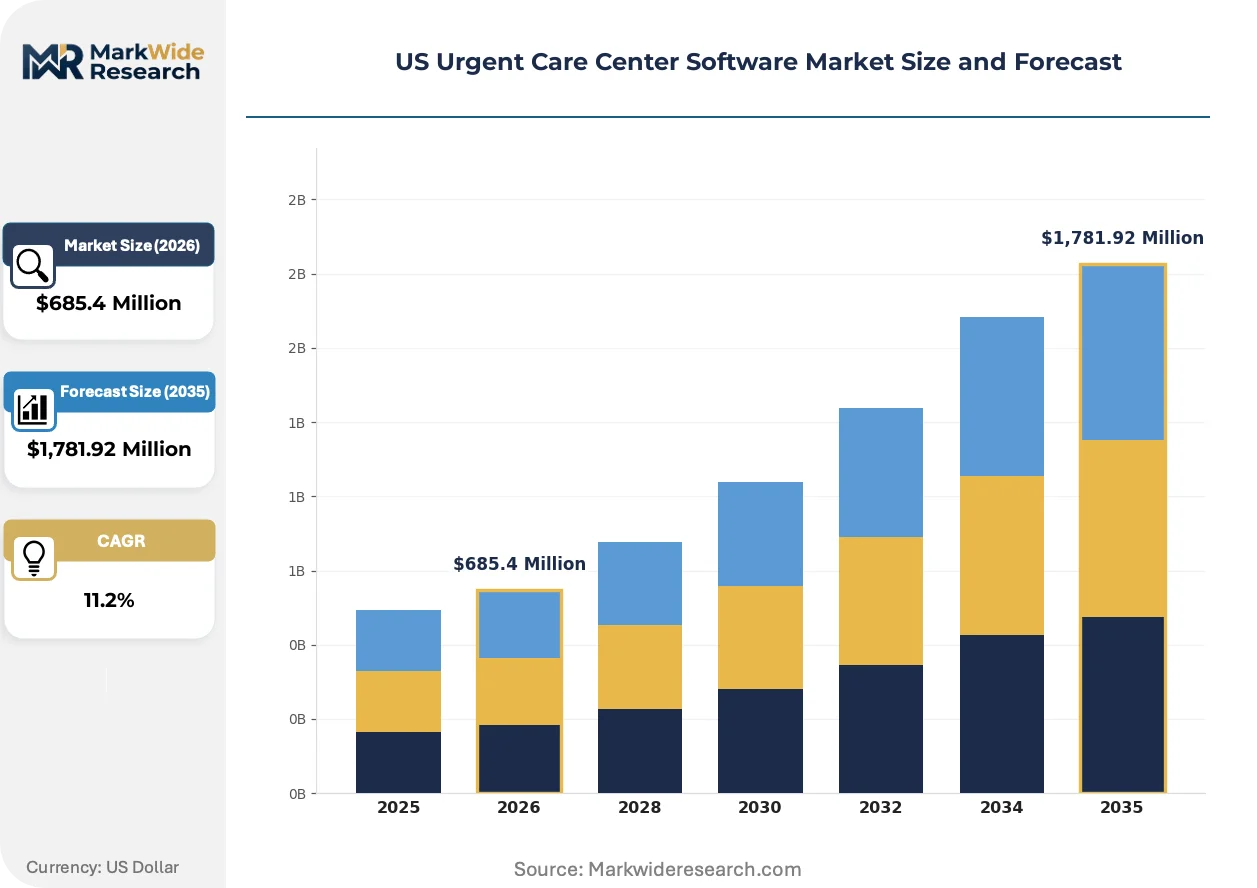
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,781.92 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EHR, Practice Management, Billing, Telemedicine End User: Clinics, Hospitals, Independent Providers, Healthcare Networks Deployment: Cloud-based, On-premise, Hybrid, Mobile Integration Level: Stand-alone, Fully Integrated, Partially Integrated, API-enabled |
| Companies Covered | Athenahealth, eClinicalWorks, AdvancedMD, Inc., CareCloud, Inc., Veradigm LLC, DrChrono Inc., NXGN Management, LLC, Experity, Inc., PrognoCIS EHR (Bizmatics, Inc.), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Urgent Care Center Software Market Trends and Innovations
Software architecture decisions are increasingly tied to Medicare reimbursement eligibility and state-level telehealth parity laws, forcing urgent care operators to prioritize platforms with embedded compliance automation.
Cloud-native EHR platforms with modular microservices architecture are expanding into multi-state urgent care networks by enabling rapid deployment across distributed clinic footprints without on-site server infrastructure. Regional chains in Texas and Florida are adopting these systems to standardize workflows while preserving local customization. The shift is compressing implementation timelines from months to weeks and lowering total cost of ownership for operators managing twenty-plus locations.
CMS information blocking rules under the 21st Century Cures Act are mandating patient data access through standardized APIs, compelling software vendors to expose clinical records to third-party applications. Urgent care operators accepting Medicare reimbursement must demonstrate compliance or face exclusion from federal payment programs. The Southeast market shows the most active vendor response, with platforms racing to certify patient access capabilities ahead of enforcement deadlines.
Subscription-based pricing for integrated EHR-practice management suites is displacing perpetual license models among mid-sized urgent care chains seeking predictable operating expenditures. Buyers in Florida and Texas are negotiating multi-year agreements that bundle telemedicine modules and revenue cycle management tools. The preference for operational expense treatment over capital investment is most pronounced among private equity-backed clinic networks optimizing cash flow metrics.
US Urgent Care Center Software Market Segmentation
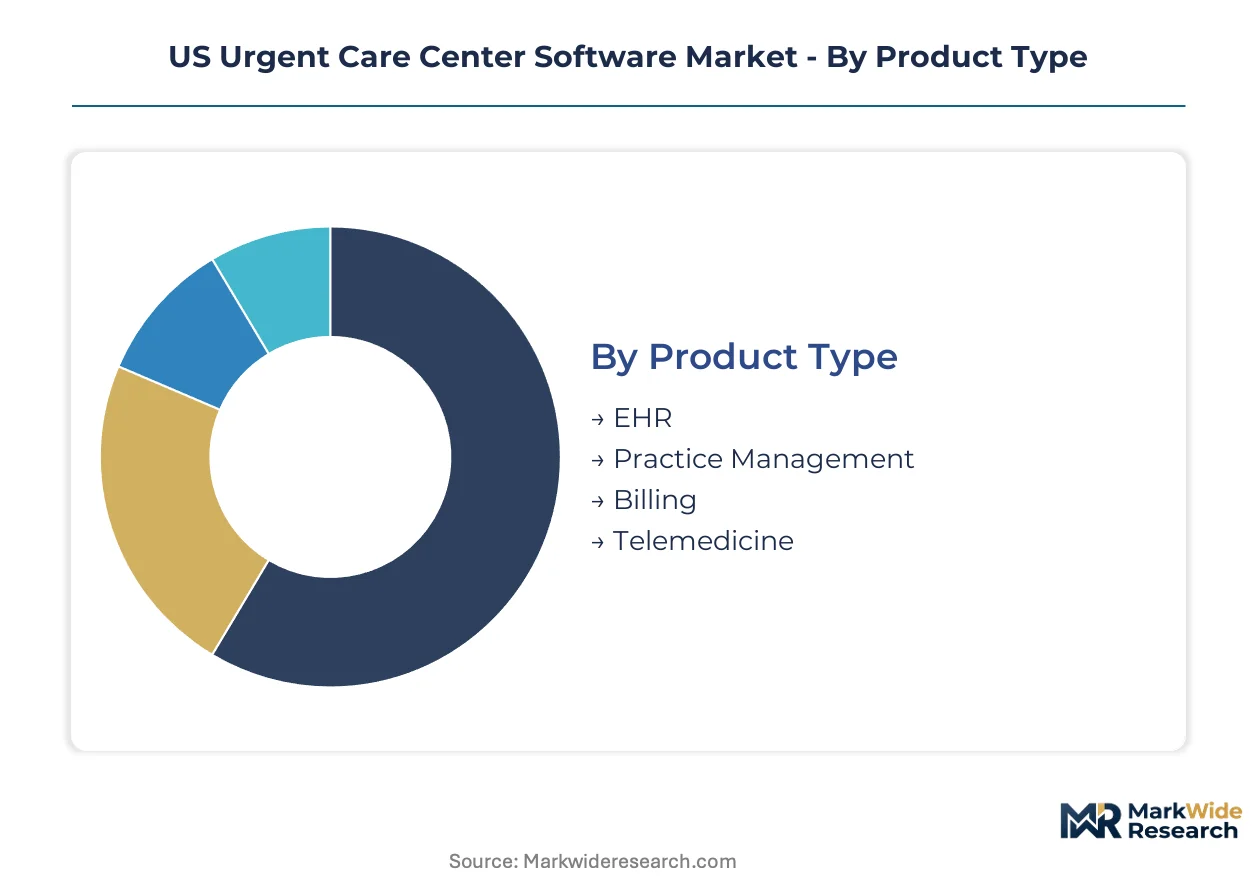
Urgent care operators select software configurations based on clinic scale, regulatory compliance timelines, and interoperability mandates. Segmentation reveals how replacement cycles concentrate demand across specific product architectures and deployment models.
Product Type:
Upgrade cycles vary sharply by product type, with compliance deadlines forcing staggered procurement timelines across clinical documentation, revenue cycle, and virtual care platforms.
- EHR:Core clinical documentation systems with HL7 FHIR APIs for interoperability exchange. Texas and Florida multi-site chains are replacing legacy systems ahead of ONC certification deadlines, compressing implementation windows.
- Practice Management:Scheduling, registration, and workflow orchestration modules. Southeast regional operators prioritize these for standardization across twenty-plus location footprints.
- Billing:Revenue cycle management with real-time eligibility verification and claim scrubbing. Same-day encounter volume demands automated coding assistance.
- Telemedicine:Embedded video platforms with synchronous documentation. Hybrid care models in Medicare-accepting clinics drive fastest adoption curves.
EHR sits at the top of the volume ranking, with Telemedicine climbing the fastest.
End User:
Customer type determines procurement sophistication, with private equity-backed networks leveraging scale advantages unavailable to independent operators.
- Clinics:Dedicated urgent care facilities with episodic care workflows. Multi-site chains in Texas and Florida deploy standardized suites across new locations.
- Hospitals:Health system-affiliated urgent care units requiring enterprise EHR integration. These buyers mandate bi-directional data exchange with acute care records.
- Independent Providers:Single or small-group operators facing capital constraints. Cloud subscription models reduce upfront migration costs for this segment.
- Healthcare Networks:Regional integrated delivery networks with unified compliance requirements. These buyers negotiate multi-year bundled agreements.
Clinics command the largest procurement volumes, while Healthcare Networks are gaining share fastest through standardization mandates.
Deployment:
Capital structure preferences are shifting expenditure classification, with operational expense treatment displacing capital investment for growth-stage operators.
- Cloud-based:SaaS delivery with remote server infrastructure and automatic updates. Private equity-backed chains favor predictable subscription expenditures.
- On-premise:Local server installations with full data control. Regulatory-sensitive operators in state Medicaid environments retain this model.
- Hybrid:Mixed architecture with sensitive data on-site and analytics in cloud. Transitional configurations for mid-market migration paths.
- Mobile:Tablet and smartphone-optimized interfaces for bedside documentation. Provider workflow efficiency drives adoption in high-volume settings.
Cloud-based deployment leads volume rankings, with Hybrid configurations expanding most quickly among mid-sized chains.
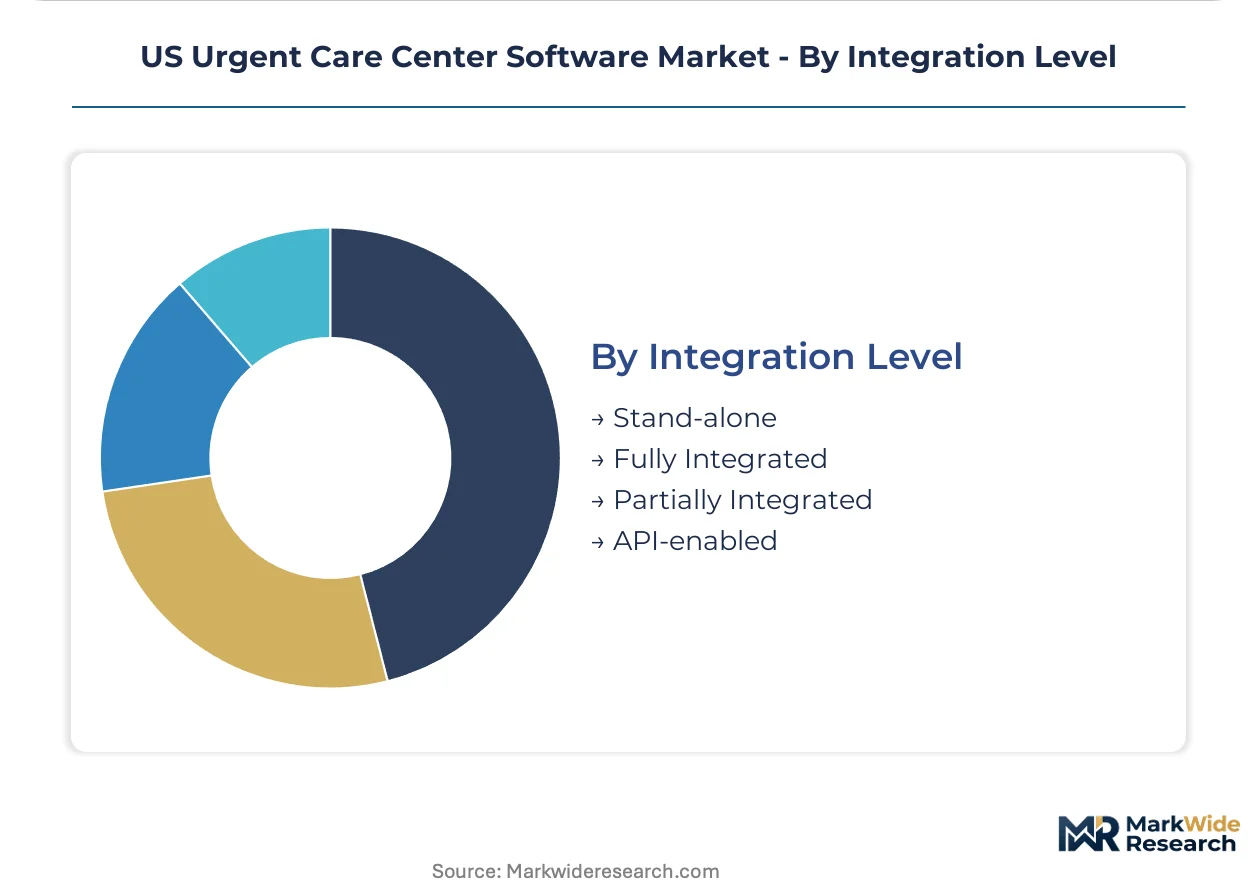
Integration Level:
Interoperability mandates under the 21st Century Cures Act are disqualifying non-certified configurations from federal reimbursement eligibility.
- Stand-alone:Single-function systems without external connectivity. Independent operators with limited IT resources retain these for cost containment.
- Fully Integrated:Unified EHR-practice management-billing platforms with single database architecture. Southeast chains standardize on these for workflow consistency.
- Partially Integrated:Selective module connections with custom interface maintenance. Legacy system retention creates ongoing technical debt.
- API-enabled:Modular platforms with standardized third-party connectivity. CMS information blocking rules require patient access capabilities.
Fully Integrated solutions dominate current procurement volumes, with API-enabled platforms showing steepest expansion trajectory ahead of enforcement deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health informatics talent clusters in Texas and Florida anchor urgent care software deployment momentum, with multi-site clinic operators driving standardization demand across the Southeast corridor.
Texas
Private equity-backed clinic networks in Dallas-Fort Worth and Houston are deploying cloud-native EHR suites across twenty-plus location footprints. HIPAA compliance mandates from HHS accelerate legacy system replacement cycles. Austin's health tech corridor hosts vendor implementation teams serving statewide rollouts.
Florida
Medicare-accepting urgent care chains in Miami-Dade and Tampa Bay prioritize telemedicine-embedded platforms for hybrid care models. ONC certification requirements under the 21st Century Cures Act disqualify non-compliant vendors from procurement cycles. Orlando's healthcare IT cluster supports rapid deployment timelines for expanding operators.
Georgia
Regional chains in Atlanta's metropolitan area are adopting fully integrated practice management solutions to unify billing workflows across acquired locations. CMS information blocking penalties create compliance-driven demand for FHIR-certified platforms. The city's health informatics workforce supports API configuration for health information exchange.
Tennessee
Mid-sized urgent care operators in Nashville and Memphis are migrating from on-premise systems to subscription-based cloud deployments. State-level telehealth parity laws shape platform selection criteria for virtual visit capabilities. Nashville's healthcare administration talent pool reduces implementation staffing constraints.
Alabama
Independent clinic operators in Birmingham and Mobile face capital constraints delaying cloud migration from aging practice management systems. Federal interoperability mandates compress replacement timelines despite budget limitations. Regional health networks are consolidating software procurement to achieve vendor scale advantages.
US Urgent Care Center Software Market Competitive Landscape
The competitive structure tilts toward cloud-native specialists with urgent care-specific workflow expertise. National EHR platforms with multi-state deployment capabilities command premium positioning among private equity-backed chains. Three archetypes dominate: legacy EHR vendors pivoting to urgent care modules, purpose-built urgent care specialists, and cloud-native generalists with healthcare verticalization. Consolidation accelerates through strategic acquisitions of regional practice management vendors and technology licensing partnerships with telemedicine platform providers.
Within the purpose-built urgent care tier, Experity and Athenahealth exemplify contrasting architectural philosophies—one anchored in episodic care workflow specialization, the other in multi-specialty cloud infrastructure scale. eClinicalWorks occupies a position bridging integrated practice management depth with ambulatory care breadth. These three entities represent the competitive tension between vertical specificity and horizontal platform extensibility that shapes procurement decisions among Southeast clinic operators.
| Leading Market Players |
|---|
| Athenahealth |
| eClinicalWorks |
| AdvancedMD, Inc. |
| CareCloud, Inc. |
| Veradigm LLC |
| DrChrono Inc. |
| NXGN Management, LLC |
| Experity, Inc. |
| PrognoCIS EHR (Bizmatics, Inc.) |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure cost indices from hyperscale providers cascade through urgent care software supply chains, compressing margins for on-premise vendors while enabling SaaS players to sustain subscription tiers across independent clinics and private equity-backed networks.
Pricing Analysis
Bundled versus unbundled service configurations split the market between fully integrated EHR-practice management-billing suites and modular point solutions. Subscription-based SaaS tiers dominate, with price differentiation resting on ONC certification status and telemedicine module inclusion. Pricing pressure stems from cloud-native entrants undercutting legacy license models. Independent providers exhibit highest price sensitivity, while multi-state chains prioritize total cost of ownership over per-seat rates.
Supply Chain Analysis
Regional distribution centers in Texas and Florida anchor hub-and-spoke deployment patterns for implementation teams serving Southeast clinic networks. Software development concentrates in the US, with cloud infrastructure sourcing from domestic hyperscale facilities. Supply chain risk centers on single-source vulnerability for FHIR certification consulting. Distribution runs through direct vendor sales organizations and value-added resellers targeting mid-market operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Texas and Florida present a geographic-arbitrage opportunity where lower cloud infrastructure costs and concentrated health informatics talent reduce implementation expenses versus Northeast markets facing scarcer technical staffing.
For Market Incumbents: Lock in multi-year subscription agreements with private equity-backed chains before ONC certification deadlines force vendor switches. Deepen API development partnerships with telemedicine platforms to neutralize ambient clinical intelligence entrants. Prioritize Southeast corridor implementation capacity to capture replacement cycle demand. For New Entrants and Emerging Players: Capture whitespace among Alabama and Tennessee independent clinics delaying cloud migration due to capital constraints. Alabama's underserved mid-sized operators represent the most penetrable segment. Lead with hybrid deployment options that preserve on-premise billing data while shifting clinical documentation to cloud. For Investors and Strategic Acquirers: Asymmetric upside sits with purpose-built urgent care specialists possessing FHIR-certified platforms and established Southeast customer bases. Five-to-ten year viability favors vendors with recurring revenue concentration above seventy percent. Monitor CMS information blocking penalty enforcement velocity as inflection indicator for compliance-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Certification Investment | ONC certification requirements under the 21st Century Cures Act disqualify non-compliant vendors from federal procurement cycles. |
| Telemedicine Platform Integration | Hybrid care models in Medicare-accepting clinics demand embedded video capabilities with synchronous documentation workflows. |
| Geographic Expansion into Southeast Corridor | Underserved markets in Georgia, Alabama, and Tennessee present whitespace for purpose-built urgent care software targeting regional chains. |
| Strategic Partnership with Cloud Hyperscalers | Cloud-native architecture enables rapid deployment across distributed clinic footprints without on-site server infrastructure. |
| Acquisition of Regional Practice Management Vendors | Consolidation accelerates market share capture among mid-sized operators seeking unified compliance and billing workflows. |
Research Methodology
Direct dialogue with urgent care operators, health system IT directors, EHR implementation specialists, and private equity clinic investors grounded qualitative findings, cross-referenced against CMS Medicare reimbursement data, ONC certification databases, state-level telehealth parity legislation, and SEC filings from publicly traded healthcare IT vendors. Bottom-up clinic deployment counts and top-down vendor revenue estimates were triangulated to establish market sizing.
Segment-level projections across the analysis window incorporate deployment model, clinic scale, integration complexity, and regional adoption patterns. CAGRs were derived from fitted growth curves incorporating HIPAA compliance deadline impacts, cloud infrastructure cost trajectories, and private equity clinic consolidation velocity. Model inputs include Medicare reimbursement policy shifts and state telehealth parity law enactment schedules.
Underlying measurement precision varies by segment; cloud-based and fully integrated configurations carry tighter precision than hybrid and stand-alone categories due to clearer vendor reporting boundaries. Forecasts reflect assumptions about enforcement timing for information blocking penalties and cloud migration adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Hospital Workforce Management Software Market
Healthcare IT
Healthcare IT Consulting Services Market
Healthcare IT
Technology Spending on Revenue Cycle Management Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Healthcare IT Outsourcing Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
High-Value Healthcare Asset Tracking and Recovery Platforms Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
Global Pharma Knowledge Management Software Market