
 Wound Irrigation Solutions Market | 2026-2036
Wound Irrigation Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Irrigation Solutions Market Analytics
Hospital supply chain procurement is fragmenting as group purchasing organizations lose leverage over specialized wound care categories. B. Braun Melsungen AG anchors its position through captive manufacturing of saline-based irrigation fluids. Zimmer Biomet differentiates via orthopedic-specific irrigation protocols tied to its implant systems. Stryker Corporation extends its reach through integrated operating room kits that bundle irrigation with power tools.
Wound irrigation solutions are sterile fluids or devices designed to cleanse wounds through mechanical debridement and antimicrobial action, typically delivered at pressures between 4 and 15 psi to remove debris without damaging granulation tissue. Their primary purpose is reducing surgical site infection rates and accelerating healing timelines across acute and chronic wound management. Automated systems command premium positioning due to precise pressure control and reduced nursing labor, while manual systems retain volume dominance in cost-sensitive clinics and emerging facilities. Burn care applications are gaining share fastest as advanced biologic dressings require standardized irrigation protocols to maintain graft viability.
The FDA governs device classification and antimicrobial claims under 510(k) and de novo pathways, while the EPA regulates environmental discharge limits for irrigation fluids containing cytotoxic agents. In Europe, the MDR and REACH frameworks impose stricter biocompatibility testing and chemical substance restrictions on reusable device materials. Stakeholders must monitor evolving pressure thresholds in clinical guidelines and anticipate reimbursement shifts tied to infection rate outcomes rather than procedural volume.
Market Dynamics
Hospital procurement departments are fragmenting away from group purchasing organizations as specialized wound care categories demand clinical specificity over volume leverage. This shift is compressing margins for undifferentiated saline suppliers while rewarding automated system manufacturers with direct contracting power.
Growth Catalysts
- Antimicrobial Formulation Advances:The FDA's streamlined 510(k) clearance pathway for antimicrobial wound wash products is accelerating product pipeline velocity for developers targeting surgical site infection prevention.
- Burn Care Protocol Standardization:Advanced biologic dressings requiring standardized irrigation to maintain graft viability are expanding addressable demand across specialized wound centers.
- Germany's SSI Prevention Mandates:Updated national surgical site infection protocols are compelling hospital system upgrades to pressurized irrigation infrastructure.
Market Restraints
- Saline Supply Concentration:Captive manufacturing of sterile saline by dominant device manufacturers limits third-party fluid suppliers from penetrating integrated kit offerings.
- Reusable Device Material Restrictions:Europe's REACH framework imposes escalating compliance costs on manufacturers of multi-use irrigation handpieces containing restricted chemical substances.
- Manual System Substitution:Cost-sensitive outpatient clinics retain preference for syringe-based irrigation, delaying automated system penetration in price-constrained settings.
Strategic Opportunities
- Japan's Aging Surgical Population:Demographic pressure on orthopedic and wound care volumes creates expansion potential for precision irrigation systems in tertiary hospitals.
- Home Care Channel Development:Direct-to-patient distribution models for chronic wound management are opening bypass routes around traditional hospital procurement.
- Power Tool Integration:Convergence between irrigation systems and surgical power platforms enables bundled positioning in operating room capital budgets.
Industry Challenges
- Biocompatibility Testing Backlogs:Europe's MDR transition has extended material certification timelines for reusable irrigation device components.
- Nursing Labor Optimization:Automated system adoption requires retraining clinical staff on pressure calibration protocols, creating implementation friction in understaffed facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Irrigation Solutions Market |
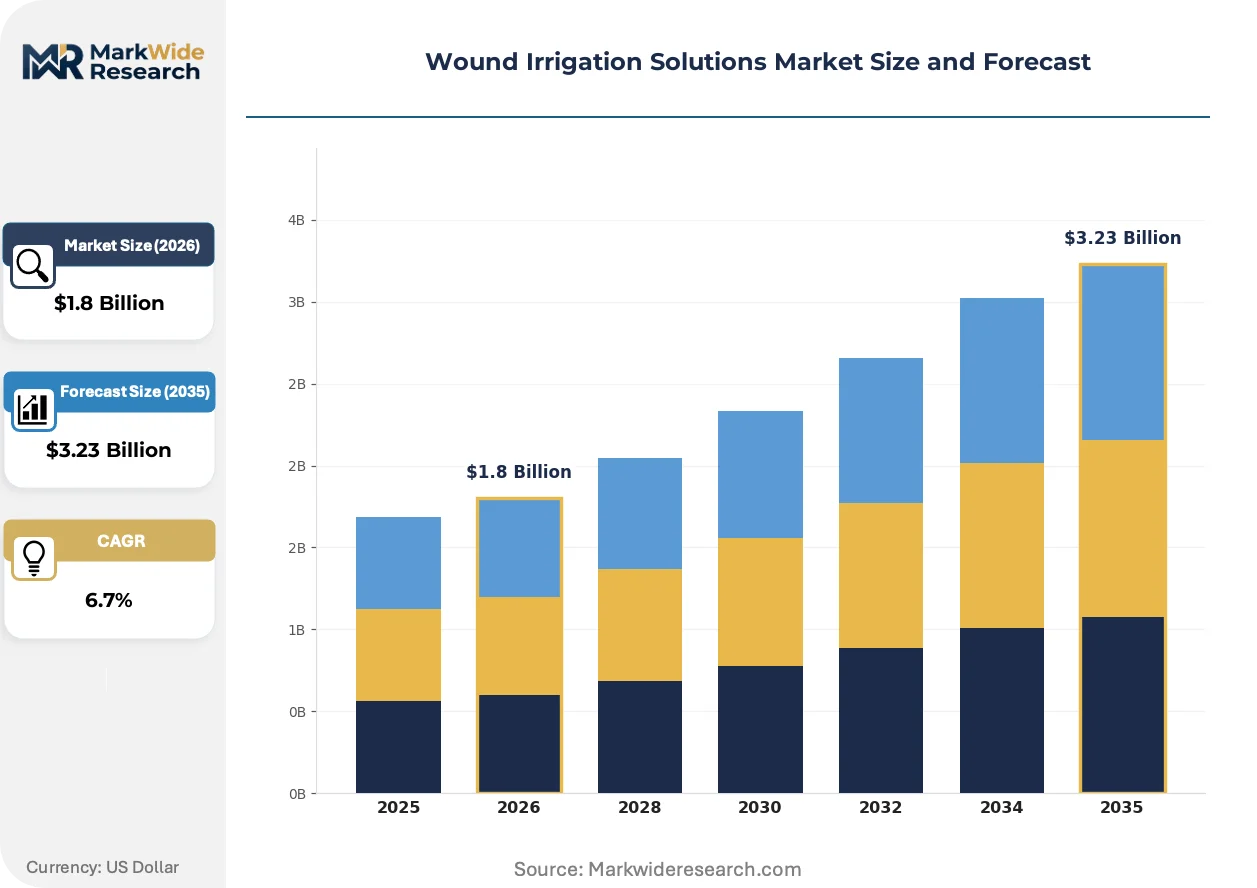
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Automated Systems, Disposable Devices, Reusable Devices Technology: Electrolytic, Non-Electrolytic, Thermal, Ultrasonic End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Application: Acute Wounds, Chronic Wounds, Surgical Wounds, Burn Care |
| Companies Covered | Zimmer Biomet, Westmed Inc., B. Braun Melsungen AG, Medtronic Plc, CooperSurgical Inc., ConvaTec Group Plc, Becton, Dickinson and Company, 3M Company, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Irrigation Solutions Market Evolving Landscape
Precision pressure control technology is rendering gravity-fed and manual irrigation methods structurally uncompetitive in acute care settings. Device manufacturers are embedding sensors and feedback mechanisms that transform irrigation from commodity fluid delivery into data-capturing clinical workflows.
Closed-loop pressure modulation systems is rendering obsolete conventional syringe-and-cannula techniques that rely on subjective operator force. Academic medical centers in the United States are adopting these platforms fastest, driven by liability concerns around tissue damage from excessive irrigation pressure. The technology is compressing acceptable performance thresholds downward, forcing manual system suppliers into purely cost-driven positioning.
The FDA's updated 510(k) antimicrobial claims pathway is accelerating evidentiary requirements for wound wash products seeking differentiated positioning. Manufacturers must now submit expanded biocompatibility data and clinical performance benchmarks to support bactericidal efficacy statements. Antimicrobial fluid developers targeting hospital formulary inclusion face the steepest compliance burden, while saline-based commodity suppliers remain unaffected.
Supply chain contracting is fragmenting as orthopedic service lines gain independent procurement authority over wound care categories. United States hospital systems are disintermediating group purchasing organizations for specialized irrigation protocols tied to implant procedures. This behavioral shift concentrates buying power within surgical departments rather than centralized materials management.
Wound Irrigation Solutions Market Segmentation
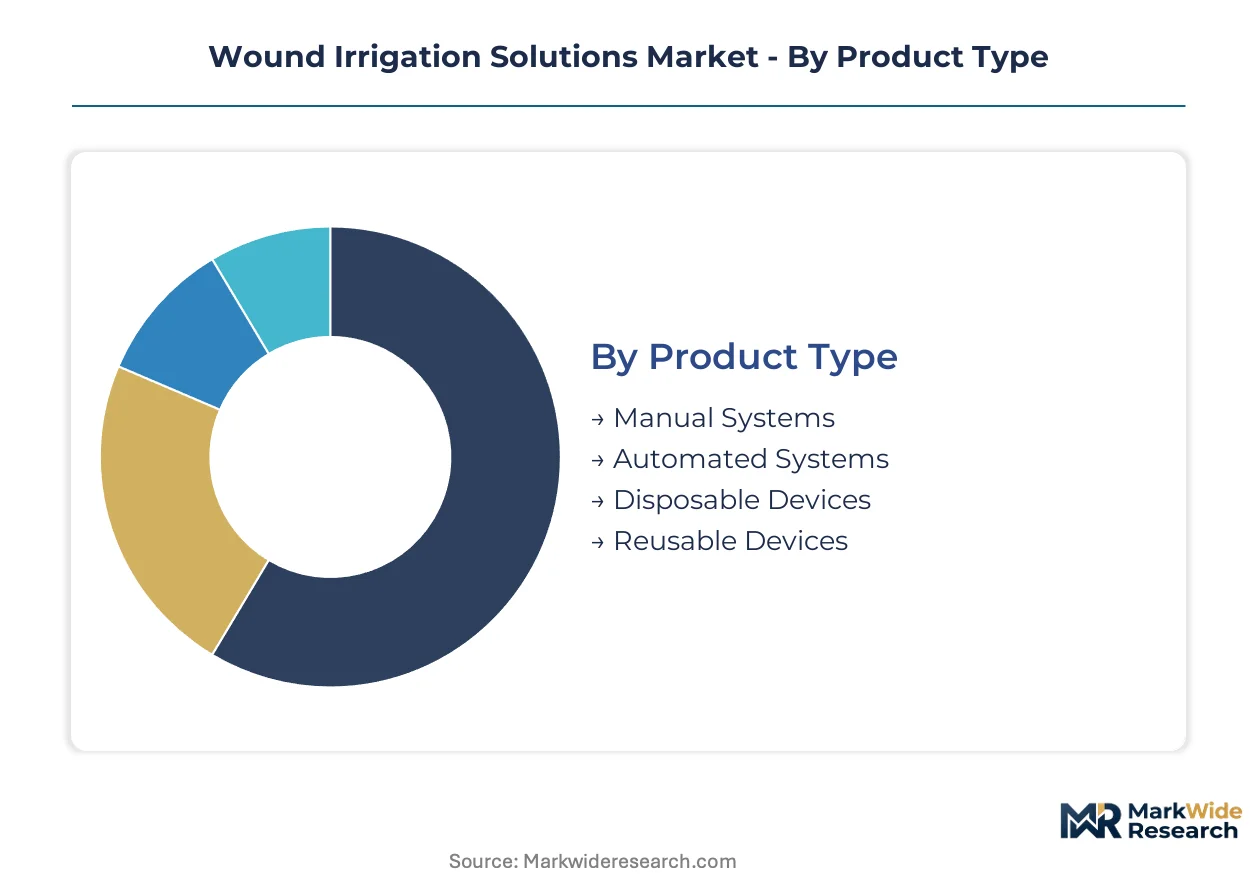
Wound irrigation solutions fragment across multiple technical and usage dimensions. Each segmentation axis reveals distinct procurement patterns and margin structures that shape competitive positioning.
Product Type:
Automated systems turn over fastest as hospitals refresh capital equipment on compressed cycles. Manual systems and disposables exhibit slower replacement rates tied to commodity supply contracts.
- Automated Systems:Closed-loop pressure modulation platforms deliver calibrated irrigation between 4 and 15 psi through sensor-feedback mechanisms. Demand concentrates in United States academic medical centers where liability exposure around tissue damage drives precision requirements. Germany's updated surgical site infection mandates are accelerating replacement of gravity-fed units in tertiary hospitals.
- Manual Systems:Syringe-and-cannula configurations rely on operator-applied force without pressure feedback. Cost-sensitive outpatient clinics in Japan retain preference for these units, delaying automated penetration where nursing labor costs remain constrained.
- Disposable Devices:Single-use irrigation handpieces and tubing sets designed for sterile field maintenance.
- Reusable Devices:Multi-cycle handpieces and pressure canisters subject to Europe's REACH material restrictions.
Manual systems dominate installed base. Automated systems are where expansion concentrates.
Technology:
Electrolytic platforms command premium pricing through antimicrobial efficacy claims. Non-electrolytic and thermal alternatives compete on capital cost and maintenance simplicity.
- Electrolytic:Systems generate antimicrobial solutions through electrochemical activation of saline, producing hypochlorous acid for bactericidal irrigation. United States hospitals pursuing surgical site infection reduction are prioritizing these platforms for orthopedic and implant procedures.
- Non-Electrolytic:Gravity-fed or mechanically pressurized delivery without electrochemical modification of irrigation fluid. Clinics in cost-constrained Japanese prefectures favor these systems where antimicrobial claims are not reimbursement-critical.
- Thermal:Heated irrigation delivery maintaining fluid temperature for patient comfort and tissue perfusion.
- Ultrasonic:Cavitation-based debridement systems combining irrigation with mechanical tissue disruption.
Non-electrolytic systems retain volume leadership. Electrolytic platforms are climbing the fastest.
End User:
Hospitals concentrate procurement authority for capital-intensive automated platforms. Home care and rehabilitation settings drive disposables volume through distributed chronic wound management.
- Hospitals:Tertiary surgical centers and academic medical facilities with dedicated orthopedic and burn service lines. United States hospital systems are disintermediating group purchasing organizations for specialized irrigation protocols, concentrating buying power within surgical departments.
- Clinics:Outpatient wound care and ambulatory surgical centers with constrained capital budgets.
- Home Care:Direct-to-patient distribution channels for chronic wound irrigation. Japan's aging demographic pressure is expanding addressable demand for portable systems in home settings.
- Rehabilitation Centers:Long-term care facilities managing pressure ulcers and post-surgical wound maintenance.
Hospitals anchor revenue concentration. Home care is gaining share fastest.
Application:
Burn care protocols standardization is accelerating equipment refresh cycles. Chronic wound applications exhibit slower technology adoption tied to reimbursement complexity.
- Burn Care:Standardized irrigation protocols maintaining graft viability for advanced biologic dressings. Specialized wound centers in Germany are upgrading pressurized infrastructure to meet national protocol requirements.
- Surgical Wounds:Intraoperative and postoperative irrigation for orthopedic, abdominal, and implant procedures. United States hospitals tie procurement to power tool integration and operating room kit bundling.
- Acute Wounds:Trauma and emergency department irrigation for debridement and contamination control.
- Chronic Wounds:Pressure ulcers, diabetic foot ulcers, and venous stasis wounds requiring extended irrigation protocols.
Surgical wounds represent the largest addressable base. Burn care shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways for antimicrobial wound wash products anchor demand concentration in the United States. Germany and Japan follow with surgical site infection protocol upgrades and aging surgical populations driving equipment refresh cycles.
United States
Academic medical centers prioritize closed-loop pressure modulation systems to mitigate liability exposure from tissue damage. FDA antimicrobial claims pathways now require expanded biocompatibility data for differentiated positioning. Boston and Cleveland surgical clusters drive fastest adoption of sensor-feedback irrigation platforms.
Germany
Updated national surgical site infection mandates compel tertiary hospitals to upgrade pressurized irrigation infrastructure. MDR and REACH frameworks impose stricter biocompatibility testing on reusable device materials. Berlin and Munich wound centers lead standardization for advanced biologic dressing protocols.
Japan
Demographic pressure on orthopedic volumes expands demand for precision irrigation in tertiary hospitals. METI standards guide medical device procurement for aging surgical populations. Osaka and Nagoya medical clusters concentrate capital equipment investment despite constrained nursing labor budgets.
United Kingdom
NHS procurement fragmentation enables direct contracting between surgical departments and automated system manufacturers. MHRA alignment with MDR extends certification timelines for reusable irrigation components. London and Manchester academic centers pioneer power tool integration in operating room kit bundling.
India
CDSCO medical device regulations tighten quality thresholds for imported irrigation systems while expanding domestic manufacturing incentives. Cost-sensitive outpatient clinics retain manual system preference. Delhi-NCR and Maharashtra surgical hubs concentrate demand for mid-tier pressurized equipment.
Wound Irrigation Solutions Market Competitive Landscape
Integrated device manufacturers and specialized fluid suppliers split the market into distinct procurement channels. Hospital supply chain fragmentation compresses margins for undifferentiated saline suppliers while rewarding automated system vendors with direct surgical department contracting authority. Three strategic archetypes dominate: captive saline manufacturers bundling fluids with capital equipment, orthopedic-integrated device companies tying irrigation to implant protocols, and standalone automated system specialists. Competitive moves concentrate on power tool convergence and home care channel development.
Among diversified medical technology conglomerates, Stryker Corporation and Zimmer Biomet occupy positions exemplifying orthopedic-integrated strategies, while B. Braun Melsungen AG anchors the captive fluid manufacturing archetype through in-house saline production. These three entities represent the structural tension between bundled kit offerings and specialized automated platforms.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Westmed Inc. |
| B. Braun Melsungen AG |
| Medtronic Plc |
| CooperSurgical Inc. |
| ConvaTec Group Plc |
| Becton, Dickinson and Company |
| 3M Company |
| Stryker Corporation |
| Others |
Value Network & Pricing Analysis
Regulatory chokepoints around antimicrobial fluid certifications determine both pricing tier spreads and supply chain shape in wound irrigation solutions. FDA 510(k) evidentiary requirements for bactericidal efficacy claims widen the gap between commodity saline suppliers and electrolytic platform manufacturers, compressing mid-tier positioning while rewarding vertically integrated device-fluid bundlers.
Pricing Analysis
Configured-to-order pricing for closed-loop pressure modulation systems commands substantial premiums over standard gravity-fed units. Three-tier pricing structure across premium sensor-feedback platforms, standard pressurized systems, and economy manual syringes reflects certification grade differentiation and after-sales calibration service bundling. Cost compression in economy tiers intensifies because outpatient clinics in Japan and India retain syringe-based preference. Price-sensitive buyers concentrate in ambulatory surgical centers and home care channels, while academic medical centers in the United States and Germany show minimal sensitivity to capital equipment premiums.
Supply Chain Analysis
Export-control regimes around sensor technology and electrochemical activation components limit flows of precision pressure modulation hardware from United States and German manufacturers to certain markets. Manufacturing concentrates in Germany, the United States, and Japan for automated platforms, while China and India anchor disposable tubing and cannula production. Raw material dependencies center on medical-grade stainless steel for handpieces, specialized polymers for single-use sets, and pharmaceutical-grade sodium chloride for saline formulations. Single-source vulnerability sits with electrochemical cell suppliers for electrolytic systems. Distribution runs through hospital procurement departments increasingly disintermediated from group purchasing organizations, with direct surgical department contracting gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital supply chain fragmentation creates multiple entry niches as specialized wound care categories escape volume-leverage purchasing. Orthopedic service line autonomy and burn center protocol standardization are generating demand pockets too specific for conglomerate bundlers to capture efficiently.
For Market Incumbents: Harden market position through captive saline manufacturing integration and exclusive hospital system partnerships for pressurized infrastructure. Automated system manufacturers face emerging pressure from power tool convergence plays by orthopedic device conglomerates. Priority levers include backward integration into electrochemical cell production and direct contracting authority with United States academic medical centers. For New Entrants and Emerging Players: Pursue home care channel development for chronic wound irrigation as the most penetrable white space, where direct-to-patient distribution bypasses hospital procurement concentration entirely. Japan's aging demographic pressure and portable system demand create favorable entry conditions. A software companion development angle linking irrigation data to wound healing analytics offers differentiation against capital equipment incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors automated system specialists with FDA antimicrobial claims clearance and established surgical department relationships. Long-term viability across the analysis window rests on regulatory moats around 510(k) pathways and MDR certification timelines. Acquisition targets should demonstrate installed base conversion capability and power tool integration potential. The signal to watch is reimbursement shifts tying irrigation procurement to surgical site infection rate outcomes rather than procedural volume.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Formulation Development | FDA 510(k) clearance for hypochlorous acid efficacy claims secures hospital formulary inclusion against saline commoditization. |
| Power Tool Integration Partnership | Operating room kit bundling with orthopedic implant systems captures capital budget authority from standalone fluid suppliers. |
| Home Care Channel Buildout | Direct-to-patient distribution for chronic wound management bypasses hospital procurement fragmentation entirely. |
| Closed-Loop Pressure Modulation Upgrade | Sensor-feedback platforms displace gravity-fed units in Germany's mandated SSI prevention infrastructure refresh. |
| Reimbursement Strategy Alignment | Outcome-based contracting tied to infection rate metrics positions automated systems for preferential procurement. |
Research Methodology
Operator-level perspectives from hospital procurement directors, orthopedic service line chiefs, burn center clinical coordinators, and biomedical engineering managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) clearance databases, hospital GPO contract filings, and MDR certification timelines from notified bodies. Bottom-up sizing triangulated against top-down macroeconomic healthcare expenditure models.
Scenario-bracketing framed analytical projections across the modeling period, with volume and value outputs reflecting segmentation by product type, technology platform, end-user channel, and application category. CAGRs derived from equipment replacement cycle analysis, protocol adoption curves, and reimbursement trajectory modeling. Industry-specific forecast inputs incorporated surgical site infection rate benchmarking data and antimicrobial claims regulatory pathway velocity.
Sensitivities concentrate around FDA evidentiary requirement changes, MDR transition timeline extensions, and reimbursement shifts toward outcome-based procurement. Forecasts reflect assumptions regarding hospital capital budget allocation patterns and nursing labor availability for system implementation training. Material shifts in antimicrobial regulatory pathways or surgical site infection prevention mandate scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Wound Closure Strips Market
Wound Care
Middle East and Africa Advanced Wound Care Market
Wound Care
Wound Debridement (Wound Cleaning) Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Pressure Ulcer Treatment Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Global Burn Care Market
Wound Care
Bioactive Wound Management Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Wound Healing Supplement Market
Wound Care
Wound Retractor Market
Wound Care
Italy Wound Care Market