
 US Transdermal Drug Delivery System Market | 2026-2036
US Transdermal Drug Delivery System Market Size, Share, and Industry Trends Forecast 2026-2036
US Transdermal Drug Delivery System Market Intelligence
Domestic patch manufacturing capacity is restructuring as contract developers expand specialized facilities in Minnesota and North Carolina. Novartis AG leverages its Sandoz generics division to sustain transdermal fentanyl patch supply across Veterans Affairs networks. Johnson & Johnson anchors consumer-facing analgesic patch distribution through retail pharmacy chains, while 3M Company competes on adhesive science leadership for extended-wear formulations.
A transdermal drug delivery system administers therapeutic agents through intact skin via diffusion across the stratum corneum, typically employing pressure-sensitive adhesives with drug-loaded reservoirs or matrix layers achieving zero-order release kinetics over 24–72 hours. Patches dominate volume due to chronic pain and hormone replacement indications, while microneedle arrays represent the fastest-expanding delivery mode as biologic compatibility improves. Home care settings capture margin pools through direct-to-patient subscription models, whereas hospital procurement concentrates on immediate-release iontophoretic systems for acute postoperative protocols.
FDA 505(b)(2) pathways and cGMP inspections shape product entry timelines, while USP-NF monographs on transdermal performance testing define dissolution and adhesion benchmarks. The Drug Enforcement Administration's quota system for Schedule II opioids constrains fentanyl patch production planning. Stakeholders must monitor CMS reimbursement parity decisions between institutional and home-administered transdermal therapies to anticipate demand migration patterns.
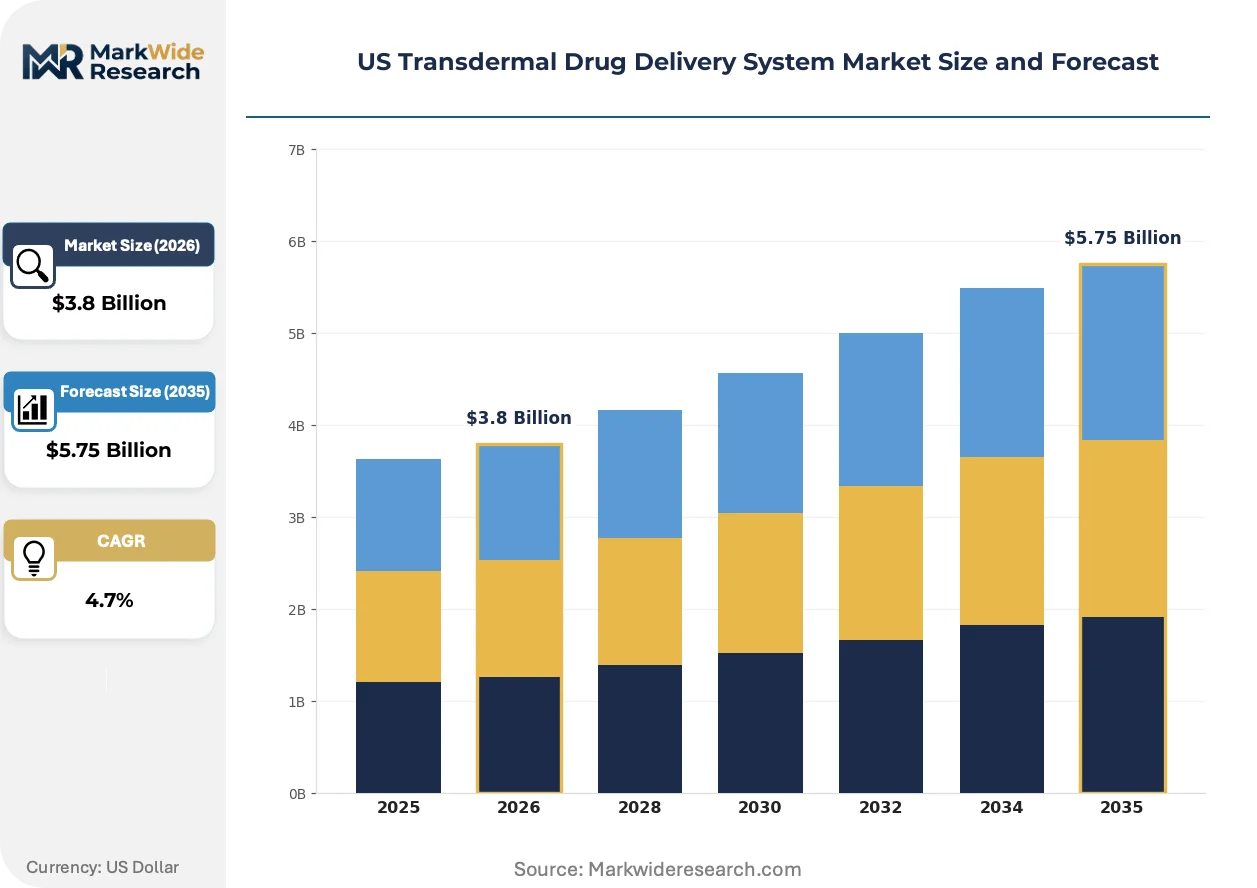
Market Dynamics
Medicare reimbursement parity decisions between institutional and home-administered transdermal therapies are redistributing demand toward ambulatory settings, forcing manufacturers to reconfigure distribution networks and patient-support infrastructure around direct-to-patient fulfillment models.
Growth Catalysts
- FDA 505(b)(2) Pathway:Abbreviated approval routes for generic transdermal products compress development timelines and lower capital barriers for specialty manufacturers entering chronic pain and hormone replacement segments.
- Home Care Sector Expansion:Medicare Advantage plans in Texas and Florida are expanding coverage for transdermal opioid and non-opioid patch programs, shifting volume from hospital outpatient departments to residential settings.
- Adhesive Science Advances:Pressure-sensitive adhesive formulations achieving 72-hour wear times improve patient compliance in Veterans Affairs networks and reduce nursing intervention frequency.
Market Restraints
- DEA Quota System:The Drug Enforcement Administration's Schedule II opioid allocation limits constrain fentanyl patch production planning and create supply uncertainty for pain management clinics.
- Stratum Corneum Barrier:The outermost skin layer restricts molecular penetration to compounds under 500 Daltons, excluding most biologics from passive transdermal delivery.
- Manufacturing Concentration:Contract development and manufacturing organizations cluster specialized transdermal facilities in Minnesota and North Carolina, creating geographic supply vulnerability.
Strategic Opportunities
- Microneedle Array Convergence:Dissolvable microneedles combined with biologic-compatible formulations open delivery pathways for peptides and vaccines previously excluded from transdermal routes.
- Subscription Distribution Models:Direct-to-patient pharmacy services in California and New York bypass wholesale channels and capture margin pools through automated refill programs for chronic conditions.
- Iontophoretic Acute Care:Electronic active-delivery systems enable rapid therapeutic onset for postoperative protocols in ambulatory surgical centers, differentiating from passive patch competition.
Industry Challenges
- cGMP Inspection Backlogs:FDA facility inspections for transdermal manufacturing sites create approval delays that extend product launch timelines by 12-18 months.
- Adhesion Testing Standardization:USP-NF monograph harmonization for peel strength and dissolution benchmarks remains incomplete, forcing redundant validation across contract laboratories.
- Formulation Scientist Scarcity:Specialized expertise in pressure-sensitive adhesive rheology and skin permeation modeling concentrates among retiring cohorts at legacy pharmaceutical firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Transdermal Drug Delivery System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patches, Gels, Films, Sprays Delivery Mode: Microneedles, Iontophoresis, Usual Patches, Sonophoresis Therapy Area: Hormonal Disorders, Pain Management, Cardiovascular, Neurology End User: Hospitals, Home Care, Clinics, Pharmacies |
| Companies Covered | Novartis AG, Boehringer Ingelheim, Johnson & Johnson, LTS Lohmann Therapie-Systeme AG, Hisamitsu Pharmaceutical Co., Inc., 3M Company, Teva Pharmaceutical Industries, Noven Pharmaceuticals, Viatris Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Transdermal Drug Delivery System Market Strategic Shifts & Innovations
Active electronic delivery mechanisms and biologic-compatible microneedle platforms are compressing the boundary between passive diffusion systems and invasive administration routes, while reimbursement policy accelerates demand migration toward patient-controlled home settings.
Microneedle arrays fabricated from dissolvable polymers or silicon are electrifying transdermal biologic delivery by creating microchannels through the stratum corneum without pain sensation. Academic medical centers in Massachusetts and Pennsylvania are piloting these devices for vaccine and peptide administration, compressing the historical exclusion of large-molecule drugs from dermal routes. The technology is enabling chronic disease management models that bypass injection anxiety and cold-chain logistics.
FDA draft guidance on transdermal and topical delivery systems issued in 2022 is tightening comparative bioavailability requirements for generic patch approvals. The policy elevates clinical endpoint study costs and extends development timelines for abbreviated new drug applications. Generic manufacturers are responding by prioritizing 505(b)(2) submissions for complex formulations with modified release kinetics rather than pure bioequivalence pathways.
Patient-administered therapy models are displacing clinic-based patch application across Medicare-covered populations. Home health agencies in Florida and Arizona are contracting directly with specialty pharmacies for automated delivery of fentanyl and hormone replacement patches, eliminating intermediary distributor margins. The behavioral shift concentrates procurement authority with pharmacy benefit managers who negotiate exclusive formulary placement.
US Transdermal Drug Delivery System Market Segmentation
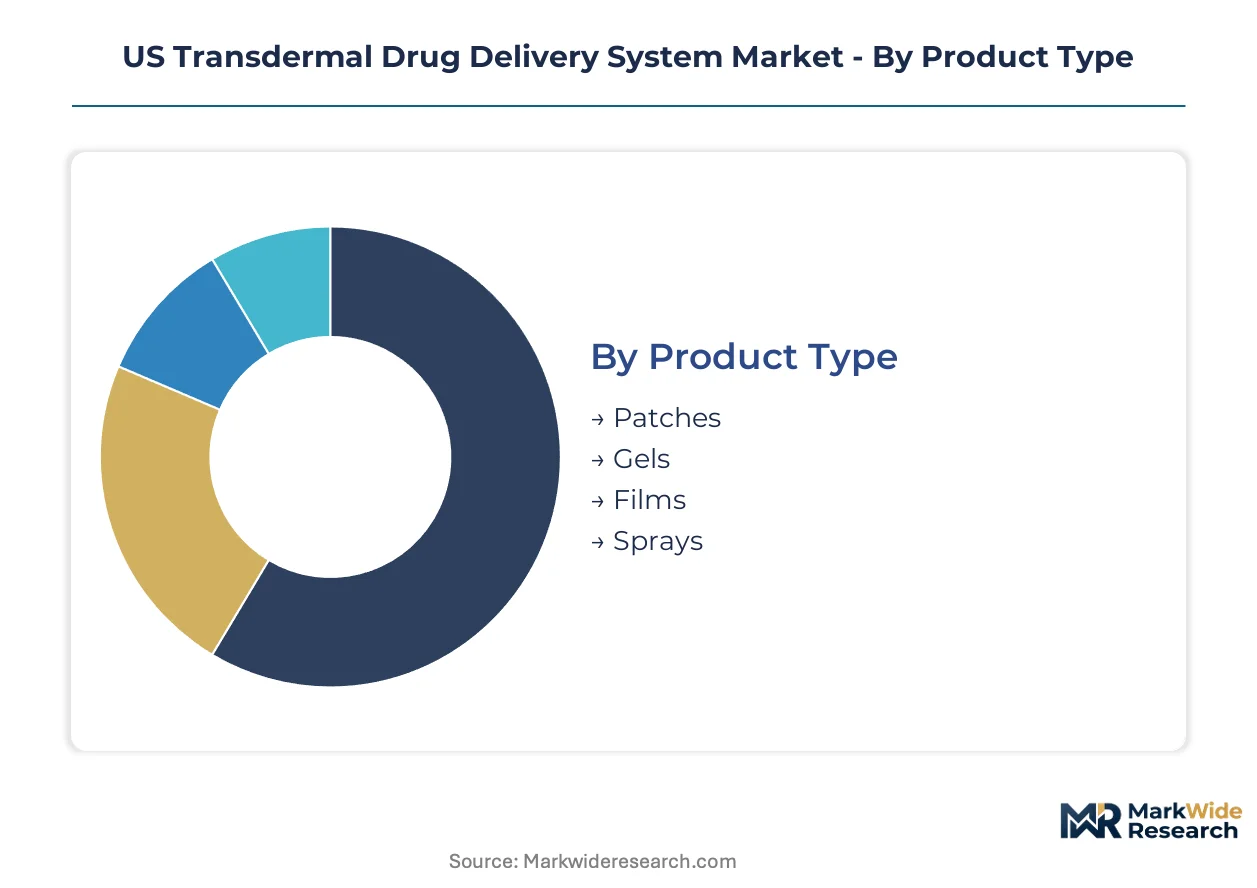
Transdermal system buyers prioritize distinct performance attributes across therapeutic contexts. Hospital procurement teams demand rapid-onset iontophoretic platforms, while Medicare-covered home patients value 72-hour adhesive durability and automated refill logistics.
Product Type:
Cost tier separates chronic-condition patients seeking multi-day wear from acute-care settings requiring rapid dose adjustment flexibility.
- Patches:Matrix or reservoir-layer constructions with pressure-sensitive adhesives achieve zero-order release over 24–72 hours. Veterans Affairs networks and Florida pain clinics concentrate procurement here, driven by Medicare reimbursement parity favoring ambulatory administration over institutional stays.
- Gels:Semisolid formulations enable dose titration through variable application area, suiting hormone replacement protocols requiring periodic adjustment. Texas endocrinology practices and California compounding pharmacies drive demand, constrained by stratum corneum penetration limits for molecules exceeding 500 Daltons.
- Films:Ultra-thin polymeric substrates dissolve or adhere for rapid buccal/transmucosal absorption in breakthrough pain scenarios.
- Sprays:Metered-dose aerosol systems deliver topical anesthetics and corticosteroids with immediate onset for dermatology and sports medicine applications.
Volume sits with Patches; growth tilts toward Gels as personalized hormone protocols expand.
Delivery Mode:
Application urgency distinguishes acute postoperative protocols from chronic disease management timelines.
- Microneedles:Dissolvable polymer or silicon arrays create microchannels through the stratum corneum without pain sensation, enabling biologic delivery previously excluded from dermal routes. Massachusetts and Pennsylvania academic medical centers pilot these for vaccines and peptides, climbing the fastest as chronic disease models bypass injection anxiety.
- Iontophoresis:Electronic active-delivery systems use mild electrical current to drive ionized drugs across skin barriers within minutes. Ambulatory surgical centers in Arizona and North Carolina adopt these for postoperative analgesia, differentiating from passive patch competition through rapid therapeutic onset.
- Usual Patches:Passive diffusion dominates Medicare-covered populations through established fentanyl and nicotine replacement supply chains.
- Sonophoresis:Low-frequency ultrasound temporarily disrupts stratum corneum lipid structure to enhance permeation for localized anti-inflammatory delivery.
Usual Patches hold installed base; steepest expansion trajectory belongs to Microneedles as biologic compatibility improves.
Therapy Area:
Patient volume concentration versus reimbursement rate determines manufacturer portfolio prioritization.
- Pain Management:Opioid and non-opioid patches for chronic and acute analgesia. Texas and Florida pain clinics expand programs here, constrained by DEA Schedule II quota limitations on fentanyl production planning.
- Hormonal Disorders:Estrogen, testosterone, and contraceptive delivery through skin for steady-state hormone levels. Home care subscription models in California and New York capture margin pools through automated refill programs.
- Cardiovascular:Nitroglycerin patches for angina prophylaxis maintain steady demand through hospital formularies and emergency department protocols.
- Neurology:Rivastigmine and rotigotine patches for Parkinson's and Alzheimer's symptom management serve aging populations in Florida and Arizona retirement corridors.
Pain Management commands volume share; Hormonal Disorders gain share fastest through direct-to-patient pharmacy bypass of wholesale channels.
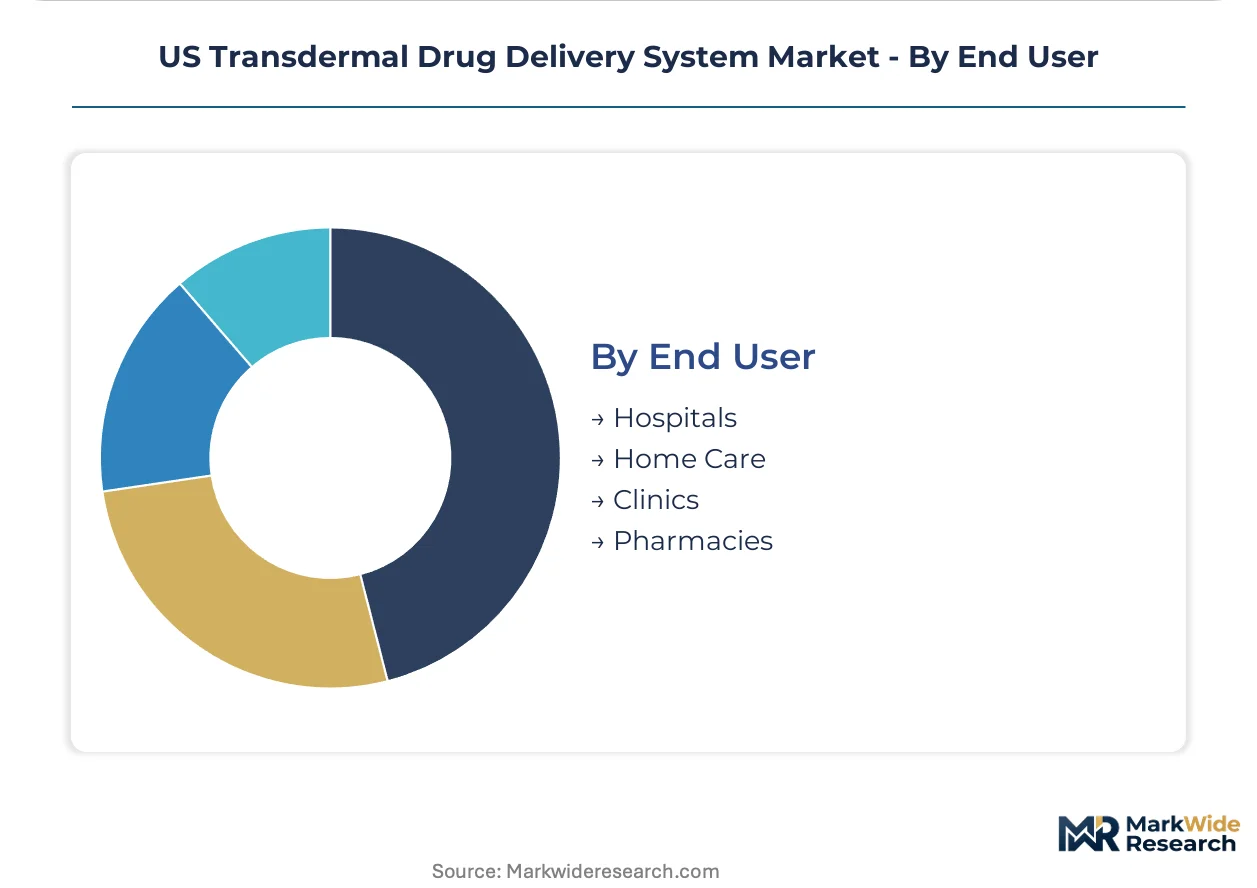
End User:
Procurement authority and margin capture mechanism separate institutional buyers from patient-directed fulfillment.
- Home Care:Patient-administered therapy with automated delivery from specialty pharmacies. Medicare Advantage plans in Texas and Florida drive volume migration here, eliminating intermediary distributor margins through direct contracting.
- Hospitals:Immediate-release iontophoretic systems and acute pain patches for postoperative and emergency protocols. Formulary committees concentrate procurement authority, though reimbursement shifts erode volume share.
- Clinics:Pain management and endocrinology practices in high-Medicare-density states anchor transdermal program expansion.
- Pharmacies:Retail chains and specialty mail-order services capture subscription revenue through chronic condition refill automation.
Hospitals retain acute-case volume; expansion concentrates in Home Care as CMS reimbursement parity decisions redistribute demand toward residential settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pressure-sensitive adhesive feedstock production concentrates in Minnesota and North Carolina, anchoring domestic patch manufacturing capacity for Veterans Affairs networks and Medicare-covered populations across the United States.
Texas
Pain management clinics in Houston and Dallas expand transdermal opioid and non-opioid patch programs for chronic conditions. DEA Schedule II quota allocations constrain fentanyl production planning statewide. The Texas Medical Center anchors clinical trial recruitment for extended-wear adhesive formulations.
Florida
Medicare Advantage plans drive volume migration toward home-administered therapy models in Miami and Tampa retirement corridors. CMS reimbursement parity decisions redistribute demand from hospital outpatient departments to residential settings. Specialty pharmacies in Orlando contract directly with home health agencies for automated patch delivery.
California
Direct-to-patient subscription models capture margin pools through automated refill programs for hormone replacement therapies in Los Angeles and San Francisco. FDA 505(b)(2) abbreviated approval pathways streamline entry for generic transdermal products developed by Bay Area contract research organizations. Silicon Valley biotech clusters pilot microneedle arrays for vaccine administration.
Massachusetts
Academic medical centers in Boston pilot dissolvable microneedle platforms for peptide and biologic delivery previously excluded from dermal routes. NIH funding flows toward stratum corneum permeation research at MIT and Harvard-affiliated institutions. The Route 128 corridor hosts specialized formulation scientists in pressure-sensitive adhesive rheology.
North Carolina
Contract development and manufacturing organizations cluster transdermal facilities in Research Triangle Park for iontophoretic acute-care system production. Ambulatory surgical centers in Charlotte and Raleigh adopt electronic active-delivery platforms for postoperative analgesia. The state's pharmaceutical workforce pipeline feeds specialized expertise in skin permeation modeling.
US Transdermal Drug Delivery System Market Key Industry Players
Global majors compete with regional champions across adhesive science and generic manufacturing capabilities. The vendor base splits between diversified healthcare conglomerates and specialized transdermal technology developers. Three archetypes dominate: pharmaceutical giants with generics divisions, adhesive science specialists with healthcare divisions, and pure-play contract manufacturers. Capacity expansion and 505(b)(2) regulatory pathway specialization represent the dominant competitive moves.
Among diversified pharmaceutical conglomerates, Novartis AG and Johnson & Johnson exemplify scale-driven archetypes with integrated generics and consumer health divisions. 3M Company occupies a position as an adhesive science specialist leveraging materials expertise for extended-wear formulations. These three entities represent the competitive spectrum from drug development through delivery technology.
| Leading Market Players |
|---|
| Novartis AG |
| Boehringer Ingelheim |
| Johnson & Johnson |
| LTS Lohmann Therapie-Systeme AG |
| Hisamitsu Pharmaceutical Co., Inc. |
| 3M Company |
| Teva Pharmaceutical Industries |
| Noven Pharmaceuticals |
| Viatris Inc. |
| Others |
Cost & Logistics Intelligence
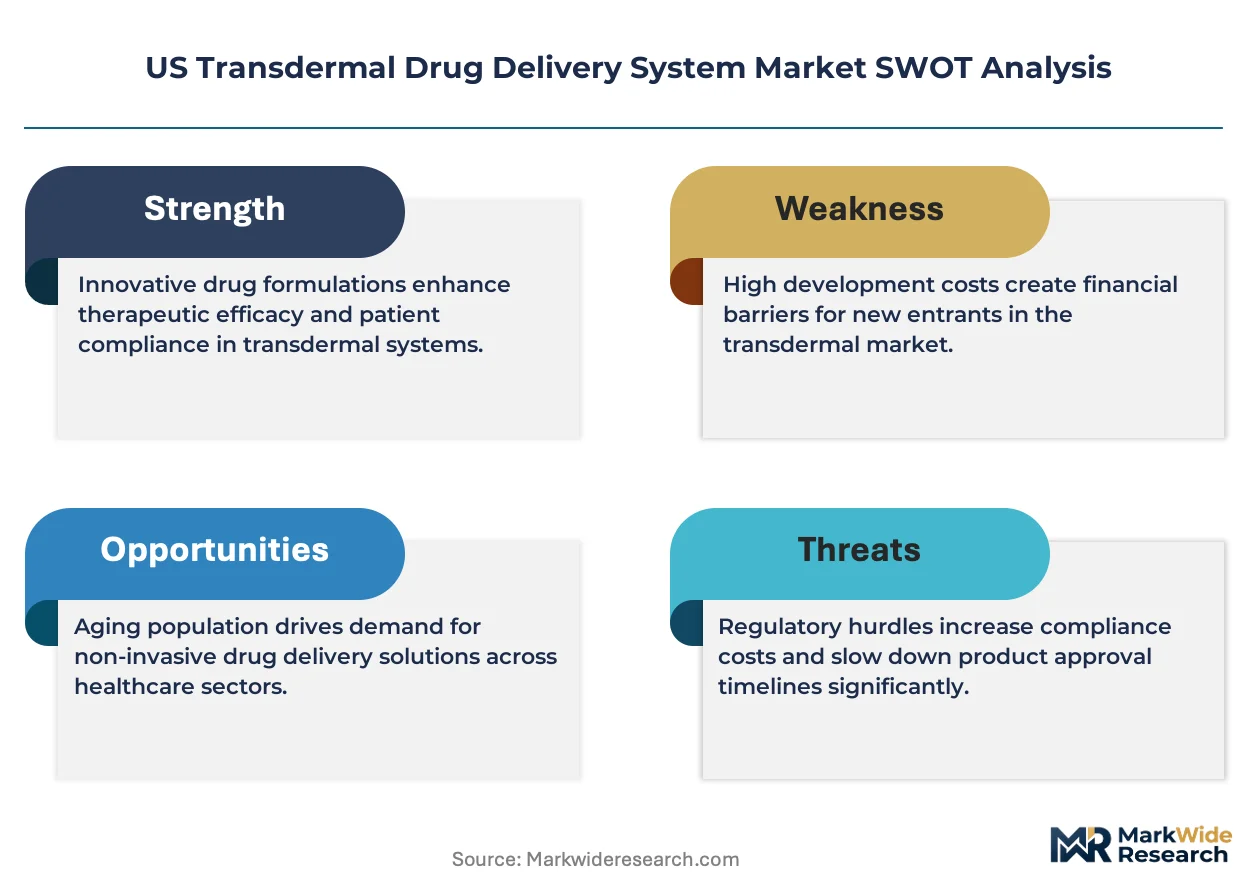
Extended-wear adhesive certification separates premium transdermal patches from commodity generics, with FDA 505(b)(2) pathway complexity and Veterans Affairs contract eligibility determining both margin capture and supplier qualification tiers across Minnesota and North Carolina manufacturing clusters.
Pricing Analysis
Patient-support service bundling distinguishes branded chronic pain patches from unbundled generic equivalents. Three-tier pricing structure across premium 72-hour formulations, standard 48-hour patches, and economy 24-hour alternatives reflects DEA quota scarcity and adhesive science IP. Pricing pressure stems from Medicare reimbursement compression favoring lowest-cost therapeutic equivalents. Home care subscription buyers exhibit highest price sensitivity; hospital iontophoretic procurement tolerates premium positioning for rapid-onset performance.
Supply Chain Analysis
Single-source vulnerability sits with pressure-sensitive adhesive polymer feedstock concentrated in Minnesota and North Carolina contract manufacturing facilities. Active pharmaceutical ingredient sourcing draws from India and China for synthetic opioids, with domestic compounding for hormone actives. Tariff exposure on imported excipients threatens margin stability at generic manufacturers. Distribution runs through specialty pharmacy direct-to-patient channels bypassing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA cGMP inspection backlogs and DEA quota administration create cost-of-compliance moats that protect incumbent patch manufacturers from commodity entrants while elevating capital requirements for facility qualification.
For Market Incumbents: Acquire specialized formulation scientist talent pools retiring from legacy pharmaceutical firms to secure pressure-sensitive adhesive rheology expertise. Expand iontophoretic acute-care capacity in North Carolina Research Triangle Park to defend against electronic delivery substitutes. Secure backward integration into adhesive polymer feedstock to insulate margin from imported excipient tariff volatility. For New Entrants and Emerging Players: Capture microneedle array white space in Massachusetts and Pennsylvania academic medical center pilot programs before biologic compatibility standards crystallize. Target hormone replacement gel segments in California direct-to-patient subscription channels where 505(b)(2) pathway familiarity lowers regulatory barriers. Pursue 72-hour wear time equivalence as primary go-to-market differentiation against established patch competitors. For Investors and Strategic Acquirers: Re-rating potential sits with contract development organizations possessing FDA-inspected transdermal facilities given cGMP inspection backlog bottlenecks. Five-to-ten year viability favors CDMOs with Veterans Affairs contract history and DEA Schedule II manufacturing licenses. Watch CMS reimbursement parity decisions between institutional and home-administered therapies as volume migration inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| 505(b)(2) Regulatory Pathway Specialization | Abbreviated approval routes compress development timelines for complex transdermal formulations against pure bioequivalence submissions. |
| Adhesive Science R&D Investment | Extended-wear pressure-sensitive formulations achieving 72-hour durability command premium positioning in Medicare-covered populations. |
| Direct-to-Patient Distribution Buildout | Specialty pharmacy subscription models bypass wholesale intermediaries and capture margin pools in chronic condition management. |
| Microneedle Platform Development | Dissolvable polymer arrays enable biologic delivery previously excluded from passive transdermal routes in academic medical centers. |
| DEA Schedule II Quota Optimization | Strategic allocation planning secures fentanyl production capacity against opioid supply constraints in pain management clinics. |
Research Approach
Document review covered FDA 505(b)(2) approval databases, DEA quota allocation records, and CMS reimbursement policy filings, complemented by interviews with transdermal formulation scientists, regulatory affairs leads at generic manufacturers, Veterans Affairs pharmacy procurement managers, and specialty pharmacy distribution executives. Secondary validation drew from USP-NF monograph drafts, cGMP inspection observation databases, and Medicare Advantage plan formulary disclosures. Bottom-up volume modeling triangulated against top-down therapeutic category spending benchmarks.
Segment-level projections across product type, delivery mode, therapy area, and end user configuration generated value and volume estimates over the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical approval timelines and reimbursement policy adoption patterns. Forecast inputs incorporated DEA Schedule II quota trajectory assumptions and microneedle clinical trial enrollment velocities at Massachusetts and Pennsylvania academic medical centers.
The model holds under stable FDA inspection throughput and DEA opioid quota allocation continuity; deviation in cGMP facility approval timelines or CMS reimbursement parity enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Global Anesthesia Drugs Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Dextromethorphan Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market