
 Global Anti-Retroviral Drugs Market | 2026-2036
Global Anti-Retroviral Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Retroviral Drugs Market Foresight
Long-acting injectable and implantable drug delivery systems are reshaping treatment paradigms in HIV care. Gilead Sciences leverages its nucleotide analogue portfolio to sustain dominance in oral combination therapies across developed and emerging markets. ViiV Healthcare anchors the long-acting segment through cabotegravir-rilpivirine formulations, while GSK plc extends manufacturing capacity to secure supply chain resilience in high-burden regions.
Anti-retroviral drugs comprise synthetic chemical agents that interrupt HIV replication through targeted enzymatic inhibition, with formulations requiring precise bioavailability parameters and stability profiles for chronic administration. Integrase strand transfer inhibitors lead clinical preference due to superior viral suppression rates and tolerability margins, while entry inhibitors occupy narrower therapeutic niches reserved for multidrug-resistant patient populations. The therapy area dimension concentrates margin pools within HIV-1 infection management, though pre-exposure prophylaxis represents the fastest-growing demand channel as prevention frameworks expand beyond treatment-only models.
FDA tentative approval pathways and WHO prequalification standards govern market access for generic formulations in donor-funded procurement systems, with EMA centralized procedures shaping European reimbursement negotiations. The EPA and national environmental regulators in India and South Africa impose manufacturing discharge standards that elevate production compliance costs for active pharmaceutical ingredient synthesis. Stakeholders must monitor evolving patent cliff dynamics for integrase inhibitors and prepare portfolio transitions toward next-generation combination platforms.
Market Dynamics
Long-acting injectable formulations are collapsing daily pill burden into quarterly dosing intervals, fundamentally altering adherence economics and reshaping competitive positioning across HIV treatment and prevention protocols.
Growth Catalysts
- PEPFAR and Global Fund procurement frameworks:Donor-funded bulk purchasing programs in sub-Saharan Africa expand patient access through centralized tender mechanisms and volume guarantees.
- Integrase inhibitor therapeutic preference:Superior viral suppression rates and tolerability margins drive clinical adoption ahead of protease and reverse transcriptase alternatives.
- Pre-exposure prophylaxis (PrEP) demand expansion:Prevention-focused healthcare models in Brazil and Thailand create new patient populations beyond treatment-only frameworks.
Market Restraints
- Active pharmaceutical ingredient supply concentration:Bulk manufacturing of tenofovir and emtricitabine precursors clusters in Indian and Chinese chemical parks, creating single-point vulnerability.
- Cold chain infrastructure deficits:Long-acting injectable stability requirements exceed storage capacity in rural clinics across Uganda, Nigeria, and Mozambique.
- Patent cliff compression for integrase inhibitors:Expiring composition-of-matter protections accelerate generic entry and erode originator pricing power.
Strategic Opportunities
- Sub-Saharan Africa clinic network densification:Community-based distribution models in Kenya and South Africa bypass centralized hospital dependency for injectable administration.
- Multipurpose prevention technology convergence:Combination HIV-contraceptive implants address overlapping health needs in high-burden female populations.
- FDA tentative approval pathway leverage:Streamlined regulatory review for generic formulations accelerates donor-funded procurement eligibility.
Industry Challenges
- Pharmacovigilance workforce scarcity:Long-acting drug safety monitoring requires specialized clinical research capacity that remains underdeveloped in high-burden regions.
- Legacy oral therapy switching friction:Patient and provider inertia complicates transitions from established daily regimens to injectable alternatives despite adherence advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Retroviral Drugs Market |
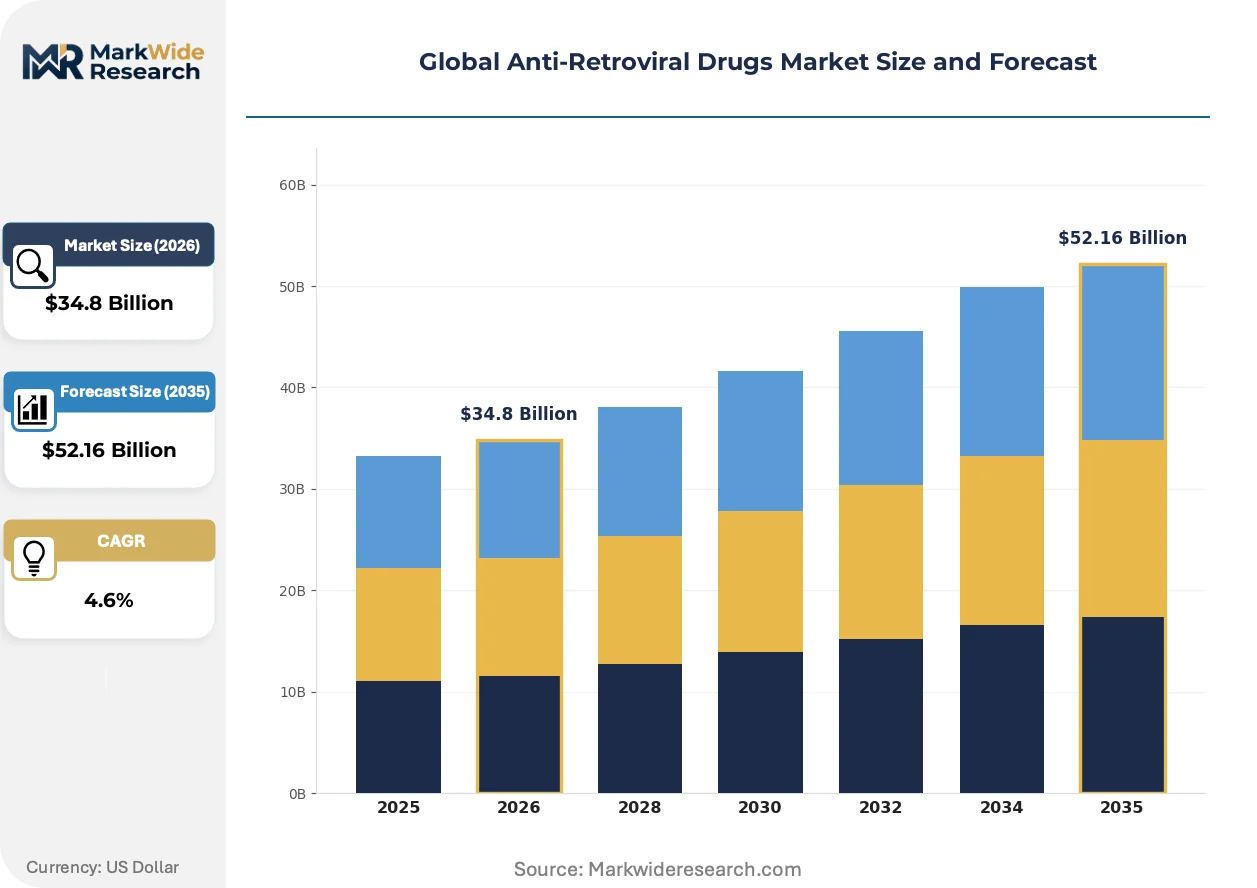
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $52.16 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Nucleoside Reverse Transcriptase Inhibitors, Non-Nucleoside Reverse Transcriptase Inhibitors, Protease Inhibitors, Integrase Strand Transfer Inhibitors, Entry Inhibitors Therapy Area: HIV-1 Infection, HIV-2 Infection, Pre-Exposure Prophylaxis, Post-Exposure Prophylaxis, Opportunistic Infection Prevention Patient Demographics: Adults, Adolescents, Pediatric, Geriatric Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Community Health Centers, Government Programs |
| Companies Covered | Gilead Sciences, ViiV Healthcare, Merck & Co., Inc., AbbVie, Bristol-Myers Squibb Company, Johnson & Johnson, F. Hoffmann-La Roche Ltd., GSK plc, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Retroviral Drugs Market Shifts & Advancements
Biopharmaceutical delivery systems are collapsing administration frequency from daily to quarterly intervals. Formulation chemistry advances and regulatory science convergence are compressing development timelines while expanding addressable patient populations.
Cabotegravir-rilpivirine nanosuspension technology is collapsing the distinction between treatment and prevention administration models. Subcutaneous and intramuscular depot formulations enable quarterly dosing that eliminates daily adherence burden. HIV clinics in France, Australia, and Canada are adopting these protocols fastest, compressing visit frequency and enabling decentralized care models.
WHO prequalification standards are harmonizing quality benchmarks across donor-funded procurement systems. The program accelerates generic market entry by accepting FDA tentative approvals and EMA centralized opinions as parallel pathways. Manufacturers in India and South Africa are restructuring quality management systems to satisfy unified standards, reducing duplicate facility inspections.
Community pharmacy dispensing is displacing hospital-centered distribution for oral PrEP in urban Thailand and Brazil. Retail channel penetration reduces stigma-associated clinic visits while expanding geographic reach. Pharmacist-administered screening and prescription protocols are compressing initiation delays that previously constrained prevention uptake among key populations.
Global Anti-Retroviral Drugs Market Segmentation
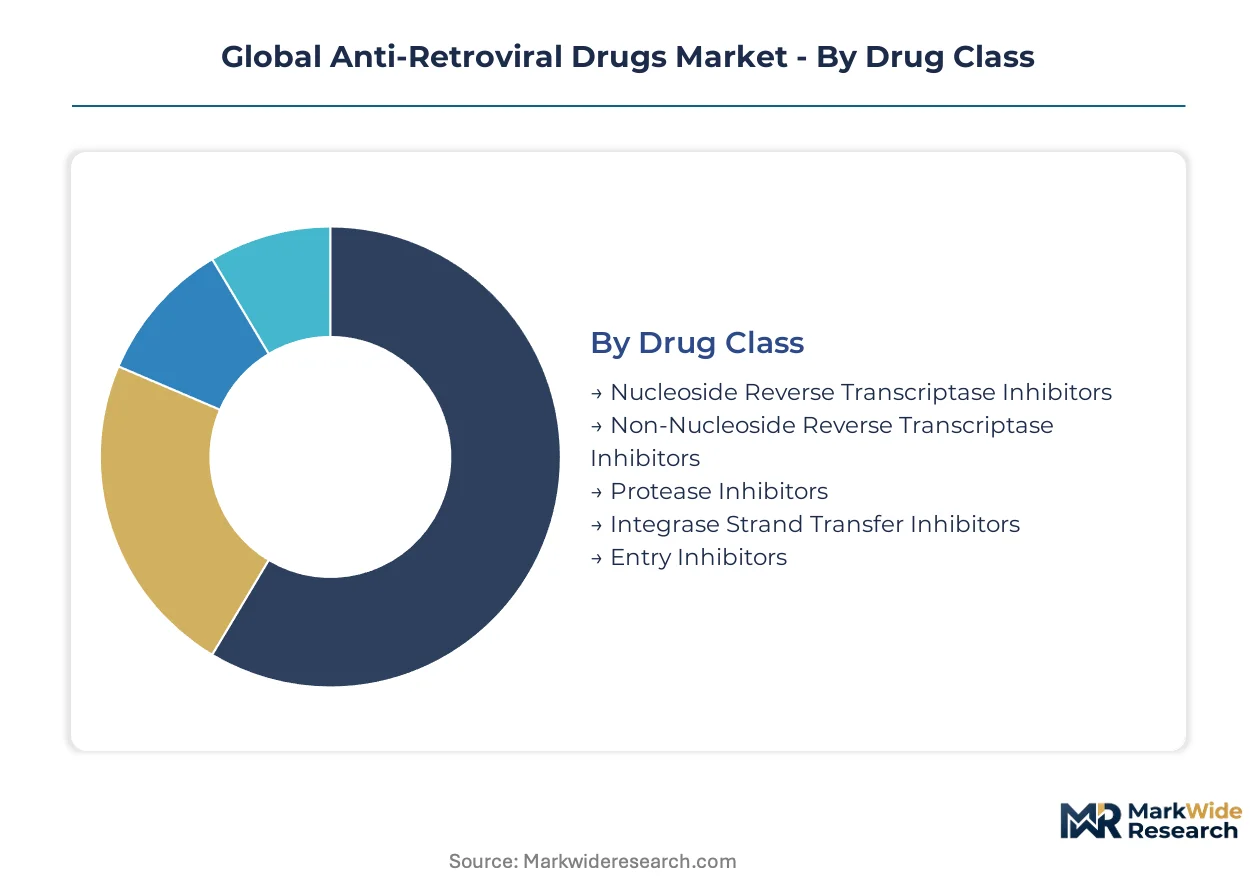
Segmentation in anti-retroviral drugs exposes divergent clinical utility across mechanism classes and reveals how prevention frameworks are fragmenting traditional treatment-only demand pools. Understanding these divides sharpens portfolio positioning for manufacturers navigating patent transitions and geographic expansion.
Drug Class:
Mature nucleoside analogues anchor volume foundations while emerging integrase platforms capture premium positioning and prescriber preference shifts.
- Integrase Strand Transfer Inhibitors:These agents block viral DNA integration into host chromosomes with superior barrier resistance and tolerability profiles. Demand concentrates in first-line treatment protocols across France, Brazil, and South Africa where dolutegravir-based regimens dominate national guidelines. Regulatory preference from WHO and FDA for integrase-first sequencing accelerates displacement of older classes.
- Nucleoside Reverse Transcriptase Inhibitors:Synthetic nucleoside analogues terminate DNA chain elongation through competitive incorporation. Tenofovir and emtricitabine combinations remain the backbone of generic procurement through PEPFAR and Global Fund tenders in Kenya, Uganda, and Nigeria, sustained by manufacturing scale in Indian API parks.
- Non-Nucleoside Reverse Transcriptase Inhibitors:Allosteric enzyme inhibitors like efavirenz and rilpivirine persist in resource-limited settings due to cost advantages and established supply chains.
- Protease Inhibitors:These agents cleave viral polyproteins into functional units, now reserved primarily for salvage therapy in multidrug-resistant cases.
- Entry Inhibitors:CCR5 antagonists and fusion inhibitors occupy narrow niches for patients with tropism-specific resistance patterns.
Integrase Strand Transfer Inhibitors retain volume leadership; Entry Inhibitors hold the steepest expansion curve among salvage therapy alternatives.
Therapy Area:
Cost tier stratification separates chronic treatment commodities from prevention-focused premium formulations commanding differentiated pricing.
- HIV-1 Infection:Chronic suppressive therapy for the dominant viral subtype represents the foundational revenue pool. Treatment demand concentrates in sub-Saharan Africa clinic networks and urban Brazilian public health systems where patient volumes sustain manufacturing economies.
- Pre-Exposure Prophylaxis:Preventive daily or long-acting regimens for seronegative populations represent the demand frontier. Uptake accelerates in Thailand's community pharmacy networks and Australia's sexual health clinics where stigma reduction campaigns expand addressable populations beyond traditional treatment cohorts.
- HIV-2 Infection:West African-specific protocols require adapted regimens due to natural integrase resistance and slower disease progression.
- Post-Exposure Prophylaxis:Occupational and non-occupational emergency regimens serve healthcare workers and exposure incidents through hospital emergency departments.
- Opportunistic Infection Prevention:Prophylactic co-trimoxazole and isoniazid for immunocompromised patients complements ART in advanced disease management.
HIV-1 Infection commands absolute volume; Pre-Exposure Prophylaxis climbs the fastest as prevention frameworks displace treatment-only models.
Patient Demographics:
Application urgency varies sharply across age bands, with pediatric formulations demanding specialized delivery systems and geriatric populations presenting comorbidity complexity.
- Adults:The core demographic for standardized oral and injectable formulations. Demand concentrates in 25-49 year cohorts across South Africa, India, and the United States where prevalence peaks and treatment literacy supports adherence.
- Pediatric:Weight-band dosing requirements and palatability challenges necessitate dispersible tablets and liquid formulations. Procurement through UNICEF and national programs in Mozambique and Zambia drives volume despite formulation complexity premiums.
- Adolescents:Transition-age populations require adherence support distinct from both pediatric and adult care models.
- Geriatric:Aging HIV-positive populations present polypharmacy management challenges as non-communicable disease burdens accumulate.
Adults retain volume leadership; Pediatric holds the steepest expansion curve as early diagnosis programs expand birth cohort coverage.
Distribution Channel:
Customer type stratification separates institutional procurement from retail and community-based models with divergent service requirements.
- Government Programs:Centralized tender mechanisms through PEPFAR, Global Fund, and national AIDS programs in Tanzania and Malawi aggregate volume and compress pricing. These channels require WHO prequalification and FDA tentative approval as gatekeeping standards.
- Hospital Pharmacies:Institutional dispensing anchors initiation protocols and complex case management in tertiary centers across Spain, Italy, and urban Indian hospitals.
- Retail Pharmacies:Community-based dispensing expands geographic reach and reduces clinic congestion in Thailand's pharmacy-led PrEP models.
- Community Health Centers:Decentralized administration supports injectable long-acting delivery in Kenyan and South African rural networks.
- Online Pharmacies:Digital channels serve privacy-sensitive populations in North American and European markets with courier-based delivery.
Government Programs retain volume leadership; Community Health Centers gain share fastest as injectable administration decentralizes beyond hospital dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports active pharmaceutical ingredients for tenofovir and emtricitabine to PEPFAR-funded procurement programs across sub-Saharan Africa, establishing a dominant trade corridor that shapes regional supply security.
United States
FDA tentative approval pathways accelerate generic eligibility for donor-funded procurement. Gilead Sciences and ViiV Healthcare anchor commercial demand through long-acting injectable launches. Boston and San Francisco biotech clusters drive next-generation formulation chemistry for quarterly dosing intervals.
South Africa
The national AIDS program sustains the continent's largest patient cohort on dolutegravir-based first-line therapy. WHO prequalification standards govern centralized tender mechanisms through the national Department of Health. Cape Town and Johannesburg manufacturing facilities expand fill-finish capacity for regional distribution.
India
Hyderabad and Ahmedabad chemical parks concentrate bulk synthesis of nucleoside analogues for global generic supply. CDSCO manufacturing standards align with WHO prequalification to secure export eligibility. Domestic patient access programs expand alongside export-oriented production scale.
Brazil
Community pharmacy networks in São Paulo and Rio de Janeiro displace hospital-centered PrEP distribution. ANVISA regulatory frameworks accommodate prevention-focused prescribing protocols. Public health system integration reduces stigma-associated barriers to preventive therapy initiation.
Thailand
Bangkok and Chiang Mai sexual health clinics pioneer pharmacist-administered screening and prescription models. Ministry of Public Health prevention campaigns expand addressable populations beyond traditional treatment cohorts. Retail channel penetration compresses geographic access constraints for key demographic segments.
Global Anti-Retroviral Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent access models. The vendor base stratifies between originator firms commanding premium positioning in long-acting formulations and generic manufacturers capturing volume through donor-funded tenders. Three archetypes dominate: integrated pharmaceutical conglomerates with nucleotide analogue portfolios, standalone HIV-focused specialists with depot injection platforms, and emerging-market generic houses with API-to-finished-dose vertical control. Competitive moves concentrate on manufacturing capacity expansion in high-burden regions and strategic licensing arrangements for patent-protected combination therapies.
Among originator-tier developers, Gilead Sciences exemplifies the nucleotide analogue specialist archetype through its established oral combination franchise. ViiV Healthcare occupies a parallel position within the long-acting injectable segment, representing the HIV-dedicated specialist model. GSK plc anchors the diversified conglomerate approach with manufacturing infrastructure spanning multiple therapeutic categories.
| Leading Market Players |
|---|
| Gilead Sciences |
| ViiV Healthcare |
| Merck & Co., Inc. |
| AbbVie |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd. |
| GSK plc |
| Cipla |
| Others |
Supply & Pricing Matrix
Indian API manufacturers in Hyderabad and Ahmedabad chemical parks anchor cost structures for tenofovir and emtricitabine precursors, concentrating margin capture in generic finished-dose producers while originators defend premium positioning through long-acting formulation patents. This upstream concentration creates divergent pricing power between commodity oral regimens and patented quarterly injectables.
Pricing Analysis
Current-generation oral combination therapies, prior-generation protease inhibitor salvage regimens, and next-generation long-acting injectables occupy distinct price bands. Three-tier pricing structure across premium, standard, and economy levels separates originator depot formulations from WHO-prequalified generics and non-prequalified regional suppliers. Price differentiation rests on regulatory certification tier and manufacturing scale, with PEPFAR tender volumes compressing unit economics for standard-tier suppliers. Pricing pressure stems from patent cliff dynamics for integrase inhibitors as composition-of-matter protections expire. Government procurement programs in sub-Saharan Africa exhibit highest price sensitivity; private-pay markets in North America and Western Europe demonstrate lowest.
Supply Chain Analysis
Contract manufacturing organizations including Patheon, Catalent, and Lonza hold fill-finish capacity for long-acting injectable nanosuspensions, while Indian API houses perform upstream synthesis. Geographic supply concentration clusters in India for tenofovir precursors, China for advanced intermediates, and the United States for proprietary formulation technology. Raw material dependencies include pyrimidine nucleobases, organometallic catalysts, and specialized lipids for depot formulations. Single-source vulnerability concentrates in cold-chain logistics for temperature-sensitive injectables. Distribution runs through centralized government tenders in high-burden regions and hospital pharmacy networks in developed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-acting injectable administration services and adherence monitoring programs represent a recurring-revenue layer expanding faster than molecular hardware, creating attach-rate opportunities for clinic networks and specialty pharmacies.
For Market Incumbents: Entrench position through backward integration into API synthesis for tenofovir and emtricitabine precursors, securing supply continuity against Indian and Chinese export restrictions. Expand fill-finish capacity in Cape Town and Johannesburg to reduce cold-chain exposure across sub-Saharan distribution. Patent cliff compression for dolutegravir represents the dominant threat requiring accelerated next-generation combination platform investment. For New Entrants and Emerging Players: Pursue community health center dispensing partnerships in Kenya and South Africa, where injectable administration decentralization creates channel access without hospital infrastructure investment. Target adolescent and pediatric formulation gaps as the most penetrable patient demographics, where weight-band dosing requirements and palatability challenges deter incumbent specialization. Deploy pharmacist-administered screening protocols modeled on Thailand's retail PrEP expansion. For Investors and Strategic Acquirers: Capital is best deployed toward vertically controlled generic houses with API-to-finished-dose manufacturing in Indian chemical parks and WHO prequalification status. Long-term viability over the coming decade hinges on regulatory pathway expertise and donor-funded procurement eligibility rather than proprietary pipeline depth. Monitor FDA tentative approval grants to Indian and South African manufacturers as inflection indicators for generic market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Development | Quarterly dosing intervals from ViiV Healthcare and Gilead Sciences collapse adherence burden and reshape competitive positioning. |
| WHO Prequalification Investment | Quality system alignment accelerates PEPFAR and Global Fund eligibility for generic manufacturers in India and South Africa. |
| Cold Chain Infrastructure Buildout | Regional distribution hubs in Nairobi and Lagos address stability requirements for injectable depot formulations. |
| Community Pharmacy Partnership | Retail channel penetration in Bangkok and São Paulo reduces stigma barriers and expands PrEP addressable populations. |
| Patent Portfolio Transition | Next-generation integrase inhibitor combinations defend originator positioning against impending composition-of-matter expirations. |
Research Methodology
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases anchors the qualitative findings. Bottom-up patient volume modeling by country and treatment line triangulates against top-down procurement expenditure data from PEPFAR and Global Fund disclosures.
Calibration against historical tender awards and patient enrollment trajectories informs the analytical framework across the projection horizon. Segmentation dimensions include drug class mechanism, therapy area indication, patient demographic cohort, administration route, and regional regulatory cluster. CAGRs derive from patent expiry schedules, generic entry assumptions, and prevention framework expansion rates. Forecast inputs incorporate long-acting formulation adoption curves and cold-chain infrastructure investment pipelines.
Sensitivities concentrate around integrase inhibitor patent litigation outcomes, Indian API export policy shifts, and donor funding continuity for sub-Saharan procurement programs. Forecasts reflect documented assumptions regarding regulatory pathway timelines and manufacturing capacity expansion schedules. Quarterly review of FDA tentative approval grants, WHO prequalification status updates, and PEPFAR procurement award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
Prescription Drugs Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
US Hormone Replacement Therapy Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Global Human Vaccines Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
Botulinum Toxin Market