
 North America Pharmaceutical Warehousing Market | 2026-2036
North America Pharmaceutical Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pharmaceutical Warehousing Market Insights
The FDA's Drug Supply Chain Security Act is shifting compliance burdens toward serialized track-and-trace infrastructure across pharmaceutical distribution networks. McKesson Corporation leverages its vertically integrated distribution footprint to absorb these compliance costs at scale. Cardinal Health anchors its competitive position through specialized oncology and biologics handling capabilities. AmerisourceBergen Corp differentiates via its focus on specialty pharmaceutical logistics and physician office distribution.
North America pharmaceutical warehousing encompasses the temperature-controlled storage, inventory management, and order fulfillment of drug products within facilities maintaining specific environmental parameters such as 2-8°C for refrigerated biologics or -20°C to -80°C for frozen cell therapies, serving the essential function of preserving product integrity from manufacturer to dispenser. Cold chain storage commands premium infrastructure investment as biologics and gene therapies expand their share of pharmaceutical pipelines. Automated warehousing represents the fastest-growing model category as labor costs and accuracy requirements intensify across pharmaceutical manufacturers and retail pharmacies.
The FDA enforces current Good Manufacturing Practice and Good Distribution Practice standards that dictate facility design, temperature mapping, and documentation protocols for all pharmaceutical warehousing operations in the United States. Health Canada and PMRA apply parallel stringent requirements for cross-border distribution into Canadian markets, creating a dual-compliance environment for North American operators. Stakeholders must monitor evolving serialization deadlines and temperature excursion reporting thresholds as regulatory bodies harmonize standards across the integrated North American supply chain.
Market Dynamics
The FDA's Drug Supply Chain Security Act serialization mandates are compressing operational timelines across pharmaceutical distribution networks, forcing warehouse operators to deploy track-and-trace infrastructure ahead of enforcement deadlines.
Growth Catalysts
- Biologics pipeline expansion:Cell and gene therapies require specialized cryogenic storage at -80°C, creating demand for ultra-low temperature infrastructure across the United States and Canada.
- Health Canada serialization alignment:The country's national pharmaceutical regulator is harmonizing traceability standards with FDA mandates, enabling cross-border operational efficiencies for integrated North American networks.
- Oncology hub concentration:Pennsylvania and New Jersey distribution clusters are attracting specialized cold chain investment from manufacturers seeking proximity to major hospital systems.
Market Restraints
- Energy cost volatility:Refrigeration systems consume substantial electricity, and regional grid pricing fluctuations in California and Texas directly compress facility operating margins.
- Qualified technician scarcity:The specialized labor pool for GMP-compliant warehouse operations remains thin in secondary markets across the Midwest and Mountain states.
- Real estate availability:Suitable industrial zoned land near major metropolitan healthcare clusters in Boston, San Francisco, and Toronto commands premium lease rates that deter new entrant expansion.
Strategic Opportunities
- Mexico nearshoring corridor:Manufacturers are establishing secondary distribution nodes in Baja California and Nuevo León to serve emerging Latin American markets while maintaining FDA-compliant standards.
- Direct-to-patient distribution:Specialty pharmacies are contracting for last-mile cold chain capabilities that bypass traditional wholesale channels for temperature-sensitive therapies.
- AI-driven predictive maintenance:Machine learning platforms are converging with IoT sensor networks to prevent temperature excursions before they compromise product integrity.
Industry Challenges
- Serialization system integration:Legacy warehouse management platforms require expensive middleware development to interface with FDA-mandated track-and-trace databases.
- Temperature mapping validation:Regulatory protocols demand continuous thermal monitoring documentation that strains quality assurance staffing across multi-zone facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pharmaceutical Warehousing Market |
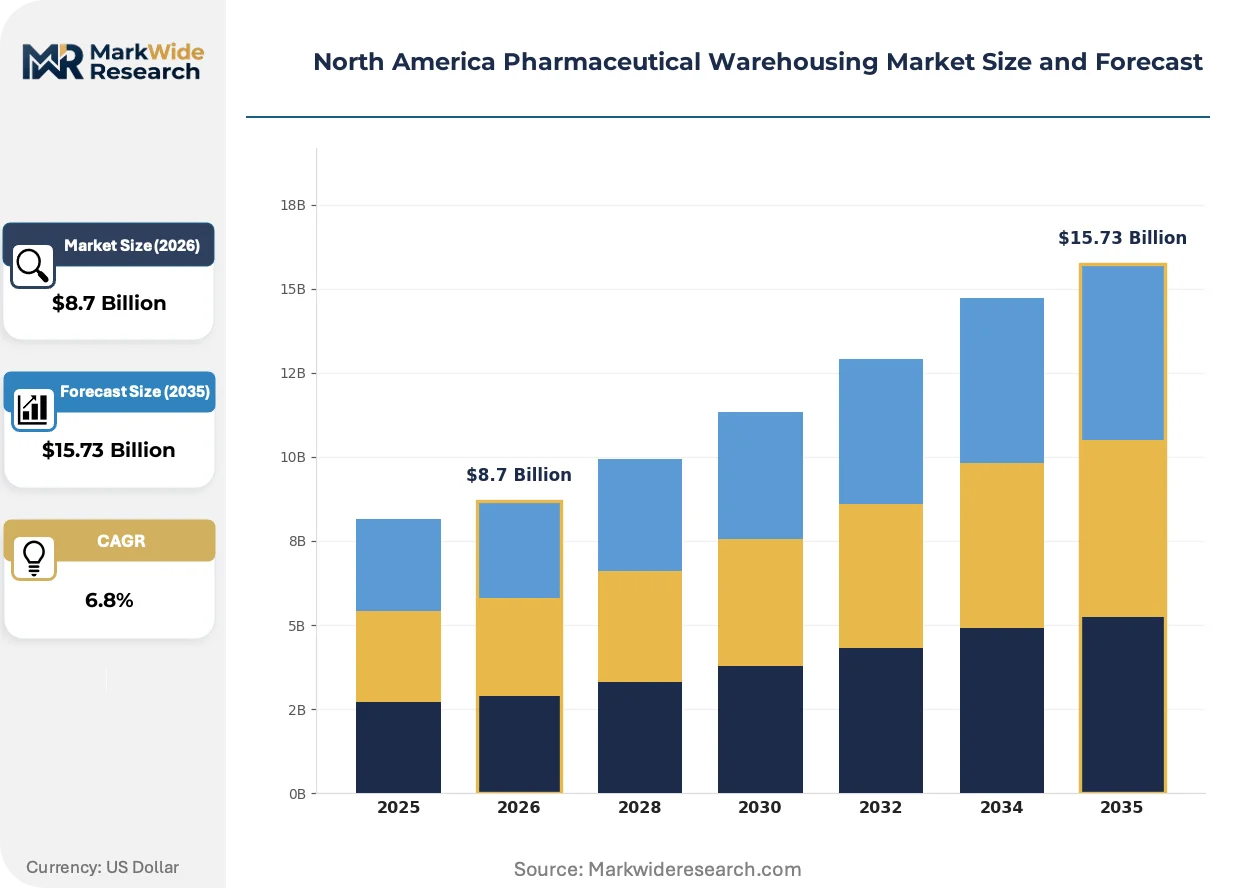
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cold Chain Storage, Inventory Management, Order Fulfillment, Distribution Warehousing Model: Public Warehousing, Contract Warehousing, Automated Warehousing, Private Warehousing End User: Pharmaceutical Manufacturers, Distributors, Wholesalers, Retail Pharmacies Temperature Control: Ambient, Refrigerated, Frozen, Controlled Room Temperature |
| Companies Covered | McKesson Corporation, Cardinal Health, AmerisourceBergen Corp, UPS Healthcare, Langham Logistics, FedEx Corporation, Deutsche Post DHL, C.H. Robinson, Alloga, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pharmaceutical Warehousing Market Trends and Innovations
Automated storage and retrieval systems are compressing labor dependency while raising throughput accuracy requirements. Three developments are restructuring competitive capabilities across North American pharmaceutical warehousing.
Autonomous mobile robots are unifying inventory movement with real-time location tracking in high-throughput distribution centers. McKesson and Cardinal Health facilities in the Northeast corridor are deploying these systems at scale. This convergence is unifying warehouse labor models toward technician oversight rather than manual handling, compressing headcount per pallet position.
The FDA's Enhanced Drug Distribution Security provisions are mandating unit-level traceability by November 2023 enforcement windows. Pharmaceutical distributors must upgrade serialization infrastructure to comply with interoperable data exchange standards. Oncology and biologics segments face the steepest compliance costs given their high-value, temperature-sensitive product mixes.
Hospital systems are consolidating procurement through centralized service agreements that bundle warehousing with distribution and clinical support. Integrated delivery networks in Texas and Florida are displacing fragmented supplier relationships with single-source logistics contracts. This concentration is most visible in cancer center supply chains where inventory carrying costs and stockout risks carry patient safety implications.
North America Pharmaceutical Warehousing Market Segmentation
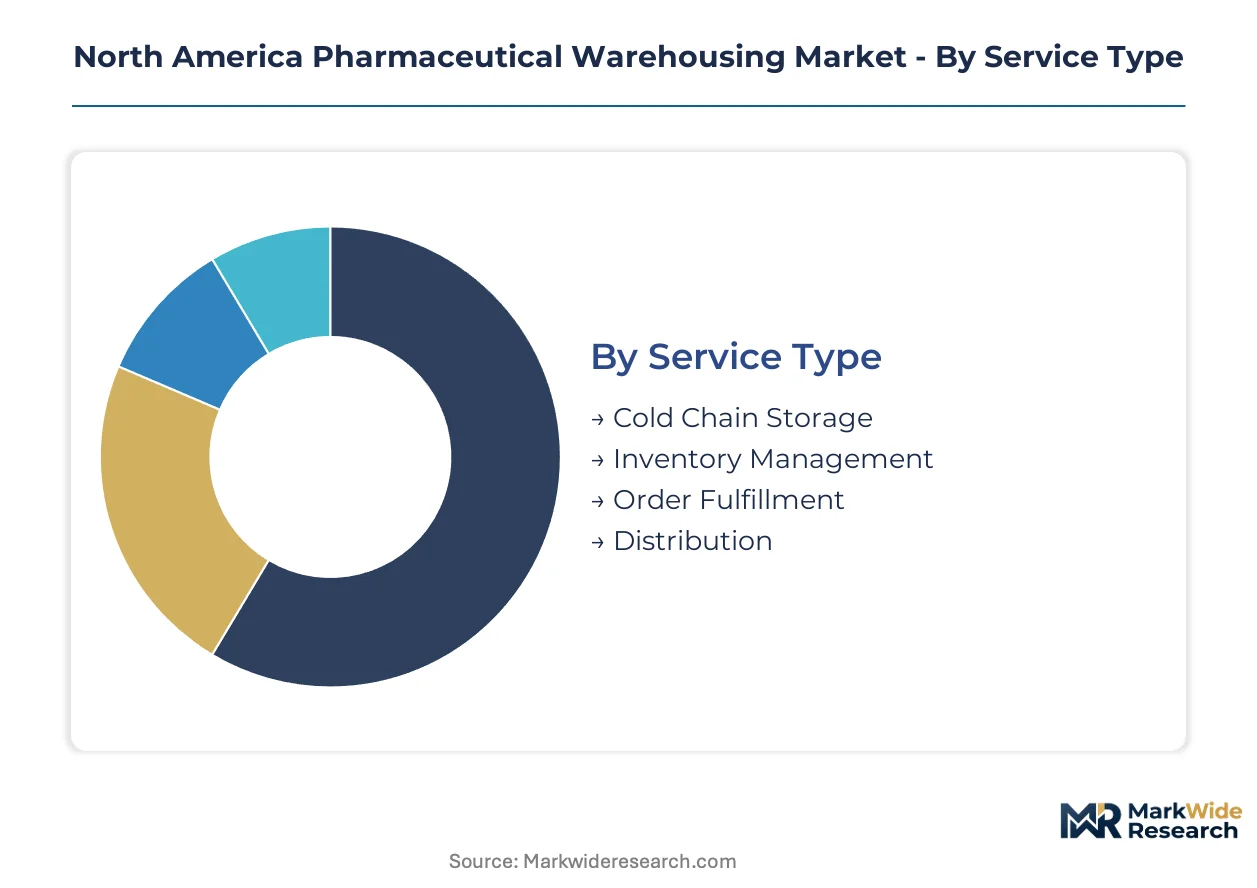
Pharmaceutical warehousing segmentation reveals divergent capital requirements across service types and infrastructure models. Cold chain capabilities command premium investment intensity while automated systems reshape operating economics across the United States and Canada.
Service Type:
Cold chain storage demands the heaviest upfront infrastructure investment among service categories, with specialized refrigeration and backup power systems consuming facility budgets.
- Cold Chain Storage:Temperature-controlled environments maintain 2-8°C for refrigerated biologics or -20°C to -80°C for frozen cell therapies, requiring redundant compressor systems and continuous monitoring. Demand concentrates in New Jersey and Pennsylvania hubs serving Northeast corridor hospital systems, driven by biologics pipeline expansion and FDA serialization compliance timelines.
- Inventory Management:Serialized track-and-trace systems integrate with warehouse management platforms to maintain lot-level visibility from manufacturer to dispenser. Pharmaceutical distributors in Texas and Florida are deploying these capabilities to serve consolidated hospital procurement networks managing oncology supply chains.
- Order Fulfillment:Pick-and-pack operations for pharmaceutical products require validated workflows and contamination controls.
- Distribution:Cross-dock and line-haul services connect storage nodes to end dispensers across North American markets.
Most installed capacity flows through inventory management systems. Expansion is steepest in cold chain storage.
Warehousing Model:
Automation intensity separates models by labor substitution potential and throughput scalability across facility networks.
- Automated Warehousing:Autonomous mobile robots and automated storage and retrieval systems compress labor dependency while raising accuracy requirements. McKesson and Cardinal Health facilities in the Northeast corridor deploy these systems at scale, unifying inventory movement with real-time location tracking.
- Contract Warehousing:Third-party operators assume facility investment and compliance burden for pharmaceutical manufacturers seeking operational flexibility. Demand clusters near Toronto and Boston where real estate constraints deter captive facility development.
- Public Warehousing:Multi-tenant facilities offer shared infrastructure with standardized temperature zones and security protocols.
- Private Warehousing:Captive facilities serve single manufacturers with dedicated quality systems and customized workflows.
Contract warehousing dominates current revenue share. Automated warehousing is climbing the fastest as labor costs intensify.
End User:
Customer scale and compliance sophistication determine service packaging and pricing structures across the value chain.
- Pharmaceutical Manufacturers:Large-scale producers of small-molecule drugs and biologics require integrated storage with serialization infrastructure and temperature mapping validation. Investment concentrates in Pennsylvania and New Jersey clusters proximate to major distribution corridors.
- Distributors:National wholesalers absorb FDA Drug Supply Chain Security Act compliance costs through vertically integrated footprints spanning multiple temperature zones.
- Wholesalers:Regional operators serve fragmented retail pharmacy networks with consolidated procurement and delivery schedules.
- Retail Pharmacies:Chain and independent dispensers contract for last-mile distribution and inventory replenishment services.
Distributors control the largest facility footprint. Manufacturers are driving the steepest capacity expansion for cell and gene therapy storage.
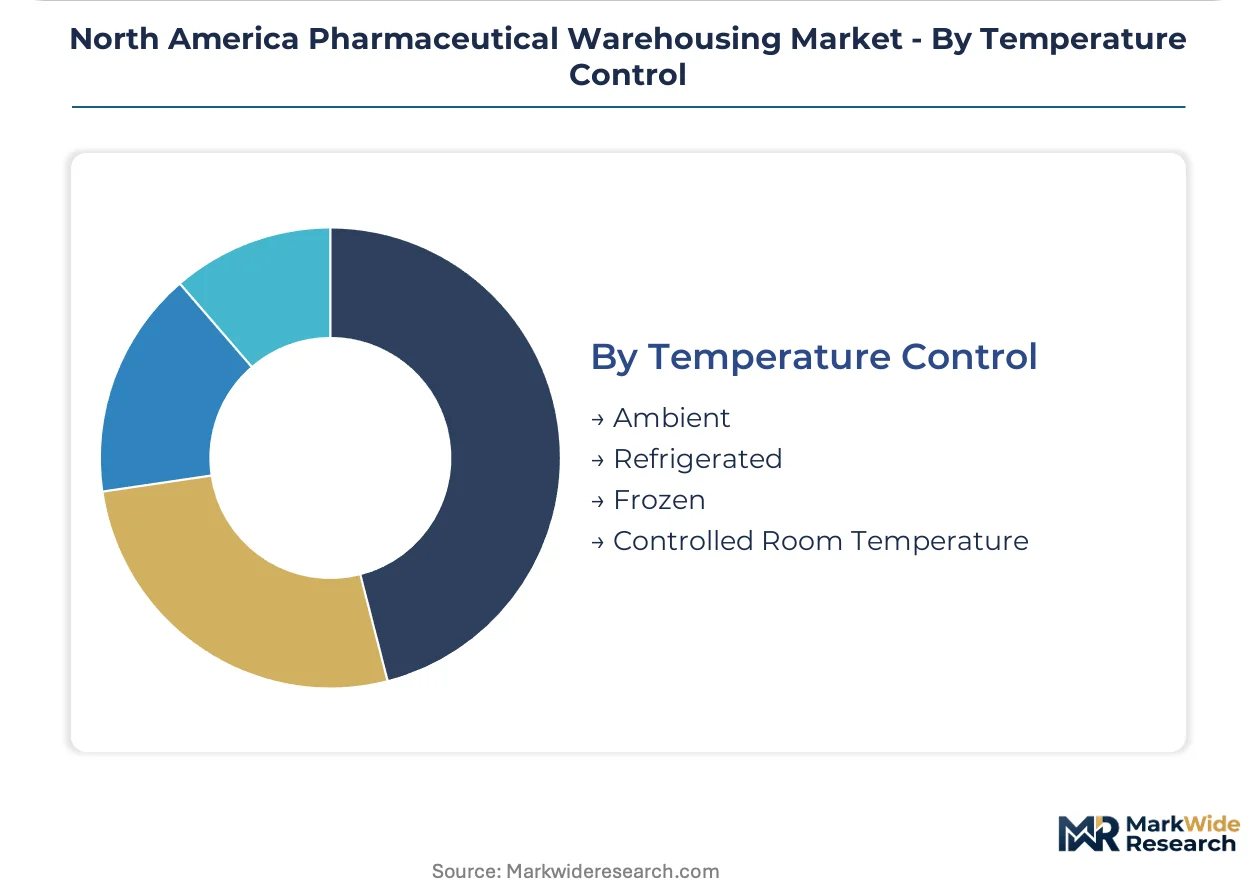
Temperature Control:
Regulatory stringency escalates with temperature deviation risk, segmenting infrastructure investment and operational protocols.
- Frozen:Ultra-low temperature systems maintain -20°C to -80°C for cell therapies and gene therapy materials, requiring specialized freezer farms and liquid nitrogen backup systems. Pennsylvania oncology hubs attract concentrated investment from manufacturers seeking proximity to major hospital systems.
- Refrigerated:2-8°C environments serve monoclonal antibodies and vaccines with validated cold chain continuity. Demand clusters in California and Texas where energy cost volatility directly compresses operating margins.
- Ambient:Standard temperature storage applies to stable small-molecule pharmaceuticals with minimal environmental sensitivity.
- Controlled Room Temperature:20-25°C ranges with humidity controls protect moisture-sensitive formulations.
Refrigerated capacity represents the largest installed base. Frozen infrastructure is gaining share fastest on biologics pipeline expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized logistics talent clusters anchor pharmaceutical warehousing capacity across North American metropolitan corridors, with FDA-trained quality technicians concentrated in Northeast distribution hubs and cold chain engineers gravitating toward biotech manufacturing zones.
United States
FDA serialization mandates and biologics pipeline expansion drive infrastructure investment in Pennsylvania and New Jersey distribution clusters. The Drug Supply Chain Security Act enforcement windows compress operational timelines for track-and-trace deployment. Philadelphia anchors specialized oncology cold chain capacity serving major hospital systems.
Canada
Health Canada harmonization with FDA traceability standards enables cross-border operational efficiencies for integrated North American networks. The PMRA applies stringent temperature mapping requirements for biologics distribution into Canadian markets. Toronto concentrates contract warehousing demand where real estate constraints deter captive facility development.
Mexico
Nearshoring strategies establish secondary distribution nodes in Baja California and Nuevo León for Latin American market access. Manufacturers maintain FDA-compliant standards while serving emerging regional demand. Monterrey attracts cold chain investment from multinational pharmaceutical distributors seeking geographic diversification.
North America Pharmaceutical Warehousing Market Competitive Landscape
The competitive structure tilts toward vertically integrated national distributors with multi-temperature-zone footprints. Three archetypes dominate: wholesale distributors with serialization-scale infrastructure, third-party logistics specialists with biologics handling credentials, and express carriers extending into healthcare verticals. Competitive moves concentrate on M&A for cold chain capabilities and strategic partnerships with specialty pharmacy networks.
Within the wholesale distributor tier, McKesson Corporation, Cardinal Health, and AmerisourceBergen Corp represent the consolidated core absorbing FDA compliance costs at scale. These distributors anchor national footprints spanning refrigerated, frozen, and ambient storage zones. Third-party logistics specialists occupy positions serving manufacturers seeking operational flexibility without captive facility investment. Express carriers with healthcare divisions exemplify the convergence of transportation and warehousing services for direct-to-patient distribution models.
| Leading Market Players |
|---|
| McKesson Corporation |
| Cardinal Health |
| AmerisourceBergen Corp |
| UPS Healthcare |
| Langham Logistics |
| FedEx Corporation |
| Deutsche Post DHL |
| C.H. Robinson |
| Alloga |
| Others |
Pricing and Supply Chain Analysis
Industrial electricity rate indices in California and Texas cascade through pharmaceutical warehousing economics, compressing operating margins for refrigerated and frozen storage tiers while concentrating pricing power among distributors with multi-zone captive generation capacity.
Pricing Analysis
Bundled service contracts versus unbundled transactional storage define the dominant pricing split in North American pharmaceutical warehousing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated cold chain facilities from temperature-mapped standard storage and basic ambient warehousing. Price differentiation hinges on certification grade and geographic delivery cost to hospital clusters. Cost compression in standard-tier refrigerated storage is intensifying because energy price volatility in deregulated grids erodes margins. Retail pharmacy chains exhibit the highest price sensitivity, while biologics manufacturers accept premium rates for validated cryogenic infrastructure.
Supply Chain Analysis
Regional distribution centers in Pennsylvania, New Jersey, and Ontario anchor hub-and-spoke patterns across the North American pharmaceutical warehousing network. Supply concentrates in the United States and Canada, with emerging nodes in Mexico drawing from multinational distributor networks. The supply chain draws from specialized refrigeration equipment, backup generator systems, and GMP-trained technician labor pools. Single-source vulnerability in ultra-low temperature compressor systems poses structural risk given limited qualified service providers. Distribution runs through vertically integrated national wholesalers serving consolidated hospital procurement networks and fragmented retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
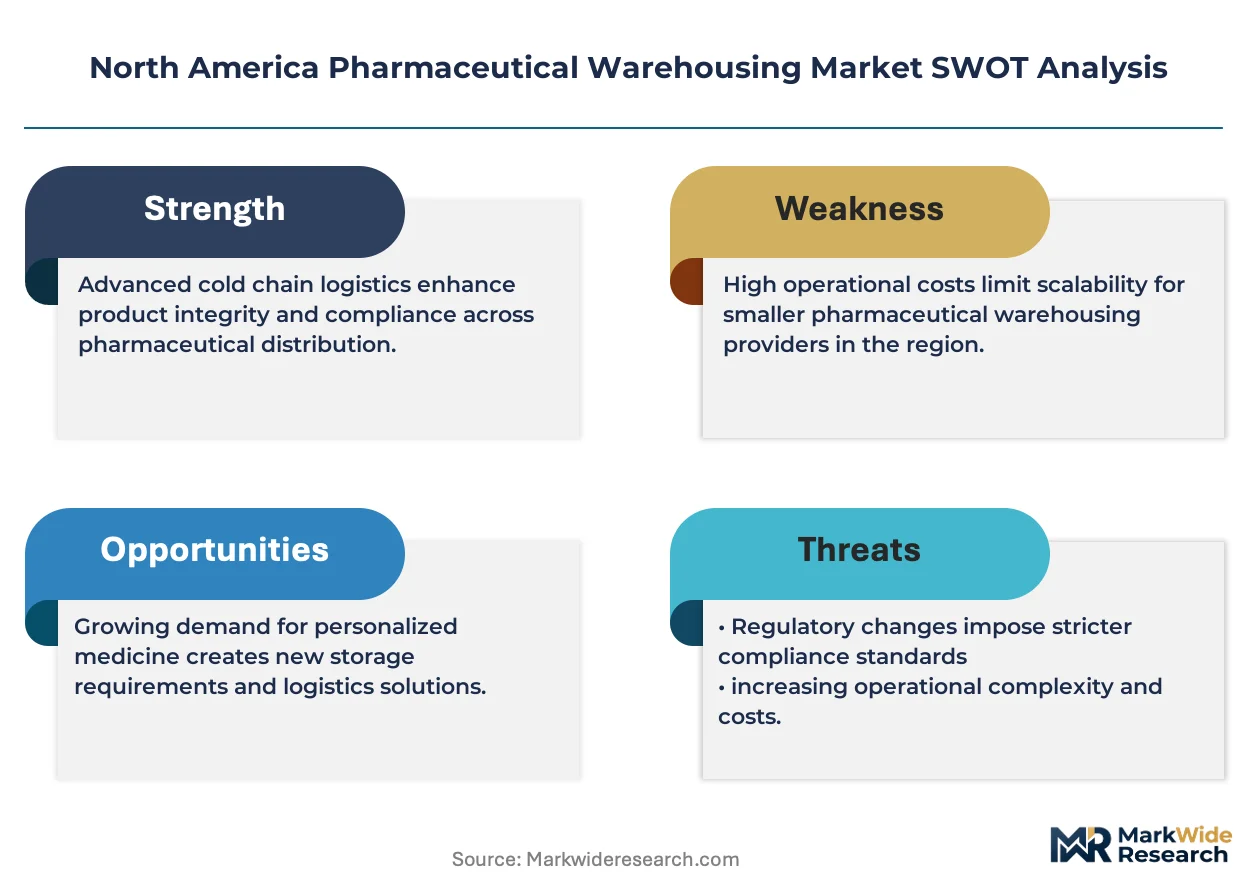
The North America pharmaceutical warehousing market functions as a stable compounder, with biologics pipeline expansion generating predictable infrastructure demand across temperature-controlled storage tiers.
For Market Incumbents: To counter serialization compliance cost escalation, McKesson Corporation and Cardinal Health should deepen backward integration into track-and-trace software platforms while expanding captive cold chain capacity in Pennsylvania oncology hubs. Channel control through exclusive service agreements with integrated delivery networks in Texas and Florida reinforces defensive positioning against third-party logistics encroachment.
For New Entrants and Emerging Players: The mid-market price-point gap between premium biologics handling and economy ambient storage creates entry opportunity for contract warehousing specialists targeting Toronto and Boston real estate constraints. Automated warehousing capabilities in secondary Midwest markets represent the most penetrable white space. A go-to-market angle emphasizing AI-driven predictive maintenance for temperature excursion prevention differentiates against legacy operator service models.
For Investors and Strategic Acquirers: Consolidation pressure builds where FDA serialization deadlines force sub-scale operators to seek acquisition exit rather than fund compliance infrastructure. The five-to-ten-year viability window favors vertically integrated distributors with multi-temperature-zone footprints over single-service contract operators. Acquisition targets include regional cold chain specialists with validated biologics credentials in underserved Mountain and Southwest states. The signal to watch is Health Canada-PMRA harmonization enforcement timing, which will accelerate cross-border network consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Capacity Expansion | Pennsylvania and New Jersey hubs attract investment serving Northeast corridor oncology networks. |
| Serialization Infrastructure Deployment | FDA Drug Supply Chain Security Act mandates force track-and-trace system upgrades ahead of enforcement windows. |
| Automated Warehousing Adoption | Autonomous mobile robots compress labor dependency while raising throughput accuracy requirements at McKesson and Cardinal Health facilities. |
| Cross-Border Network Integration | Health Canada harmonization with FDA standards enables operational efficiencies for integrated United States-Canada distribution. |
| Direct-to-Patient Distribution Partnerships | Specialty pharmacies contract for last-mile cold chain capabilities bypassing traditional wholesale channels. |
Research Methodology
Direct dialogue with pharmaceutical distribution executives, cold chain operations managers, FDA regulatory affairs leads, hospital procurement directors, and third-party logistics specialists grounded the qualitative foundation of this study. Secondary validation drew from FDA Drug Supply Chain Security Act guidance documents, Health Canada serialization advisories, ClinicalTrials.gov biologics pipeline data, and SEC 10-K filings of publicly traded distributors. Bottom-up facility capacity modeling and top-down pharmaceutical spending allocation triangulated market sizing across service type, warehousing model, and temperature control segments.
Segment-level value outputs emerged from infrastructure investment intensity differentials and operating cost structures across the projection horizon. The analytical framework modeled service type, warehousing model, end user category, and temperature control tier as core segmentation dimensions. CAGRs were derived from capacity expansion announcements, regulatory compliance timelines, and biologics pipeline progression rates through clinical development stages. Cryogenic storage demand curves and automated system adoption rates served as industry-specific forecast inputs.
Caveats apply where energy price volatility, qualified technician availability, or serialization deadline extensions could materially shift the outlook. Forecasts reflect documented assumptions regarding biologics approval trajectories and regulatory harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Germany Pharmaceuticals Market
Pharmaceuticals
Dystonia Drugs Market
Pharmaceuticals
Prescription Drugs Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market