
 Pharmaceuticals Lipids Market | 2026-2036
Pharmaceuticals Lipids Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceuticals Lipids Market Analysis
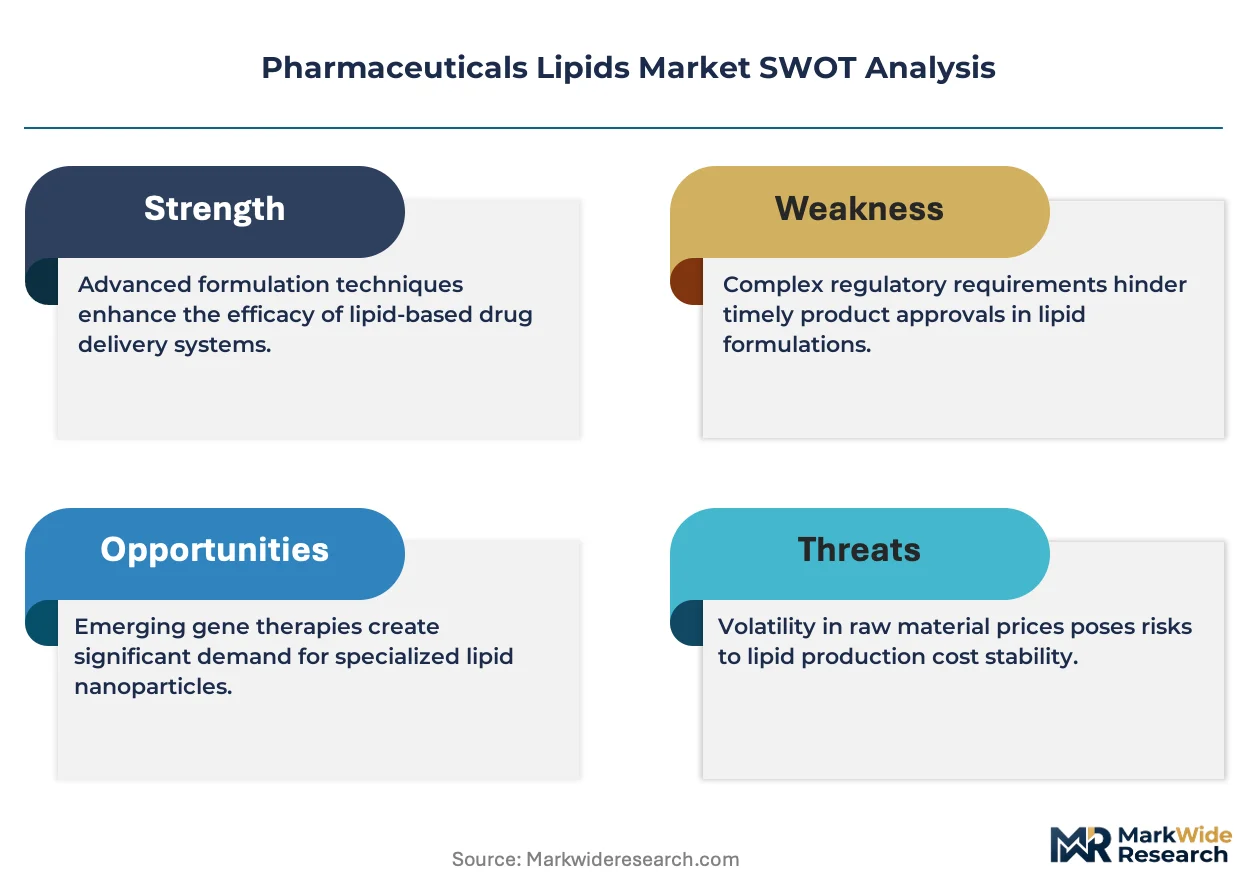
Project finance for lipid nanoparticle manufacturing facilities is narrowing the competitive field to players with capital-market access. BASF SE leverages its integrated chemical platform to control raw material costs across phospholipid production. Evonik Health Care anchors its position through dedicated lipid excipient capacity serving gene therapy developers. Croda Pharma differentiates via pharmaceutical-grade emulsion systems that meet tightening purity thresholds.
Pharmaceuticals lipids comprise amphiphilic molecules including phospholipids, fatty acids, triglycerides, and glycerol derivatives, typically synthesized through solvent extraction or enzymatic esterification to achieve defined chain lengths and saturation profiles for drug delivery matrices. Phospholipids dominate current revenue pools due to their role in liposomal and lipid nanoparticle formulations, while gene therapy applications represent the fastest-expanding demand segment driven by viral vector stabilization needs. Powder and liquid forms split the market by stability requirements, with emulsions capturing premium positioning in parenteral delivery systems.
FDA quality guidelines for complex drug substances, EMA's MDR-aligned excipient standards, and Japan's PMDA manufacturing site inspections collectively elevate barrier costs for new lipid suppliers. The EU Green Deal chemical sustainability frameworks are beginning to constrain solvent-heavy extraction processes. Stakeholders must monitor regulatory divergence between US purity benchmarks and European sustainability mandates when selecting manufacturing partners.
Market Dynamics
Pharmaceuticals lipids markets are tightening around lipid nanoparticle manufacturing capacity, where FDA quality benchmarks for complex drug substances now filter supplier pools and concentrate procurement among qualified excipient producers.
Growth Catalysts
- Lipid Nanoparticle Platforms:mRNA vaccine developers are pulling specialized phospholipid supply into long-term offtake agreements, locking manufacturing slots at dedicated facilities.
- Japan's PMDA Manufacturing Standards:Inspection protocols for pharmaceutical-grade lipid production sites are validating Japanese suppliers for global biologics export.
- Gene Therapy Viral Vector Stabilization:Synthetic lipid demand from cell and gene therapy developers is accelerating faster than traditional small-molecule applications.
Market Restraints
- Phospholipid Feedstock Concentration:Crude lecithin supply chains cluster in Southeast Asian palm and South American soybean processing regions, exposing processors to agricultural volatility.
- Solvent-Heavy Extraction Costs:EU Green Deal chemical sustainability frameworks are constraining traditional solvent extraction methods, forcing capital-intensive process redesign.
- Specialized Esterification Equipment:Enzymatic production lines for defined-chain lipids require stainless-steel reactor systems with limited qualified fabricators.
Strategic Opportunities
- India's CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore are building lipid formulation capabilities for Western biotech outsourcing.
- Continuous Processing Technology:Flow chemistry integration with lipid nanoparticle assembly is compressing batch cycle times and reducing solvent waste footprints.
- EMA MDR-Aligned Excipient Certification:European medical device regulation convergence is creating premium positioning for suppliers with dual pharmaceutical-device qualification.
Industry Challenges
- Lipid Nanoparticle Formulation Scientists:Talent scarcity in mRNA-lipid complexation and particle size distribution control is throttling capacity expansion timelines.
- Multi-Regulatory Site Qualification:Simultaneous FDA, EMA, and PMDA inspection readiness demands redundant quality management systems and documentation protocols.
- Legacy Batch Record Integration:Digital manufacturing transitions for lipid production require reconciling paper-based legacy systems with real-time process analytical technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceuticals Lipids Market |
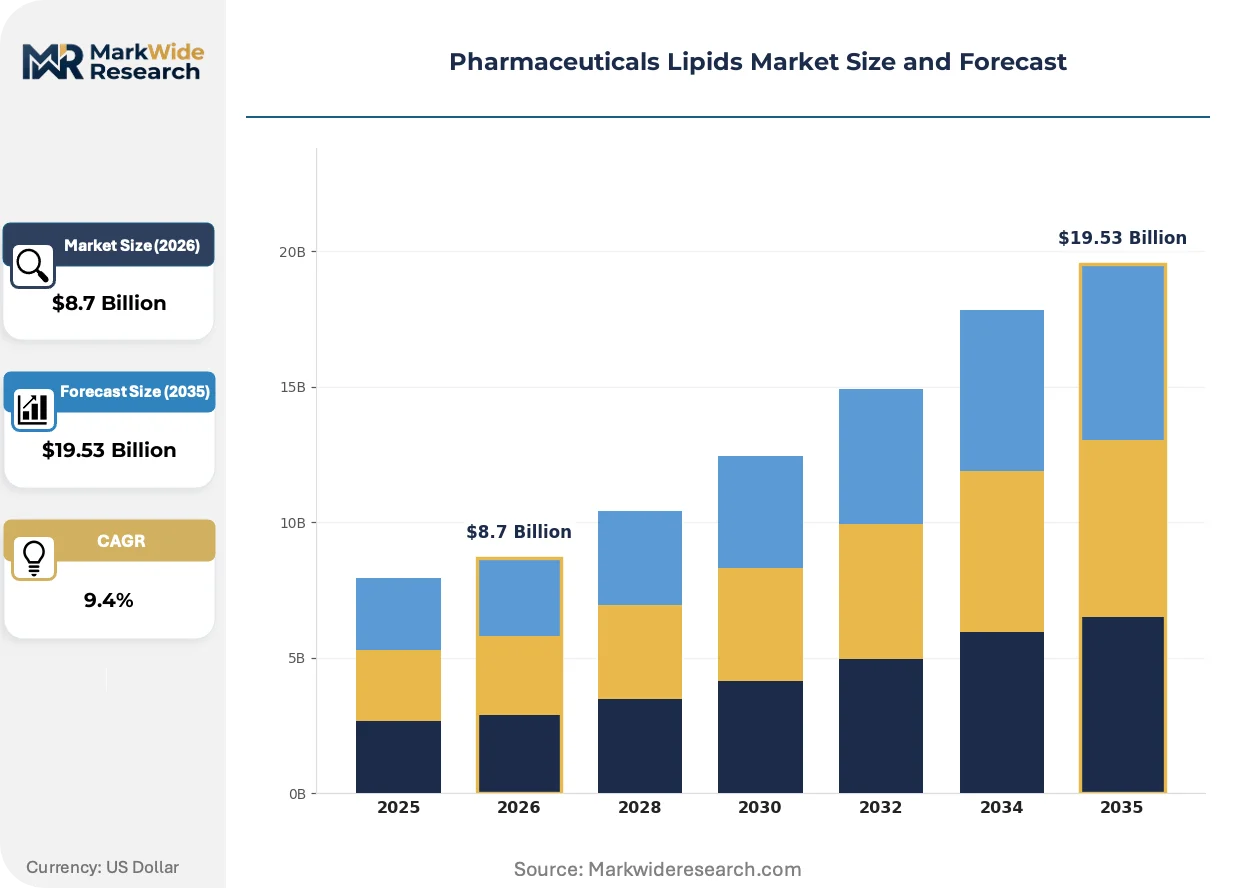
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phospholipids, Fatty Acids, Triglycerides, Glycerol End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturers, Research Institutions Application: Drug Delivery, Nutraceuticals, Gene Therapy, Vaccines Form: Liquid, Powder, Emulsions, Capsules |
| Companies Covered | Merck KGaA, BASF SE, Avanti Polar Lipids Inc., CordenPharma International GmbH, Cayman Chemical Company, Croda Pharma, Lipoid GmbH, Evonik Health Care, NOF Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceuticals Lipids Market Emerging Trajectories
Active pharmaceutical ingredient delivery is pivoting toward synthetic lipid architectures that enable precise payload release kinetics, compressing the relevance window for conventional natural-source excipients.
Microfluidic mixing technology for lipid nanoparticle assembly is migrating from academic research settings into commercial manufacturing suites. Gene therapy developers at scale-up phase are adopting these platforms to achieve monodisperse particle distributions below 100 nanometers. The shift is compressing reliance on traditional bulk homogenization equipment and favoring modular, continuous production architectures.
REACH chemical registration requirements in Europe are tightening substance identity documentation for imported lipid excipients. Suppliers must now disclose full supply chain composition data down to 0.1% w/w thresholds. Pharmaceutical-grade phospholipid importers are responding by qualifying European toll manufacturers or establishing regional synthesis capabilities to bypass documentation burdens.
Biotech procurement teams are consolidating lipid supplier panels from multi-source spot buying toward strategic partnership models with dedicated capacity allocation. Large-molecule developers are replacing transactional purchasing with multi-year offtake agreements that embed quality audit rights and process change notification clauses. This concentration is most visible among Boston and San Diego cluster companies where mRNA pipeline density exceeds regional manufacturing capacity.
Pharmaceuticals Lipids Market Segmentation
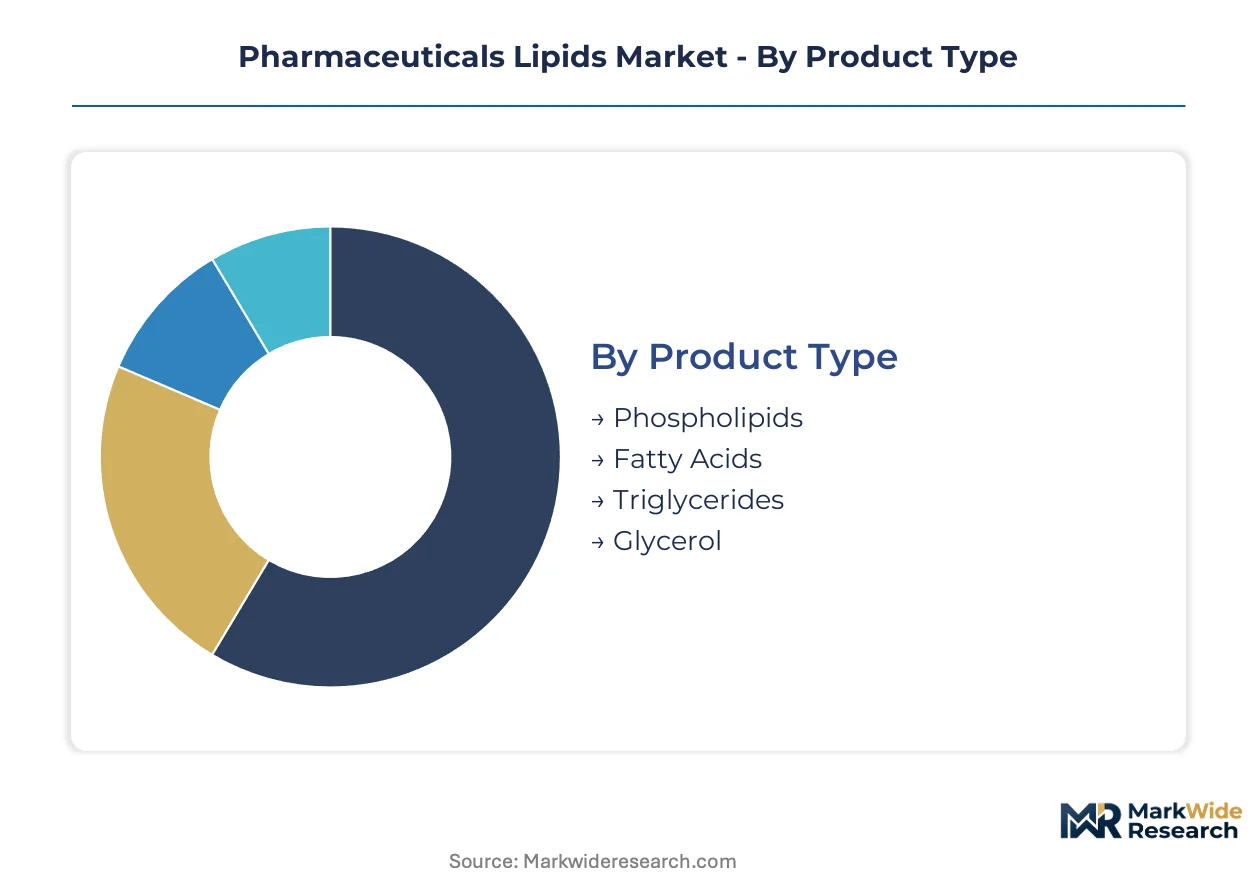
Pharmaceuticals lipids segmentation reveals how formulation requirements fragment supply chains across molecular architectures and delivery modalities. Each dimension carries distinct technical specifications, regulatory pathways, and customer procurement behaviors that reshape competitive positioning.
Product Type:
After-sales technical support intensity varies sharply across lipid chemistries, with phospholipid customers demanding ongoing formulation troubleshooting that fatty acid buyers rarely require.
- Phospholipids:Amphiphilic molecules with hydrophilic head groups and dual fatty acid tails, synthesized to defined phase transition temperatures for membrane fusion applications. Demand concentrates among mRNA vaccine developers in the United States and Germany, where lipid nanoparticle assembly requires ionizable phospholipid supply with documented impurity profiles.
- Fatty Acids:Carboxylic acid chains of defined length and saturation, purified through fractional crystallization or distillation to pharmaceutical-grade specifications. Japanese and Swiss nutraceutical manufacturers anchor volume procurement, though gene therapy viral vector stabilization is accelerating specialized demand.
- Triglycerides:Esterified glycerol backbone with three fatty acid substituents, serving as sustained-release matrices and solubility enhancers for poorly bioavailable APIs.
- Glycerol:Three-carbon polyol backbone for lipid synthesis and humectant applications in parenteral formulations, with tightening USP-NF monograph compliance requirements.
By volume, phospholipids lead. By growth pace, fatty acids for gene therapy applications are ahead.
End User:
Customer procurement sophistication spans from transactional chemical purchasing to embedded partnership models with dedicated manufacturing slots.
- Pharmaceutical Companies:Integrated biopharma operations with captive formulation development capabilities, driving qualification-heavy supplier selection and multi-year offtake structures. Large-molecule developers in Boston and Basel clusters dominate specialized phospholipid procurement.
- Biotech Firms:Venture-backed developers lacking internal manufacturing infrastructure, outsourcing lipid nanoparticle assembly to CDMOs while retaining specification control.
- Contract Manufacturers:CDMOs building dedicated lipid formulation suites in Hyderabad, Bangalore, and Research Triangle Park to capture Western biotech outsourcing.
- Research Institutions:Academic and government laboratories with small-batch, high-variability demand and limited supplier qualification resources.
Contract manufacturers are expanding capacity fastest, though pharmaceutical companies retain the highest per-account value concentration.
Application:
Clinical development stage and regulatory burden fragment demand across therapeutic modalities with divergent lipid performance requirements.
- Drug Delivery:Liposomal and lipid nanoparticle systems for oncology, infectious disease, and CNS targeting, where payload encapsulation efficiency and release kinetics determine commercial viability.
- Nutraceuticals:Omega-3 fatty acid concentrates and phospholipid complexes for dietary supplement applications, facing less stringent purity benchmarks than pharmaceutical grades.
- Gene Therapy:Viral vector stabilization and non-viral lipid nanoparticle delivery for CRISPR and mRNA therapeutics, representing the steepest expansion trajectory as pipeline candidates advance to pivotal trials.
- Vaccines:Adjuvant emulsions and mRNA lipid nanoparticle formulations, with post-pandemic demand settling at sustained levels above pre-2020 baselines.
Drug delivery commands current revenue share. Gene therapy applications are climbing the fastest.
Form:
Physical state determines stability profiles, packaging configurations, and handling protocols throughout distribution networks.
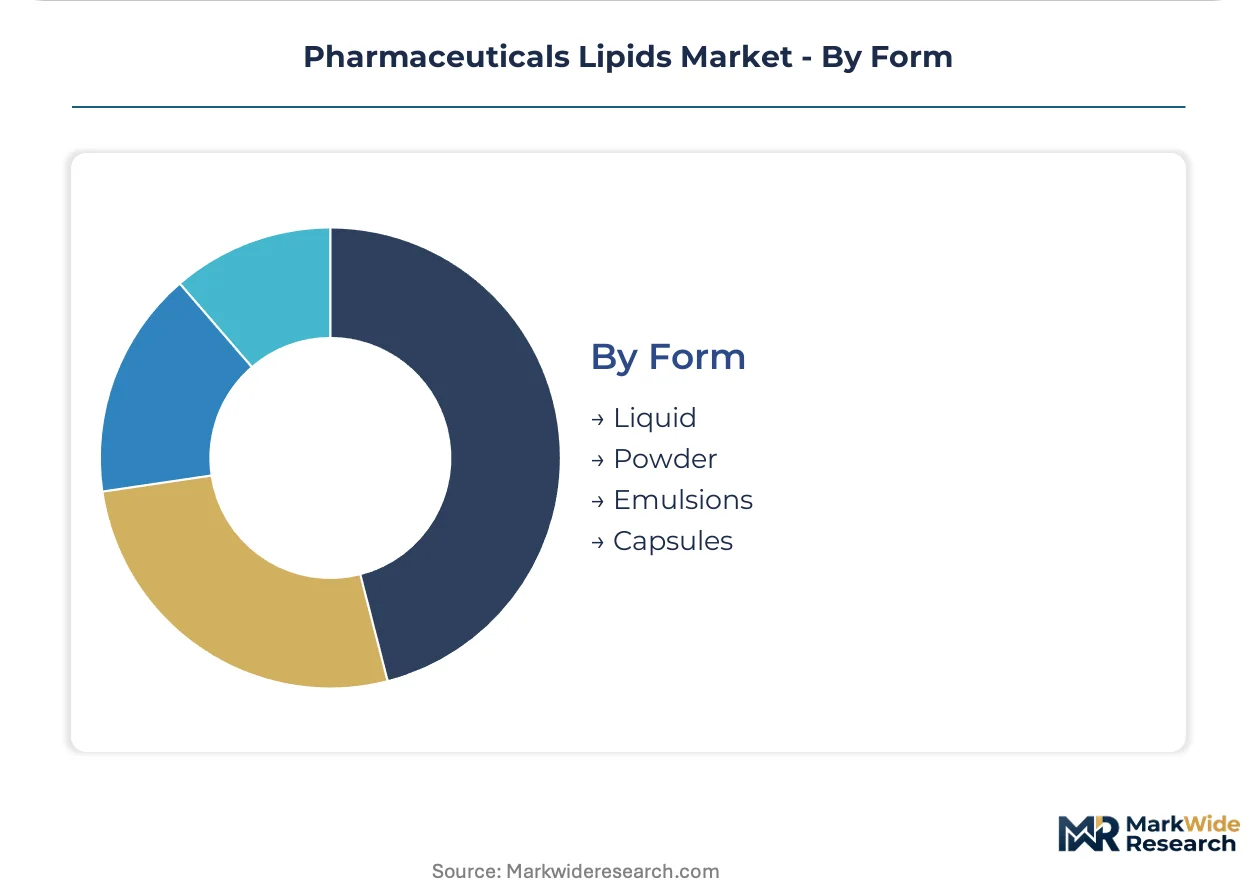
- Liquid:Bulk phospholipid dispersions and oil-phase lipids requiring nitrogen blanketing and cold-chain logistics, preferred for high-throughput manufacturing integration.
- Powder:Spray-dried or lyophilized lipid excipients with extended shelf stability, dominating international shipping routes where temperature excursion risks concentrate.
- Emulsions:Pre-formed lipid nanoparticle or liposomal dispersions, capturing premium positioning in parenteral delivery systems with particle size distribution guarantees.
- Capsules:Unit-dose softgel or hard-shell configurations for oral lipid delivery, serving nutraceutical and select pharmaceutical applications with convenience-driven demand.
Powder forms dominate cross-border trade volumes. Emulsions generate the highest value per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tax incentives for biologics manufacturing in the United States and Japan are accelerating facility investments, while EU Green Deal chemical sustainability frameworks are constraining traditional production methods. These policy vectors are redistributing lipid supply chain capacity toward jurisdictions with aligned regulatory and capital-market conditions.
United States
FDA expanded guidance on complex drug substances is elevating quality benchmarks for lipid nanoparticle suppliers, filtering procurement toward qualified excipient producers. The Inflation Reduction Act's domestic manufacturing provisions support facility construction in biotech clusters. Greater Boston and San Diego concentrate mRNA developer demand, locking manufacturing slots at dedicated phospholipid facilities.
Germany
EMA MDR-aligned excipient standards are creating premium positioning for suppliers with dual pharmaceutical-device qualification. REACH chemical registration requirements tighten substance identity documentation for imported lipids. The Rhine-Ruhr chemical corridor anchors integrated phospholipid production, with BASF SE leveraging captive raw material control across manufacturing stages.
Japan
PMDA manufacturing site inspection protocols are validating domestic suppliers for global biologics export. METI industrial policy supports lipid nanoparticle capacity expansion for gene therapy applications. The Kanto region around Tokyo concentrates formulation science talent, though scarcity in mRNA-lipid complexation expertise throttles expansion timelines.
India
CDSCO alignment with international GMP standards is enabling contract manufacturers to serve Western biotech outsourcing. PLI scheme incentives support lipid formulation capability builds in Hyderabad and Bangalore. These CDMO clusters are capturing gene therapy viral vector stabilization demand as pipeline candidates advance to pivotal trials.
Switzerland
Swissmedic pharmaceutical-grade manufacturing requirements sustain high-barrier market positioning for specialized lipid suppliers. The country's dual-accession to EU regulatory frameworks facilitates cross-border supply to German and French biopharma clusters. Basel anchors integrated biologics operations with captive formulation development capabilities.
Pharmaceuticals Lipids Market Vendor Landscape
On the supply side, the industry is consolidating around integrated chemical platforms and dedicated excipient capacity, with project finance requirements narrowing the competitive field to players with capital-market access. Three strategic archetypes dominate: diversified chemical conglomerates with backward integration into raw materials, specialized pharmaceutical-grade lipid producers with regulatory qualification depth, and contract manufacturers building regional formulation capabilities. Competitive moves concentrate on multi-year offtake agreements with embedded audit rights, and continuous processing technology adoption to compress batch cycle times.
Within the integrated chemical tier, BASF SE and Evonik Health Care exemplify archetypes combining raw material control with dedicated healthcare divisions. Croda Pharma occupies a position representing pharmaceutical-grade emulsion specialization, while Merck KGaA anchors the diversified science-and-technology conglomerate segment with life sciences exposure. Avanti Polar Lipids Inc. sits within the specialized phospholipid producer tier focused on lipid nanoparticle formulations.
| Leading Market Players |
|---|
| Merck KGaA |
| BASF SE |
| Avanti Polar Lipids Inc. |
| CordenPharma International GmbH |
| Cayman Chemical Company |
| Croda Pharma |
| Lipoid GmbH |
| Evonik Health Care |
| NOF Corporation |
| Others |
Supply Flow & Price Mechanics
Southeast Asian palm and South American soybean processing regions concentrate crude lecithin feedstock, anchoring margin pools with phospholipid refiners who command premium positioning through FDA-grade certification and documented impurity profiles. This upstream concentration translates directly into pricing power for qualified excipient producers serving mRNA vaccine developers.
Pricing Analysis
Certification level creates the primary spread, with FDA-grade phospholipids commanding substantial premiums over food-grade alternatives. Pricing stratifies across pharmaceutical-grade, technical-grade, and feedstock tiers, where ionizable lipid specifications for lipid nanoparticle assembly sit at the apex. Cost compression in technical-grade segments is intensifying because CDMOs in India are expanding enzymatic esterification capacity. Biotech firms exhibit the highest price sensitivity due to venture-funded budget constraints, while integrated pharmaceutical companies prioritize supply security over unit cost.
Supply Chain Analysis
Agricultural volatility across Malaysian and Indonesian palm estates and Argentinian soybean belts dominates supply chain risk exposure for phospholipid feedstocks. Crude lecithin, degummed vegetable oils, and specialized fatty acid methyl esters constitute the critical input trinity. Single-source vulnerability concentrates around enzymatic catalyst suppliers and stainless-steel reactor fabricators qualified for pharmaceutical production. Distribution runs through regional chemical distributors with cold-chain capabilities, consolidating at biologics manufacturing clusters in Greater Boston, Basel, and the Kanto region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment defines this market's defensive moat, as simultaneous FDA, EMA, and PMDA qualification creates switching costs that lock in incumbent suppliers for multi-year contract cycles.
For Market Incumbents: Entrench market position by deepening backward integration into Southeast Asian palm processing assets to secure feedstock cost advantage against emerging Indian CDMOs. Expand dedicated lipid nanoparticle capacity in the Rhine-Ruhr corridor to capture EMA MDR-aligned excipient premiums. Prioritize continuous processing technology adoption to compress batch cycle times and defend margin position against solvent-heavy extraction cost pressures from EU Green Deal frameworks.
For New Entrants and Emerging Players: Pursue white-space opportunities in gene therapy viral vector stabilization lipids, where demand acceleration outpaces qualified supplier capacity. Target Hyderabad and Bangalore CDMO partnerships as the most penetrable entry channel, leveraging PLI scheme incentives and Western biotech outsourcing momentum. Lead with microfluidic mixing technology differentiation to bypass legacy homogenization equipment barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized phospholipid producers with existing FDA master file documentation and lipid nanoparticle formulation expertise, given the decade-long viability window for mRNA and gene therapy platform expansion. Monitor CDSCO GMP alignment progress and PMDA inspection validation rates as inflection indicators for Indian supplier qualification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | mRNA developers lock manufacturing slots through multi-year phospholipid offtake contracts with embedded audit rights. |
| Backward Integration | Integrated chemical platforms control crude lecithin costs across Malaysian and Indonesian processing assets. |
| Regulatory Approval Pathway | Dual FDA-EMA excipient qualification creates premium positioning for lipid nanoparticle suppliers. |
| Manufacturing Scale-Up | Continuous flow chemistry integration reduces solvent waste footprints and compresses batch cycle times. |
| Joint Venture | Western biotechs partner with Hyderabad CDMOs to access PLI-subsidized lipid formulation capacity. |
Methodological Framework
A standing panel of lipid formulation scientists, pharmaceutical procurement directors, CDMO operations managers, and regulatory affairs specialists provided ongoing calibration against operating reality. Primary interviews with these stakeholders combined with secondary validation from FDA drug master file databases, EMA excipient certification registries, PMDA manufacturing site inspection reports, and customs trade data for phospholipid imports. Bottom-up volume modeling across product types and top-down market sizing triangulated to convergence.
Scenario bracketing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning molecular architecture, therapeutic application, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating gene therapy pipeline advancement rates, lipid nanoparticle manufacturing capacity buildouts, and evolving FDA guidance on complex drug substances. Industry-specific inputs included mRNA vaccine developer offtake patterns and enzymatic esterification technology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, biotech venture funding availability, or pharmaceutical capital expenditure cycles would shift the trajectory. Forecasts reflect assumptions about regulatory harmonization pace and sustained gene therapy clinical advancement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Mail Order Pharmacy Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Seropositive Rheumatoid Arthritis Drug Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Cefazedone Sodium Market
Pharmaceuticals
Isotretinoin Drugs Market