
 US Sex Reassignment Hormone Therapy Market | 2026-2036
US Sex Reassignment Hormone Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
US Sex Reassignment Hormone Therapy Market Insights
Specialty pharmacy distribution is reconfiguring around direct-to-patient fulfillment models for hormone therapy. Viatris Inc. leverages its generic injectable portfolio to control cost-sensitive segments. AbbVie Inc. anchors transgender care through its established testosterone franchise. Pfizer Inc. competes on manufacturing scale for parenteral estrogen formulations.
US sex reassignment hormone therapy comprises exogenous administration of estrogen, testosterone, anti-androgens, and progesterone to induce secondary sex characteristics aligned with gender identity, typically requiring sustained serum hormone levels within target ranges over months to years. The primary purpose is clinical management of gender dysphoria under endocrinological supervision. Injectable delivery mode dominates hospital and clinic settings due to precise dosing control and reliable pharmacokinetics. Transdermal patches represent the fastest-expanding segment in home care environments where patient self-administration and steady-state absorption matter. Orals retain mature volume in pharmacy-dispensed maintenance protocols where convenience outweighs peak-trough variability.
FDA approval pathways, DEA scheduling requirements for testosterone, and state-level scope-of-practice laws governing nurse practitioner prescribing collectively shape product access and formulary placement. CMS reimbursement determinations and private payer prior authorization protocols further constrain which delivery modes and settings patients can access. Stakeholders must monitor evolving state legislation on gender-affirming care restrictions and their downstream effects on prescriber availability and pharmacy network participation.
Market Dynamics
FDA guidance on compounded bioidentical hormones is reshaping prescriber behavior and distribution models across hospital-based endocrinology departments and specialty pharmacy networks. State-level scope-of-practice laws governing nurse practitioner prescribing are fragmenting access corridors, creating geographic winners and losers in patient intake capacity.
Growth Catalysts
- Expanded Gender-Affirming Clinic Protocols:Pacific Northwest and Northeast hospital systems are standardizing multidisciplinary intake workflows, reducing time-to-treatment initiation for hormone therapy candidates.
- DEA Scheduling Reforms:Proposed relaxations on testosterone distribution are enabling broader pharmacy network participation beyond specialty locked-in channels.
- Transdermal Patch Innovation:Steady-state absorption profiles in home care settings are extending patient self-administration viability and reducing clinic visit burden.
Market Restraints
- API Supply Concentration:Estradiol and testosterone active pharmaceutical ingredient manufacturing concentrates among three overseas bulk suppliers, exposing formulators to geopolitical disruption risk.
- State Legislative Fragmentation:Gender-affirming care restriction bills in multiple statehouses are constraining prescriber availability and forcing patient relocation to permissive jurisdictions.
- Reimbursement Compression:CMS reimbursement determinations for injectable delivery modes lag acquisition costs, pressuring hospital formulary placement decisions.
Strategic Opportunities
- Direct-to-Patient Fulfillment Models:Specialty pharmacies are bypassing traditional wholesale distribution to capture margin and improve adherence monitoring through integrated digital platforms.
- Anti-Androgen Combination Protocols:Emerging clinical evidence for progesterone-spironolactone regimens is opening formulation white space beyond monotherapy dominance.
- Telehealth Prescribing Expansion:Interstate licensure compacts are enabling virtual endocrinology consultations for rural and underserved patient populations in Mountain West and Deep South sub-regions.
Industry Challenges
- Endocrinology Workforce Scarcity:Fellowship-trained specialists in transgender medicine remain concentrated in coastal academic medical centers, creating appointment backlogs exceeding six months in interior states.
- Compounding Pharmacy Compliance Burden:USP <797> sterile compounding standards and state board inspection frequency are elevating operational costs for customized parenteral formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sex Reassignment Hormone Therapy Market |
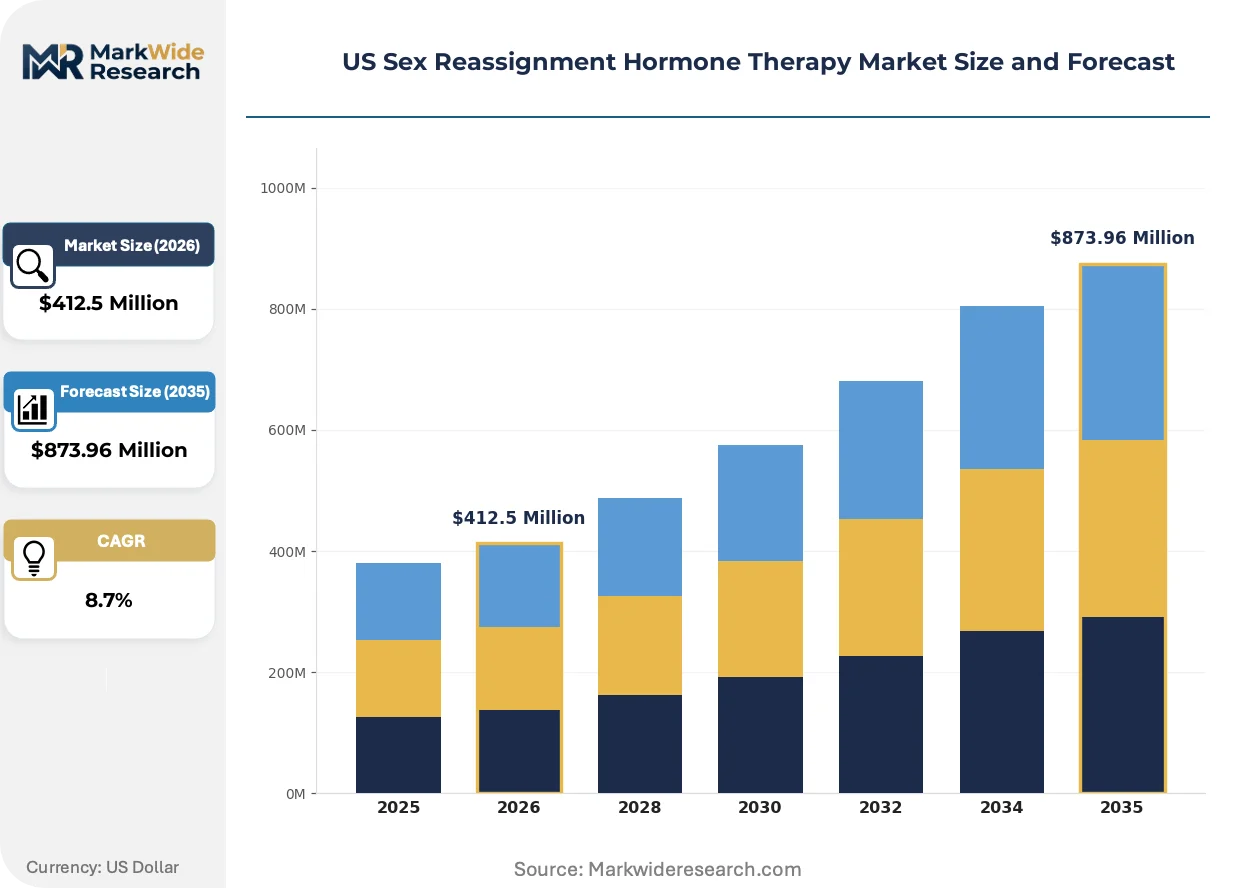
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Estrogen, Testosterone, Anti-Androgens, Progesterone Delivery Mode: Injectables, Orals, Transdermal Patches, Gels End User: Hospitals, Clinics, Home Care, Pharmacies Regulatory Approval: FDA Approved, Off-Label Use, Clinical Trials, Research Use |
| Companies Covered | Viatris Inc., AbbVie Inc., ASCEND Therapeutics US, LLC., Pfizer Inc., Novartis AG, Eli Lilly and Company, Endo International plc, Halozyme Therapeutics, Inc., Besins Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sex Reassignment Hormone Therapy Market Trends and Innovations
Delivery mode innovation and regulatory clarity are compressing traditional care pathways, enabling patient-managed protocols that bypass conventional clinic-centric models. Technology convergence with remote monitoring is collapsing geographic barriers to specialist access.
Subcutaneous hormone pellet implants are collapsing the injection frequency burden for maintenance-phase patients. Community health centers in Texas and Florida are adopting this modality to reduce nursing staff time allocation. The technology is collapsing the distinction between acute clinical supervision and chronic self-management, enabling quarterly rather than weekly patient touchpoints.
FDA draft guidance on 503B outsourcing facility compounding is clarifying permissible hormone formulation categories for bulk manufacturing. Hospital systems are reconfiguring procurement toward registered 503B facilities to reduce in-house compounding liability. California and Massachusetts providers are most affected, accelerating vendor qualification timelines to secure supply continuity.
Patient-driven protocol switching is disrupting traditional prescriber-controlled titration models. Transgender health platforms are enabling direct laboratory result sharing and dose adjustment requests, compressing the physician intermediary role. This behavioral shift is most visible in New York and Washington state markets where digital health infrastructure penetration is highest among gender-diverse patient populations.
US Sex Reassignment Hormone Therapy Market Segmentation
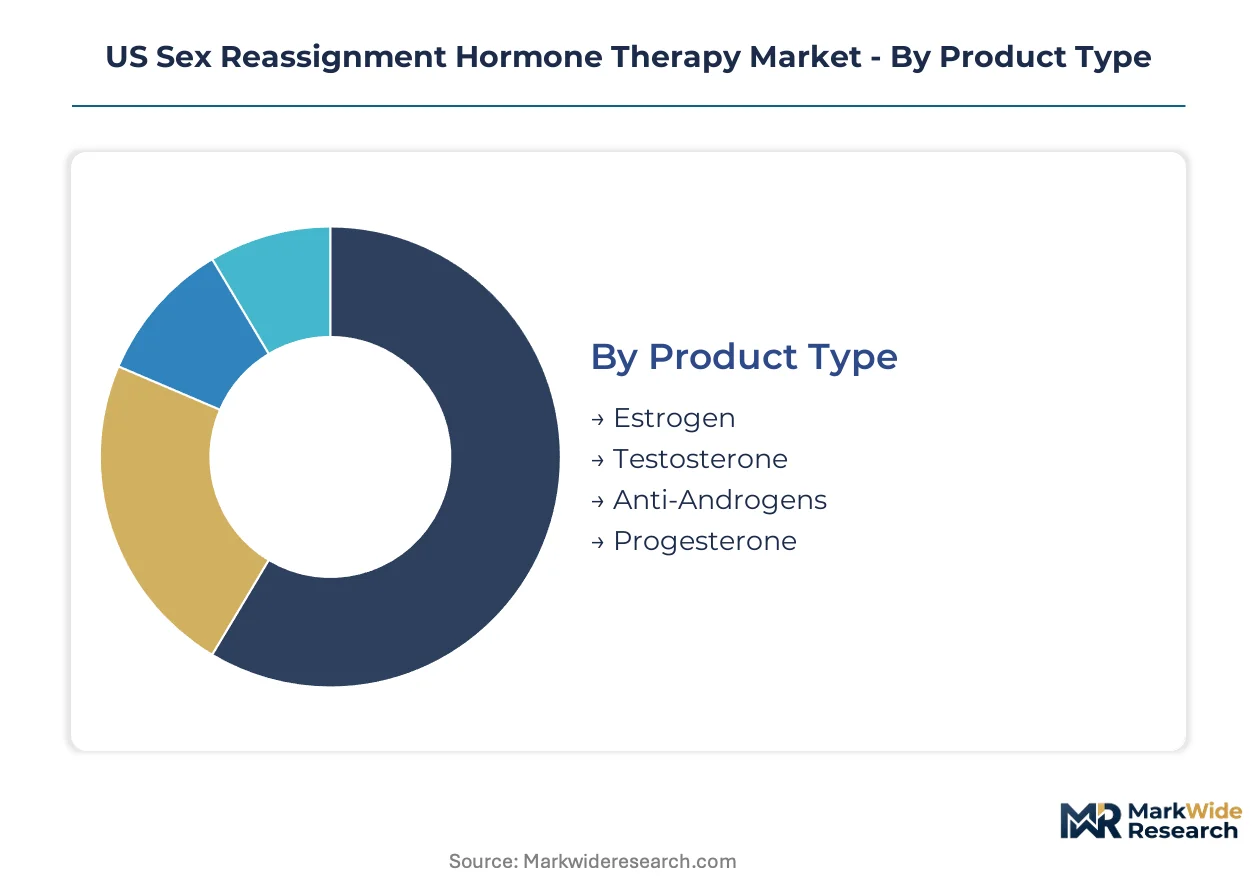
Hormone therapy segmentation in the US reveals distinct procurement cycles and prescriber preferences across product categories. Delivery mode selection directly determines reimbursement pathways and patient adherence profiles, making granular segment understanding essential for formulary positioning.
Product Type:
Cycle times vary sharply across hormone classes, with testosterone formulations turning over fastest due to DEA scheduling constraints and inventory limits, while progesterone protocols move slowest given narrower prescriber familiarity.
- Estrogen:Estradiol valerate and cypionate formulations dominate hospital-based feminization protocols. Demand concentrates in California and New York endocrinology departments where multidisciplinary clinic density supports complex titration regimens. CMS reimbursement gaps for injectable estradiol create formulary friction in Massachusetts hospital systems.
- Testosterone:DEA Schedule III classification drives 30-day dispensing limits and specialty pharmacy lock-in. Pacific Northwest gender-affirming clinics favor long-acting testosterone undecanoate for reduced injection frequency. Proposed DEA scheduling reforms threaten to fragment current distribution economics.
- Anti-Androgens:Spironolactone anchors standard-of-care testosterone suppression in most US protocols.
- Progesterone:Micronized formulations remain concentrated in research-oriented academic medical centers with active transgender health divisions.
Testosterone anchors the volume base while progesterone gains share at the steepest rate as clinical evidence accumulates for feminization enhancement.
Delivery Mode:
Cost tier stratification separates hospital-procured injectables from retail-dispensed orals and direct-to-patient transdermal systems, with reimbursement spread determining access corridors.
- Injectables:Intramuscular and subcutaneous formulations enable precise serum level targeting in supervised clinical settings. Hospital endocrinology departments in California and Massachusetts standardize on injectable protocols for treatment initiation phases. Nursing staff time allocation drives quarterly pellet implant adoption in Texas community health centers.
- Orals:Convenience positioning supports pharmacy-dispensed maintenance where patient self-management outweighs pharmacokinetic precision. New York and Washington state markets show highest oral protocol persistence among insured populations with stable employment.
- Transdermal Patches:Steady-state absorption profiles reduce peak-trough variability for home-based patients.
- Gels:Topical testosterone gel competes on patient autonomy and reduced clinic visit burden.
Injectables retain the dominant revenue position while transdermal patches expand most quickly as home care protocols gain prescriber acceptance.
End User:
Customer type segmentation maps directly to prescriber credential requirements and state scope-of-practice laws, fragmenting access by geography.
- Hospitals:Academic medical centers anchor complex case management with fellowship-trained endocrinologists. California, New York, and Massachusetts hospital systems concentrate transgender medicine expertise, creating six-month appointment backlogs that push patients to alternative settings.
- Clinics:Federally qualified health centers in Texas and Florida adopt pellet implant protocols to extend nursing capacity. Pacific Northwest independent gender-affirming clinics standardize multidisciplinary intake workflows reducing time-to-treatment initiation.
- Home Care:Patient self-administration concentrates among transdermal and oral protocol adherents with established dosing stability.
- Pharmacies:Specialty pharmacy networks capture hormone therapy distribution through direct-to-patient fulfillment models with integrated adherence monitoring.
Hospitals anchor the volume base while home care gains share at the steepest rate as remote monitoring technology collapses geographic barriers to specialist oversight.
Regulatory Approval:
Supply concentration among 503B outsourcing facilities and compounders creates tiered risk profiles that reshape procurement toward registered bulk manufacturers.
- FDA Approved:Manufactured formulations from Viatris, AbbVie, and Pfizer anchor hospital formulary placement and prior authorization compliance. Commercial payers require FDA-approved products for reimbursement in most state Medicaid programs.
- Off-Label Use:Progesterone protocols and spironolactone dosing regimens frequently operate outside original indication approvals. Prescriber liability concerns concentrate off-label practice in academic medical centers with institutional review capacity.
- Clinical Trials:Investigational hormone formulations recruit through coastal gender medicine research consortia.
- Research Use:Laboratory and academic applications remain marginal to commercial market volume.
FDA Approved products anchor the volume base while Off-Label Use climbs the fastest as prescriber experience accumulates beyond original trial populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California and Massachusetts hospital systems where multidisciplinary clinic density supports premium formulary placement, while Texas and Florida community health centers compete on nursing efficiency and pellet implant protocols to offset reimbursement compression.
California
Academic medical centers in Los Angeles and San Francisco anchor complex feminization protocols requiring fellowship-trained endocrinologists. FDA guidance on compounded bioidentical hormones is accelerating procurement shifts toward registered 503B outsourcing facilities. Stanford and UCSF Medical Center concentrate transgender medicine expertise, creating six-month appointment backlogs that push patients to telehealth alternatives.
New York
Hospital-based endocrinology departments in Manhattan and Brooklyn standardize on injectable estradiol valerate for treatment initiation phases. State Medicaid programs require FDA-approved products for reimbursement, locking formulary placement to manufactured formulations. Mount Sinai and Callen-Lorde Community Health anchor patient intake protocols, with digital health infrastructure enabling direct laboratory result sharing and dose adjustment requests.
Massachusetts
Massachusetts General Hospital and Fenway Health concentrate research-oriented progesterone protocols operating outside original indication approvals. CMS reimbursement gaps for injectable estradiol create formulary friction that pressures procurement toward oral maintenance alternatives. Boston's transgender health research consortia recruit for investigational hormone formulations, drawing patient migration from interior states.
Texas
Community health centers in Houston and Dallas adopt subcutaneous hormone pellet implants to reduce nursing staff time allocation and extend quarterly rather than weekly patient touchpoints. State legislative restrictions on gender-affirming care are constraining prescriber availability and forcing patient relocation to permissive jurisdictions. Planned Parenthood Gulf Coast and Legacy Community Health anchor care delivery despite regulatory pressure.
Pacific Northwest
Oregon and Washington independent gender-affirming clinics standardize multidisciplinary intake workflows, reducing time-to-treatment initiation for hormone therapy candidates. Interstate licensure compacts enable virtual endocrinology consultations for rural populations in Idaho and Montana sub-regions. Seattle's Polyclinic and Portland's Q Center concentrate prescriber capacity where digital health infrastructure penetration is highest among gender-diverse patient populations.
US Sex Reassignment Hormone Therapy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying active pharmaceutical ingredients and delivery mechanisms. The market structures around three concentration points: generic injectable manufacturers serving cost-sensitive hospital segments, established hormone franchises anchoring prescriber relationships, and scale-driven parenteral formulators competing on manufacturing throughput. Strategic moves center on direct-to-patient fulfillment model expansion and 503B outsourcing facility partnerships to reduce compounding liability.
Among the named pharmaceutical manufacturers, Viatris Inc. and AbbVie Inc. occupy positions representing distinct competitive archetypes. Viatris anchors the generic injectable portfolio tier where cost-sensitive hospital procurement decisions concentrate. AbbVie exemplifies the established testosterone franchise model that transgender care protocols increasingly reference. Pfizer Inc. sits within the scale-driven parenteral formulation segment where manufacturing volume determines competitive positioning against 503B facility alternatives.
| Leading Market Players |
|---|
| Viatris Inc. |
| AbbVie Inc. |
| ASCEND Therapeutics US, LLC. |
| Pfizer Inc. |
| Novartis AG |
| Eli Lilly and Company |
| Endo International plc |
| Halozyme Therapeutics, Inc. |
| Besins Healthcare |
| Others |
Pricing and Supply Chain Analysis
Overseas API manufacturing clusters in China and India anchor bulk estradiol and testosterone supply, concentrating pricing power among three dominant suppliers whose capacity constraints ripple through US hospital formulary negotiations. This geographic concentration amplifies cost volatility when geopolitical friction disrupts shipping lanes or customs clearance protocols.
Pricing Analysis
The customization-premium spread separates compounded parenteral formulations from manufactured standard products. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery mode complexity and prescriber credential requirements. Pricing pressure stems from CMS reimbursement gaps for injectable estradiol that lag acquisition costs in Massachusetts and California hospital systems. Federally qualified health centers in Texas exhibit highest price sensitivity due to constrained Medicaid formulary budgets, while academic medical centers in New York anchor the least sensitive tier through research grant offsets.
Supply Chain Analysis
Contract-manufacturing concentration for sterile hormone formulations rests with registered 503B outsourcing facilities in California and Massachusetts. Active pharmaceutical ingredient production draws from China, India, and Italy for estradiol derivatives and testosterone esters. Raw material dependencies center on soy and yam-derived sterol precursors, sesame oil injection vehicles, and specialized transdermal adhesive polymers. Single-source vulnerability concentrates in overseas API suppliers subject to FDA import alert risk. Distribution runs through specialty pharmacy direct-to-patient fulfillment models that bypass traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US sex reassignment hormone therapy market represents an early-cycle expansion story where telehealth prescribing infrastructure and interstate licensure compacts are collapsing geographic barriers to specialist access faster than workforce training can supply qualified endocrinologists.
For Market Incumbents: Build prescriber relationship moats through fellowship-trained endocrinologist network exclusivity in coastal academic medical centers. Anchor hospital formulary placement against 503B facility competition by securing FDA-approved product prior authorization compliance in state Medicaid programs. Expand direct-to-patient fulfillment capacity to capture margin from specialty pharmacy lock-in threatened by proposed DEA scheduling reforms on testosterone distribution.
For New Entrants and Emerging Players: Rural Mountain West and Deep South sub-regions present the most penetrable geographic white space where interstate licensure compacts enable virtual consultation models without physical clinic infrastructure. Target community health center procurement in Texas and Florida where pellet implant protocols reduce nursing staff burden and create adherence advantages over injection-dependent competitors. Pursue 503B outsourcing facility partnerships to enter hospital supply chains without manufacturing capital requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty pharmacy platforms with integrated adherence monitoring and direct-to-patient fulfillment infrastructure. Long-term viability over a multi-year horizon favors acquisition targets with established 503B registration and hospital system vendor qualification in place. Watch for state legislative inflection signals where gender-affirming care restriction bills force patient migration patterns toward permissive jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| 503B Outsourcing Facility Partnership | Reduces in-house compounding liability for California hospital systems facing USP <797> compliance burdens. |
| Telehealth Prescribing Platform Expansion | Captures rural patient populations in Idaho and Montana through interstate licensure compact leverage. |
| Direct-to-Patient Fulfillment Model | Bypasses wholesale distribution to capture margin and improve adherence monitoring via digital platforms. |
| Pellet Implant Protocol Adoption | Reduces nursing staff time allocation in Texas community health centers facing reimbursement compression. |
| Anti-Androgen Combination Development | Opens formulation white space beyond monotherapy dominance through progesterone-spironolactone evidence accumulation. |
Research Methodology
Initial hypotheses were tested against primary input from hospital endocrinology department directors, specialty pharmacy procurement managers, 503B facility compliance officers, and gender-affirming clinic operations leads and refined through secondary validation against FDA guidance documents, DEA controlled substance distribution reports, state board of pharmacy inspection records, and CMS reimbursement determination databases. Bottom-up patient volume estimates from hospital discharge data were triangulated with top-down pharmaceutical manufacturer shipment reports.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling patient intake capacity constraints against API manufacturing throughput and 503B facility sterility assurance capacity. Segmentation dimensions included hormone class, delivery mode, end-user setting, and state regulatory environment cluster. CAGRs were derived from patient population growth trajectories and prescriber workforce expansion rates. Forecast inputs incorporated FDA draft guidance implementation timelines and state legislative session calendars for gender-affirming care restriction bills.
The forecast holds incumbent behavior within observed patterns; aggressive moves by telehealth-first platforms or large hospital system consolidators would shift outcomes through rapid patient volume capture. Quarterly review of state legislative filing activity, 503B facility inspection citation trends, and DEA scheduling reform proposal advancement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Proton Pump Inhibitors Market
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Latin America Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Hepatic Antiviral Drugs Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Farm Animal Drugs Market