
 Oral Contraceptive Pills Market | 2026-2036
Oral Contraceptive Pills Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Contraceptive Pills Market Intelligence
Pharmacy-to-digital distribution channels is reconfiguring how oral contraceptive pills reach end users. Bayer AG leverages its manufacturing scale to sustain supply chain control across European and North American markets. Pfizer Inc. competes through R&D intensity in extended-cycle formulations. Teva Pharmaceutical Industries Ltd. anchors its position in generic progestin-only segments through cost-competitive production.
Oral contraceptive pills are synthetic hormone formulations, typically combining ethinyl estradiol with progestin compounds or containing progestin alone, designed to suppress ovulation and alter cervical mucus properties for pregnancy prevention. Combined pills dominate current prescription volumes due to established clinical familiarity and broader non-contraceptive indications, while extended cycle pills represent the fastest-growing product type as women seek reduced menstruation frequency. Applications for polycystic ovary syndrome and endometriosis management command premium positioning through off-label reimbursement pathways. Family planning clinics and gynecology centers remain the primary end-user channels where clinical counseling drives product selection.
The FDA oversees new drug applications and risk management protocols for hormonal contraceptives in the United States, while the EMA governs centralized marketing authorizations across European member states through its Committee for Medicinal Products for Human Use. India's CDSCO implements phased strengthening of good manufacturing practice inspections for domestic and export-oriented pill producers. Stakeholders must monitor how evolving pharmacovigilance requirements for thromboembolic risk labeling reshape product portfolios and geographic market access priorities.
Market Dynamics
Pharmacy-to-digital channel migration is compressing traditional distribution margins while FDA Risk Evaluation and Mitigation Strategy requirements for estrogen formulations reshape product portfolios and geographic access priorities.
Growth Catalysts
- Extended-cycle formulations:Women seeking reduced menstruation frequency drive prescription volume toward 84-day and 365-day regimens, expanding addressable demand beyond conventional 28-day cycles.
- Polycystic ovary syndrome management:Off-label reimbursement pathways for hormonal therapy in endocrine clinics create premium positioning opportunities for combined oral contraceptives with anti-androgenic progestins.
- EMA centralized marketing authorizations:Streamlined approval pathways across European member states accelerate cross-border product launches and reduce regulatory fragmentation for multinational manufacturers.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for ethinyl estradiol concentrates in Chinese and Indian contract manufacturers, exposing formulators to geopolitical disruption and customs delays.
- Thromboembolic risk labeling:FDA-mandated black box warnings for venous thromboembolism in estrogen-containing products constrain prescribing enthusiasm among risk-averse clinicians in family planning settings.
- Long-acting reversible contraceptives:Intrauterine devices and subdermal implants displace oral pill prescriptions among nulliparous women seeking set-and-forget alternatives with lower daily adherence burden.
Strategic Opportunities
- Telehealth direct-to-patient channels:Digital pharmacies bypass traditional clinic gatekeepers, capturing prescription volume from time-constrained urban professionals seeking asynchronous consultation models.
- Progestin-only mini-pill expansion:Lactating women and estrogen-contraindicated patients represent underpenetrated segments where norethindrone and drospirenone formulations command loyalty through tolerability advantages.
- India CDSCO GMP strengthening:Phased inspection intensity upgrades for domestic manufacturers create first-mover advantages for export-oriented producers achieving PIC/S equivalence ahead of compliance deadlines.
Industry Challenges
- Pharmacovigilance signal detection:Post-market surveillance requirements for rare adverse events demand specialized epidemiology capabilities that strain mid-tier generic manufacturers without dedicated safety departments.
- Cold chain integrity for clinical trial materials:Temperature-controlled logistics for bioequivalence studies of novel progestin analogs impose capital requirements that extend development timelines for abbreviated new drug applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Contraceptive Pills Market |
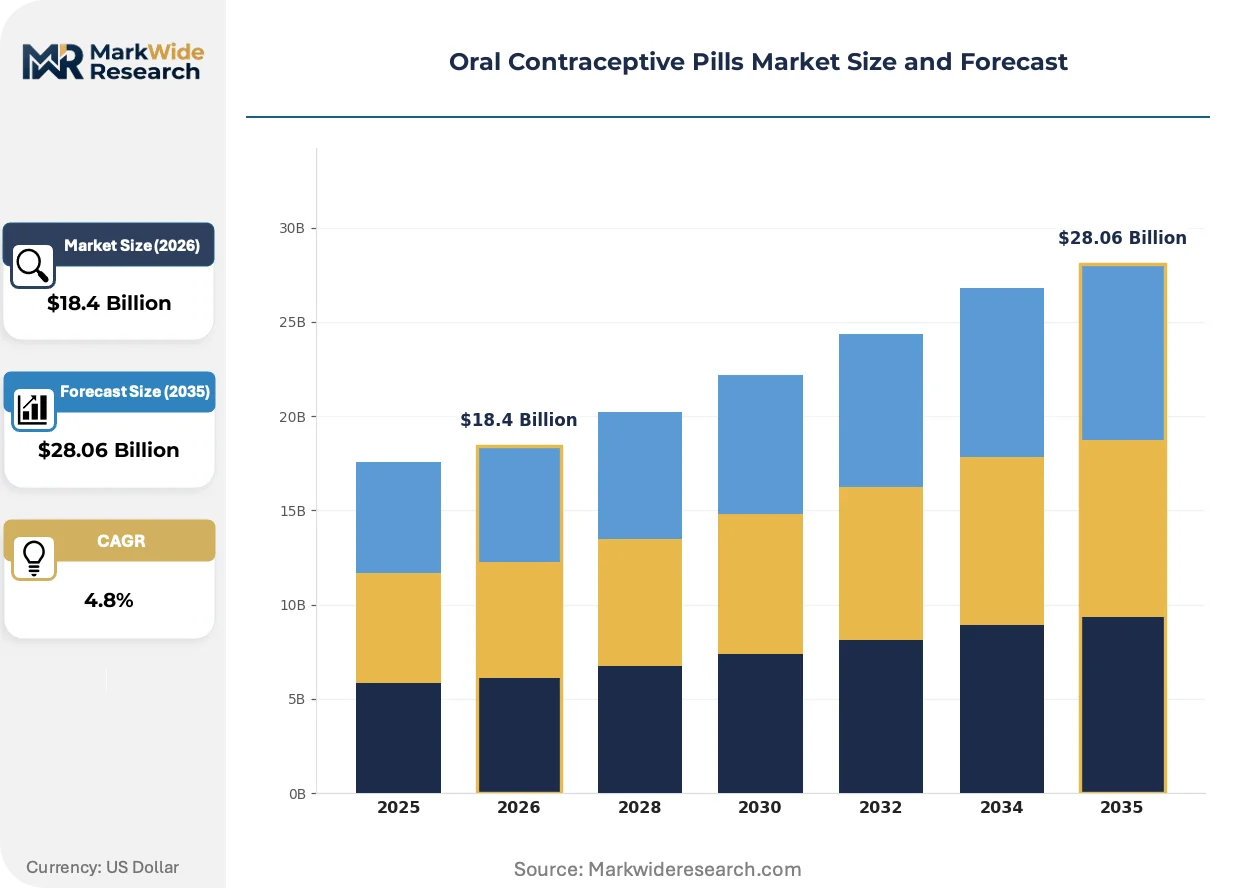
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $28.06 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combined Pills, Progestin-Only Pills, Extended Cycle Pills, Continuous Cycle Pills Application: Birth Control, Menstrual Regulation, Acne Treatment, Endometriosis Management, Polycystic Ovary Syndrome End User: Family Planning Clinics, Gynecology Centers, Hospitals, Private Practitioners, Health Awareness Programs Distribution Channel: Pharmacies, Online Retailers, Hospitals Pharmacies, Wellness Centers, Community Health Stores |
| Companies Covered | Bayer AG, Pfizer Inc., Merck & Co. Inc., Johnson & Johnson, Teva Pharmaceutical Industries Ltd., Allergan plc, Cipla Inc., Lupin Limited, Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Contraceptive Pills Market Strategic Shifts & Innovations
Formulation science and regulatory science are converging to compress development cycles while digital health infrastructure reconfigures patient access pathways and clinical data capture.
Continuous-delivery oral systems utilizing solubility-enhancing polymer matrices are collapsing the distinction between daily pills and long-acting alternatives. Early-stage biopharmaceutical developers in Massachusetts and Basel are piloting month-long formulations with zero-order release kinetics. Women's health clinics in academic medical centers are accelerating adoption timelines through investigator-initiated trials that bypass traditional phase sequencing.
EMA's strengthened pharmacovigilance requirements under the Good Pharmacovigilance Practices guideline are mandating real-world evidence collection through patient registries. Marketing authorization holders must now submit periodic safety update reports with active surveillance data rather than passive adverse event reporting. Combined oral contraceptive sponsors with established European infrastructure are absorbing compliance costs while smaller applicants delay centralized procedures pending clarity on registry implementation standards.
Subscription-based contraceptive delivery is displacing pharmacy counter pickup among digitally native cohorts. Nurx, Hers, and analogous platforms bundle asynchronous provider consultation, automated refill scheduling, and discreet home delivery into single monthly fees. Urban markets with high smartphone penetration and insurance carve-outs for telehealth services exhibit the fastest migration away from traditional clinic-pharmacy pathways.
Oral Contraceptive Pills Market Segmentation
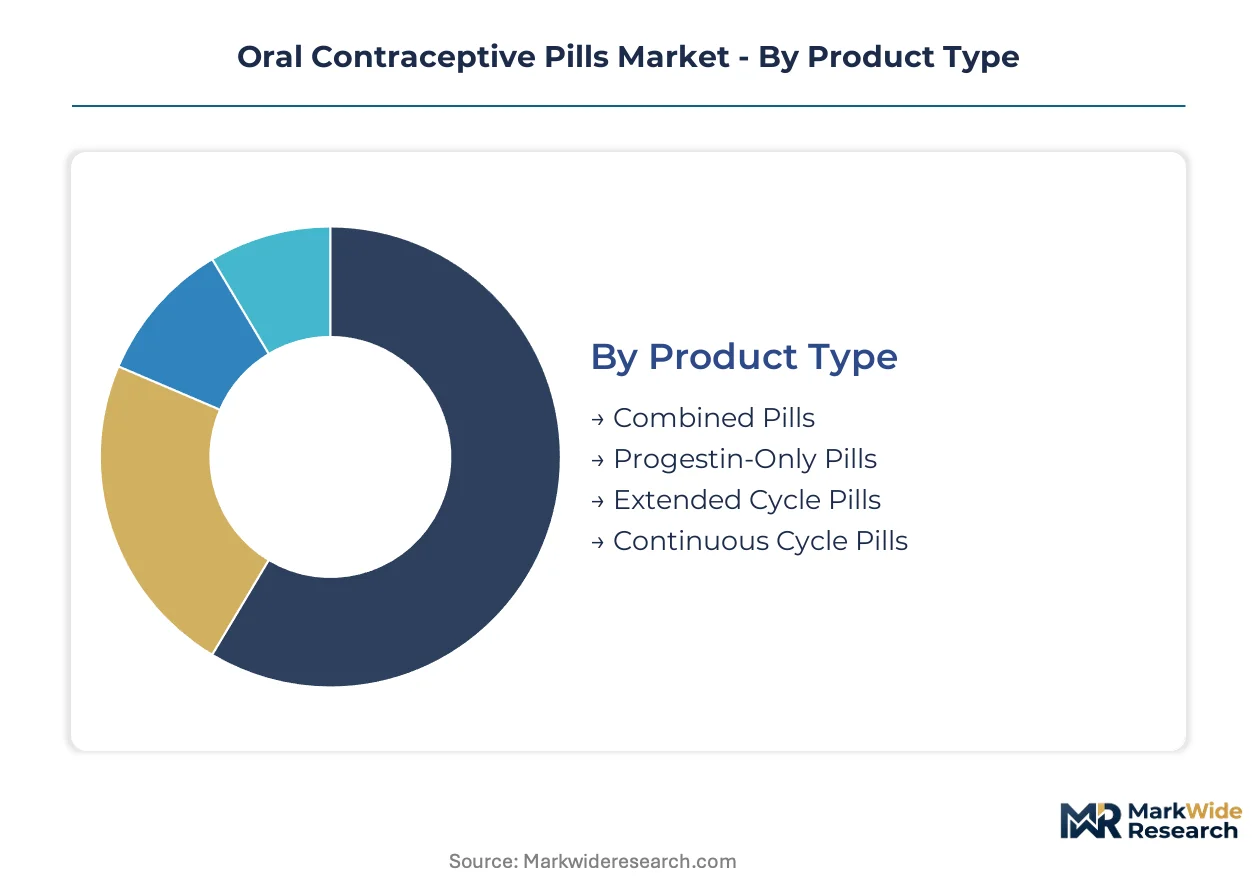
Segmentation in oral contraceptives reveals how formulation chemistry, clinical indication, and channel access stratify commercial opportunity. Manufacturers configure R&D pipelines and distribution partnerships around specific segment economics rather than treating the category as uniform.
Product Type:
Cost tier positioning separates mass-market generics from premium extended-cycle innovations with differentiated pricing power.
- Combined Pills:Synthetic estrogen-progestin pairings dominate prescription volumes through established clinical familiarity and broader non-contraceptive indications. Demand concentrates in United States family planning clinics where insurance coverage minimizes out-of-pocket costs for monthly 28-day regimens.
- Extended Cycle Pills:84-day and 365-day regimens reduce menstruation frequency through continuous hormone delivery. Urban professionals in Massachusetts and California health systems drive adoption fastest as women prioritize convenience over traditional cycling.
- Progestin-Only Pills:Norethindrone and drospirenone formulations serve lactating women and estrogen-contraindicated patients with tolerability advantages in breastfeeding support programs.
- Continuous Cycle Pills:Zero-menstruation protocols utilize solubility-enhancing polymer matrices for month-long release kinetics in early-stage trials at Basel-area biopharmaceutical developers.
Combined Pills holds installed capacity. Extended Cycle Pills is rotating up the share rankings.
Application:
Volume concentration varies sharply by whether reimbursement pathways recognize hormonal therapy beyond pregnancy prevention.
- Birth Control:Pregnancy prevention remains the foundational indication driving baseline prescription volumes across all geographies and payer systems.
- Polycystic Ovary Syndrome:Anti-androgenic progestin formulations command premium positioning through off-label reimbursement in United States endocrine clinics where prior authorization requirements filter demand toward established brands.
- Endometriosis Management:Hormonal suppression of ectopic tissue growth creates recurring prescription loyalty in academic medical center gynecology departments with specialized pain management protocols.
- Menstrual Regulation:Cycle control for athletic and professional scheduling drives discretionary use in urban markets with high smartphone penetration and telehealth adoption.
- Acne Treatment:Dermatology co-prescriptions with isotretinoin alternatives capture adolescent and young adult demand in European markets where EMA guidelines support hormonal therapy for moderate-to-severe cases.
Birth Control anchors volume throughput. Polycystic Ovary Syndrome is climbing the fastest as reimbursement pathways mature.
End User:
Customer type determines whether clinical counseling or self-directed access governs product selection and brand loyalty.
- Family Planning Clinics:Federally qualified health centers and Title X facilities in United States urban counties generate concentrated prescription volumes through subsidized access programs.
- Gynecology Centers:Academic medical center practices in Boston, New York, and San Francisco drive premium formulation adoption through specialist prescribing influence and sample availability.
- Hospitals:Inpatient formulary decisions and postpartum discharge protocols create captive initiation points for progestin-only options in maternity wards.
- Private Practitioners:Solo and group OB-GYN practices in suburban United States markets sustain branded prescription loyalty through established patient relationships.
- Health Awareness Programs:Non-governmental organization distribution in low-access geographies relies on donated or deeply discounted generic supplies.
Family Planning Clinics holds installed capacity. Gynecology Centers is rotating up the share rankings.
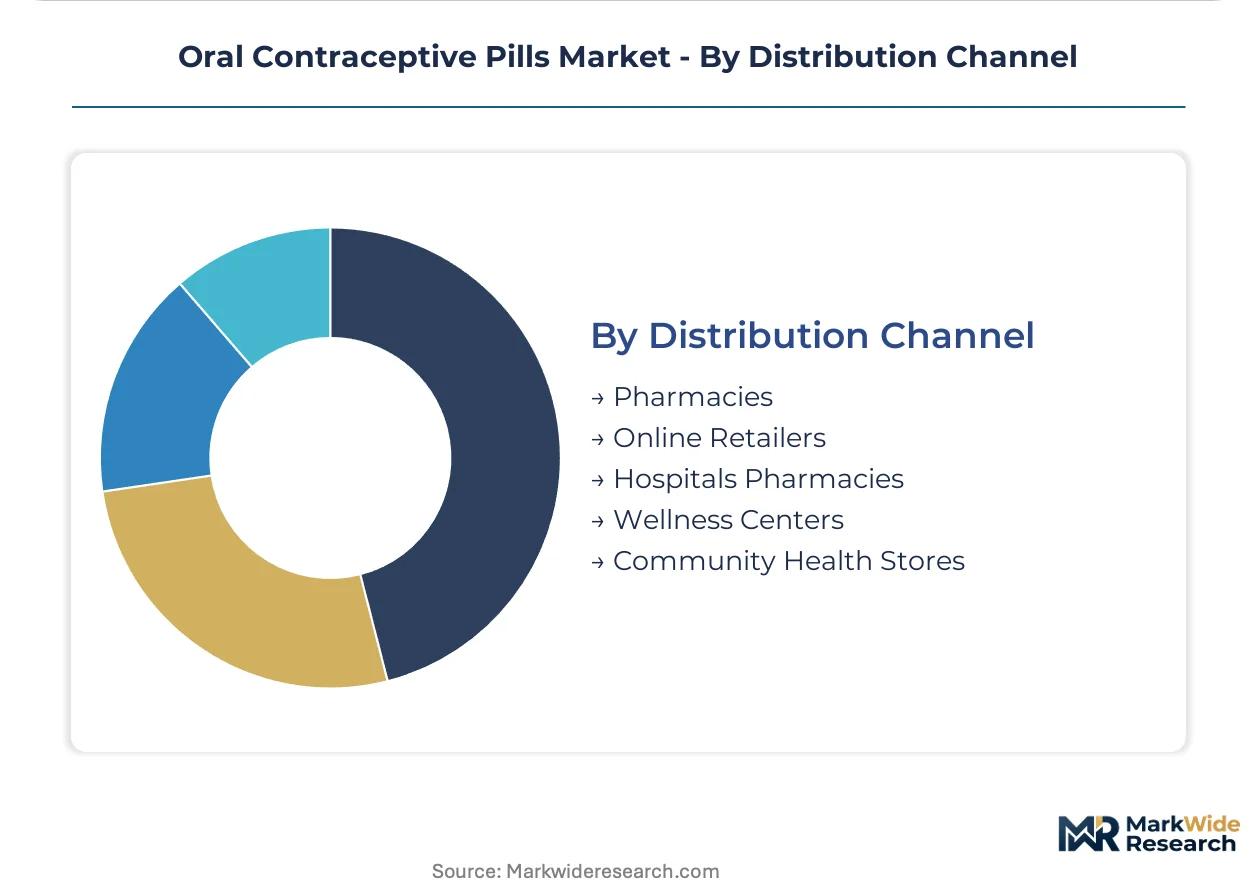
Distribution Channel:
Margin structure shifts dramatically as pharmacy-to-digital migration compresses traditional wholesale-retail economics.
- Pharmacies:Chain and independent retail locations in United States metropolitan areas retain majority volume through insurance network participation and same-day fulfillment convenience.
- Online Retailers:Nurx, Hers, and analogous platforms bundle asynchronous consultation with automated refill scheduling in markets with telehealth carve-outs and high smartphone penetration.
- Hospitals Pharmacies:Captive outpatient dispensing captures post-procedure and discharge prescriptions with limited patient choice.
- Wellness Centers:Integrated health system retail locations in European markets combine contraceptive access with broader women's health services.
- Community Health Stores:Non-profit and cooperative distribution channels serve underinsured populations in rural United States counties with limited pharmacy density.
Pharmacies holds installed capacity. Online Retailers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites European distribution reach for hormone formulations manufactured in Basel and Frankfurt. This logistics backbone enables just-in-time replenishment of oral contraceptive inventories across EMA-regulated markets without temperature excursion risk.
United States
Urban family planning clinics in Massachusetts and California drive prescription volume through Title X subsidized access programs. The FDA's Risk Evaluation and Mitigation Strategy for estrogen-containing formulations shapes product availability and labeling requirements. Boston-area academic medical centers accelerate adoption of extended-cycle protocols through investigator-initiated trials.
Germany
Bayer AG's manufacturing scale in Leverkusen anchors European supply chain control for combined oral contraceptives. EMA centralized marketing authorizations through the Committee for Medicinal Products for Human Use streamline cross-border launches. The Rhine-Ruhr pharmaceutical cluster concentrates formulation expertise and regulatory affairs capabilities.
India
Domestic contract manufacturers in Maharashtra and Gujarat supply active pharmaceutical ingredients for ethinyl estradiol to global formulators. CDSCO's phased strengthening of good manufacturing practice inspections creates compliance pressure for export-oriented producers. The Hyderabad-Visakhapatnam corridor concentrates API synthesis capacity for progestin compounds.
Switzerland
Basel-area biopharmaceutical developers pilot month-long continuous-delivery formulations with zero-order release kinetics. Swissmedic maintains stringent pharmacovigilance standards that influence EMA guideline development. The Basel-Zurich corridor attracts women's health venture capital for novel progestin analog development.
United Kingdom
NHS England's contraceptive prescribing guidelines influence formulary decisions across integrated care systems. The MHRA's post-Brexit regulatory autonomy permits divergence from EMA centralized procedures for certain generic approvals. London's digital health startup ecosystem spawns telehealth platforms bundling asynchronous consultation with automated refill scheduling.
Oral Contraceptive Pills Market Key Industry Players
On the supply side, the industry is tiered between multinational pharmaceutical conglomerates with integrated R&D-manufacturing-distribution capabilities and mid-tier generic specialists competing on cost-competitive production. Three strategic archetypes dominate: research-intensive innovators pursuing extended-cycle formulations, scale-driven manufacturers leveraging captive API supply, and digitally native direct-to-patient platforms bypassing traditional clinic gatekeepers. Competitive moves concentrate on portfolio diversification into progestin-only segments and geographic expansion through EMA centralized marketing authorizations.
Among research-intensive conglomerates, Bayer AG and Pfizer Inc. exemplify the innovation-driven archetype, while Teva Pharmaceutical Industries Ltd. occupies a position within the cost-competitive generic tier. These three anchors represent divergent strategic postures: integrated manufacturing scale, R&D intensity in novel formulations, and volume-driven production of established hormone combinations.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| Merck & Co. Inc. |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| Allergan plc |
| Cipla Inc. |
| Lupin Limited |
| Mylan N.V. |
| Others |
Cost & Logistics Intelligence
The Hyderabad-Visakhapatnam corridor concentrates active pharmaceutical ingredient synthesis for ethinyl estradiol and progestin compounds, concentrating upstream bargaining power among Indian contract manufacturers who feed formulation plants in Basel and Frankfurt. This geographic clustering allows API suppliers to capture margin through volume-commitment contracts while downstream formulators absorb price volatility through long-term offtake agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates extended-cycle branded formulations from established combined pills and commodity generic progestin-only alternatives. Price differentiation hinges on FDA Risk Evaluation and Mitigation Strategy compliance costs for estrogen-containing products and EMA centralized marketing authorization investment for cross-border European launches. Pricing pressure stems from telehealth platforms compressing traditional pharmacy margins through subscription bundling. Family planning clinics exhibit highest price sensitivity due to Title X subsidy constraints, while academic medical center gynecology departments tolerate premium positioning for specialized indications.
Supply Chain Analysis
Chinese and Indian contract manufacturers hold captive capacity for ethinyl estradiol API production, with Maharashtra and Gujarat facilities serving as primary supply nodes for global formulators. Raw material dependencies center on steroid precursor chemicals sourced from specialized fermentation operations and solvent reagents for progestin analog synthesis. Supply chain risk concentrates in customs delays at Rotterdam and Mumbai ports disrupting just-in-time hormone formulation schedules. Distribution runs through temperature-controlled pharmaceutical logistics networks linking Basel-area manufacturing to EMA-regulated markets, with digital pharmacies now bypassing traditional wholesale-retail channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern patient access as telehealth subscription models disintermediate clinic-pharmacy pathways, with asynchronous consultation infrastructure creating network effects that reward first-movers in smartphone-penetrated urban markets.
For Market Incumbents: Pre-empt telehealth platform consolidation by acquiring direct-to-patient subscription infrastructure or building captive digital pharmacy capabilities before channel gatekeepers solidify patient data ownership. Defend formulary position through backward integration into API production, securing ethinyl estradiol supply from Hyderabad-Visakhapatnam corridor manufacturers ahead of CDSCO inspection intensification. Prioritize EMA centralized marketing authorization maintenance as pharmacovigilance registry requirements raise compliance barriers for smaller competitors. For New Entrants and Emerging Players: Pursue progestin-only mini-pill white space in lactating women and estrogen-contraindicated patient segments where tolerability advantages command loyalty absent generic commoditization. Target United States urban professionals seeking menstrual regulation for athletic and professional scheduling through telehealth channels with asynchronous consultation models. Anchor go-to-market strategy through Nurx and Hers platform partnerships rather than building independent clinical infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical conglomerates divesting women's health portfolios to focus on oncology and immunology therapeutic areas. Long-term viability hinges on regulatory compliance infrastructure capable of absorbing EMA pharmacovigilance registry costs and FDA Risk Evaluation and Mitigation Strategy maintenance. Monitor telehealth platform prescription volume share as inflection indicator for channel power shift away from traditional clinic gatekeepers.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Centralized Marketing Authorization | Streamlined cross-border launches reduce regulatory fragmentation for multinational manufacturers across European member states. |
| Telehealth Platform Integration | Direct-to-patient subscription models bypass traditional clinic gatekeepers and capture urban professional prescription volume. |
| API Supply Security Investment | Backward integration into Indian and Chinese contract manufacturing insulates formulators from geopolitical disruption risks. |
| Extended-Cycle Formulation Pipeline | Continuous-delivery polymer matrix development collapses distinction between daily pills and long-acting alternatives. |
| Pharmacovigilance Registry Compliance | Real-world evidence collection capabilities satisfy EMA Good Pharmacovigilance Practices guideline requirements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at family planning clinics, and telehealth platform medical officers. Secondary validation drew from FDA new drug application filings, EMA Committee for Medicinal Products for Human Use opinions, ClinicalTrials.gov protocol registries, and United States Title X program utilization data. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical market audit databases to ensure segmentation integrity.
Calibration against historical prescription trends and regulatory approval timelines anchored projection assumptions across the analysis window. Segmentation dimensions modeled included formulation chemistry, clinical indication, end-user channel type, and distribution pathway evolution. CAGRs derived from regression analysis of volume trajectories adjusted for policy shifts including FDA Risk Evaluation and Mitigation Strategy implementation and EMA pharmacovigilance guideline updates. Forecast inputs incorporated telehealth platform growth curves and API supply capacity expansion announcements from Indian contract manufacturers.
Sensitivities concentrate around CDSCO inspection timeline acceleration, EMA registry implementation standard clarity, and telehealth reimbursement carve-out policy shifts at state Medicaid levels. Quarterly review of prescription channel mix data and API import customs records is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Global Intravenous Solutions Market
Pharmaceuticals
Herbal Drugs Market
Pharmaceuticals
Cefazedone Sodium Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Plasma Protein Therapeutics Market
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market