
 Dextromethorphan Market | 2026-2036
Dextromethorphan Market Size, Share, and Industry Trends Forecast 2026-2036
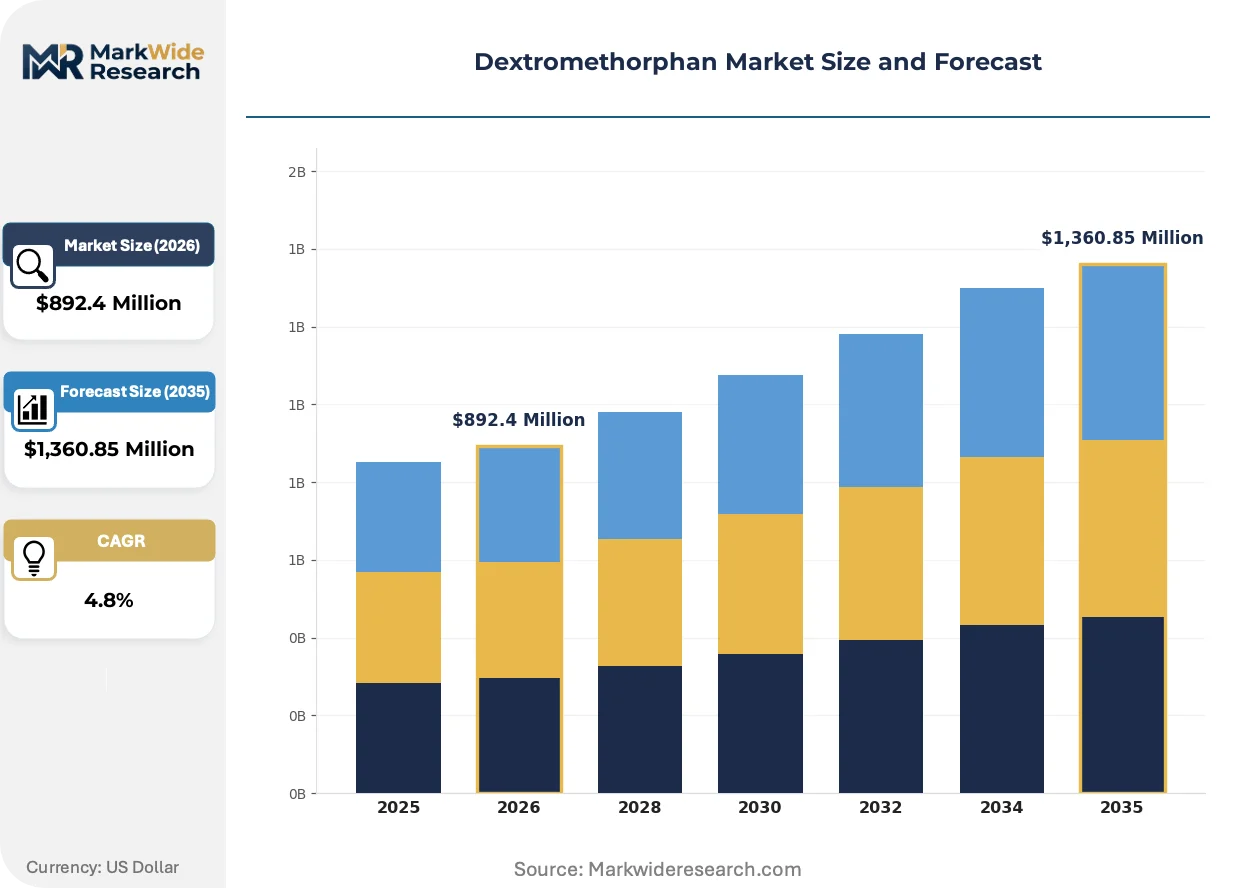
Dextromethorphan Market Outlook
Multi-source API procurement is expanding across dextromethorphan supply chains as formulators reduce reliance on single-origin active pharmaceutical ingredient. Pfizer Inc. leverages backward integration into precursor chemistry to secure cost advantages. Sun Pharmaceutical Industries Ltd. anchors its position through captive manufacturing of both API and finished dosage forms. Teva Pharmaceutical Industries Ltd. competes via specialized lozenge and suspension capabilities in regulated markets.
Dextromethorphan is a synthetic morphinan derivative acting as a non-opioid sigma-1 receptor agonist and NMDA receptor antagonist, primarily formulated as hydrobromide salts for antitussive therapy at 10–30 mg unit doses. Cough syrup formulations dominate volume consumption in seasonal cold and flu cycles, while tablet and capsule segments capture higher pharmacy margins through convenience positioning. E-commerce distribution channels represent the fastest-growing access pathway, though retail stores and hospital pharmacies retain bulk procurement leverage through direct sales arrangements.
The US FDA OTC monograph system governs dextromethorphan labeling and dosage limits, while India's CDSCO regulates domestic manufacturing standards for export-bound API batches. The EU EMA classifies combination products containing dextromethorphan under centralized marketing authorization pathways, tightening quality documentation requirements. Stakeholders must monitor evolving scheduling debates in multiple jurisdictions where recreational misuse concerns threaten OTC access status.
Market Dynamics
OTC monograph reforms and API supply diversification are restructuring competitive positioning across dextromethorphan value chains, with backward integration becoming the primary defense against input cost volatility.
Growth Catalysts
- FDA OTC Monograph Modernization:The US FDA's streamlined review pathways accelerate product classification decisions, reducing time-to-market for reformulated cough suppressants.
- Seasonal Cold Cycle Intensity:Extended influenza seasons in temperate climates sustain baseline demand for antitussive syrups and lozenges through retail pharmacy channels.
- India CDSCO Export Certification:India's streamlined API batch certification for export markets enables domestic manufacturers to scale formulation output for regulated destinations.
Market Restraints
- Precursor Chemical Sourcing:Narcotic precursor controls on 1-benzyl-3-methyl-4-piperidone tighten import licensing requirements for hydrobromide salt manufacturers.
- Single-Origin API Dependency:Concentrated production of morphinan-derived intermediates in specific chemical clusters creates supply vulnerability during environmental compliance shutdowns.
- Recreational Misuse Scheduling:Debates over dextromethorphan abuse potential threaten OTC status in multiple jurisdictions, forcing contingency planning for prescription-only transitions.
Strategic Opportunities
- Pediatric Formulation Gap:Alcohol-free suspension development for children under six addresses unmet need in family medicine segments.
- E-Commerce Direct Access:Subscription-based cold medicine delivery bypasses traditional pharmacy stocking constraints for chronic condition households.
- Combination Therapy Expansion:Pairing dextromethorphan with expectorants or antihistamines captures multi-symptom relief positioning in self-medication markets.
Industry Challenges
- Analytical Method Transfer:Migrating impurity profiling from pharmacopeial to in-house chromatography systems demands specialized separation science talent.
- Cross-Border Label Harmonization:Reconciling maximum daily dose statements across FDA, EMA, and CDSCO requirements fragments packaging runs and extends compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dextromethorphan Market |
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,360.85 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cough Syrup, Tablets, Capsules, Lozenges End User: Pharmacy, Hospitals, Clinics, Online Retailers Distribution Channel: Direct Sales, Wholesalers, Retail Stores, E-Commerce Formulation: Liquid, Solid, Suspension, Powder |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Aurobindo Pharma, GSK plc., Novartis AG, Sanofi, F. Hoffmann-La Roche Ltd., Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dextromethorphan Market Strategic Shifts
Continuous manufacturing and real-time release testing are compressing batch cycle times while regulatory convergence around quality-by-design principles reshapes process validation requirements.
Hot-melt extrusion for dextromethorphan polistirex complexes is unifying taste-masking and modified-release functions in a single unit operation. Pediatric and geriatric formulators adopt this platform to eliminate alcohol-based solvents. The technology is compressing formulation development timelines from eighteen months to under nine.
REACH substance registration deadlines for cough suppressant excipients are forcing EU-based manufacturers to substitute legacy solvents with bio-based alternatives. EMA's tightened nitrosamine impurity limits extend analytical burden to all imported API batches. Combination product sponsors now front-load extractables and leachables studies to preempt centralized authorization delays.
Direct-to-consumer diagnostic integration is reshaping purchase triggers for antitussive products. Smartphone-connected COVID-flu multiplex tests that recommend symptom-specific relief drive pharmacy traffic toward algorithm-guided self-selection. This pattern concentrates in US and UK markets where telehealth prescribing laws enable seamless OTC-to-prescription transitions.
Dextromethorphan Market Segmentation
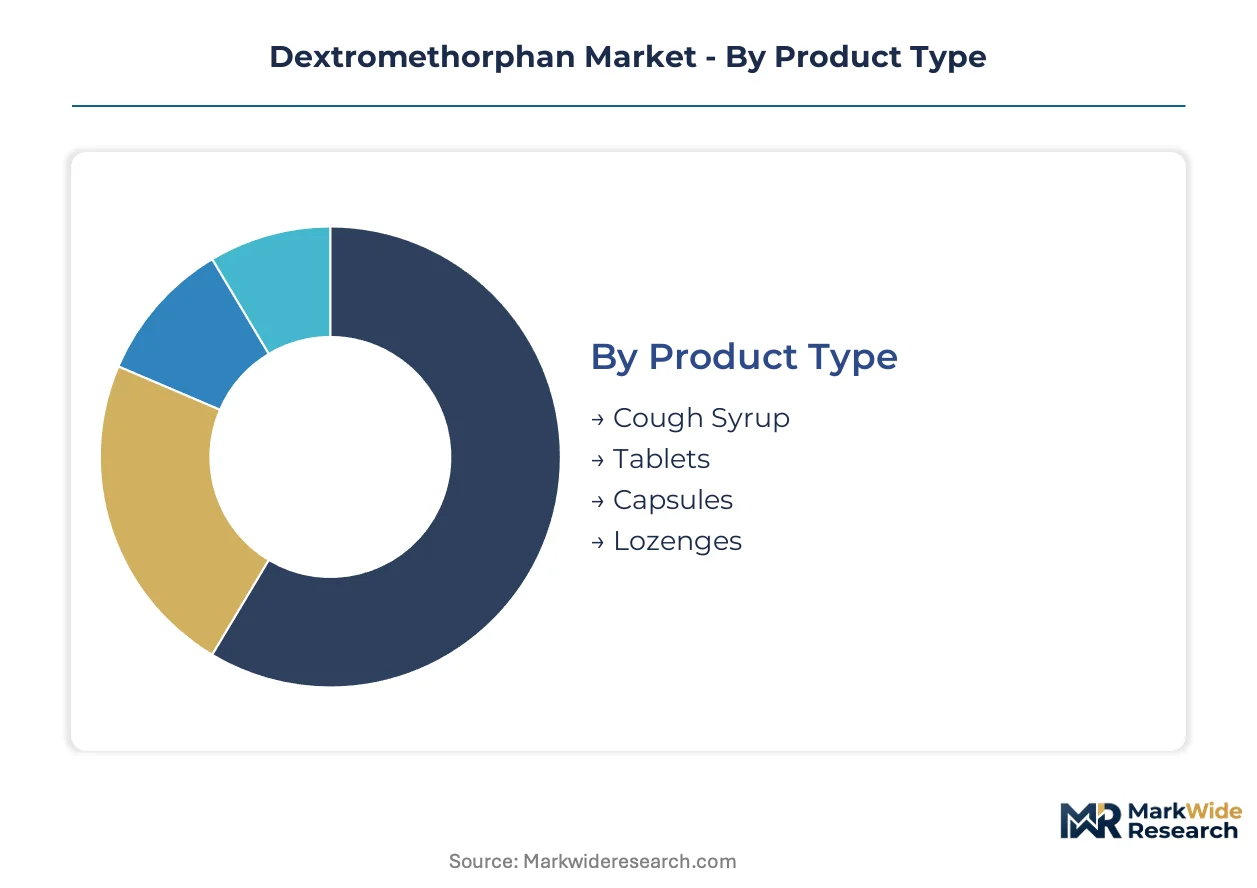
Dextromethorphan product configurations vary sharply in patient compliance, manufacturing complexity, and margin structure. Formulation choices determine API salt selection, stability requirements, and regulatory filing pathways. Distribution channel selection locks in customer access patterns and pricing power.
Product Type:
Standardized unit-dose formats dominate high-volume production, while specialized delivery systems command formulation premiums through differentiated onset profiles.
- Cough Syrup:Hydrobromide salt dissolved in aqueous vehicles with viscosity modifiers and flavor masking systems. Demand clusters in India and Southeast Asia for seasonal flu response through pharmacy counters. Alcohol-free variants address pediatric regulatory constraints in EU markets.
- Tablets:Direct compression of granulated API with disintegrants and lubricants enables high-speed rotary press operations. US retail chains prefer blister-packaged tablets for inventory efficiency and theft deterrence. Modified-release coatings extend dosing intervals for nighttime formulations.
- Capsules:Hard gelatin shells encapsulate powder blends or mini-tablets for taste masking without liquid excipients. Hospital formularies favor unit-dose capsules for automated dispensing systems.
- Lozenges:Hot-melt extrusion or candy-base molding delivers localized oropharyngeal activity with controlled dissolution rates. Teva Pharmaceutical Industries anchors specialized capabilities in this segment.
Leading the category by volume: Cough Syrup. Growing fastest: Lozenges.
End User:
Procurement authority shifts from clinical decision-makers to retail buyers as product familiarity reduces prescriber involvement.
- Pharmacy:Independent and chain pharmacies stock seasonal inventory based on CDC flu surveillance data. Self-medication trends expand front-of-store placement for dextromethorphan monograph products.
- Hospitals:Formulary committees evaluate antitussive alternatives for post-operative cough suppression and palliative care protocols. Bulk procurement contracts favor tablet and capsule presentations.
- Clinics:Urgent care and family practice settings dispense sample quantities or short-course prescriptions. Limited on-site inventory reduces storage infrastructure requirements.
- Online Retailers:Amazon and specialized health platforms bypass traditional pharmacy stocking constraints through direct-to-consumer fulfillment. Age verification systems address regulatory compliance for OTC sales.
Pharmacy channels capture the highest transaction frequency. Online Retailers expand most quickly.
Distribution Channel:
Channel selection determines working capital intensity, with direct sales requiring receivables management and e-commerce demanding last-mile logistics investment.
- Direct Sales:Manufacturer representatives negotiate annual contracts with hospital purchasing groups and pharmacy chains. Price transparency is lowest in this channel due to volume-tiered negotiations.
- Wholesalers:McKesson and Cardinal Health aggregate demand across fragmented retail accounts, providing inventory financing and returns processing. Cold chain requirements for liquid formulations limit wholesaler participation in certain segments.
- Retail Stores:Mass merchandisers and convenience stores stock impulse-purchase sizes near checkout counters. Planogram placement fees influence shelf positioning during peak cold seasons.
- E-Commerce:Subscription models for chronic condition households reduce customer acquisition costs through recurring revenue. Regulatory scrutiny of age-restricted product sales intensifies platform compliance burdens.
Wholesalers move the largest absolute volumes. E-Commerce gains share fastest.
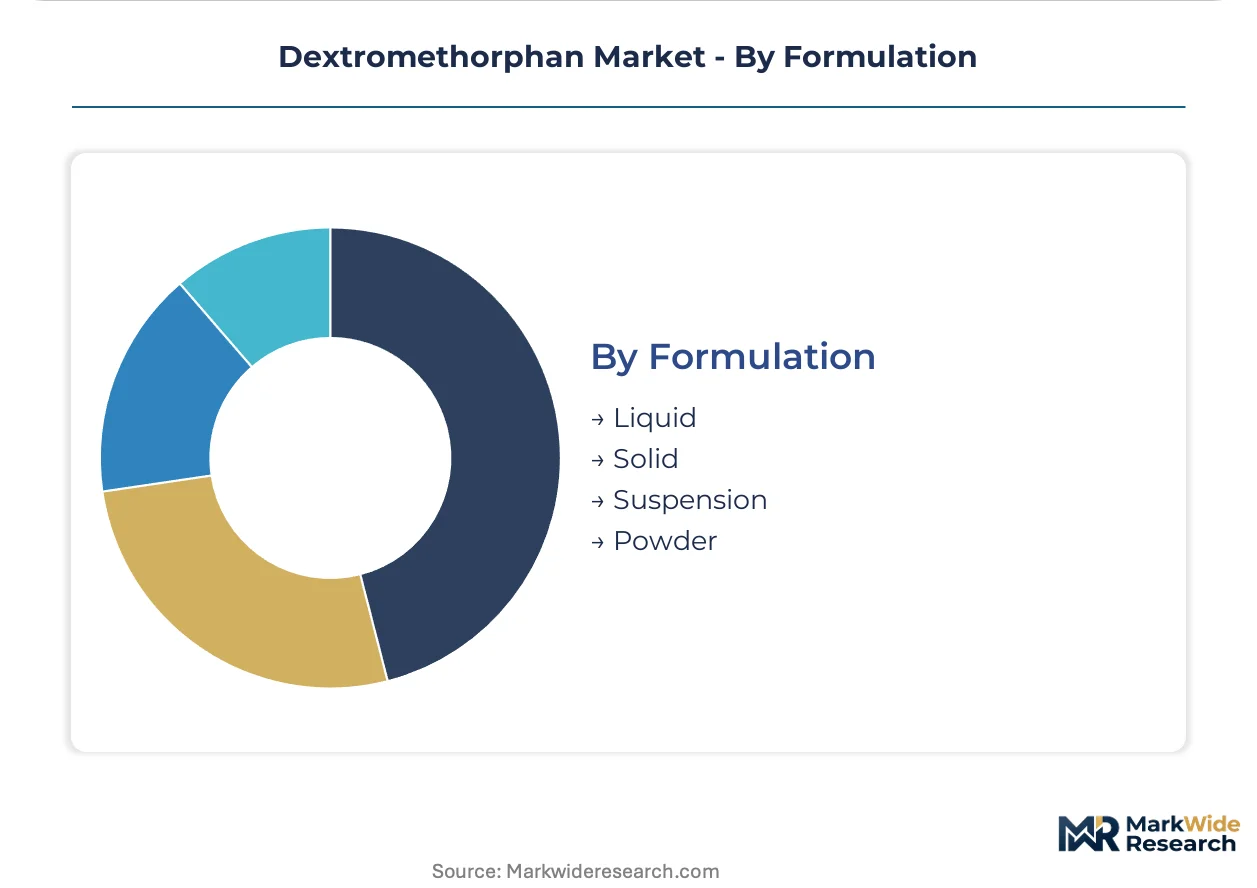
Formulation:
Physical state selection drives excipient compatibility, packaging requirements, and patient acceptability across age demographics.
- Liquid:Aqueous solutions with preserved stability and measured-dose dispensing caps. Pediatric preference drives formulation development toward palatable flavor systems.
- Solid:Tablets and capsules offer dosing precision and extended shelf life without refrigeration. Manufacturing scales efficiently through continuous direct compression.
- Suspension:Micronized API dispersed in viscous vehicles requires resuspension instructions and homogeneous distribution verification. Hot-melt extrusion of polistirex complexes enables taste masking without alcohol solvents.
- Powder:Sachet or stick-pack presentations for reconstitution travel well and enable precise weight-based pediatric dosing. Limited commercial presence outside specialized markets.
Solid formulations dominate manufacturing throughput. Suspension formats climb fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates dextromethorphan API production through vertically integrated manufacturers serving export markets. The United States and Germany anchor formulation demand through pharmacy and hospital channels. Regulatory divergence across FDA, EMA, and CDSCO frameworks shapes regional competitive dynamics.
United States
Seasonal influenza patterns drive pharmacy restocking cycles for cough suppressants. The FDA's OTC monograph modernization accelerates product classification reviews for reformulated antitussives. New Jersey and Pennsylvania host formulation packaging operations serving retail chain distribution networks.
India
Domestic manufacturers scale API-to-formulation output for regulated export destinations. CDSCO streamlined batch certification enables faster clearance of hydrobromide salt shipments to North American and European markets. Hyderabad and Mumbai chemical clusters concentrate morphinan derivative synthesis capacity.
Germany
Hospital formularies maintain steady procurement of unit-dose antitussive presentations for post-operative care. EMA centralized marketing authorization pathways tighten quality documentation for combination products containing dextromethorphan. Frankfurt and Munich anchor pharmaceutical distribution hubs for EU-wide wholesaler networks.
China
Narcotic precursor controls on 1-benzyl-3-methyl-4-piperidone intensify import licensing scrutiny for hydrobromide manufacturers. NMPA alignment with ICH quality guidelines elevates impurity profiling standards for exported API batches. Zhejiang and Jiangsu provinces concentrate fine chemical intermediate production.
United Kingdom
Telehealth prescribing integration drives algorithm-guided self-selection of antitussive products through pharmacy channels. MHRA post-Brexit regulatory autonomy creates parallel filing requirements distinct from EMA centralized procedures. London and Southeast England concentrate specialty pharmaceutical distribution infrastructure.
Dextromethorphan Market Competitive Environment
Backward integration dominates the current landscape as formulators secure captive API supply against precursor chemical volatility. The vendor base concentrates around three strategic tiers: multinational pharmaceutical conglomerates with full vertical control, mid-scale generic specialists with regional formulation focus, and API-centric manufacturers expanding into finished dosage forms. Consolidation pressure intensifies through selective M&A targeting polistirex complex capabilities and geographic expansion into India's export-certified manufacturing zones.
Among vertically integrated conglomerates, Pfizer Inc. and Sun Pharmaceutical Industries Ltd. exemplify the backward-integration archetype through in-house precursor chemistry and captive formulation output. Teva Pharmaceutical Industries Ltd. occupies a specialized position in modified-release delivery systems. These three entities represent distinct competitive vectors: cost-secured supply chains, scale-driven generic penetration, and technology-differentiated product formats.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Aurobindo Pharma |
| GSK plc. |
| Novartis AG |
| Sanofi |
| F. Hoffmann-La Roche Ltd. |
| Mylan N.V. |
| Others |
Value Chain & Pricing Dynamics
1-benzyl-3-methyl-4-piperidone precursor pricing cascades through dextromethorphan value chains, compressing margins for hydrobromide salt manufacturers while rewarding backward-integrated players with captive precursor supply. FDA OTC monograph compliance costs stratify pricing tiers, separating CDSCO-certified Indian exporters from higher-cost European formulators serving EMA-regulated markets.
Pricing Analysis
Volume-driven cough syrup sales generate thin unit margins through pharmacy wholesale channels, while modified-release lozenges and pediatric suspensions capture formulation premiums through differentiated delivery technology. Price differentiation hinges on CDSCO export certification status and alcohol-free formulation compliance for EU pediatric markets. Cost compression in standard hydrobromide tablets is intensifying as Indian API producers scale output for North American retail chains. Hospital procurement committees exhibit lowest price sensitivity due to formulary lock-in, whereas mass merchandisers and e-commerce platforms drive aggressive tender negotiations.
Supply Chain Analysis
Morphinan derivative synthesis rests on concentrated chemical manufacturing clusters in India, China, and the United States, with Hyderabad and Zhejiang provinces anchoring global intermediate output. Dextromethorphan production draws from 1-benzyl-3-methyl-4-piperidone precursors, hydrobromic acid reagents, and polistirex resin complexes for modified-release applications. Single-source vulnerability in specialty piperidone intermediates creates exposure during environmental compliance shutdowns. Distribution runs through McKesson and Cardinal Health wholesaler networks for retail pharmacy fulfillment, supplemented by direct manufacturer contracts with hospital purchasing groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
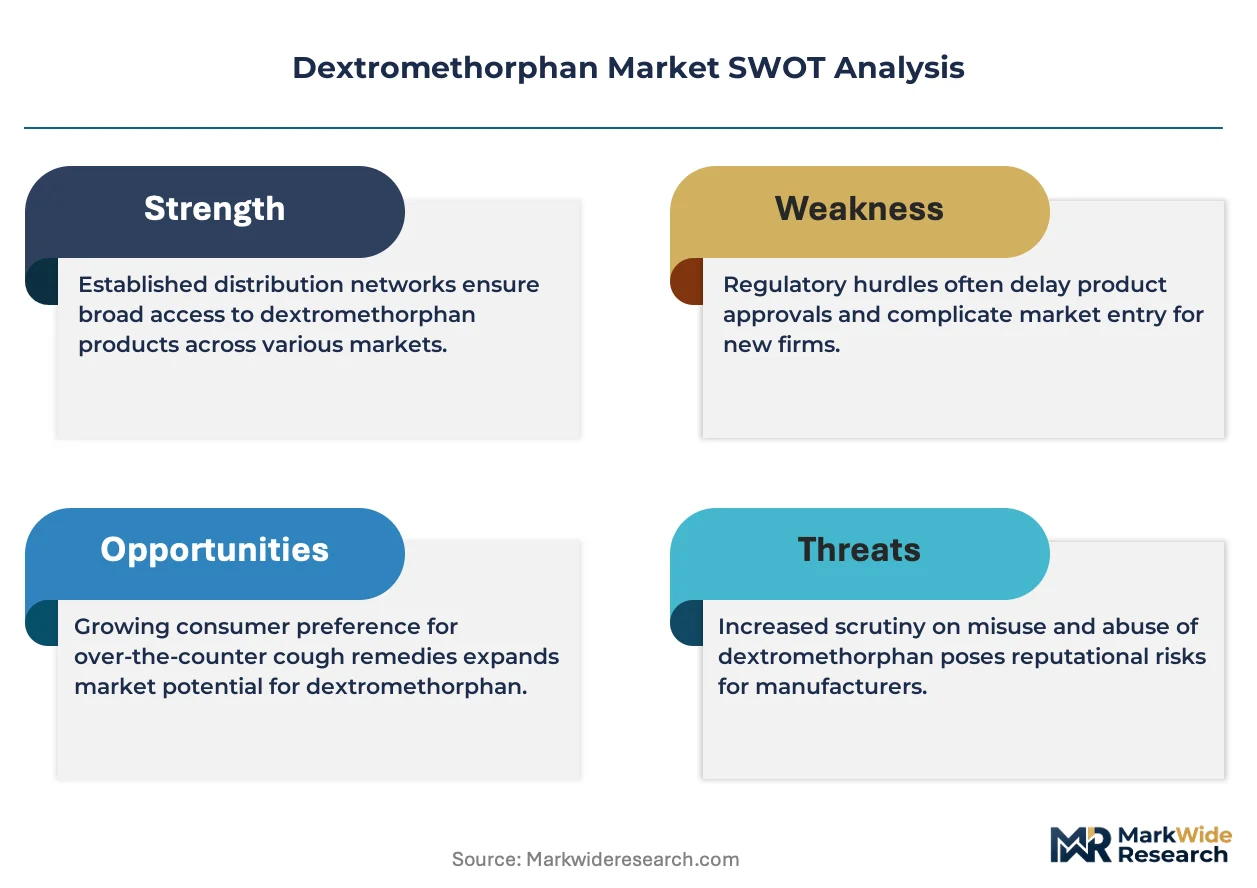
The dextromethorphan market functions as a cost-of-compliance arena where FDA OTC monograph modernization and EMA nitrosamine impurity standards erect regulatory moats favoring incumbents with validated analytical infrastructure.
For Market Incumbents: Lock in backward integration into 1-benzyl-3-methyl-4-piperidone precursor chemistry to neutralize input cost volatility from narcotic chemical licensing constraints. Expand hot-melt extrusion capacity for polistirex complex manufacturing, defending against Teva Pharmaceutical Industries' specialized lozenge positioning while capturing pediatric formulation premiums through alcohol-free suspension platforms. For New Entrants and Emerging Players: FDA OTC monograph modernization in the United States opens a window for streamlined product classification entry through reformulated antitussive submissions. Target subscription-based e-commerce distribution for chronic condition households, bypassing McKesson and Cardinal Health wholesale concentration through direct-to-consumer fulfillment models with embedded age-verification compliance. For Investors and Strategic Acquirers: Distressed-cycle entries favor CDSCO-certified Indian manufacturers with captive API-to-formulation output and established North American export relationships. Prioritize acquisition targets with validated nitrosamine impurity profiling systems and REACH-registered excipient portfolios. Watch EMA scheduling debates on recreational misuse as the critical inflection signal threatening OTC status transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistry | Pfizer and Sun Pharmaceutical Industries neutralize 1-benzyl-3-methyl-4-piperidone licensing volatility through captive synthesis. |
| Hot-Melt Extrusion Capacity Expansion | Polistirex complex manufacturing compresses formulation timelines from eighteen months to under nine for pediatric markets. |
| CDSCO Export Certification Investment | Indian manufacturers accelerate hydrobromide salt clearance for FDA-regulated North American destinations. |
| E-Commerce Subscription Platform Launch | Amazon and specialized health platforms bypass Cardinal Health wholesale constraints for chronic household segments. |
| Alcohol-Free Suspension Development | Pediatric regulatory compliance in EU markets addresses unmet family medicine demand without solvent-based excipients. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with CDSCO regulatory affairs leads, FDA compliance officers, hospital formulary directors, and pharmacy chain procurement managers. FDA OTC monograph submissions, EMA centralized marketing authorization pathways, Indian DGFT export statistics, and US customs import records provided validation benchmarks. Bottom-up volume modeling triangulated against top-down pharmaceutical market sizing across the projection horizon.
Granularity-level modeling operated at formulation-type, distribution-channel, and regional-regulatory-cluster dimensions throughout the forecast period. CAGRs derived from time-series analysis of API batch certification volumes, seasonal influenza surveillance correlations, and e-commerce penetration trajectories. Treatment-line segmentation captured self-medication versus clinical prescribing patterns, while dosage-form analysis tracked syrup-to-solid conversion trends in pharmacy inventory cycles.
The model assumes a particular technology adoption path; alternative pathways for continuous manufacturing and real-time release testing would alter the outlook if regulatory convergence accelerates beyond current EMA quality-by-design timelines. Forecasts reflect assumptions regarding CDSCO certification efficiency, narcotic precursor licensing stability, and OTC scheduling status continuity. A small set of named triggers—EMA misuse scheduling decisions, REACH solvent substitution deadlines, and FDA monograph finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Trisenox Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
RAS-Acting Agents Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Constipation Laxative Market
Pharmaceuticals
Global Diphenhydramine Market