
 Anti-Platelet Agents Market | 2026-2036
Anti-Platelet Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Platelet Agents Market Analytics
REACH compliance is broadening the cost-of-entry calculus for active pharmaceutical ingredient suppliers serving European formulations. Bayer AG anchors its position through backward integration into salicylic acid precursors and established aspirin manufacturing scale. AstraZeneca differentiates via sustained R&D intensity in ticagrelor analog development. Daiichi Sankyo Company, Limited navigates competitive positioning in prasugrel derivatives across Asian regulatory environments.
Anti-platelet agents constitute pharmacological compounds that inhibit platelet aggregation through irreversible or reversible binding to cyclooxygenase-1, P2Y12 receptors, or glycoprotein IIb/IIIa complexes, with primary commercial purpose of preventing thrombotic events in acute coronary syndromes and cerebrovascular intervention. Aspirin and clopidogrel occupy mature, high-volume positions where generic competition has compressed unit margins, while ticagrelor commands premium positioning in acute coronary syndrome protocols due to reversible binding kinetics and faster offset profiles. Oral delivery mode dominates prescription volumes, though intravenous formulations capture critical care settings where rapid platelet inhibition proves essential.
The FDA, EMA, and PMDA each enforce distinct pharmacovigilance frameworks that shape post-market surveillance obligations and label expansion pathways for antiplatelet therapies. ISO 15189 accreditation requirements for clinical testing laboratories indirectly constrain biomarker-guided personalization of dual antiplatelet therapy duration. Stakeholders must monitor evolving guidance on genotyping integration into clopidogrel prescribing decisions across reimbursement authorities.
Market Dynamics
The FDA's accelerated approval pathways for cardiovascular drugs are compressing development timelines while reshaping clinical trial requirements for P2Y12 inhibitors and aspirin analogs. This regulatory velocity is forcing sponsors to adapt biomarker strategies and manufacturing scale-up plans simultaneously.
Growth Catalysts
- Post-PCI protocol standardization:Hospital pharmacies are expanding procurement of oral antiplatelet therapies for patients following percutaneous coronary intervention, embedding dual antiplatelet therapy into discharge bundles.
- REACH compliance expansion:ECHA's chemical safety framework is broadening the cost-of-entry calculus for active pharmaceutical ingredient suppliers serving European formulations, filtering marginal producers from the supply base.
- Aging procedural volumes:United States demographics sustain prescription volumes for P2Y12 inhibitors as cardiac catheterization rates rise among patients over sixty-five.
Market Restraints
- Salicylic acid supply concentration:Backward integration into precursors limits viable supplier pools, with captive production dominating feedstock access for aspirin manufacturers.
- Generic margin compression:Clopidogrel and aspirin occupy mature positions where unit economics have deteriorated, constraining R&D reinvestment capacity for established players.
- Genotyping reimbursement friction:Variable coverage for CYP2C19 testing across United States payers creates prescribing uncertainty and delays personalized therapy adoption.
Strategic Opportunities
- Intravenous formulation expansion:Critical care settings where rapid platelet inhibition proves essential represent underpenetrated demand for glycoprotein IIb/IIIa inhibitors and IV P2Y12 antagonists.
- Asian regulatory arbitrage:Prasugrel derivative development across Japan's PMDA and China's NMPA pathways offers label expansion potential distinct from FDA-established indications.
- Biomarker-guided duration protocols:ISO 15189-accredited laboratory networks enable personalized dual antiplatelet therapy duration, creating service revenue streams adjacent to pharmaceutical sales.
Industry Challenges
- Pharmacovigilance workforce scarcity:Post-market surveillance obligations under FDA, EMA, and PMDA frameworks strain safety signal detection capacity across sponsor organizations.
- Legacy manufacturing integration:Reversible binding kinetics production lines require process revalidation that conflicts with existing irreversible inhibitor batch records and quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Platelet Agents Market |
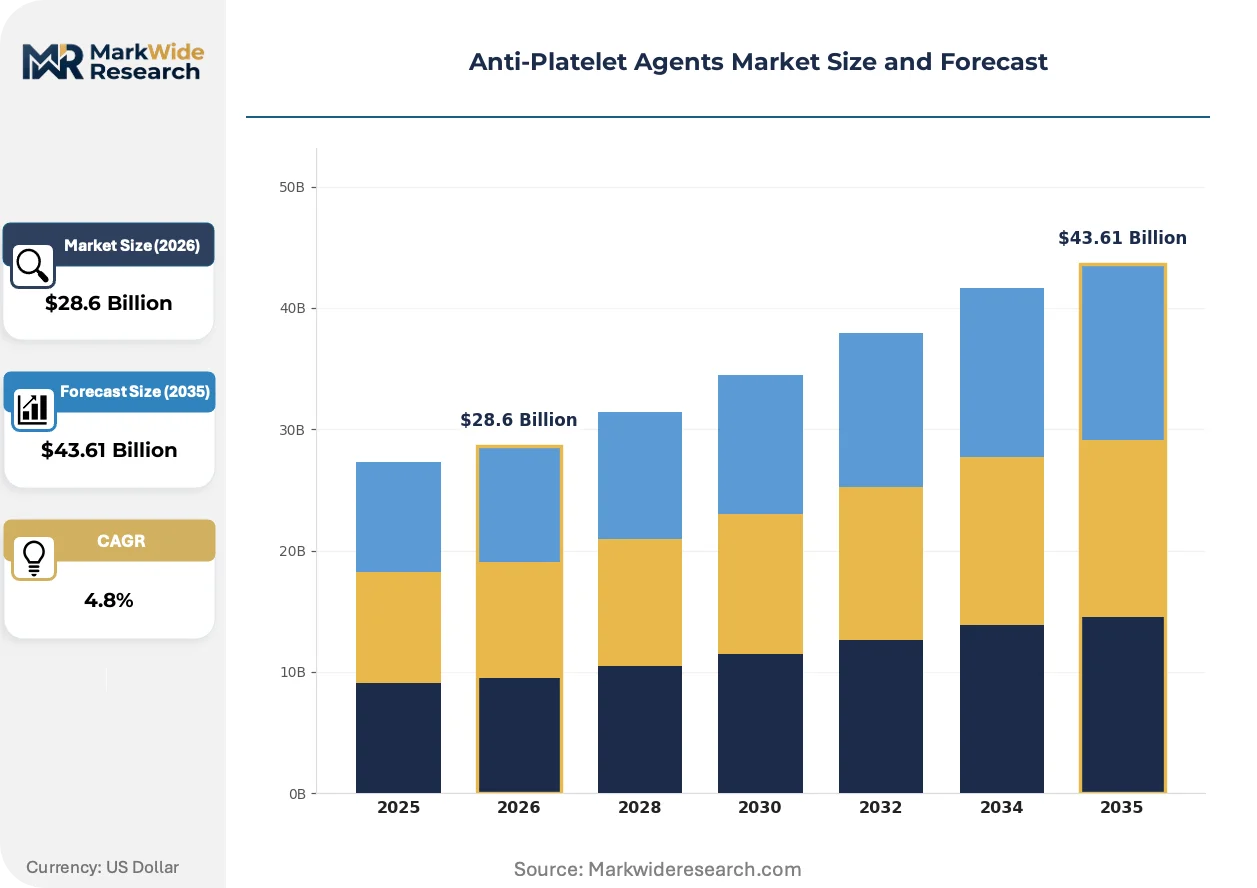
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspirin, Clopidogrel, Prasugrel, Ticagrelor Therapy Area: Cardiovascular Diseases, Stroke, Coronary Artery Disease, Peripheral Artery Disease Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers |
| Companies Covered | Pfizer Inc., Sanofi, AstraZeneca, Bayer AG, Bristol-Myers Squibb Company, Novartis AG, Daiichi Sankyo Company, Limited, Eli Lilly And Company, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Platelet Agents Market Evolving Landscape
Reversible P2Y12 inhibition is displacing irreversible binding as the kinetic standard in acute coronary syndrome protocols, while pharmacogenomic integration and point-of-care testing reshape prescribing workflows across hospital and ambulatory settings.
Platelet function testing platforms are expanding into bedside diagnostic workflows, enabling real-time assessment of aspirin and P2Y12 inhibitor response. Cardiology departments in tertiary United States hospitals are adopting these systems to guide transfusion and surgical timing decisions. The technology is compressing the window between laboratory result and clinical action, reducing bleeding risk in urgent revascularization cases.
EMA's evolving guidance on genotyping integration into clopidogrel prescribing decisions is forcing label updates across European formulations. Sponsors must now submit pharmacogenomic subpopulation data as a condition of marketing authorization maintenance. This regulatory pressure is most acute in Germany and France, where reimbursement authorities have begun conditioning payment on documented CYP2C19 status.
Hospital procurement consortia are consolidating antiplatelet purchasing through multi-year sole-source agreements, displacing traditional wholesaler relationships. Integrated delivery networks in the United States are leveraging volume commitments to extract price concessions on ticagrelor and prasugrel. This concentration is visible most clearly in the Midwest and Southeast, where Catholic health systems and for-profit chains have unified formularies across dozens of facilities.
Anti-Platelet Agents Market Segmentation
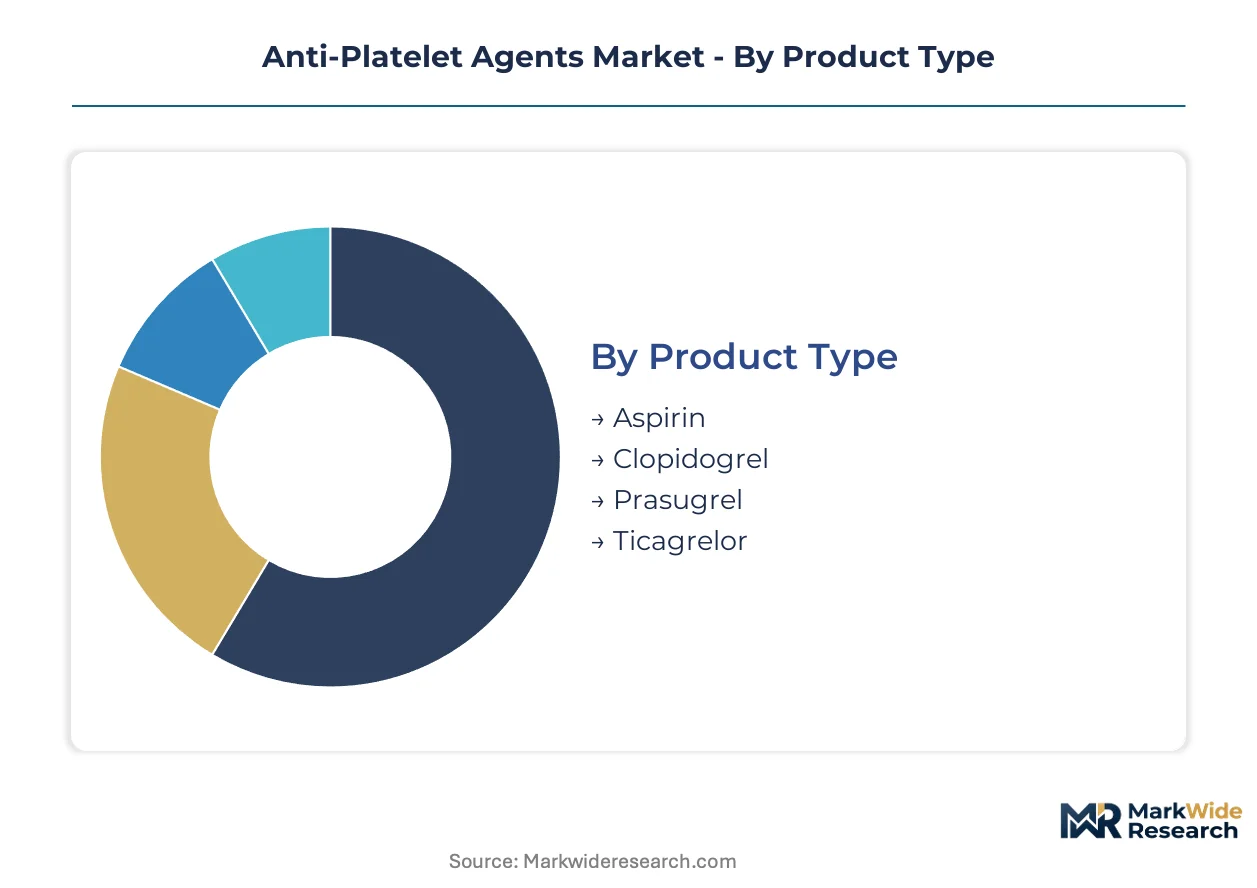
Anti-platelet agent segmentation reveals how formulation chemistry, clinical setting, and patient acuity reshape procurement patterns across cardiovascular care. Understanding these divisions exposes where pricing power concentrates and where generic substitution erodes margins.
Product Type:
Binding kinetics and metabolic pathways differentiate commercial positioning across the four molecular classes.
- Aspirin:Irreversible cyclooxygenase-1 inhibition produces permanent platelet suppression for the drug's lifespan. Demand concentrates in United States primary prevention protocols and post-stroke maintenance regimens, though bleeding risk concerns constrain expansion into elderly populations.
- Ticagrelor:Reversible P2Y12 antagonism enables faster offset kinetics critical for urgent surgical windows. Acute coronary syndrome protocols at Cleveland Clinic, Mayo Clinic, and Johns Hopkins have embedded this agent into STEMI bundles, driving premium pricing despite twice-daily dosing compliance challenges.
- Clopidogrel:Prodrug requiring CYP2C19 metabolism generates variable responder profiles that pharmacogenomic testing increasingly stratifies.
- Prasugrel:Third-generation thienopyridine with faster onset than clopidogrel but restricted labeling due to bleeding risk in prior stroke patients.
Mature deployment sits with aspirin and clopidogrel. Newer deployment is concentrated in ticagrelor for acute coronary syndrome pathways.
Therapy Area:
Procedural volume and reimbursement intensity vary sharply across these four cardiovascular indications.
- Cardiovascular Diseases:Broad acute coronary syndrome category spanning STEMI, NSTEMI, and unstable angina presentations. United States hospital discharge data shows percutaneous coronary intervention volumes sustaining dual antiplatelet therapy prescriptions at tertiary centers in Texas, Florida, and California.
- Stroke:Secondary prevention dominates, with aspirin monotherapy or combination approaches guided by TOAST classification of ischemic subtypes. Medicare reimbursement for transient ischemic attack workups creates diagnostic-driven prescribing windows in neurology clinics.
- Coronary Artery Disease:Chronic management of stable ischemic heart disease where risk stratification tools (SYNTAX score, FFR) determine revascularization candidacy and subsequent antiplatelet duration.
- Peripheral Artery Disease:Lower-extremity atherosclerosis with underrecognized antiplatelet utilization despite guideline recommendations for aspirin or clopidogrel monotherapy.
Volume concentrates in cardiovascular diseases and stroke. Peripheral artery disease shows the steepest expansion trajectory as screening protocols expand in diabetes populations.
Delivery Mode:
Speed of onset and care setting dictate formulation selection across the four administration routes.
- Oral:Tablets and capsules dominate outpatient maintenance therapy, with once-daily aspirin and clopidogrel maximizing adherence. United States retail pharmacy chains (CVS, Walgreens) move millions of units monthly through 90-day refill programs.
- Intravenous:Glycoprotein IIb/IIIa inhibitors (abciximab, eptifibatide, tirofiban) and IV cangrelor enable immediate platelet suppression in cardiac catheterization laboratories. Cleveland Clinic's cath lab protocols specify IV loading for high-risk PCI cases.
- Injectable:Subcutaneous formulations capture bridging scenarios where oral intake is contraindicated.
- Transdermal:Patch-based delivery remains investigational for aspirin, with adhesion and absorption variability limiting clinical adoption.
Oral formulations anchor chronic therapy. Intravenous deployment is expanding fastest as complex PCI volumes rise and same-day discharge protocols demand rapid therapeutic transitions.
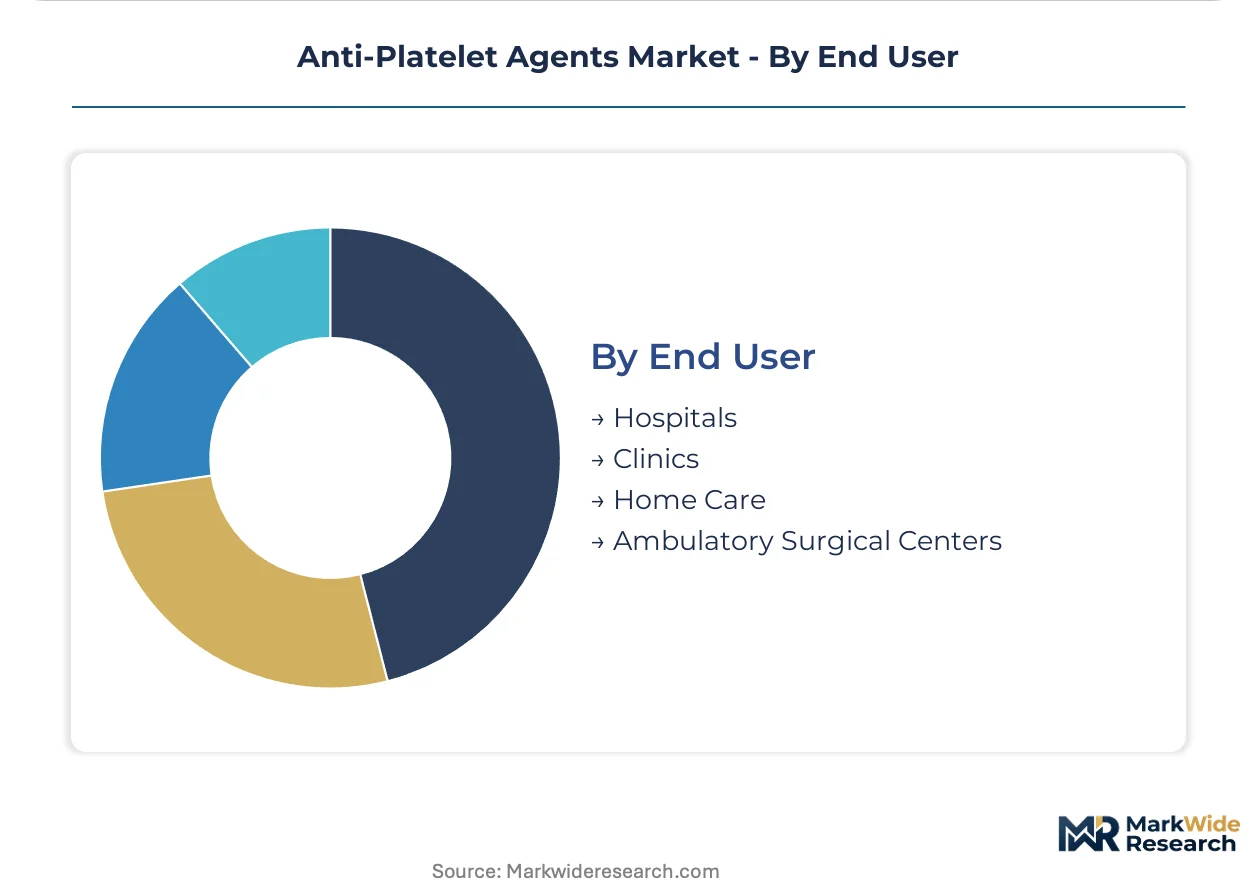
End User:
Purchasing authority and formulary control diverge across these four care settings.
- Hospitals:Integrated delivery networks negotiate sole-source contracts for P2Y12 inhibitors, embedding preferred agents into order sets. Catholic health systems in the Midwest and for-profit chains in the Southeast have unified formularies across dozens of facilities.
- Ambulatory Surgical Centers:Outpatient PCI and peripheral vascular procedures create same-day prescribing needs with limited on-site pharmacy infrastructure.
- Clinics:Cardiology and neurology offices manage chronic therapy adjustments, with prior authorization requirements varying by United States payer.
- Home Care:Post-discharge compliance monitoring and medication reconciliation fall to visiting nurses and telehealth platforms.
Procurement authority concentrates in hospital pharmacy and therapeutics committees. Ambulatory surgical centers represent the fastest-growing prescription origin as outpatient procedural volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States cardiac catheterization volumes sustain the highest per-capita consumption of P2Y12 inhibitors worldwide. Hospital procurement consortia in Texas, Florida, and California embed dual antiplatelet therapy into standardized discharge bundles. Aging demographics and procedural protocol standardization reinforce prescription concentration.
United States
Medicare reimbursement for percutaneous coronary intervention sustains dual antiplatelet therapy prescriptions at Cleveland Clinic, Mayo Clinic, and Johns Hopkins. FDA accelerated approval pathways compress development timelines for cardiovascular drug candidates. Integrated delivery networks in the Midwest and Southeast negotiate sole-source contracts embedding preferred agents into order sets.
Germany
EMA pharmacovigilance frameworks enforce post-market surveillance obligations that strain sponsor safety signal detection capacity. REACH compliance broadens cost-of-entry calculus for active pharmaceutical ingredient suppliers serving European formulations. Manufacturing clusters in North Rhine-Westphalia and Bavaria anchor salicylic acid precursor production for aspirin derivatives.
Japan
PMDA regulatory arbitrage offers prasugrel derivative development pathways distinct from FDA-established indications. METI industrial policy supports domestic pharmaceutical manufacturing scale. Tokyo and Osaka metropolitan areas concentrate cardiology research infrastructure and hospital pharmacy procurement authority.
China
NMPA marketing authorization requirements reshape clinical trial design for P2Y12 inhibitor candidates targeting domestic populations. Dual carbon goals pressure energy-intensive active pharmaceutical ingredient production facilities. Yangtze River Delta pharmaceutical clusters expand generic clopidogrel manufacturing capacity for export markets.
India
CDSCO regulatory harmonization efforts accelerate cardiovascular drug approval timelines for domestic sponsors. PLI scheme incentives attract contract manufacturing investment in oral antiplatelet formulations. Gujarat and Maharashtra pharmaceutical corridors export aspirin and clopidogrel active pharmaceutical ingredients to European and African markets.
Anti-Platelet Agents Market Competitive Landscape
United States and European pharmaceutical conglomerates anchor one tier; Japanese and Indian specialists hold differentiated positions in regional regulatory pathways. Market structure concentrates around diversified conglomerates with cardiovascular portfolios spanning multiple therapeutic modalities. Three archetypes dominate: backward-integrated precursor producers, reversible-binding kinetic specialists, and generic volume manufacturers. Competitive moves center on manufacturing scale-up coordination with regulatory velocity and biomarker-guided therapy service expansion.
Within the diversified pharmaceutical conglomerate tier, Pfizer Inc., AstraZeneca, and Bayer AG exemplify distinct strategic positioning. Pfizer represents scale-driven cardiovascular portfolio breadth. AstraZeneca occupies a position emphasizing reversible P2Y12 antagonism development intensity. Bayer anchors backward integration into salicylic acid precursors with established aspirin manufacturing scale. These three entities collectively illustrate how geographic origin and historical therapeutic focus shape competitive archetype selection in antiplatelet agent development.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi |
| AstraZeneca |
| Bayer AG |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Daiichi Sankyo Company, Limited |
| Eli Lilly And Company |
| Boehringer Ingelheim |
| Others |
Value Network & Pricing Analysis
Hospital procurement consortia in the United States are consolidating antiplatelet purchasing through multi-year sole-source agreements, forcing API suppliers to validate manufacturing lines against FDA accelerated approval timelines and compressing margin structures for generic clopidogrel and aspirin producers.
Pricing Analysis
Volume concentrates in mature oral formulations where generic competition has eroded unit economics, while premium pricing persists for reversible P2Y12 inhibitors in acute coronary syndrome protocols. Price differentiation hinges on binding kinetics profile and FDA label breadth for urgent surgical windows. Pricing pressure intensifies in clopidogrel and aspirin tiers due to Indian and Chinese API oversupply. Ambulatory surgical centers exhibit highest price sensitivity; Cleveland Clinic and Mayo Clinic networks command lowest net pricing through volume commitment leverage.
Supply Chain Analysis
Single-source vulnerability sits with salicylic acid precursor production concentrated in Germany and China, where Bayer's captive backward integration and Yangtze River Delta chemical clusters dominate feedstock access. Active pharmaceutical ingredient manufacturing draws from India, China, and Italy for oral formulations. Regulatory restriction risk looms through REACH compliance expansion and ECHA chemical safety frameworks. Distribution runs through hospital pharmacy and therapeutics committees with integrated delivery network consolidation displacing traditional wholesaler relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Salicylic acid precursor capacity constraints in Europe and energy-intensive API production pressures under China's dual carbon goals are propping pricing for backward-integrated incumbents while filtering marginal producers from the supply base.
For Market Incumbents: Extend manufacturing scale-up coordination with FDA accelerated approval velocity to defend ticagrelor premium positioning against prasugrel derivative entrants. Deepen backward integration into salicylic acid precursors to offset REACH compliance cost inflation. Prioritize biomarker-guided therapy service expansion adjacent to pharmaceutical sales to capture ISO 15189-accredited laboratory network revenue. For New Entrants and Emerging Players: Direct-to-clinic digital sampling platforms offer the lowest-friction route to penetrate ambulatory surgical center formularies where outpatient PCI volumes are expanding fastest. Target peripheral artery disease protocols for aspirin and clopidogrel monotherapy where screening expansion in diabetes populations creates underpenetrated demand. Pursue Asian regulatory arbitrage through PMDA and NMPA prasugrel derivative pathways distinct from FDA-established indications. For Investors and Strategic Acquirers: Re-rating potential sits with reversible-binding kinetic specialists given pharmacogenomic integration tailwinds and point-of-care testing adoption reshaping prescribing workflows. Long-term viability favors sponsors with simultaneous FDA, EMA, and PMDA pharmacovigilance infrastructure. Watch for CYP2C19 genotyping reimbursement harmonization across United States payers as inflection indicator for personalized therapy adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up Coordination | FDA accelerated approval timelines compress process validation windows for reversible P2Y12 production lines. |
| Biomarker-Guided Therapy Service Expansion | ISO 15189-accredited laboratory networks enable personalized dual antiplatelet therapy duration protocols. |
| Asian Regulatory Arbitrage Development | PMDA and NMPA prasugrel derivative pathways offer label expansion distinct from FDA indications. |
| Backward Integration into Precursors | Captive salicylic acid production insulates against REACH compliance cost inflation in European formulations. |
| Hospital System Partnership Consolidation | Sole-source contracts with Catholic health systems and for-profit chains embed preferred agents into order sets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases supplied validation benchmarks. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were reconciled through iterative triangulation.
Data-stream reconciliation across patient-level claims, hospital discharge records, and API trade flows informed segmentation by binding kinetics, therapy area, delivery mode, and end-user setting across the analysis window. CAGRs were derived from procedural volume trajectories and demographic aging patterns. Forecast inputs incorporated cardiac catheterization rates, genotyping reimbursement evolution, and REACH compliance implementation timelines.
The model holds under stable regulatory harmonization and continued PCI volume expansion; deviation in CYP2C19 testing coverage policy or salicylic acid supply disruption would shift trajectory bounds. Forecasts reflect documented assumptions regarding protocol standardization and procurement consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Global Anthrax Vaccine Market
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
North America Hormone Replacement Therapy Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Topical Corticosteroids Market