
 Ultrasound Image Processing Software Market | 2026-2036
Ultrasound Image Processing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Image Processing Software Market Analytics
Hospital procurement is pivoting toward enterprise-wide AI-enhanced ultrasound platforms rather than point solutions. Siemens Healthineers AG leverages deep learning architectures to anchor its cardiology imaging suite across integrated delivery networks. GE Healthcare competes through embedded analytics within its ultrasound hardware ecosystem, sustaining recurring software revenue streams.
Ultrasound image processing software encompasses computational algorithms that reconstruct, enhance, and quantify acoustic data from transducer arrays into clinically interpretable visual outputs. These systems apply noise reduction, speckle suppression, and real-time rendering at frame rates exceeding 30 Hz to support diagnostic decision-making in time-critical clinical workflows. Three-dimensional imaging commands premium positioning in obstetrics applications where volumetric fetal assessment reduces repeat scan rates. Cloud-based solutions represent the fastest-expanding technology segment as diagnostic centers seek scalable storage and remote interpretation capabilities without capital-intensive server infrastructure.
FDA premarket review under the Software as a Medical Device framework shapes product development roadmaps for vendors targeting the United States, while the EU Medical Device Regulation imposes clinical evidence requirements on AI-based diagnostic modules seeking CE marking. The country's national pharmaceutical regulator in Japan evaluates algorithmic transparency as a condition of PMDA approval, adding compliance layers for machine-learning-enabled quantification tools. Stakeholders must monitor evolving predicate-device precedents for AI-augmented ultrasound classifications across major jurisdictions to align regulatory investment with commercial timelines.
Market Dynamics
Hospital procurement departments now mandate AI-enhanced ultrasound platforms that integrate across enterprise imaging networks, compressing vendor selection cycles and favoring suppliers with embedded analytics architectures over standalone software licensors.
Growth Catalysts
- FDA Software as a Medical Device framework:Streamlined premarket review pathways accelerate commercialization timelines for algorithmic diagnostic tools targeting the United States market.
- Cloud-native deployment models:Diagnostic centers adopt scalable storage infrastructure without capital-intensive server investments, expanding addressable customer bases to mid-tier facilities.
- Obstetrics volumetric imaging:Three-dimensional fetal assessment protocols reduce repeat scan rates, driving software upgrades in maternal-fetal medicine departments.
Market Restraints
- GPU compute cost volatility:Real-time rendering at 30+ Hz frame rates requires specialized semiconductor hardware subject to supply chain concentration in East Asian foundries.
- EU Medical Device Regulation clinical evidence requirements:CE marking for AI-based diagnostic modules demands extensive validation studies, extending development cycles for European market entry.
- Speckle suppression algorithm limitations:Current computational methods trade spatial resolution against noise reduction, constraining diagnostic confidence in low-contrast tissue differentiation.
Strategic Opportunities
- Rural hospital networks in India:Telemedicine-linked ultrasound interpretation creates demand for lightweight, cloud-connected processing platforms in underserved districts.
- Point-of-care emergency medicine:Handheld transducer integration with tablet-based AI quantification opens deployment in ambulances and field triage units.
- Japan PMDA algorithmic transparency mandates:Compliance investments by early entrants create regulatory moats against later competitors in machine-learning-enabled diagnostic tools.
Industry Challenges
- Computational sonographer training gaps:Clinical workflows require specialists who bridge acoustic physics, deep learning model interpretation, and diagnostic radiology, with limited accredited programs producing qualified personnel.
- Legacy PACS integration complexity:Enterprise imaging archives built on DICOM standards from prior decades resist seamless API connectivity with modern AI inference engines, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Image Processing Software Market |
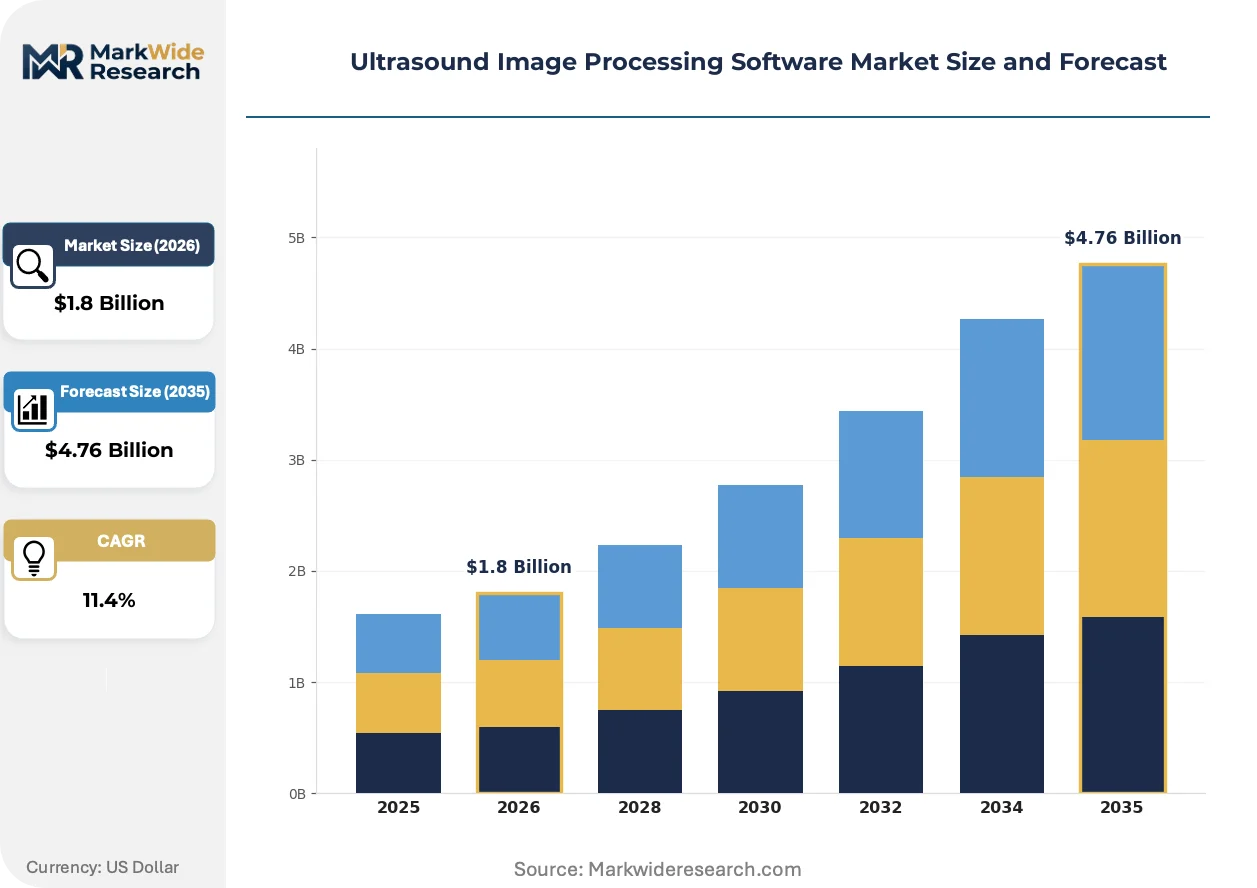
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Imaging, 3D Imaging, Doppler Imaging, Elastography Technology: AI-Based Solutions, Cloud-Based Solutions, Standalone Software, Integrated Systems End User: Hospitals, Clinics, Diagnostic Centers, Research Institutes Application: Obstetrics, Cardiology, Urology, Musculoskeletal |
| Companies Covered | Koninklijke Philips N.V., Siemens Healthineers AG, GE Healthcare, CANON MEDICAL SYSTEMS CORPORATION, Esaote SpA, Agfa-Gevaert Group, Fujifilm Holdings Corporation, MIM Software, Inc., Mindray Medical International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Image Processing Software Market Evolving Landscape
Real-time inference at the edge is redistributing computational workloads away from centralized data centers, enabling diagnostic decision support in bandwidth-constrained clinical environments.
Edge AI processing is decentralizing ultrasound interpretation by embedding neural network inference directly within transducer hardware and connected tablets. Emergency departments and rural clinics adopt these architectures to bypass cloud latency in time-critical workflows. The shift compresses infrastructure requirements for advanced diagnostic capabilities, expanding deployment scenarios beyond traditional hospital radiology suites.
REACH chemical substance restrictions and RoHS hazardous material limits in Europe constrain printed circuit board manufacturing for ultrasound hardware, forcing redesigns of signal processing modules. Vendors reformulate solder compositions and substrate materials to maintain CE marking eligibility. Cardiology imaging systems face the steepest compliance costs due to their dense component packaging and thermal management requirements.
Subscription-based software licensing is displacing perpetual purchase models as integrated health systems negotiate enterprise-wide agreements spanning multiple facilities. Radiology departments unbundle hardware procurement from analytics subscriptions, treating image processing as an operational expense rather than capital outlay. The United States exhibits the most pronounced shift, with IDNs consolidating vendor relationships across 15+ hospital networks.
Ultrasound Image Processing Software Market Segmentation
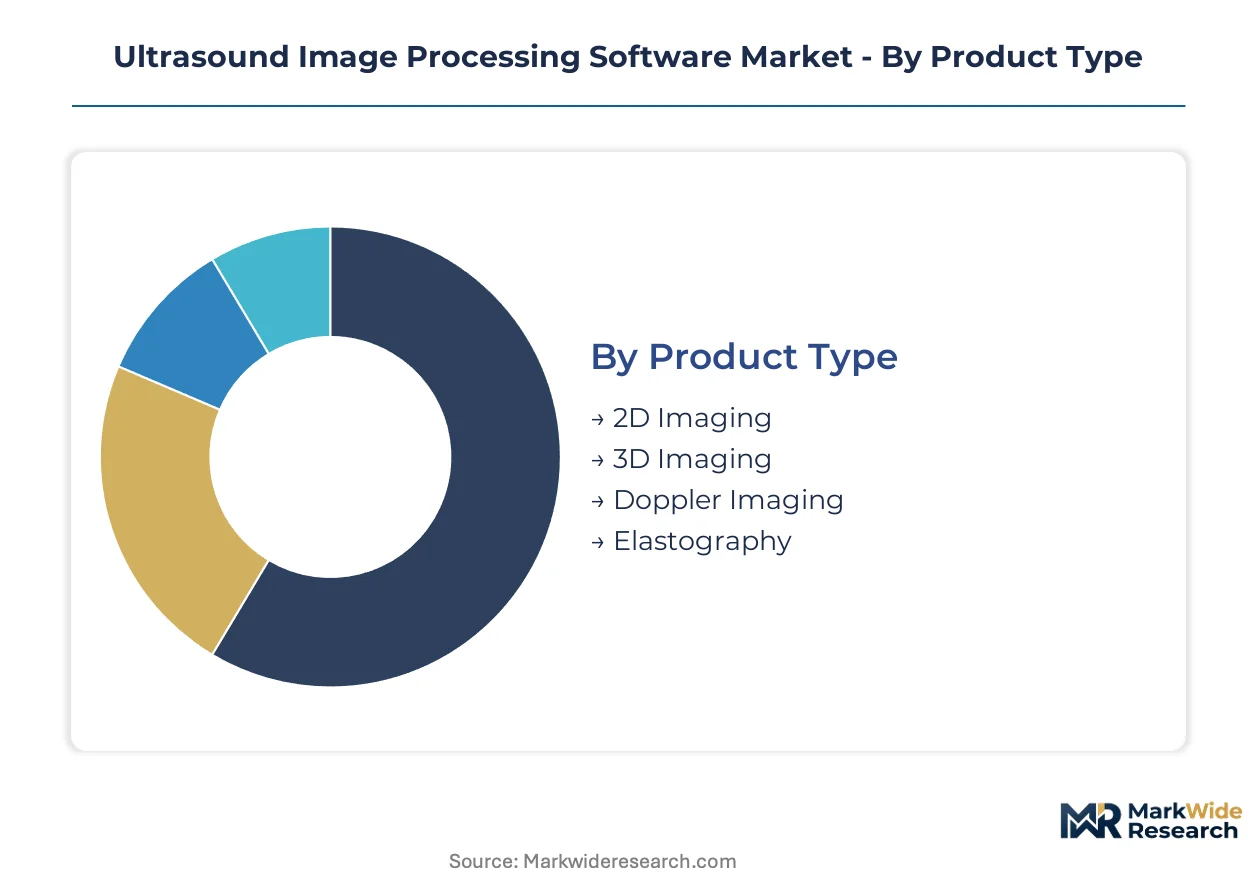
Ultrasound image processing software segments diverge sharply by integration depth, with embedded systems commanding premium pricing against standalone deployments. Procurement patterns across hospitals and diagnostic centers favor architectures that compress workflow friction and unify data pipelines.
Product Type:
Integration depth varies dramatically: 2D and Doppler systems dominate standalone installations, while 3D imaging and elastography require tight hardware coupling.
- 2D Imaging:Foundational grayscale reconstruction algorithms process B-mode acoustic data at sub-30-millisecond latency. Demand concentrates in primary care clinics across India and Brazil where cost constraints limit hardware refresh cycles.
- 3D Imaging:Volumetric rendering engines reconstruct multi-planar fetal and cardiac views from rotational transducer sweeps. Maternal-fetal medicine departments in United States integrated delivery networks drive replacement demand as repeat scan reduction protocols tighten.
- Doppler Imaging:Spectral and color flow mapping for hemodynamic assessment in cardiology and vascular departments.
- Elastography:Strain and shear-wave stiffness quantification for liver fibrosis and breast lesion characterization.
Volume placements concentrate in 2D Imaging; the faster expansion belongs to 3D Imaging.
Technology:
Cost tier stratification separates capital-intensive integrated systems from lightweight cloud subscriptions accessible to mid-tier facilities.
- AI-Based Solutions:Deep learning models automate lesion detection, measurement, and classification with FDA-cleared algorithms for thyroid nodule assessment. United States hospital procurement mandates are accelerating enterprise-wide deployment across radiology and cardiology service lines.
- Cloud-Based Solutions:Scalable SaaS architectures eliminate on-premise server infrastructure for storage and remote interpretation. Diagnostic centers in Germany and France adopt these platforms to comply with EU data sovereignty requirements while avoiding hardware capital expenditure.
- Standalone Software:Perpetual-licensed packages running on conventional workstations without vendor hardware lock-in.
- Integrated Systems:Embedded processing modules within OEM ultrasound hardware with recurring software revenue streams.
Integrated Systems capture the largest installed base; AI-Based Solutions are climbing the fastest as FDA premarket pathways compress commercialization timelines.
End User:
Customer type determines procurement authority complexity, with hospital networks negotiating enterprise agreements against single-facility clinic purchases.
- Hospitals:Enterprise imaging networks mandate AI-enhanced platforms with PACS integration and multi-department deployment rights. United States integrated delivery networks consolidate vendor relationships across 15-plus hospital systems.
- Clinics:Point-of-care deployments favor handheld transducer and tablet combinations for immediate diagnostic feedback.
- Diagnostic Centers:High-throughput facilities prioritize throughput optimization and automated reporting workflows.
- Research Institutes:Algorithm development environments requiring raw data access and custom model training pipelines.
Hospitals dominate absolute spending; Diagnostic Centers show the steepest expansion trajectory as outpatient imaging volume shifts from inpatient settings.
Application:
Maturity curves separate established obstetrics protocols from emerging musculoskeletal adoption where reimbursement pathways remain unsettled.
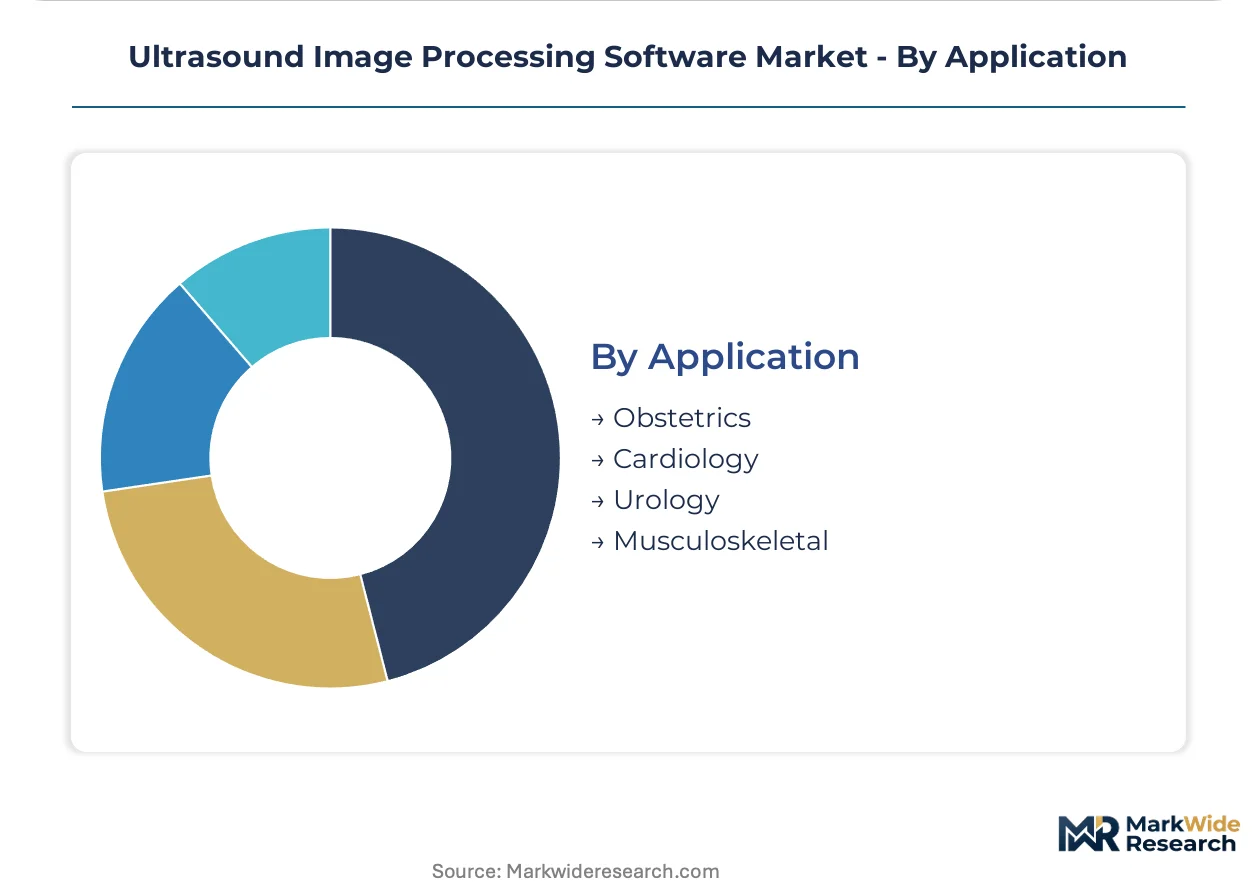
- Obstetrics:Volumetric fetal assessment with biometric automation and anomaly detection screening. Three-dimensional imaging protocols in United States maternal-fetal medicine reduce repeat scan rates and malpractice exposure.
- Cardiology:Strain imaging, automated ejection fraction calculation, and AI-guided valve assessment. German cardiology departments drive demand for embedded analytics as CE marking requirements under EU MDR elevate validation standards.
- Urology:Prostate volume measurement and renal hemodynamic assessment in urology practices.
- Musculoskeletal:Tendon, ligament, and joint imaging with shear-wave elastography for sports medicine applications.
Obstetrics maintains the deepest penetration; Musculoskeletal represents the fastest-growing application as sports medicine clinics expand ultrasound-first diagnostic protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan anchors GPU supply chains for real-time ultrasound rendering engines, while regulatory divergence across Washington, Brussels, and Tokyo fragments software certification pathways. Hospital procurement authority concentrates in integrated delivery networks that span multiple jurisdictions.
United States
Integrated delivery networks in Texas and California mandate enterprise-wide AI-enhanced ultrasound platforms with embedded analytics architectures. FDA Software as a Medical Device framework compresses premarket review timelines for algorithmic diagnostic tools. The Research Triangle Park cluster in North Carolina hosts validation laboratories where machine-learning models undergo clinical evidence generation for 510(k) submissions.
Germany
Cardiology departments in Bavaria and North Rhine-Westphalia drive demand for strain imaging and automated ejection fraction calculation modules. EU Medical Device Regulation imposes extensive clinical evidence requirements on AI-based diagnostic modules seeking CE marking. The Munich medical technology corridor concentrates embedded systems engineering talent for ultrasound hardware-software integration.
Japan
Academic medical centers in Tokyo and Osaka evaluate algorithmic transparency as a condition of PMDA approval for machine-learning-enabled quantification tools. METI funding programs accelerate edge AI processing development for bandwidth-constrained clinical environments. The Kansai biomedical cluster advances real-time inference architectures within transducer hardware.
India
Rural hospital networks in Maharashtra and Karnataka adopt telemedicine-linked ultrasound interpretation platforms for underserved districts. CDSCO regulatory pathways for Software as a Medical Device remain under development, creating compliance uncertainty for foreign vendors. The Hyderabad medical devices corridor attracts cloud-native software developers targeting point-of-care deployments.
United Kingdom
NHS England procurement frameworks favor cloud-based solutions with scalable storage infrastructure for diagnostic centers in London and Manchester. MHRA post-Brexit regulatory divergence from EU MDR creates dual certification burdens for AI-augmented ultrasound classifications. The Cambridge life sciences cluster develops raw data access pipelines for research institute algorithm training.
Ultrasound Image Processing Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native deployment models and edge AI architectures. The vendor base stratifies across three tiers: diversified medical technology conglomerates with embedded hardware-software ecosystems, specialized imaging software developers with SaaS delivery capabilities, and regional equipment manufacturers with localized service networks. Dominant competitive moves include strategic partnerships for PACS integration and portfolio diversification into AI-based diagnostic modules.
Within the diversified conglomerate tier, Koninklijke Philips N.V. and Siemens Healthineers AG occupy positions exemplifying enterprise-wide platform strategies. GE Healthcare anchors the embedded analytics architecture segment. Among specialized developers, MIM Software, Inc. represents the standalone software licensor archetype targeting research institute algorithm development environments.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| GE Healthcare |
| CANON MEDICAL SYSTEMS CORPORATION |
| Esaote SpA |
| Agfa-Gevaert Group |
| Fujifilm Holdings Corporation |
| MIM Software, Inc. |
| Mindray Medical International Limited |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in the United States concentrate procurement authority for AI-enhanced ultrasound platforms, compressing vendor selection cycles and entrenching subscription-based SaaS pricing as the dominant commercial model across enterprise imaging networks.
Pricing Analysis
Volume placements concentrate in 2D imaging tiers where cost constraints limit hardware refresh cycles in India and Brazil, while premium margins accrue to 3D volumetric rendering and AI-based diagnostic modules in United States maternal-fetal medicine departments. Pricing stratifies across embedded analytics architectures, standalone software licenses, and cloud-native SaaS subscriptions, with FDA-cleared algorithm tiers commanding substantial premiums over uncertified equivalents. Pricing pressure stems from GPU compute cost volatility and foundry supply chain concentration in Taiwan, compressing margins for real-time rendering engines. Mid-tier diagnostic centers in Germany and France exhibit the highest price sensitivity, deferring capital-intensive integrated system purchases in favor of scalable cloud subscriptions.
Supply Chain Analysis
Regional distribution centers in Singapore and Rotterdam anchor hub-and-spoke logistics for ultrasound hardware components serving Asian and European diagnostic centers respectively. GPU semiconductor supply concentrates in Taiwan and South Korea, with advanced packaging capacity in the United States, while printed circuit board manufacturing feeds from China and Vietnam under REACH and RoHS regulatory constraints. Raw material dependencies span rare earth elements for transducer piezoelectric crystals, high-purity silicon for signal processing modules, and specialized solder compositions reformulated for CE marking eligibility. Single-source vulnerability in Taiwan foundry capacity represents the dominant structural risk. Distribution runs through OEM direct sales forces for integrated systems and cloud platform providers for SaaS deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise-wide procurement mandates from United States integrated delivery networks are forcing consolidation among standalone software vendors unable to embed analytics within hardware ecosystems or secure FDA Software as a Medical Device clearances.
For Market Incumbents: Lock in enterprise imaging network contracts across multi-hospital systems before cloud-native entrants achieve regulatory parity, while deepening backward integration into GPU allocation agreements with Taiwan foundries to secure semiconductor supply for real-time rendering engines. Defensive investments in PACS integration middleware address legacy archive connectivity gaps that emerging competitors exploit. For New Entrants and Emerging Players: Edge AI processing architectures embedded within handheld transducer hardware offer a technology-first wedge into point-of-care emergency medicine and rural telemedicine networks in India where bandwidth constraints exclude cloud-dependent incumbents. Target Maharashtra and Karnataka district hospitals with lightweight tablet-based quantification tools and CDSCO-compliant regulatory pathways. For Investors and Strategic Acquirers: The window for entry favors specialized imaging software developers with SaaS delivery capabilities and FDA-cleared algorithm portfolios, as diversified conglomerates seek acquisition targets to fill AI diagnostic module gaps. Watch PMDA algorithmic transparency mandate compliance investments as the inflection signal for Japan market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Accelerates commercialization timelines for algorithmic diagnostic tools targeting United States hospital procurement. |
| CE Marking Pathway under EU MDR | Enables market access for AI-based modules in German cardiology departments with elevated validation standards. |
| Hospital System Partnership | Secures enterprise-wide deployment rights across United States integrated delivery networks consolidating vendor relationships. |
| Software Companion Development | Extends hardware platform utility through recurring analytics subscriptions in embedded systems architectures. |
| Reimbursement Strategy | Aligns AI quantification tool positioning with CMS and private payer coverage determinations for automated diagnostic reporting. |
Research Methodology
Multi-period observation of FDA 510(k) clearance trajectories, EU MDR CE marking timelines, and hospital procurement contract values anchored the trend analysis, supplemented by interviews with ultrasound product managers at diversified medical technology conglomerates, regulatory affairs specialists navigating Software as a Medical Device frameworks, hospital purchasing committee chairs at United States integrated delivery networks, biomedical engineers managing PACS integration projects, and cloud platform architects at diagnostic center SaaS providers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR clinical evidence submission records, hospital procurement databases tracking enterprise imaging network vendor selections, GPO contract disclosure filings, and CMS Medicare reimbursement coding updates. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models.
Segment-weighting approaches distributed value and volume projections across integration depth tiers, technology architectures, and end-user procurement authority levels throughout the forecast period. CAGRs derived from fitted growth curves applied to AI-based solutions, cloud-based deployments, and embedded analytics modules respectively, with elasticity adjustments for GPU compute cost volatility and regulatory pathway compression effects. Industry-specific forecast inputs incorporated PMDA algorithmic transparency mandate compliance timelines and CDSCO Software as a Medical Device pathway development status.
Several conditions sit outside the modeled scope, including unforeseen regulatory reclassification of AI diagnostic algorithms, acute semiconductor supply disruptions beyond Taiwan foundry concentration risks, and rapid reimbursement policy shifts affecting automated quantification tool coverage. Forecasts reflect documented assumptions regarding FDA premarket review efficiency, EU MDR clinical evidence generation timelines, and cloud infrastructure scaling economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
India Magnetic Resonance Imaging Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Fluorescence Microscopy Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Saudi Arabia Digital Radiology Market