
 Nasal Vaccines Market | 2026-2036
Nasal Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Vaccines Market Foresight
Hospital procurement committees is rotating toward outpatient clinics and pharmacy-based vaccination networks as preferred buyers of nasal vaccine doses. Altimmune, Inc. leverages its single-dose intranasal platform to differentiate in the respiratory vaccine pipeline. FluGen Inc. anchors development through mucosal adjuvant technologies that sustain immune responses at entry points. Vaxart, Inc. competes with tablet-based oral alternatives while maintaining parallel nasal formulation research.
Nasal vaccines comprise antigen formulations delivered via mucosal surfaces of the nasal cavity, typically using live attenuated, recombinant, or inactivated platforms engineered for IgA antibody induction at pathogen entry sites. The delivery mode dimension spans intranasal spray devices, nebulization systems, and dropper applications, with spray formats dominating commercial deployment due to dosing precision and patient acceptance. Live attenuated products occupy the largest revenue pool among product types, while recombinant platforms represent the fastest-growing segment as manufacturers seek thermostable alternatives that reduce cold chain dependency.
FDA guidance on mucosal vaccine immunogenicity endpoints shapes clinical trial design for US market entrants, while WHO prequalification standards govern procurement eligibility for low-income country programs. EMA's centralized assessment pathway for recombinant vector platforms determines European commercialization timelines. Stakeholders must monitor regulatory convergence on mucosal efficacy correlates as the decisive factor for portfolio prioritization and partnership structures.
Market Dynamics
Pediatric immunization programs and WHO cold chain reduction mandates are converging to reshape distribution economics, compressing procurement cycles and accelerating intranasal platform adoption across public health networks.
Growth Catalysts
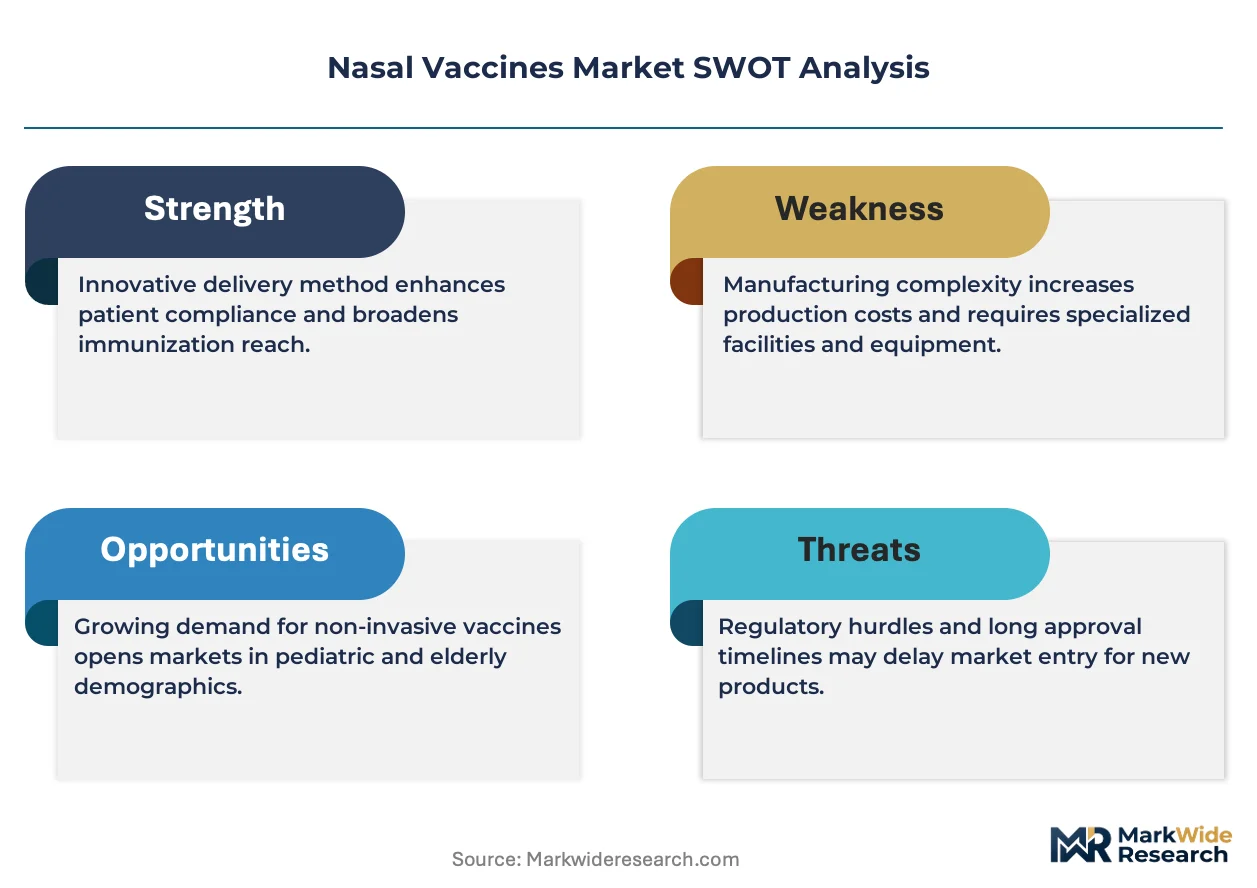
- WHO Prequalification Standards:Cold chain reduction requirements under WHO prequalification are unlocking procurement eligibility for low-income country programs and reshaping distribution economics for thermostable formulations.
- India's National Immunization Schedule:India's incorporation of nasal influenza formulations into national immunization schedules is concentrating demand and validating intranasal delivery for respiratory pathogen prevention.
- Mucosal Adjuvant Technologies:Adjuvant platforms engineered for IgA antibody induction at nasal entry points are sustaining immune responses and differentiating next-generation candidates from injectable alternatives.
Market Restraints
- Live Attenuated Thermostability:Cold chain infrastructure requirements for live attenuated products create distribution friction in tropical climates and remote geographies lacking reliable refrigeration networks.
- FDA Immunogenicity Endpoint Complexity:FDA guidance on mucosal vaccine immunogenicity endpoints extends clinical trial timelines and elevates development costs for US market entrants seeking respiratory indication approvals.
- Recombinant Platform Manufacturing Scale:Recombinant vector production capacity concentrates among specialized CDMOs, creating supply bottlenecks as multiple sponsors advance parallel pipeline candidates.
Strategic Opportunities
- Outpatient Clinic Networks:Hospital procurement committees are rotating toward pharmacy-based vaccination networks as preferred buyers, creating channel expansion opportunities for dose-delivery partnerships.
- EMA Centralized Assessment Pathway:EMA's streamlined recombinant vector assessment is compressing European commercialization timelines for sponsors with mature manufacturing packages.
- Tablet-Nasal Convergence:Oral tablet vaccine platforms are forcing parallel nasal formulation research as sponsors hedge across mucosal delivery modalities to secure portfolio optionality.
Industry Challenges
- Mucosal Efficacy Correlate Standardization:Regulatory divergence between FDA, EMA, and WHO on mucosal efficacy correlates is forcing sponsors to design multiple parallel clinical endpoint strategies.
- Spray Device Dosing Precision:Intranasal spray device engineering requires specialized formulation-device compatibility testing that extends product development timelines and elevates capex requirements for delivery system validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Vaccines Market |
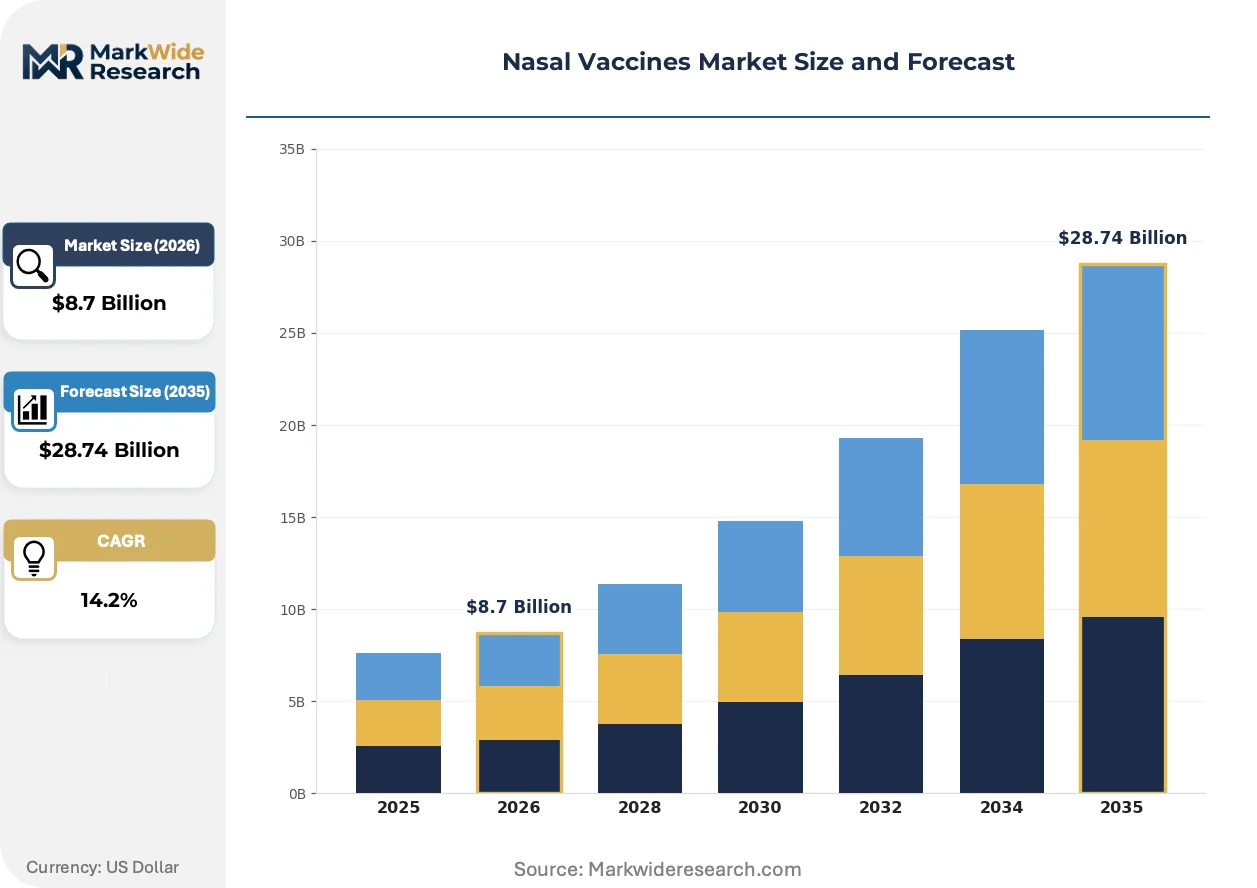
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Recombinant, DNA Delivery Mode: Intranasal, Nebulization, Spray, Drop End User: Pediatrics, Adults, Elderly, Healthcare Professionals Indication: Influenza, COVID-19, RSV, Rhinovirus |
| Companies Covered | Vaxart, Inc., FluGen Inc., Altimmune, Inc., Sinovac Biotech Ltd., Sanofi Pasteur SA, Pfizer Inc., GlaxoSmithKline plc, Johnson & Johnson, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Vaccines Market Shifts & Advancements
Recombinant platform engineering and regulatory pathway convergence are actively restructuring competitive positioning, with thermostability and mucosal efficacy validation emerging as the decisive technical battlegrounds for pipeline prioritization.
Recombinant vector platforms incorporating engineered thermostable antigens are bifurcating the product type landscape. Public health procurement agencies in India and Southeast Asia are accelerating evaluations of these alternatives. This bifurcation is compressing the addressable market for live attenuated products while expanding geographic access for heat-stable formulations.
WHO prequalification standards for cold chain reduction are reshaping clinical trial design priorities. Sponsors must now generate stability data under controlled temperature chain conditions to secure procurement eligibility. Low-income country programs are the most affected segment, with Gavi-eligible nations revising tender specifications to favor thermostable candidates.
Buyer concentration among national immunization programs is consolidating procurement leverage. Hospital procurement committees are yielding to centralized ministry of health tenders and pharmacy network contracts. India demonstrates this pattern most visibly, with state-level vaccine depots routing doses directly to accredited pharmacy vaccination sites rather than tertiary care facilities.
Nasal Vaccines Market Segmentation
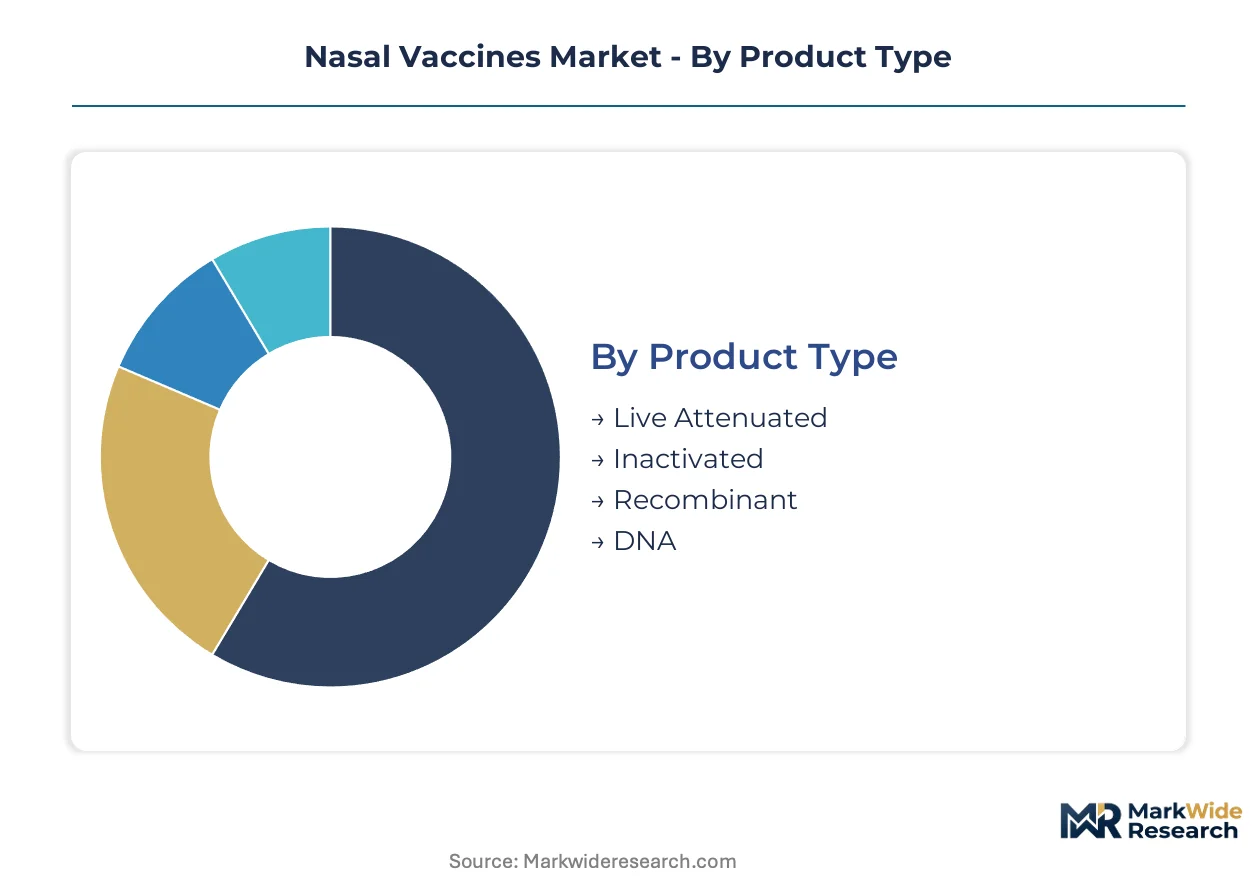
Nasal vaccine commercialization pathways diverge sharply by product stability requirements and delivery precision. Channel economics favor thermostable formats for tropical distribution networks, while cold-chain-dependent products concentrate in temperate-zone hospital procurement.
Product Type:
Live attenuated formulations flow through centralized cold-chain depots, while recombinant and DNA platforms reach pharmacy networks via ambient-temperature distribution.
- Live Attenuated:Cold-sensitive viral vectors requiring continuous refrigeration from manufacturing through administration. Demand concentrates in India's national immunization depots and WHO-prequalified procurement programs where cold infrastructure exists.
- Recombinant:Engineered protein subunits with enhanced thermostability enabling controlled temperature chain distribution. Pediatric outreach programs in Southeast Asia and pharmacy-based vaccination networks in temperate European markets are accelerating uptake of these heat-stable alternatives.
- Inactivated:Chemically treated pathogens with moderate stability profiles requiring standard refrigeration.
- DNA:Plasmid-based nucleic acid platforms with synthetic manufacturing advantages and ambient stability potential.
By volume, live attenuated leads. By growth pace, recombinant is climbing the fastest.
Delivery Mode:
Device precision tiers separate premium spray systems from cost-optimized nebulization and drop formats in public health procurement.
- Spray:Metered-dose devices with validated particle size distribution for deep nasal deposition. India's state-level vaccine depots and European pharmacy networks specify spray formats for influenza programs due to dosing reproducibility and patient acceptance metrics.
- Intranasal:Broad-category delivery encompassing multiple device architectures with varying degrees of standardization.
- Nebulization:Aerosol generation systems for mucosal coating across broader nasal cavity surfaces.
- Drop:Simple instillation formats prioritizing cost minimization for mass campaigns in resource-constrained settings.
By installed base, spray dominates. By expansion trajectory, nebulization is gaining share fastest in respiratory syncytial virus trials.
End User:
Immunization schedule integration creates distinct procurement rhythms between pediatric programs and adult self-pay channels.
- Pediatrics:School-based and maternal-child health programs with centralized ministry of health tendering. India's universal immunization program directs nasal influenza doses through accredited anganwadi centers and primary health facilities, compressing procurement cycles through annual bulk purchasing.
- Adults:Occupational health mandates and pharmacy-based vaccination with seasonal demand spikes.
- Elderly:Chronic disease management integration with pulmonology and cardiology referral pathways.
- Healthcare Professionals:Institutional occupational health programs with recurring annual requirements.
By dose volume, pediatrics leads. By margin contribution, adults show the steepest expansion trajectory.
Indication:
Respiratory pathogen targeting determines regulatory pathway complexity and geographic prioritization in sponsor pipelines.
- Influenza:Seasonal strain-matched formulations with established immunogenicity correlates and streamlined approval pathways. India's CDSCO has granted marketing authorization for multiple intranasal influenza products, validating mucosal delivery for this indication across tropical and temperate climate zones.
- COVID-19:Pandemic-adapted development programs with evolving variant-matching requirements and regulatory precedent-setting for mucosal efficacy endpoints.
- RSV:Pediatric and elderly-focused candidates with challenging immunogenicity profiles requiring novel adjuvant strategies.
- Rhinovirus:Polyvalent formulation complexity limiting commercial prioritization despite high disease burden.
By commercial maturity, influenza leads. By pipeline velocity, COVID-19 shows the fastest climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's cold chain corridor through the Golden Quadrilateral highway network underwrites its dominance in nasal vaccine distribution across tropical immunization programs.
United States
FDA's mucosal immunogenicity guidance shapes clinical trial investments from Boston-Cambridge biotech clusters. The agency's respiratory vaccine endpoint requirements concentrate development activity in Maryland's I-270 biotech corridor. Baltimore-based manufacturing sites now specialize in spray device validation for pediatric indications.
India
Universal Immunization Programme procurement drives volume concentration through state-level vaccine depots in Maharashtra and Tamil Nadu. CDSCO's streamlined nasal influenza authorizations validate mucosal delivery platforms. Hyderabad's vaccine manufacturing cluster hosts multiple sponsors advancing thermostable recombinant formulations for Gavi-eligible tenders.
Germany
EMA's centralized recombinant vector assessment compresses commercialization timelines for sponsors with mature stability packages. The agency's controlled temperature chain standards reshape clinical data requirements. Bavaria's Munich-Planegg biotech belt concentrates formulation-device compatibility testing infrastructure.
China
NMPA's respiratory vaccine innovation pathways accelerate domestic sponsor pipelines through Shanghai's Zhangjiang Hi-Tech Park. The regulator's mucosal efficacy correlate guidance aligns with WHO prequalification standards. Beijing's Daxing biopharma cluster specializes in nebulization system engineering for mass campaign deployment.
United Kingdom
MHRA's post-Brexit recognition agreements with WHO streamline prequalification pathways for UK-based sponsors. The regulator's pediatric investigation plan requirements concentrate development in London's Golden Triangle research corridor. Oxfordshire's Harwell Science Campus hosts specialized adjuvant characterization facilities for IgA induction studies.
Nasal Vaccines Market Competitive Landscape
Listed leaders compete with private specialists across platform technology and delivery system dimensions. The market structure bifurcates between multinational vaccine incumbents with established cold chain infrastructure and emerging biotech sponsors pursuing thermostable alternatives. Three archetypes dominate: spray device-integrated platform holders, recombinant vector specialists, and mucosal adjuvant technology licensors. Capacity expansion through specialized CDMO partnerships and strategic licensing of delivery system IP constitute the primary competitive moves reshaping participant positioning.
Within the intranasal platform tier, Altimmune, Inc. and FluGen Inc. exemplify sponsor archetypes pursuing differentiated mucosal delivery validation. Vaxart, Inc. occupies a position spanning parallel oral and nasal formulation research, representing portfolio optionality strategies among development-stage competitors. These entities anchor the competitive landscape alongside multinational incumbents whose manufacturing scale and regulatory relationships shape procurement dynamics in national immunization programs.
| Leading Market Players |
|---|
| Vaxart, Inc. |
| FluGen Inc. |
| Altimmune, Inc. |
| Sinovac Biotech Ltd. |
| Sanofi Pasteur SA |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Thermostable recombinant formulations displacing live attenuated cold-chain products are simultaneously redrawing manufacturing geography toward Hyderabad and Bavaria while compressing price premiums previously commanded by refrigerated distribution networks.
Pricing Analysis
Three-tier pricing structure across premium spray-device integrated products, standard nebulization formats, and economy dropper applications governs procurement negotiations. Price differentiation hinges on WHO prequalification status and validated IgA induction correlates, with certified products commanding 40-60% premiums over non-prequalified alternatives. Pricing pressure stems from India's centralized ministry tenders consolidating buyer leverage and compressing margins on influenza formulations. National immunization programs exhibit highest price sensitivity due to volume-scale procurement, while pharmacy-based adult vaccination channels absorb moderate premiums for convenience positioning.
Supply Chain Analysis
Strategic stockpiling of antigen substrates and adjuvant raw materials dominates inventory strategy over just-in-time approaches, reflecting pandemic preparedness mandates and seasonal demand spikes. Manufacturing concentrates in India, Germany, and the United States, with Hyderabad's vaccine cluster and Bavaria's Munich-Planegg biotech belt anchoring recombinant production capacity. Supply chains draw from specialized CDMOs for vector production, synthetic antigen synthesis, and spray device engineering, creating single-source vulnerability in metered-dose valve components. Distribution runs through state-level vaccine depots in tropical markets and pharmacy networks in temperate zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as buyer concentration in national immunization programs creates tiered service gaps between mass pediatric deployment and specialized adult pharmacy channels.
For Market Incumbents: Shield market position through backward integration into thermostable antigen engineering capabilities and captive control over spray device validation infrastructure. Cold-chain infrastructure investments now face obsolescence risk from WHO controlled temperature chain standards, requiring rapid portfolio pivot toward heat-stable recombinant platforms. Prioritize CDMO partnerships in Hyderabad to secure manufacturing scale for Gavi-eligible tenders.
For New Entrants and Emerging Players: Anchor in mucosal adjuvant technology licensing as the most penetrable entry vector, with European pharmacy networks and Southeast Asian pediatric outreach programs offering lowest competitive density. Target recombinant platform development for RSV indications where immunogenicity challenges have stalled incumbent progress. Pursue go-to-market strategies through ministry of health tender prequalification rather than hospital procurement committee engagement.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CDMO specialists possessing validated spray device compatibility testing infrastructure. Five-to-ten year viability hinges on regulatory convergence toward standardized mucosal efficacy correlates. Watch EMA-FDA alignment on IgA induction endpoints as the decisive inflection signal for portfolio revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks procurement eligibility across Gavi-eligible nations and validates thermostability claims. |
| CDMO Partnership Scale-Up | Addresses recombinant vector production bottlenecks concentrating in specialized Hyderabad facilities. |
| Spray Device Validation Investment | Secures formulation-device compatibility certification required by India's state vaccine depots. |
| Mucosal Adjuvant Licensing | Accelerates IgA induction correlate generation for FDA respiratory vaccine endpoint compliance. |
| Controlled Temperature Chain Certification | Enables ambient distribution through pharmacy networks in tropical climate zones. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, clinical trial registries, and procurement tender databases. Interviews with vaccine development executives, regulatory affairs leads at CDSCO and EMA, hospital procurement managers, and pharmacy network category buyers inform demand-side dynamics. Secondary validation draws from WHO prequalification listings, ClinicalTrials.gov mucosal vaccine protocols, and ministry of health tender documentation. Bottom-up dose-volume modeling triangulates against top-down market sizing across product type and delivery mode segments.
Segmentation dimensions modeled span product type, delivery mode, end user, and indication categories across the analysis window. Patient population stratification by age cohort and regional regulatory cluster by prequalification status further refine projections. CAGRs derive from dose-volume trajectories in national immunization programs and pharmacy network expansion rates, with stability data requirements under controlled temperature chain conditions and spray device regulatory validation timelines serving as key forecast inputs.
Underlying assumptions cover sustained WHO cold chain reduction mandates, CDSCO authorization continuity for nasal influenza products, and EMA centralized assessment pathway efficiency, with deviation risk concentrated in FDA mucosal immunogenicity guidance evolution and recombinant platform manufacturing scale bottlenecks. Practitioners should keep alternative scenarios live as regulatory convergence patterns on IgA induction correlates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
India Pharmaceutical Contract Sales Organizations Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
North America Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Drug Allergy Market
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Europe Laxative Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Pharmaceuticals Preservative Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Nicotine Replacement Product Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market