
 Alzheimer Disease Market | 2026-2036
Alzheimer Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Alzheimer Disease Market Intelligence
Biomarker-driven patient selection is rewriting how value migrates from broad symptomatic prescribing to precision-targeted therapy administration. Eli Lilly and Company leverages its manufacturing scale to secure supply chain priority for monoclonal antibody production. Biogen Inc. anchors the U.S. market through its established neurology infrastructure and payer relationships. Roche competes on diagnostic integration, pairing therapeutic development with companion amyloid imaging capabilities.
Alzheimer disease constitutes a progressive neurodegenerative disorder characterized by amyloid-beta plaque accumulation, tau protein tangles, and cholinergic neuron loss, with diagnosis increasingly dependent on cerebrospinal fluid biomarker analysis and PET imaging quantification. The condition demands therapies that modify underlying pathology rather than merely masking cognitive decline. Monoclonal antibodies represent the fastest-expanding product category as disease-modifying mechanisms displace legacy symptomatic agents. Hospitals capture the dominant share of end-user value given infusion center requirements for intravenous biologics, though home care channels are gaining traction where subcutaneous formulations permit administration outside clinical settings.
The FDA's accelerated approval framework shapes product entry timelines, while the EMA's benefit-risk assessments for amyloid therapies determine European market access conditions. Japan's PMDA has streamlined review pathways for geriatric neurodegenerative indications, accelerating regional availability. Stakeholders must monitor evolving CMS coverage determinations and HTA body evidentiary standards as these will determine which therapeutic modalities achieve sustainable reimbursement.
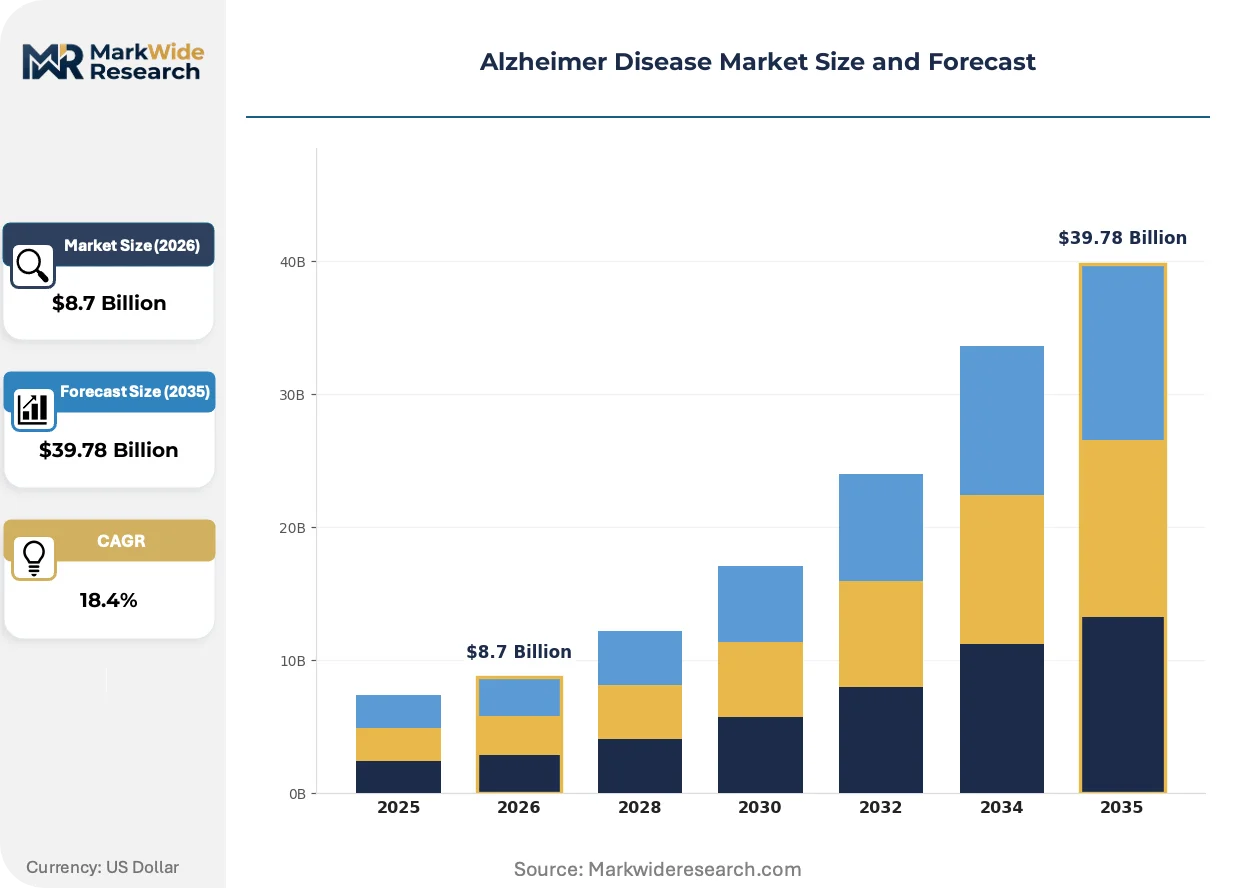
Market Dynamics
The FDA's accelerated approval pathway for amyloid-targeting monoclonal antibodies is compressing commercialization timelines while forcing reimbursement bodies to establish coverage frameworks for therapies with surrogate endpoints.
Growth Catalysts
- Biomarker-Guided Patient Selection:Cerebrospinal fluid analysis and amyloid PET imaging now enable precision-targeted therapy administration, expanding eligible patient pools for disease-modifying treatments.
- Japan's PMDA Streamlined Review:Accelerated regulatory pathways for geriatric neurodegenerative indications have compressed approval timelines, driving faster regional therapy availability.
- Specialty Neurology Clinic Expansion:Dedicated infusion centers for intravenous biologics are proliferating across the United States and Germany, building physical infrastructure for therapy delivery.
Market Restraints
- Reimbursement Uncertainty:CMS coverage determinations for accelerated-approval therapies with surrogate endpoints create payment volatility and access barriers for Medicare beneficiaries.
- Manufacturing Concentration:Monoclonal antibody production capacity clusters among a limited set of contract manufacturers, creating supply bottlenecks for high-volume biologic demand.
- Diagnostic Infrastructure Gaps:Amyloid PET imaging and lumbar puncture capabilities remain concentrated in academic medical centers, limiting patient identification in community settings.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered delivery mechanisms would unlock home care channels and reduce infusion center dependency, reshaping site-of-care economics.
- Companion Diagnostic Integration:Pairing therapeutic development with in-house amyloid imaging capabilities creates differentiated value propositions for payers seeking streamlined patient identification.
- Germany's HTA Pathway Adaptation:Early engagement with the G-BA on evidentiary requirements for disease-modifying therapies offers first-mover advantage in Europe's largest reimbursed market.
Industry Challenges
- Specialized Neurology Workforce Scarcity:Shortages of cognitive neurologists and infusion nurses constrain patient throughput at specialty clinics deploying intravenous biologics.
- Longitudinal Outcome Data Requirements:Confirmatory trials for accelerated-approval therapies demand multi-year follow-up, creating regulatory and financial exposure for developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alzheimer Disease Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cholinesterase Inhibitors, NMDA Receptor Antagonists, Monoclonal Antibodies, Combination Therapy End User: Hospitals, Home Care, Assisted Living Facilities, Clinical Research Centers Therapy Area: Symptomatic Treatment, Disease Modifying Treatment, Supportive Care, Cognitive Enhancement Delivery Mode: Oral, Intravenous, Transdermal, Intranasal |
| Companies Covered | Eisai Co., Ltd., Eli Lilly and Company, Biogen Inc., AbbVie Inc., Johnson & Johnson, Novartis AG, Roche, AstraZeneca, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alzheimer Disease Market Strategic Shifts & Innovations
Disease-modifying mechanisms are displacing legacy symptomatic agents across prescriber preference hierarchies, while diagnostic technologies and delivery formats undergo simultaneous transformation.
Blood-based biomarker assays for amyloid-beta and phosphorylated tau are collapsing the patient identification workflow. Primary care physicians and memory clinics are adopting these platforms to triage patients before specialist referral. The technology is compressing time-to-diagnosis from months to weeks, expanding the addressable screening population beyond specialist-accessible cohorts.
EMA's benefit-risk reassessment framework for amyloid-targeting therapies is tightening evidentiary standards for full marketing authorization. Developers must now generate confirmatory clinical outcome data within compressed timelines to maintain market access. European neurology practices are responding by delaying widespread adoption until traditional approval pathways conclude.
Hospital-based infusion centers face channel disintermediation as subcutaneous formulations permit administration in alternate settings. Home health agencies and specialty pharmacy networks are capturing patient volumes previously concentrated in academic medical centers. The United States exhibits the most pronounced shift, driven by Medicare Advantage plans seeking site-of-care cost differentials.
Alzheimer Disease Market Segmentation
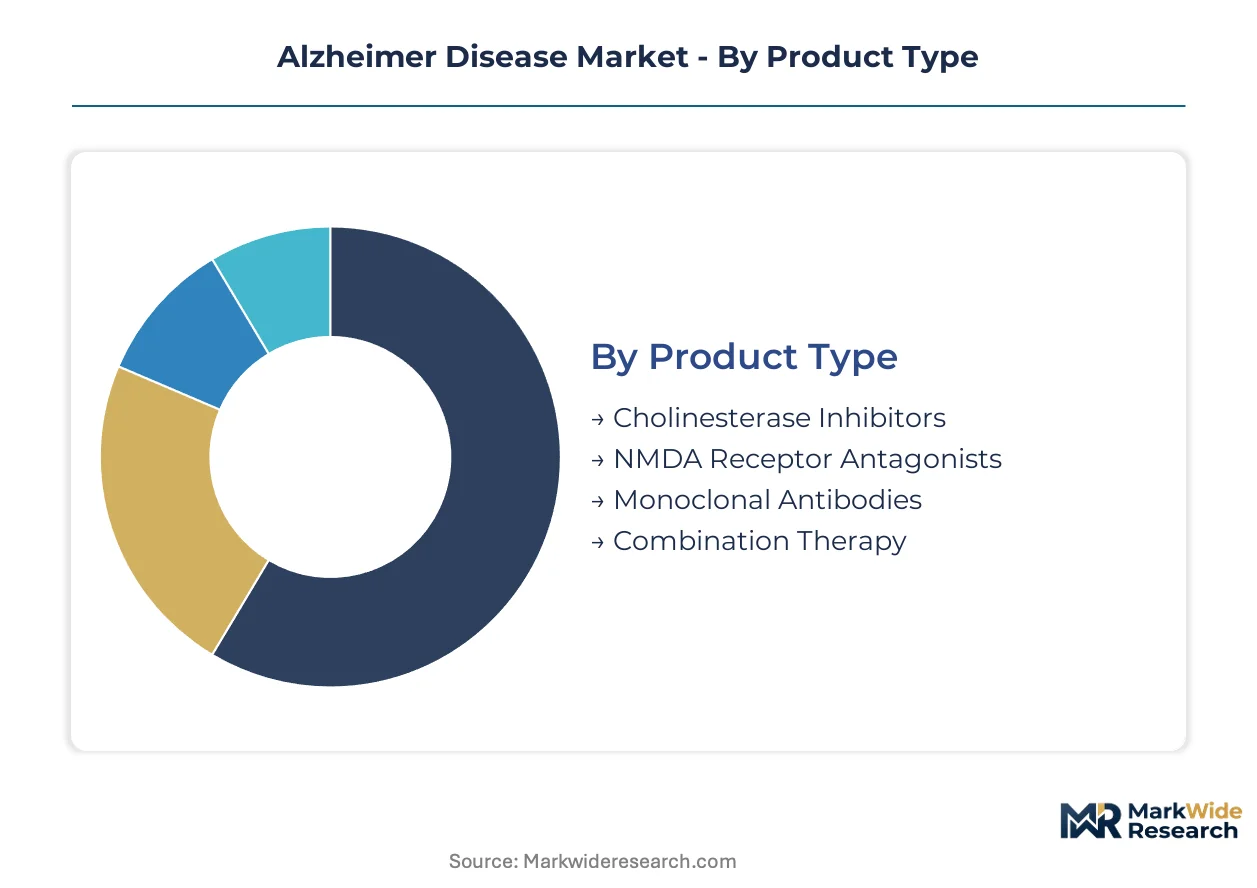
Segmentation in the Alzheimer disease market reveals how therapeutic innovation, site-of-care economics, and diagnostic infrastructure reshape value distribution. Understanding these dimensions exposes where capital deploys and which patient populations unlock commercial viability.
Product Type:
Cost tier stratification separates legacy symptomatic agents from premium biologics, with manufacturing complexity and reimbursement intensity driving portfolio positioning.
- Monoclonal Antibodies:Engineered immunoglobulins targeting amyloid-beta aggregates require cold-chain distribution and infusion center administration. Demand concentrates in the United States and Germany where CMS and G-BA have established coverage frameworks for disease-modifying therapies despite surrogate endpoint dependencies.
- Cholinesterase Inhibitors:Small-molecule agents including donepezil and rivastigmine inhibit acetylcholinesterase to modestly slow cognitive decline. Volume persists in Japan and primary care settings where diagnostic infrastructure for biomarker-guided therapy remains underdeveloped.
- NMDA Receptor Antagonists:Memantine-class compounds modulate glutamatergic neurotransmission in moderate-to-severe disease stages.
- Combination Therapy:Stacked regimens pairing cholinesterase inhibitors with memantine address mixed-pathology patient profiles.
Cholinesterase inhibitors command the established base. The steepest expansion runs through monoclonal antibodies.
End User:
Site-of-care economics determine channel profitability, with infusion infrastructure requirements and reimbursement differentials shifting patient volume between institutional and community settings.
- Hospitals:Academic medical centers and specialty neurology clinics house PET imaging suites, lumbar puncture capabilities, and infusion centers for intravenous biologics. The United States captures dominant value as Medicare Advantage plans negotiate site-of-care rates and hospital systems invest in amyloid confirmation workflows.
- Home Care:Subcutaneous formulation development enables administration outside clinical settings, reducing caregiver burden and facility overhead. Germany exhibits early traction where statutory health insurance reimbursement covers home nursing for biologic delivery.
- Assisted Living Facilities:Memory care units in residential settings manage behavioral symptoms and medication adherence for mild-to-moderate patients.
- Clinical Research Centers:Academic trial sites recruit biomarker-confirmed cohorts for disease-modifying therapy development.
Hospitals retain the volume anchor. The steepest expansion trajectory belongs to home care channels.
Therapy Area:
Clinical intent separates palliative management from pathology-intervention approaches, with regulatory pathways and evidentiary standards determining commercial access.
- Disease Modifying Treatment:Amyloid-targeting and tau-directed mechanisms aim to slow or halt neurodegenerative progression rather than mask symptoms. Japan's PMDA streamlined review pathway accelerates availability for geriatric indications, compressing timelines versus traditional EMA benefit-risk assessments.
- Symptomatic Treatment:Cognitive and functional symptom management remains the accessible standard where biomarker confirmation or infusion infrastructure is unavailable.
- Supportive Care:Behavioral and psychiatric symptom management addresses agitation, depression, and sleep disruption in later disease stages.
- Cognitive Enhancement:Adjunctive therapies targeting attention, executive function, and processing speed complement core disease management.
Symptomatic treatment holds the installed base. Disease modifying treatment is climbing the fastest.
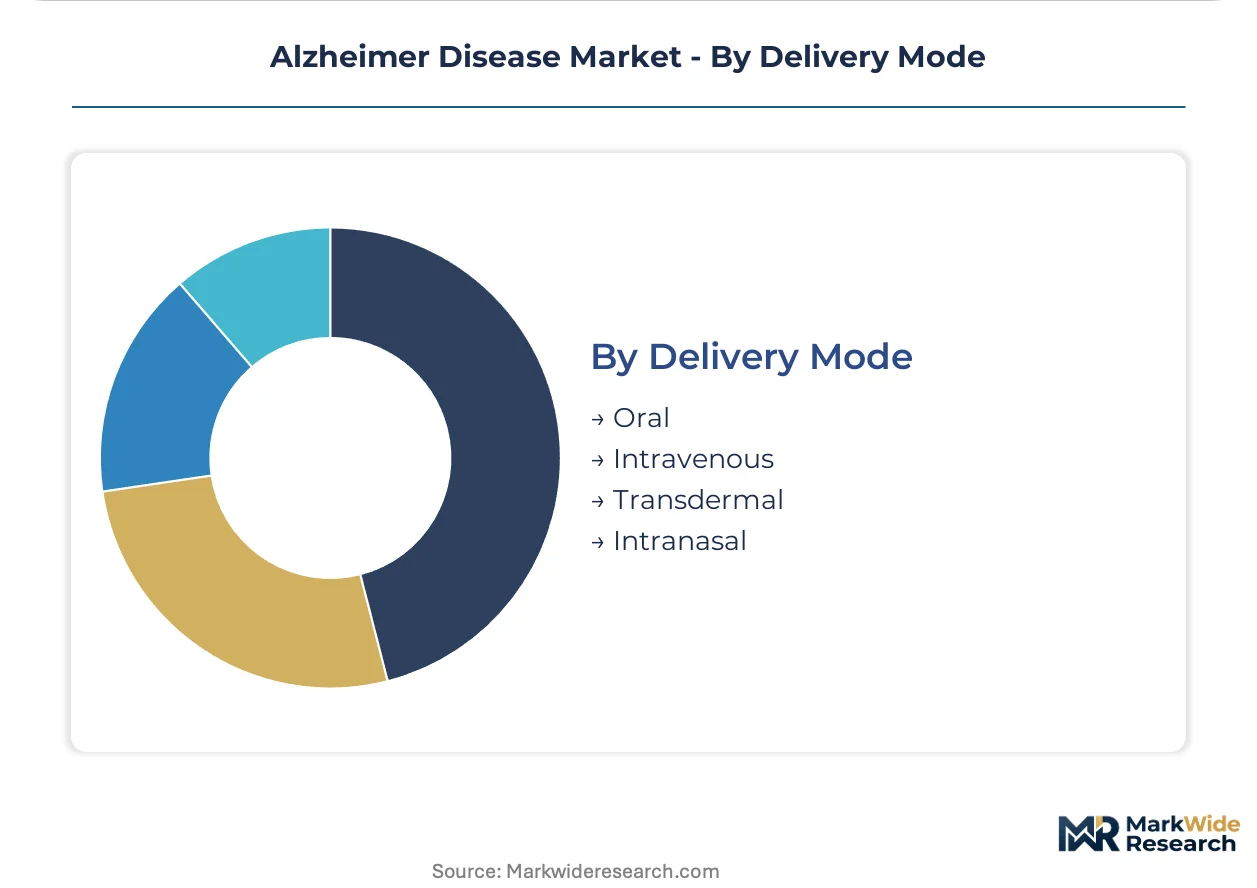
Delivery Mode:
Administration route dictates site-of-care requirements, patient adherence profiles, and manufacturing investment priorities across formulation technologies.
- Intravenous:Infusion-dependent biologics require healthcare professional administration and monitoring for amyloid-related imaging abnormalities. The United States concentrates capacity in hospital outpatient departments and standalone infusion centers.
- Oral:Small-molecule tablets and capsules enable self-administration and broad pharmacy distribution without specialist infrastructure.
- Transdermal:Patch formulations of cholinesterase inhibitors improve compliance in patients with swallowing difficulties or dosing inconsistency.
- Intranasal:Nasal spray delivery mechanisms under investigation aim to bypass blood-brain barrier limitations for biologic payloads.
Oral delivery commands the established base. Intravenous administration shows the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between reimbursement-heavy markets where disease-modifying biologics penetrate and diagnostic-limited regions where symptomatic agents dominate. The United States, Japan, and Germany concentrate infusion infrastructure and amyloid confirmation workflows, while emerging markets rely on oral cholinesterase inhibitors due to PET imaging scarcity.
United States
Medicare Advantage plans drive site-of-care economics toward hospital outpatient departments and standalone infusion centers. FDA accelerated approval pathways compress commercialization timelines for amyloid-targeting monoclonal antibodies. The Greater Boston corridor anchors clinical trial recruitment and biomarker research concentration.
Japan
Aging demographics expand the addressable patient pool faster than any developed market. PMDA streamlined review pathways for geriatric neurodegenerative indications compress regulatory timelines versus traditional EMA assessments. Tokyo and Osaka metropolitan areas concentrate specialty neurology clinics and PET imaging suites.
Germany
Statutory health insurance reimbursement frameworks cover home nursing for biologic delivery, enabling early home care channel traction. G-BA benefit assessments for disease-modifying therapies determine evidentiary standards for European market access. North Rhine-Westphalia houses the densest concentration of memory clinics and lumbar puncture capabilities.
United Kingdom
NICE technology appraisals create reimbursement gatekeeping for premium biologics despite FDA approvals. NHS England diagnostic capacity constraints limit amyloid PET imaging to specialist tertiary centers. The Cambridge-Oxford-London triangle concentrates academic research and early-phase clinical development.
Switzerland
Swissmedic benefit-risk assessments align closely with EMA standards but permit faster national implementation post-CHMP opinion. Private insurance dominance enables earlier access to disease-modifying therapies than neighboring EU markets. Basel and Zurich anchor pharmaceutical R&D clustering and neurology specialist concentration.
Alzheimer Disease Market Key Industry Players
Capability concentration sits with large-cap biopharmaceuticals possessing integrated diagnostic-therapeutic platforms; scale advantage sits with mid-cap neurology specialists with established payer relationships and infusion infrastructure. The market structures around three tiers: vertically integrated giants with manufacturing scale, neurology-focused midsize players with site-of-care control, and emerging biotechs with novel tau-directed mechanisms. Consolidation pressures intensify as confirmatory trial costs and manufacturing capacity requirements escalate. Dominant competitive moves include companion diagnostic pairing and subcutaneous formulation development to unlock home administration channels.
Within the integrated diagnostic-therapeutic tier, Roche exemplifies pairing therapeutic development with in-house amyloid imaging capabilities. Eli Lilly and Company anchors the manufacturing scale vector with monoclonal antibody production priority. Among neurology-established players, Biogen Inc. occupies a position reflecting deep payer relationships and U.S. market infrastructure concentration.
| Leading Market Players |
|---|
| Eisai Co., Ltd. |
| Eli Lilly and Company |
| Biogen Inc. |
| AbbVie Inc. |
| Johnson & Johnson |
| Novartis AG |
| Roche |
| AstraZeneca |
| Bristol-Myers Squibb |
| Others |
Cost & Logistics Intelligence
Undercapacity in monoclonal antibody production across North American contract manufacturing facilities drives both supplier prioritization behavior and premium pricing posture for disease-modifying therapies, as biopharmaceutical developers compete for limited bioreactor slots to secure commercial supply.
Pricing Analysis
Long-term offtake agreements dominate pricing structures for monoclonal antibodies, with manufacturers locking in multi-year commitments to secure manufacturing capacity amid supply constraints. Pricing stratifies across premium, standard, and economy tiers based on infusion center site-of-care economics and biomarker confirmation requirements. Cost compression in the cholinesterase inhibitor segment is intensifying due to generic erosion and formulary preference shifts toward disease-modifying alternatives. Medicare Advantage plans exhibit the highest price sensitivity, while private payers in Switzerland demonstrate greater tolerance for premium biologic pricing.
Supply Chain Analysis
Tariff exposure between the United States and Chinese suppliers of single-use bioreactor components dominates supply chain risk assessments for monoclonal antibody producers. Manufacturing capacity concentrates in the United States, Ireland, and Singapore, with fill-finish operations drawing from specialized cold-chain logistics networks. Raw material dependencies span recombinant cell lines, chromatography resins, and sterile filtration assemblies. Single-source vulnerability for amyloid-beta assay kits constrains diagnostic supply security. Distribution runs through hospital outpatient departments and specialty pharmacy networks with temperature-controlled validation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's accelerated approval pathway for amyloid-targeting therapies has compressed commercialization timelines, creating a high-growth disruption where first-mover manufacturing scale and diagnostic integration determine sustainable market access.
For Market Incumbents: Harden manufacturing scale advantages through captive bioreactor capacity additions in the United States and Ireland, insulating against contract manufacturer bottlenecks. Secure companion diagnostic partnerships to lock in patient identification workflows before tau-directed competitors emerge. Prioritize formulary director relationships to defend hospital outpatient department channel control against subcutaneous formulation disruptors.
For New Entrants and Emerging Players: Build out blood-based biomarker platforms to capture primary care triage volumes before specialist referral, addressing the diagnostic infrastructure gap in community settings. Target Germany's statutory health insurance reimbursement pathway for home nursing coverage, the most penetrable European market for subcutaneous delivery. Pursue licensing agreements with established neurology-focused midsize players to accelerate payer relationship development.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across confirmatory trial execution and manufacturing scale-up, favoring platforms with existing FDA breakthrough therapy designations. Five-to-ten year viability hinges on longitudinal outcome data generation and CMS coverage determination navigation. Acquisition target archetypes include tau-directed mechanism biotechs with validated biomarker strategies. Monitor EMA benefit-risk reassessment timing as the critical inflection signal for European market access durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Pairs therapeutic development with amyloid imaging capabilities, streamlining payer patient identification workflows. |
| Subcutaneous Formulation Development | Unlocks home care channels and reduces infusion center dependency, reshaping site-of-care economics. |
| Manufacturing Scale-Up | Secures bioreactor priority amid contract manufacturer concentration, ensuring commercial supply security. |
| Regulatory Approval Pathway | Leverages FDA accelerated approval and PMDA streamlined review to compress commercialization timelines. |
| Reimbursement Strategy | Engages CMS and G-BA early to establish coverage frameworks for surrogate endpoint-dependent therapies. |
Research Approach
The analysis maps disease-modifying therapy development, symptomatic agent positioning, diagnostic infrastructure deployment, and site-of-care channel economics, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interview insights triangulate against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare coverage determinations. Bottom-up patient flow modeling and top-down revenue reconciliation ensure cross-validation integrity.
Assumptions held fixed include regulatory pathway timelines for accelerated approval conversions and CMS coverage determination frameworks, while variables span biomarker adoption rates and subcutaneous formulation penetration. The projection horizon segments by product type, end user channel, therapy area intent, and delivery mode, with CAGRs derived from epidemiological progression modeling and pricing elasticity assessments across reimbursement clusters. Forecast inputs incorporate infusion center capacity expansion rates and blood-based diagnostic assay validation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive manufacturing scale investments by emerging biotechs or sudden EMA benefit-risk reassessment shifts would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Dystrophic Epidermolysis Bullosa Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Parry-Romberg Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Gaucher Disease Drugs Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
Byler Disease Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Methylmalonic Acidemia Market