
 Injectable Targeted Therapy Market | 2026-2036
Injectable Targeted Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Targeted Therapy Market Foresight
Prefilled syringe and autoinjector bundling with biologic drug kits is consolidating buyer choice around ready-to-administer formats. F. Hoffmann-La Roche Ltd. leverages its diagnostic-pharmaceutical integration to anchor companion testing workflows. Pfizer Inc. sustains manufacturing scale across multiple monoclonal antibody platforms. Novartis AG differentiates through radioligand therapy infrastructure that controls dose preparation and delivery.
Injectable targeted therapies are parenterally administered biologics or small molecules engineered to bind specific cellular markers, typically requiring cold-chain storage at 2–8°C and sterile compounding under ISO 5 conditions prior to patient administration; their commercial purpose is to maximize therapeutic index by concentrating drug activity at disease sites while sparing healthy tissue. Monoclonal antibodies occupy the largest value pool due to established reimbursement and biosimilar competition compressing prices. Antibody-drug conjugates represent the fastest-expanding product type, driven by linker-payload innovations that improve therapeutic windows. Subcutaneous delivery is displacing intravenous infusion in indications where volume and viscosity constraints permit, reducing hospital capacity requirements and shifting administration toward ambulatory settings.
FDA biologics license application requirements, EMA good manufacturing practice standards for sterile products, and ISO 11608 needle-based injection system specifications collectively govern device-drug combination approvals and cross-border market access. These frameworks elevate compliance costs for new entrants while rewarding manufacturers with validated quality management systems. Stakeholders must monitor evolving pharmacovigilance obligations for novel modalities and assess whether manufacturing footprints can adapt to regional serialization and track-and-trace mandates.
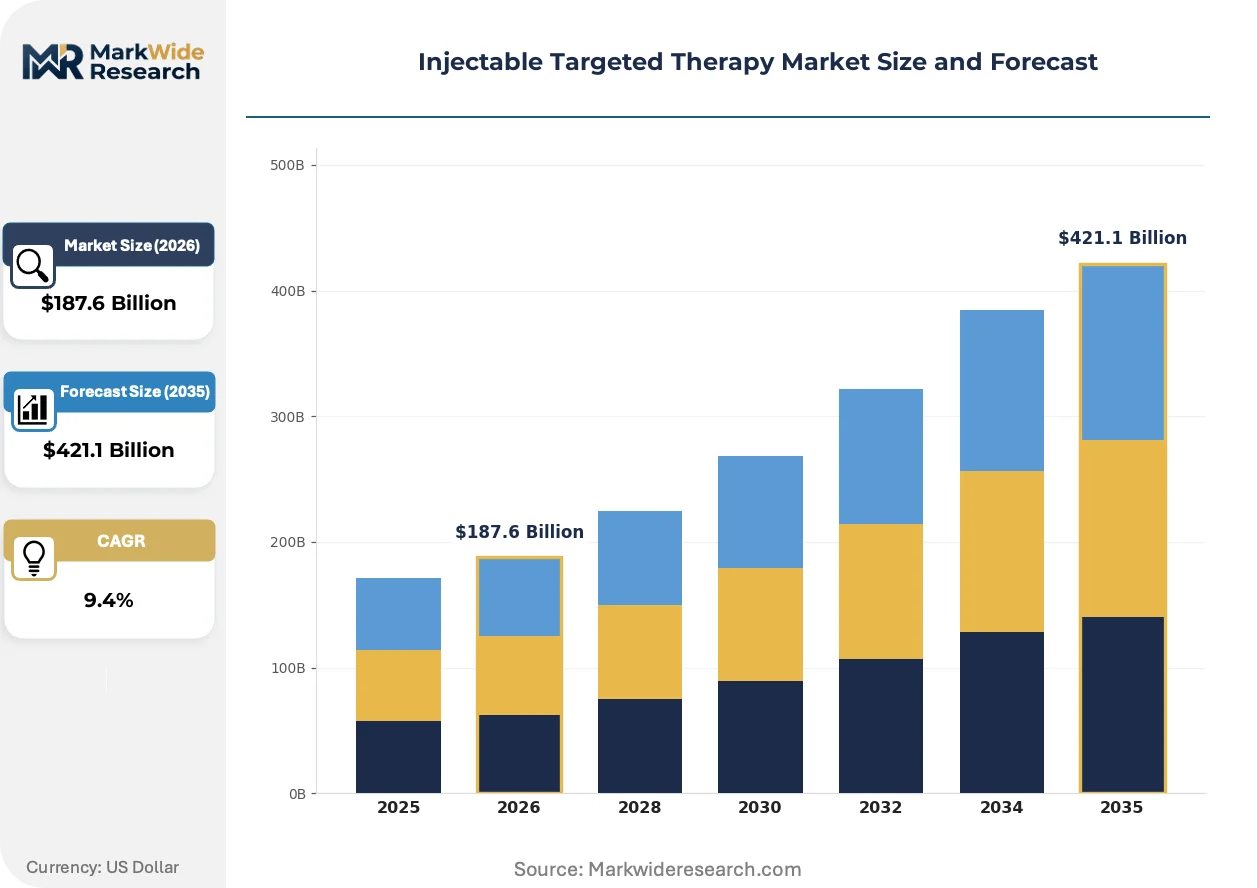
Market Dynamics
Subcutaneous delivery formats are compressing hospital capacity requirements and shifting administration toward ambulatory settings, fundamentally restructuring site-of-care economics for biologic administration.
Growth Catalysts
- FDA Accelerated Approval:Compressed development timelines for biologics are enabling faster patient access to novel antibody-drug conjugates. Oncology clinics in the United States are expanding adoption of subcutaneous formats under this pathway.
- Germany's Hospital Networks:Centralized pharmacy compounding infrastructure supports complex antibody-drug conjugate administration, creating demand concentration in integrated delivery systems.
- Linker-Payload Innovation:Advances in conjugation chemistry are improving therapeutic windows for antibody-drug conjugates, expanding addressable patient populations.
Market Restraints
- Cold-Chain Dependency:Biologics requiring 2–8°C storage create distribution cost premiums and limit reach to regions with validated logistics infrastructure.
- EMA GMP Compliance:Sterile product manufacturing standards elevate capital requirements for new entrants, consolidating production among validated quality management systems.
- Biosimilar Price Compression:Monoclonal antibody value pools face margin pressure as follow-on biologics enter therapeutic categories with established reimbursement.
Strategic Opportunities
- Ready-to-Administer Kits:Prefilled syringe and autoinjector bundling with biologic drugs is consolidating buyer choice around formats that reduce preparation time and error risk.
- Radioligand Infrastructure:Controlled dose preparation and delivery networks for radiopharmaceuticals create captive value chains that competitors cannot easily replicate.
- Companion Diagnostic Integration:Diagnostic-pharmaceutical workflow anchoring enables patient stratification that improves payer value demonstration and formulary positioning.
Industry Challenges
- ISO 11608 Validation:Needle-based injection system specifications for device-drug combinations extend development timelines and require specialized engineering capabilities.
- Pharmacovigilance Scaling:Novel modalities demand expanded adverse event monitoring infrastructure that strains regulatory affairs functions.
- Serialization Adaptation:Regional track-and-trace mandates require manufacturing footprint adjustments that complicate supply network design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Targeted Therapy Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $421.1 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecule Inhibitors, Antibody-Drug Conjugates, Cytokine Therapies Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Intra-arterial End User: Hospitals, Oncology Clinics, Ambulatory Surgical Centers, Research Laboratories Application: Oncology, Autoimmune Disorders, Infectious Diseases, Rare Diseases |
| Companies Covered | Johnson & Johnson Services Inc., F. Hoffmann-La Roche Ltd., Pfizer Inc., Novartis AG, Merck & Co. Inc., AbbVie Inc., AstraZeneca plc, Bristol-Myers Squibb Company, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Targeted Therapy Market Shifts & Advancements
Delivery technology convergence and regulatory pathway evolution are compressing development-to-commercialization timelines while redistributing economic value across the administration value chain.
Subcutaneous formulation technology is expanding into indications previously restricted to intravenous infusion. Hospital outpatient departments in the United States are adopting high-concentration antibody formulations that enable 5–10 mL subcutaneous administration. This shift is reducing chair time requirements and enabling home-based administration for select therapies.
The FDA's accelerated approval pathways for biologics are reshaping evidence generation requirements. Confirmatory trial obligations now follow conditional market entry, compressing time-to-revenue but increasing post-marketing surveillance burden. Antibody-drug conjugate developers are responding with adaptive trial designs that integrate real-world evidence collection.
Buyer concentration in Germany's hospital networks is consolidating procurement decisions around integrated drug-device offerings. Centralized pharmacy committees now evaluate total cost of administration rather than drug acquisition cost alone. This behavioral shift favors suppliers with compounding support infrastructure and training capabilities.
Injectable Targeted Therapy Market Segmentation
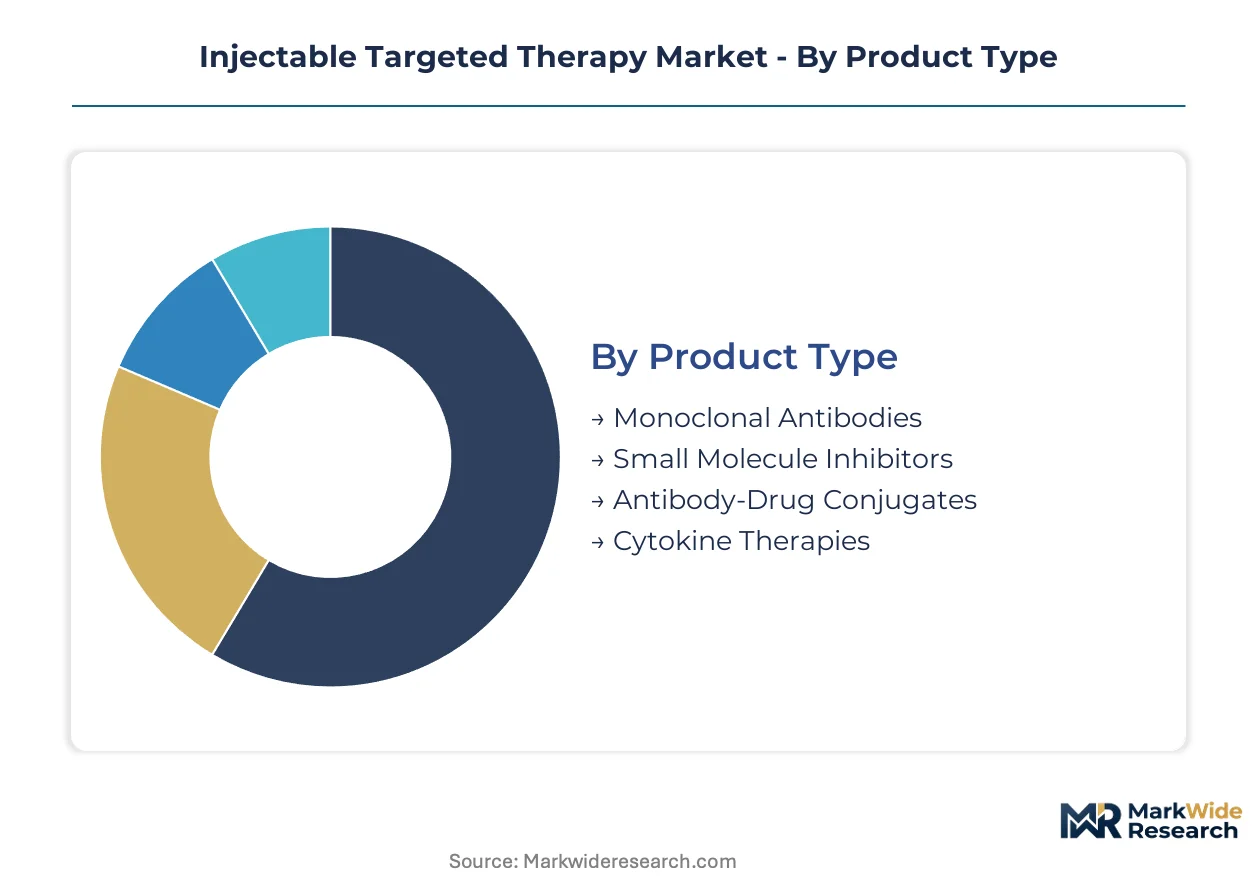
Segmentation in the Injectable Targeted Therapy Market reveals how formulation complexity, administration setting, and disease specificity create distinct commercial ecosystems with divergent margin profiles and regulatory pathways.
Product Type:
Standardization dominates monoclonal antibody manufacturing while antibody-drug conjugates demand bespoke linker-payload engineering that fragments production scale.
- Monoclonal Antibodies:These recombinant proteins bind specific antigens with high affinity, manufactured through mammalian cell culture at multi-ton bioreactor scale. Demand concentrates in United States oncology clinics where biosimilar entry has compressed pricing and consolidated procurement around validated suppliers with cold-chain reliability.
- Antibody-Drug Conjugates:Cytotoxic payloads attached via cleavable or non-cleavable linkers to monoclonal antibody backbones, requiring aseptic conjugation under ISO 5 conditions. Germany's hospital networks anchor demand through centralized pharmacy compounding infrastructure that manages complex reconstitution workflows and patient-specific dosing.
- Small Molecule Inhibitors:Synthetic compounds targeting intracellular signaling pathways, solubilized for parenteral delivery through formulation technologies.
- Cytokine Therapines:Recombinant interleukins and interferons engineered for half-life extension via PEGylation or fusion proteins.
Leading the category by volume: Monoclonal Antibodies. Expanding most quickly: Antibody-Drug Conjugates.
Delivery Mode:
Volume and viscosity constraints separate hospital-bound infusion from ambulatory-ready injection formats.
- Intravenous:Large-volume antibody formulations administered through infusion centers with chair time requirements of 30–120 minutes. United States hospital outpatient departments retain dominance for high-dose oncology indications where subcutaneous bioequivalence remains unproven.
- Subcutaneous:High-concentration formulations enabling 5–10 mL administration via prefilled syringe or autoinjector, displacing intravenous routes where pharmacokinetic equivalence is established. Oncology clinics across Germany and the United States are adopting this format to reduce capacity constraints and shift administration toward home settings.
- Intramuscular:Depot formulations designed for sustained release through muscle tissue deposition.
- Intra-arterial:Regional delivery to specific vascular beds, limited to specialized interventional radiology procedures.
Intravenous retains revenue leadership. Subcutaneous formats are climbing the fastest as formulation technology expands addressable indications.
End User:
Capital intensity and reimbursement sophistication stratify access across institutional settings.
- Hospitals:Integrated health systems with centralized pharmacy infrastructure, 340B purchasing eligibility, and capacity for complex biologic handling. United States academic medical centers anchor demand for antibody-drug conjugates requiring specialized compounding.
- Oncology Clinics:Community-based infusion centers optimizing chair utilization through subcutaneous adoption and same-day scheduling. These facilities concentrate demand in Germany's networked hospital systems and United States metropolitan corridors.
- Ambulatory Surgical Centers:Procedure-specific settings with limited biologic administration scope.
- Research Laboratories:Preclinical and clinical trial sites driving pipeline demand for novel modalities.
Hospitals lead by installed base. Oncology clinics are gaining share fastest through site-of-care migration.
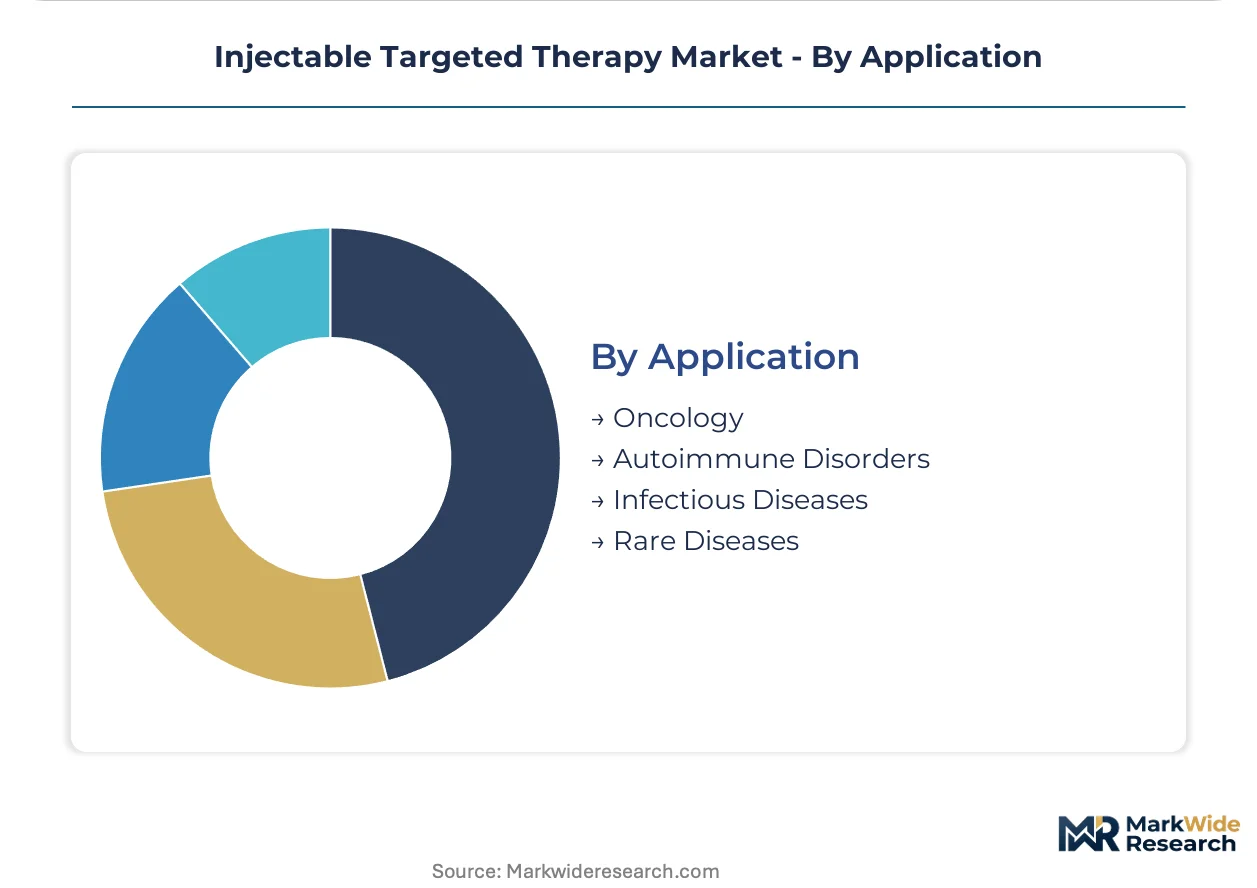
Application:
Disease biology and unmet medical need determine pricing power and development priority.
- Oncology:Solid and hematologic malignancies with validated tumor-associated antigen targets, representing the dominant value pool through checkpoint inhibitors and antibody-drug conjugates. FDA accelerated approval pathways compress development timelines for this indication.
- Autoimmune Disorders:Rheumatoid arthritis, psoriasis, and inflammatory bowel disease with established cytokine and B-cell targeting mechanisms. Demand concentrates in ambulatory settings where subcutaneous self-administration improves adherence.
- Infectious Diseases:Monoclonal antibodies against viral and bacterial pathogens, including emerging pandemic countermeasures.
- Rare Diseases:Ultra-orphan indications with small patient populations and premium pricing justified by clinical value demonstration.
Oncology leads by revenue concentration. Autoimmune Disorders follow with the steepest expansion trajectory through biosimilar-enabled access expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Switzerland and Germany while consumption concentrates in United States oncology networks and German hospital systems, creating transatlantic supply-demand asymmetries that shape cold-chain logistics investment.
United States
FDA accelerated approval pathways compress biologics development timelines while oncology clinics expand subcutaneous adoption. The 340B drug pricing program shapes hospital procurement economics for antibody-drug conjugates. Greater Boston anchors biotech manufacturing with specialized sterile fill-finish capacity serving national distribution networks.
Germany
Centralized pharmacy compounding infrastructure in hospital networks supports complex biologic administration workflows. EMA good manufacturing practice standards for sterile products elevate compliance requirements for production facilities. The Rhine-Ruhr and Bavarian clusters concentrate dose preparation expertise for radioligand therapy networks.
Switzerland
Diagnostic-pharmaceutical integration capabilities concentrate in Basel-region headquarters operations. Swissmedic regulatory frameworks support early-access programs for novel modalities. The Zurich-Geneva corridor hosts specialized cold-chain logistics providers serving European distribution.
Japan
PMDA consultation pathways for biologics enable synchronized development with FDA and EMA submissions. Pricing and reimbursement negotiations through Chuikyo shape market access timelines for monoclonal antibodies. The Kanto region concentrates clinical trial infrastructure for oncology indications.
United Kingdom
MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for innovative medicines. NHS England specialized commissioning frameworks concentrate demand for high-cost targeted therapies. The Golden Triangle research clusters support early-phase clinical development for antibody-drug conjugates.
Injectable Targeted Therapy Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the injectable targeted therapy landscape, creating tiered competitive dynamics where scale advantages clash with modality-specific expertise. Market structure shows consolidation among validated quality management systems capable of ISO 5 sterile manufacturing. Three archetypes dominate: integrated diagnostic-pharmaceutical platforms, standalone biologics manufacturers with multi-product scale, and radiopharmaceutical specialists controlling captive dose preparation networks. Dominant competitive moves include M&A to secure linker-payload technologies and capacity expansion into subcutaneous formulation capabilities.
Within the integrated platform tier, F. Hoffmann-La Roche Ltd. and Novartis AG exemplify diagnostic-anchored commercial strategies, while Pfizer Inc. occupies a position representing manufacturing scale across multiple monoclonal antibody platforms. These three entities anchor the competitive landscape through distinct value chain control points rather than direct product overlap.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Novartis AG |
| Merck & Co. Inc. |
| AbbVie Inc. |
| AstraZeneca plc |
| Bristol-Myers Squibb Company |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Cold-chain sustainability mandates from the FDA and EMA gate qualified supply access and premium-tier pricing for injectable targeted therapies, as manufacturers must validate carbon-neutral logistics to serve hospital networks and oncology clinics demanding green procurement credentials.
Pricing Analysis
Margin tightening in monoclonal antibodies reflects biosimilar entry compressing reimbursement rates across United States oncology clinics. Three-tier pricing structure across premium, standard, and economy levels separates originator biologics from biosimilars and follow-on entrants, with price differentiation hinging on cold-chain reliability certification and companion diagnostic bundling. Cost-down pressure on antibody-drug conjugates accelerates because linker-payload innovation cycles demand specialized manufacturing investment. Hospital procurement committees show highest price sensitivity, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Bioreactor capacity rests on Swiss and German specialty manufacturing infrastructure, with mammalian cell culture media and single-use bioprocessing systems drawing from United States and Japanese suppliers. Aseptic fill-finish operations hinge on isolator technology and sterile filtration components sourced from specialized European vendors. Single-source vulnerability concentrates in lipid nanoparticle excipients for emerging modalities. Distribution runs through validated cold-chain logistics providers serving hospital networks and centralized pharmacy compounding facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injectable targeted therapy markets reward vertical-integration races where control over sterile manufacturing and diagnostic anchoring determines margin capture across the administration value chain.
For Market Incumbents: Hedge against biosimilar displacement by securing proprietary linker-payload platforms and expanding subcutaneous formulation capacity in Germany's hospital network corridors. ISO 5 sterile manufacturing certification investments defend against EMA compliance escalation. Companion diagnostic workflow integration locks in formulary positioning against emerging biologics specialists. For New Entrants and Emerging Players: Oncology clinic channel partners offer the most penetrable entry vector for subcutaneous delivery formats displacing intravenous infusion. White-space concentrates in radioligand therapy dose preparation networks where captive infrastructure creates defensible moats. Go-to-market positioning should target ambulatory administration settings with ready-to-administer kit bundling. For Investors and Strategic Acquirers: FDA accelerated approval pathway expansion for antibody-drug conjugates is the leading indicator that manufacturing capacity scarcity will drive consolidation premiums. Long-term viability favors vertically integrated platforms with diagnostic-pharmaceutical convergence capabilities. Acquisition target archetypes include sterile fill-finish specialists and linker-payload engineering boutiques. Watch subcutaneous bioequivalence study readouts as inflection signals for site-of-care migration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Scale-Up | Reduces hospital chair time and shifts administration toward home settings in United States oncology networks. |
| Companion Diagnostic Integration | Anchors patient stratification workflows that improve payer value demonstration and formulary positioning. |
| Radioligand Infrastructure Buildout | Creates captive dose preparation networks controlling preparation, delivery, and administration in Germany. |
| Linker-Payload Technology Licensing | Secures proprietary conjugation chemistry improving therapeutic windows for antibody-drug conjugates. |
| Cold-Chain Sustainability Certification | Validates carbon-neutral logistics meeting EMA green procurement mandates for hospital network access. |
Research Methodology
Document review covered FDA biologics license applications, EMA good manufacturing practice guidance, ClinicalTrials.gov protocol databases, and hospital procurement records, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and centralized pharmacy managers. Secondary validation drew from ISO 11608 device specifications, SEC 10-K pharmaceutical filings, and formulary database audits. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market size estimation.
Market outputs reflect segment-level modeling across product type, delivery mode, end user, and application dimensions throughout the forecast period. CAGRs were derived from patent expiry timelines, biosimilar entry assumptions, and subcutaneous adoption curve projections. Treatment line positioning and regional regulatory cluster differentiation shaped forecast trajectories for antibody-drug conjugates and monoclonal antibodies.
Caveats apply where FDA accelerated approval confirmatory trial failures, EMA pharmacovigilance enforcement actions, or cold-chain logistics disruptions could materially shift the outlook. Forecasts embed assumptions around reimbursement stability and biosimilar substitution rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Cervical Cancer Drugs Market
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Multiple Myeloma Drugs Market
Pharmaceuticals
Isotretinoin Drugs Market
Pharmaceuticals
Inotropic Agent Market
Pharmaceuticals
Pharmaceuticals Serialization Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Calcitriol Capsules Market
Pharmaceuticals
Anti-Radiation Drugs Market