
 Global Anesthesia Drugs Market | 2026-2036
Global Anesthesia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anesthesia Drugs Market Foresight
Asset-light leasing models for anesthesia delivery equipment is fragmenting competitive dynamics across the value chain. Fresenius SE & Co. KGaA leverages its integrated care networks to sustain high utilization rates for inhaled agents. Baxter International Inc. anchors its position through captive supply of propofol and premixed intravenous solutions. Pfizer Inc. differentiates via specialized manufacturing scale in ultra-short-acting hypnotics.
Anesthesia drugs comprise pharmacological agents that induce reversible loss of sensation or consciousness, with propofol being an alkyl phenol derivative formulated as a 1% oil-in-water emulsion for intravenous induction and maintenance of general anesthesia. These agents serve surgical, diagnostic, and pain management applications by depressing central nervous system activity to targeted depths measured via bispectral index monitoring. Intravenous agents command substantial margin pools due to hospital preference for controllable titration and rapid emergence profiles. Local anesthetics such as ropivacaine and lidocaine represent the fastest-expanding product category, propelled by ambulatory surgical center expansion and ultrasound-guided regional blocks. Inhalational agents maintain entrenched positions in cardiac and pediatric cases where volatile pharmacokinetics enable precise depth adjustment.
The FDA governs new drug applications and manufacturing standards under 21 CFR, while the EMA enforces the EU MDR for device-drug combination products such as target-controlled infusion pumps. ISO 13485 certification requirements for quality management systems shape supplier qualification and procurement decisions across hospital networks. Stakeholders must monitor evolving pharmacovigilance mandates and biosimilar entry timelines to calibrate portfolio and pricing strategies.
Market Dynamics
Asset-light leasing models for anesthesia delivery equipment are fragmenting competitive dynamics across the value chain, forcing incumbent pharmaceutical suppliers to defend margin pools through captive formulation supply and integrated service contracts rather than device ownership.
Growth Catalysts
- EU MDR compliance deadlines:Stricter device-drug combination standards under the EU MDR are accelerating hospital replacement cycles for aging infusion pumps and vaporizers, pulling through attached pharmaceutical consumption.
- Ambulatory surgical center expansion:The United States, China, and Germany are witnessing rapid facility construction for outpatient procedures, expanding addressable surgical volumes beyond traditional hospital settings.
- Ultrasound-guided regional anesthesia:Enhanced visualization techniques are expanding ropivacaine and lidocaine utilization for nerve blocks, displacing general anesthesia in orthopedic and obstetric cases.
Market Restraints
- Propofol supply concentration:Manufacturing of the 1% oil-in-water emulsion depends on a limited base of sterile formulation facilities, creating vulnerability to single-site production disruptions.
- API sourcing from China and India:Active pharmaceutical ingredient production for alkyl phenol derivatives and amide local anesthetics concentrates in Asian manufacturing clusters, exposing formulators to geopolitical trade friction.
- Inhalational agent environmental restrictions:The EU F-Gas Regulation and analogous state-level mandates in California are constraining desflurane and sevoflurane utilization due to greenhouse gas potency concerns.
Strategic Opportunities
- Prefilled syringe standardization:The FDA's 21 CFR sterility guidelines and EU GMP Annex 1 revisions are creating first-mover advantages for suppliers with validated aseptic filling lines for emergency anesthesia kits.
- Pediatric formulation gaps:Weight-based dosing requirements for neonatal and infant populations remain underserved by current adult-scaled presentations, offering differentiation through concentration-optimized vials.
- Target-controlled infusion software integration:Convergence of pharmacokinetic modeling with pump hardware is enabling proprietary algorithm-anesthetic pairings that lock in recurring drug supply contracts.
Industry Challenges
- ISO 13485 quality management certification:Device-drug combination suppliers must maintain dual compliance with pharmaceutical GMP and medical device quality standards, extending qualification timelines for new manufacturing sites.
- Legacy vaporizer incompatibility:Newer halogenated ether formulations require calibrated delivery systems that hospitals resist replacing due to capital budget constraints and anesthesia workstation replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anesthesia Drugs Market |
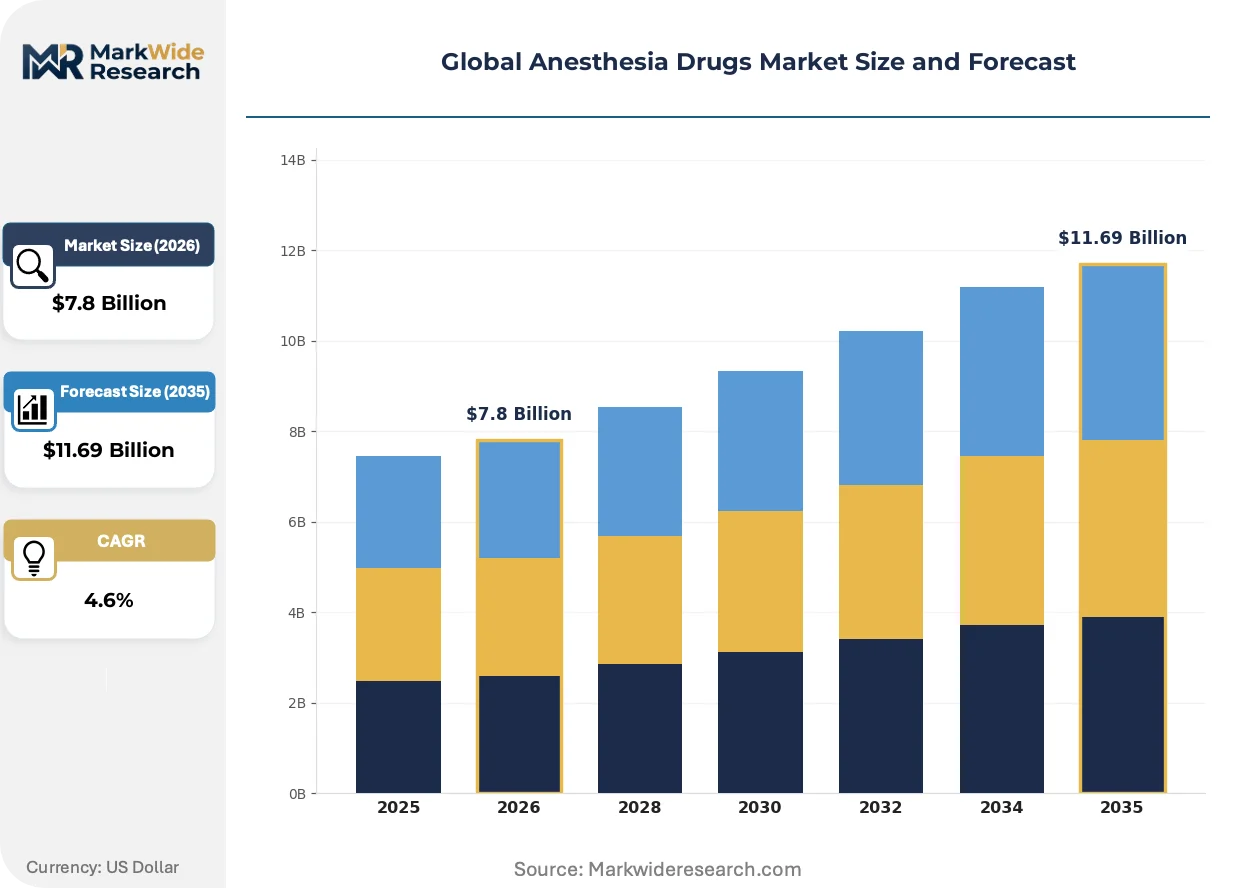
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $11.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalational Agents, Intravenous Agents, Local Anesthetics, Adjuncts Application: Surgical Procedures, Pain Management, Diagnostic Imaging, Dental Procedures, Emergency Care End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Care Centers Formulation: Liquid, Gas, Injectable, Topical, Powder |
| Companies Covered | Baxter International Inc., Fresenius SE & Co. KGaA, Aspen Pharmacare Holdings Ltd., Pfizer Inc., B. Braun Melsungen AG, Abbott Laboratories, AbbVie Inc., AstraZeneca PLC, Hikma Pharmaceuticals PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anesthesia Drugs Market Shifts & Advancements
Digital integration and formulation science are compressing the gap between pharmacological effect and physiological monitoring, enabling closed-loop delivery systems that adjust dosing in real time based on patient-specific biomarkers rather than population averages.
Closed-loop anesthesia delivery systems incorporating bispectral index feedback and automated propofol titration are rendering obsolete manual bolus administration protocols in tertiary surgical centers across Germany and the United States. Academic medical centers in Beijing and Shanghai are piloting these platforms for cardiac and neurosurgical cases where precise depth control reduces emergence delirium. The technology is compressing variation in drug consumption per procedure, pressuring suppliers to shift from volume-based to outcome-anchored contracting models.
The EU MDR's enhanced post-market surveillance requirements for device-drug combinations are forcing anesthesia equipment manufacturers to maintain pharmacovigilance databases that track adverse events across volatile agent and intravenous pump pairings. This regulatory burden is favoring suppliers with established quality management systems certified to ISO 13485, as smaller device makers exit the European market rather than absorb compliance costs. German and French hospital procurement consortia are now requiring MDR technical documentation as a mandatory bid qualification, filtering vendor pools before commercial negotiation begins.
Consolidated purchasing through regional hospital networks and government tenders in China and the United States is compressing price negotiation cycles from annual to quarterly intervals, forcing suppliers to maintain dynamic pricing capabilities and inventory positioning aligned to contract award timing. Group purchasing organizations are unbundling device and drug procurement, enabling competitive displacement of incumbent anesthetic suppliers even where delivery hardware remains unchanged. This pattern is most pronounced in United States integrated delivery networks and China's provincial centralized procurement programs, where volume commitments drive steep tiered discounts.
Global Anesthesia Drugs Market Segmentation
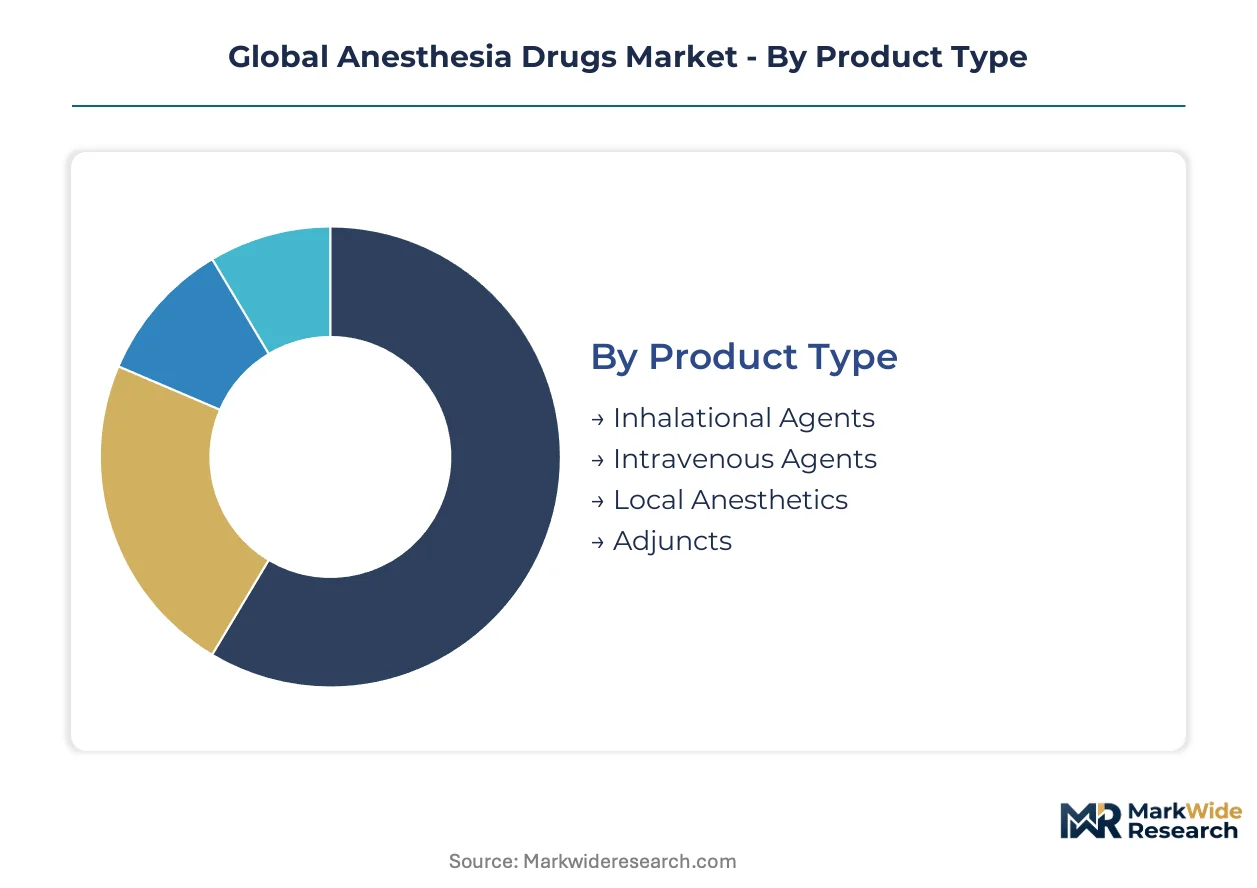
Segmentation in anesthesia drugs reveals how formulation science, delivery modality, and care setting interact to shape procurement patterns. Understanding these dimensions helps suppliers align manufacturing investments with where surgical volumes concentrate and where regulatory compliance costs escalate.
Product Type:
After-sales service intensity varies sharply across agent categories, with inhalational systems requiring vaporizer calibration and gas scavenging maintenance that intravenous lines simply do not demand.
- Intravenous Agents:Oil-in-water emulsions like propofol and ultra-short-acting hypnotics enable precise titration via target-controlled infusion. Demand concentrates in tertiary hospitals across Germany and the United States where cardiac and neurosurgical caseloads justify automated delivery infrastructure.
- Local Anesthetics:Amide derivatives including ropivacaine and lidocaine serve ultrasound-guided regional blocks. Ambulatory surgical centers in China and the United States are expanding nerve block protocols for orthopedic cases, displacing general anesthesia in same-day discharge settings.
- Inhalational Agents:Halogenated ethers such as sevoflurane and desflurane maintain entrenched positions in pediatric and cardiac anesthesia where volatile pharmacokinetics permit rapid depth adjustment.
- Adjuncts:Neuromuscular blocking agents and analgesic supplements complete anesthetic protocols, with procurement tied to bundled surgical packs in integrated delivery networks.
Intravenous agents hold the largest share; momentum sits with local anesthetics as ambulatory surgery expands.
Application:
Volume distribution across applications reflects where reimbursement incentives favor invasive intervention over conservative management.
- Surgical Procedures:General anesthesia for open and minimally invasive operations consumes the majority of agent volumes, with consumption patterns tracking seasonal elective surgery scheduling in United States hospital systems.
- Pain Management:Epidural and peripheral nerve block applications are gaining share fastest as enhanced recovery after surgery protocols prioritize opioid-sparing multimodal analgesia in European and North American facilities.
- Diagnostic Imaging:Sedation for MRI and CT procedures in pediatric and claustrophobic adult populations drives demand for short-acting intravenous agents with rapid clearance profiles.
- Dental Procedures:Local infiltration and conscious sedation applications favor lidocaine and midazolam combinations in office-based oral surgery settings.
- Emergency Care:Rapid-sequence intubation protocols in trauma bays require ketamine and etomidate availability with minimal cardiovascular depression.
Surgical procedures dominate absolute consumption; pain management is climbing the fastest as regional anesthesia protocols proliferate.
End User:
Capital equipment requirements and formulary control create distinct purchasing behaviors across facility types.
- Hospitals:Comprehensive anesthesia departments maintain diversified agent portfolios and captive pharmacy compounding capabilities, with procurement centralized through group purchasing organizations in the United States and Germany.
- Ambulatory Surgical Centers:Streamlined formularies emphasizing rapid-emergence agents align with discharge efficiency metrics; these facilities are expanding most quickly in China and the United States.
- Clinics:Office-based procedural sedation for dermatology and gastroenterology favors local anesthetics and oral anxiolytics with minimal monitoring requirements.
- Specialty Care Centers:Cardiac catheterization laboratories and obstetric units require dedicated anesthesia coverage with specialized agent preferences.
Hospitals retain the largest share; momentum sits with ambulatory surgical centers as outpatient migration accelerates.
Formulation:
Supply chain configuration and stability requirements differentiate manufacturing economics across physical states.
- Injectable:Sterile emulsions and solutions dominate hospital consumption, with propofol's oil-in-water formulation requiring cold chain integrity and short shelf lives that complicate inventory positioning.
- Liquid:Volatile agents stored in amber bottles for vaporizer filling maintain positions where institutional infrastructure resists conversion to prefilled delivery systems.
- Gas:Nitrous oxide and medical air for inhalational delivery require cylinder logistics and scavenging systems that constrain deployment outside hospital settings.
- Topical:EMLA cream and lidocaine patches serve superficial procedures and vascular access preparation with minimal professional supervision.
- Powder:Lyophilized formulations for reconstitution address stability challenges in tropical climates and emergency stockpiling scenarios.
Injectable formulations hold the largest share; topical applications are expanding most quickly as office-based procedures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government reimbursement incentives and surgical volume targets are redirecting procurement investments toward outpatient-compatible anesthesia formulations across major health systems.
United States
CMS bundled payment models for orthopedic and cardiac procedures accelerate same-day discharge protocols that favor rapid-emergence intravenous agents. The FDA's 21 CFR sterility guidelines and emergency use authorization pathways shape hospital formulary decisions. Academic medical centers in Boston and the Cleveland Clinic cluster pilot closed-loop infusion systems for neurosurgical cases.
Germany
Statutory health insurance reimbursement rates for ambulatory surgery create favorable economics for regional anesthesia protocols using ropivacaine. The EU MDR and BfArM post-market surveillance requirements extend qualification timelines for new infusion pump combinations. The Rhine-Ruhr metropolitan surgical corridor concentrates purchasing power through hospital procurement consortia in Düsseldorf and Cologne.
China
National Health Commission volume-based procurement drives steep tiered discounts for propofol and inhalational agents across provincial centralized tender programs. NMPA accelerated review pathways for innovative drug-device combinations compress time-to-market for domestic formulators. Shanghai and Beijing tertiary hospitals anchor demand for target-controlled infusion platforms in cardiac surgery units.
India
CDSCO manufacturing license requirements and the PLI scheme for active pharmaceutical ingredients attract investment in local alkyl phenol derivative production. Price controls under the National List of Essential Medicines cap margins on standard anesthesia formulations. The Hyderabad-Visakhapatnam pharmaceutical cluster expands sterile injectable capacity to serve domestic surgical volume growth.
Japan
PMDA Sakigake designation for breakthrough anesthesia delivery devices enables priority review for integrated pump-pharmacokinetic software systems. Reimbursement pricing under the Chuikyo framework rewards clinical outcome improvements over procedural volume. The Osaka-Kobe medical device corridor hosts manufacturing partnerships between anesthesia equipment makers and pharmaceutical formulators.
Global Anesthesia Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments where group purchasing organizations and government tenders unbundle traditional device-drug bundles. The vendor base organizes into three tiers: integrated care networks with captive pharmacy operations, sterile formulation specialists with validated aseptic filling lines, and regional generic injectable suppliers competing on price. Dominant competitive moves include backward integration into active pharmaceutical ingredient sourcing and strategic service contracts that lock in recurring drug supply through equipment leasing arrangements.
Among diversified health care conglomerates, Baxter International Inc. and Fresenius SE & Co. KGaA exemplify the integrated network archetype through combined device and pharmaceutical positioning. Pfizer Inc. occupies a position within the specialized manufacturing tier for ultra-short-acting hypnotics. These three entities represent distinct strategic postures: captive supply chain control, integrated care network leverage, and concentrated formulation scale.
| Leading Market Players |
|---|
| Baxter International Inc. |
| Fresenius SE & Co. KGaA |
| Aspen Pharmacare Holdings Ltd. |
| Pfizer Inc. |
| B. Braun Melsungen AG |
| Abbott Laboratories |
| AbbVie Inc. |
| AstraZeneca PLC |
| Hikma Pharmaceuticals PLC |
| Others |
Supply & Pricing Matrix
Overcapacity in China's sterile injectable manufacturing corridors is compressing margin structures for propofol emulsion suppliers while simultaneously granting volume buyers enhanced negotiating leverage across multi-year procurement contracts. This utilization dynamic feeds directly into pricing postures, as formulators with underutilized aseptic filling lines absorb steeper discounts to maintain throughput against fixed cost bases.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-validated suppliers and standard GMP facilities, with FDA-grade sterile filling commanding substantial premia over regional-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels segments the market by quality assurance depth and pharmacovigilance documentation rigor. Cost compression in the economy tier is intensifying because provincial centralized procurement programs in China and group purchasing organizations in the United States extract volume-based concessions. Academic medical centers with closed-loop anesthesia infrastructure exhibit the lowest price sensitivity, while ambulatory surgical centers operating on discharge-efficiency metrics drive the hardest bargain negotiations.
Supply Chain Analysis
Upstream alkyl phenol derivative production centers on India, China, and Germany, with the Hyderabad-Visakhapatnam corridor expanding capacity under the PLI scheme for active pharmaceutical ingredients. Critical inputs span propofol crude, amide local anesthetic bases, and halogenated ether precursors, each drawing from distinct petrochemical and fine chemical feedstocks. Single-source vulnerability concentrates in the 1% oil-in-water emulsion filling stage, where validated aseptic lines remain limited to a handful of facilities. Distribution runs through hospital procurement consortia and government tender platforms that consolidate demand before supplier qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
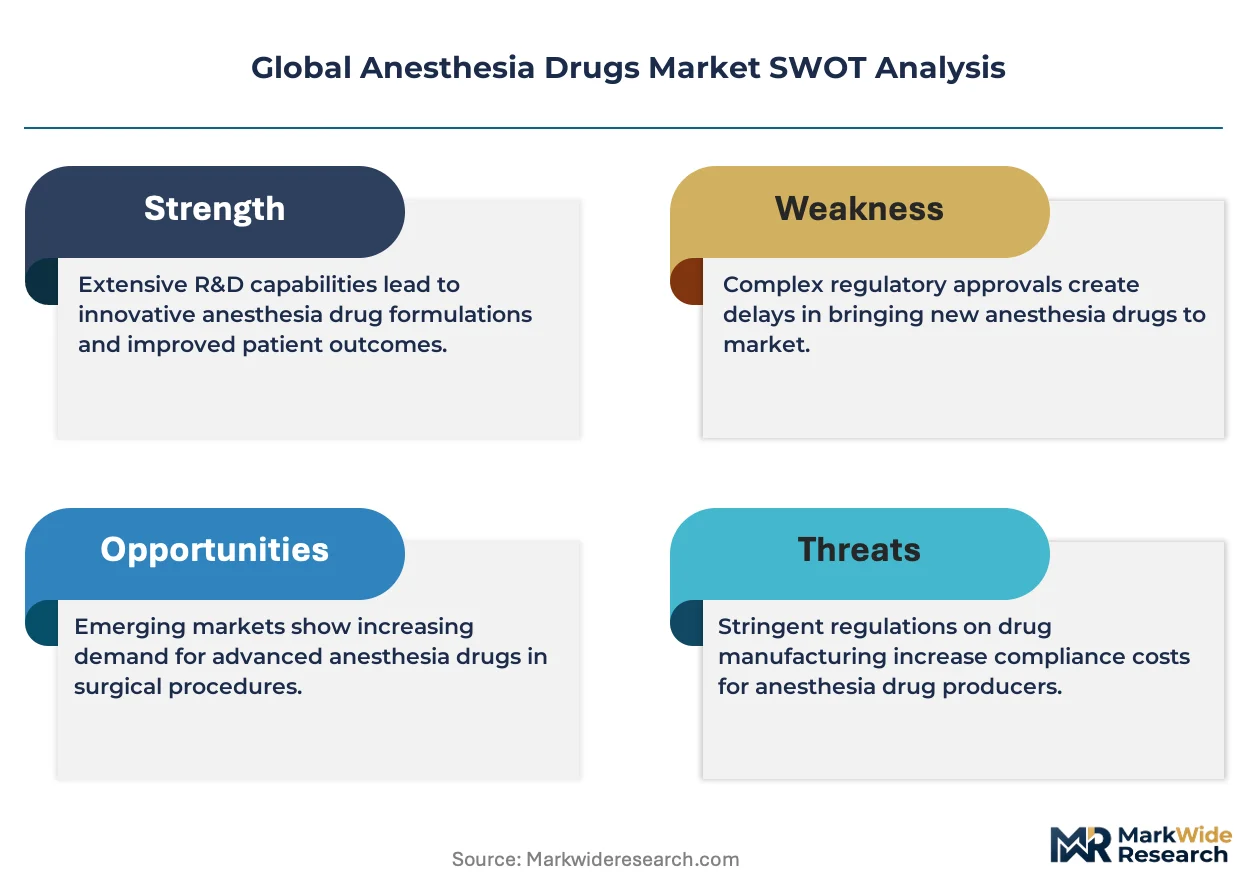
This market functions as a defensive-moat arena where regulatory entrenchment through FDA 21 CFR compliance and EU MDR technical documentation creates formidable barriers to competitive displacement. Switching costs for hospital formularies compound this structural advantage, locking in incumbent positions.
For Market Incumbents: Pre-empt biosimilar erosion by securing captive supply of propofol API through backward integration into Indian manufacturing clusters under the PLI scheme. Accelerate ISO 13485 certification investments for aseptic filling capacity in Germany and the United States to defend against emerging entrants with regional-grade quality systems. The priority lever rests on equipment-drug bundling contracts that tie vaporizer leasing to minimum volume commitments for volatile agents.
For New Entrants and Emerging Players: Establish a beachhead in pediatric formulation gaps, where weight-optimized concentration vials for neonatal populations remain underserved by adult-scaled presentations from incumbent suppliers. Target ambulatory surgical centers in China's provincial markets, where centralized procurement programs have created formulary openings for cost-competitive local anesthetics. The most penetrable entry vector runs through ropivacaine and lidocaine nerve block protocols displacing general anesthesia in orthopedic cases.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across device-drug combination manufacturing, as EU MDR compliance extends qualification timelines and dual GMP-device quality management requirements inflate facility investment thresholds. Acquisition targets should prioritize sterile formulation specialists with validated aseptic lines and existing FDA establishment registrations, positioned for consolidation into integrated care networks. The signal to watch is provincial tender award timing in China, where volume commitment announcements precede margin compression waves by two to three quarters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Sourcing | PLI scheme incentives in India reduce propofol crude dependency on Chinese alkyl phenol suppliers. |
| EU MDR Technical Documentation Investment | BfArM post-market surveillance compliance filters vendor pools before German hospital procurement negotiations. |
| Pediatric Formulation Development | Weight-based dosing requirements for neonatal populations open differentiation against adult-scaled incumbent portfolios. |
| Closed-Loop Infusion Software Integration | Proprietary algorithm-anesthetic pairings lock in recurring drug supply through pump hardware contracts. |
| Prefilled Syringe Aseptic Filling Scale-Up | FDA 21 CFR sterility guidelines create first-mover advantages for emergency anesthesia kit suppliers. |
Research Methodology
The analysis maps intravenous agents, local anesthetics, inhalational agents, and adjunct formulations, each validated through hospital pharmacy directors, anesthesia department chiefs, GPO contracts managers, and regulatory affairs leads at formulation specialists. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA marketing authorization databases, NMPA registration records, and CMS Medicare reimbursement data. Bottom-up surgical volume modeling and top-down pharmaceutical consumption estimates triangulate market sizing across the projection horizon.
Assumptions held surgical volume growth trajectories and reimbursement policy frameworks fixed while varying regulatory compliance cost inflation and biosimilar entry timing across scenarios. Segmentation dimensions span agent pharmacology, delivery modality, care setting infrastructure, and regional regulatory cluster. CAGRs derive from procedure volume elasticity to population aging and ambulatory surgery migration, cross-referenced against propofol consumption intensity per surgical case and inhalational agent environmental restriction implementation pace.
Sensitivities concentrate around EU F-Gas Regulation enforcement stringency, NMPA provincial tender discount depth, and propofol supply disruption events at single-site manufacturing facilities. Forecasts reflect documented assumptions regarding sterile filling capacity expansion and group purchasing organization consolidation trajectories. Cross-checking against IQVIA MIDAS pharmaceutical audit data and hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Powder-Filled Hard Gelatin Capsules Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Mitotane Market