
 Global Interstitial Cystitis Drugs Market | 2026-2036
Global Interstitial Cystitis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interstitial Cystitis Drugs Market Foresight
Market Context
North American pharmaceutical manufacturing capacity for bladder pain therapies is broadening as specialty API production scales up. Pfizer Inc. leverages its established urology portfolio to maintain distribution reach across hospital networks. Johnson & Johnson anchors its position through Janssen Pharmaceuticals' research intensity in pelvic disorder compounds. Astellas Pharma Inc. competes via specialized expertise in urological therapeutic development.
Technical Definition and Segment Structure
Interstitial cystitis drugs comprise pharmaceutical agents formulated to modulate bladder epithelial permeability, reduce neurogenic inflammation, or block pain signaling pathways involving mast cell mediators and substance P. These compounds serve the primary commercial purpose of alleviating chronic bladder pain and urinary dysfunction in patients with interstitial cystitis/bladder pain syndrome. Oral agents dominate current prescription volumes due to patient convenience and established reimbursement pathways, while intravesical therapies command premium positioning in refractory cases managed at urology centers. Pentosan polysulfate sodium occupies a mature regulatory niche with decades of clinical use, though pain relievers and antihistamines are gaining share in combination protocols.
Regulatory Frame and Outlook
FDA, EMA, and Japan's PMDA govern interstitial cystitis drug approvals through distinct efficacy endpoints and safety monitoring requirements, with FDA's streamlined pathways for rare urological conditions accelerating developer timelines. REACH and EU MDR compliance adds formulation and packaging standards for European market entry, while WHO guidelines influence off-label use patterns in emerging markets. Stakeholders must monitor evolving biomarker-based trial designs that could reshape which drug classes gain priority access.
Market Dynamics
FDA's streamlined pathways for rare urological conditions are compressing development timelines and redrawing competitive entry barriers for interstitial cystitis therapies. This regulatory acceleration is pulling capital toward bladder pain drug candidates while fragmenting incumbent market positions.
Growth Catalysts
- Specialist diagnostic infrastructure:Urology centers in the United States and Germany are expanding interstitial cystitis treatment protocols. This concentration of clinical expertise is creating referral networks that pull patients toward validated pharmaceutical interventions.
- EMA market access streamlining:The European Medicines Agency's bladder pain therapy pathways are reducing approval friction for novel compounds. Developers are prioritizing European submissions to capture reimbursed patient pools.
- Pentosan polysulfate sodium maturation:Decades of clinical use have established reimbursement codes and prescriber familiarity. This foundational therapy is training physicians to manage chronic bladder pain pharmacologically rather than surgically.
Market Restraints
- Active pharmaceutical ingredient concentration:Specialty API production for bladder pain therapies clusters among contract manufacturers in Switzerland and India. Supply disruptions at these nodes would cascade through formulation pipelines.
- Biomarker validation gaps:Absence of FDA-qualified surrogate endpoints forces reliance on subjective pain scales. Trial durations extend and failure rates climb compared to urological conditions with objective measures.
- Off-label substitution:Generic antihistamines and tricyclics prescribed for symptom management compete with branded interstitial cystitis indications. Payers often require step therapy through these lower-cost alternatives.
Strategic Opportunities
- Japan's PMDA orphan pathways:Japan's pharmaceutical regulator offers accelerated review and tax incentives for rare disease indications. Developers can leverage interstitial cystitis prevalence thresholds to access premium pricing in the world's third-largest pharmaceutical market.
- Intravesical delivery innovation:Combination protocols pairing oral agents with catheter-administered therapies are opening refractory case management. Urology centers are investing in ambulatory infusion infrastructure to capture these higher-acuity patients.
- WHO guideline influence:Emerging markets in Southeast Asia and Latin America reference WHO bladder pain management recommendations. Manufacturers can build prescriber education programs around these frameworks to establish brand preference before local registration.
Industry Challenges
- Mast cell mediator assay standardization:Variability in laboratory measurement of substance P and histamine levels complicates patient stratification. Clinical trial enrollment requires centralized testing partnerships that extend site activation timelines.
- Legacy electronic health record integration:Bladder pain symptom tracking tools must interface with hospital systems from Epic, Cerner, and regional vendors. Custom integration costs consume digital health budgets that could deploy patient-facing adherence applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interstitial Cystitis Drugs Market |
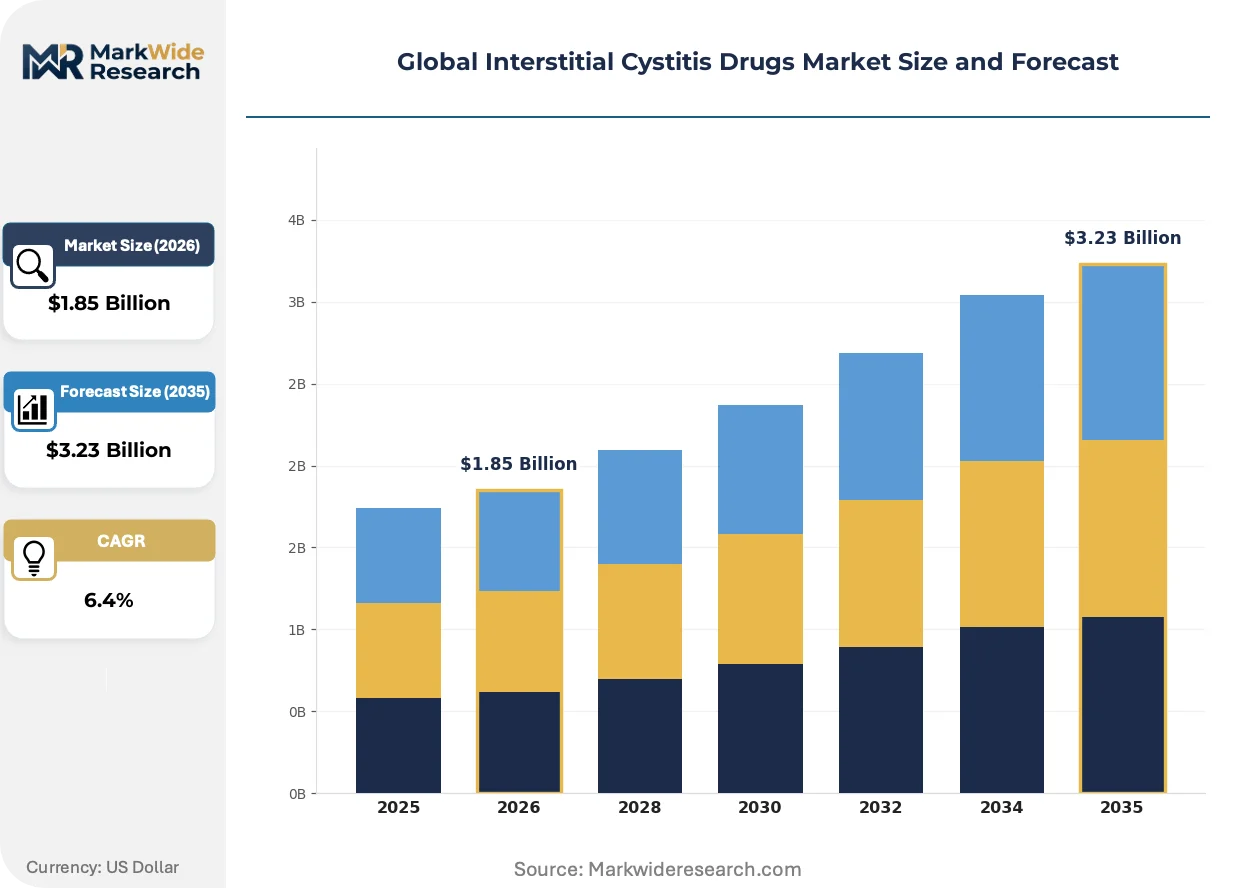
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Agents, Intravesical Therapies, Pain Relievers, Antihistamines, Pentosan Polysulfate Sodium Therapy Area: Bladder Pain, Urinary Frequency, Urgency, Non-Urological Symptoms, Pelvic Discomfort End User: Specialized Clinics, Urology Centers, Outpatient Facilities, Home Care Services, Research Institutes Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales, Wholesalers |
| Companies Covered | Pfizer Inc., Johnson & Johnson (Janssen Pharmaceuticals), Astellas Pharma Inc., Teva Pharmaceutical Industries, AbbVie Inc., Eli Lilly and Company, Sandoz AG, Boehringer Ingelheim, Kyorin Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interstitial Cystitis Drugs Market Shifts & Advancements
Neurogenic inflammation research is electrifying the interstitial cystitis pipeline, with developers targeting mast cell stabilization and nerve sensitization mechanisms that were previously addressed only symptomatically.
Peripheral nerve stimulation devices paired with pharmaceutical protocols are electrifying multimodal bladder pain management. Academic medical centers in Boston and Heidelberg are adopting these combinations for refractory cases. The technology is electrifying expansion of urology center service lines beyond medication-only approaches.
REACH and EU MDR compliance requirements are reshaping formulation and packaging standards for European market entry. Manufacturers must submit extensive substance safety dossiers and maintain post-market surveillance systems. Small molecule oral agents face the steepest documentation burdens, pushing some developers toward intravesical delivery to simplify regulatory classification.
Patient advocacy organizations are consolidating purchasing influence through dedicated pharmacy benefit structures. The Interstitial Cystitis Association and equivalent European patient groups are negotiating direct distribution agreements that bypass traditional wholesale channels. This concentration is most visible in Germany and the Netherlands where disease-specific health foundations hold formal consultation status with national payers.
Global Interstitial Cystitis Drugs Market Segmentation
Pharmaceutical purchasing decisions for interstitial cystitis therapies hinge on route of administration convenience versus clinical severity. Reimbursement pathways and prescriber familiarity with specific drug classes further stratify how manufacturers prioritize development resources across the addressable patient population.
Product Type:
Patient compliance expectations and prescriber training histories determine which delivery formats capture prescription volumes.
- Oral Agents:Pentosan polysulfate sodium and other systemic compounds offer self-administration convenience that aligns with chronic disease management protocols. United States urology centers prescribe oral formulations as first-line therapy for newly diagnosed patients, though step-therapy requirements from commercial payers delay branded agent access.
- Intravesical Therapies:Catheter-administered solutions containing dimethyl sulfoxide or heparin analogues deliver higher local concentrations to bladder epithelium. German academic medical centers have invested in ambulatory infusion infrastructure to manage refractory cases that fail oral protocols, creating premium pricing corridors for device-drug combinations.
- Pain Relievers:Amitriptyline and gabapentin derivatives address neuropathic components of bladder pain syndrome through off-label prescribing patterns.
- Antihistamines:Hydroxyzine targets mast cell-mediated symptoms in combination regimens with pentosan polysulfate sodium.
- Pentosan Polysulfate Sodium:The sole FDA-approved oral agent for interstitial cystitis occupies a distinct regulatory niche with established Medicare reimbursement codes.
Volume sits with Oral Agents; growth tilts toward Intravesical Therapies.
Therapy Area:
Symptom severity hierarchies in clinical practice guidelines shape which therapeutic targets justify premium development investment.
- Bladder Pain:The cardinal symptom driving diagnostic workups and treatment initiation commands the deepest pharmaceutical pipeline investment. Japanese PMDA orphan drug pathways specifically prioritize pain reduction endpoints, attracting developers to target this indication for accelerated regulatory review.
- Urinary Frequency:Nocturia and daytime voiding disturbances impose measurable quality-of-life decrements that support pharmacological intervention. United Kingdom NICE guidelines recognize frequency reduction as a co-primary endpoint, expanding reimbursable indications beyond pain-centric approaches.
- Urgency:Sudden compelling voiding sensations respond variably to antimuscarinic agents repurposed from overactive bladder indications.
- Non-Urological Symptoms:Dyspareunia and systemic sensitization patterns require cross-specialty collaboration between urology and gynecology practices.
- Pelvic Discomfort:Overlapping pathology with chronic prostatitis and pelvic floor dysfunction complicates pure pharmaceutical management.
Clinical trial enrollment concentrates on Bladder Pain; regulatory innovation is expanding fastest in Urinary Frequency.
End User:
Site-of-care economics and reimbursement intensity determine where pharmaceutical manufacturers deploy specialist sales forces.
- Urology Centers:High-acuity referral destinations manage complex cases requiring multimodal protocols combining oral and intravesical agents. Academic centers in Boston and Heidelberg generate treatment algorithms that diffuse to community practice, establishing prescriber habits that persist across care settings.
- Specialized Clinics:Dedicated interstitial cystitis practices in the Netherlands and Germany consolidate patient volumes sufficient to support catheter-based therapy administration. These centers negotiate direct purchasing agreements that bypass traditional wholesale markups.
- Outpatient Facilities:General urology practices initiate most new prescriptions within primary diagnostic encounters.
- Home Care Services:Self-administration training programs enable patient-managed intravesical therapy for geographically dispersed populations.
- Research Institutes:Academic medical centers conduct biomarker validation studies that reshape future trial designs.
Prescription origin concentrates at Urology Centers; patient capture is climbing fastest at Specialized Clinics.
Distribution Channel:
Reimbursement mechanics and patient cost-sharing structures determine which logistics pathways dominate drug flow.
- Hospital Pharmacies:Captive dispensing within integrated delivery networks ensures formulary compliance and captures 340B pricing advantages for eligible institutions. United States health systems increasingly require hospital pharmacy sourcing for specialty medications administered in infusion centers.
- Retail Pharmacies:Community dispensing locations handle oral agent fulfillment for stable patients on maintenance therapy. CVS and Walgreens negotiate preferred network status with commercial payers that steer pentosan polysulfate sodium prescriptions toward specific locations.
- Online Pharmacies:Mail-order fulfillment reduces out-of-pocket costs for patients in high-deductible health plans.
- Direct Sales:Manufacturer-to-patient distribution bypasses wholesale margins for orphan-designated therapies.
- Wholesalers:McKesson and AmerisourceBergen maintain inventory positions that buffer supply disruptions.
Transaction volume flows through Hospital Pharmacies; channel expansion is accelerating most quickly at Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty API production for bladder pain therapies clusters in Swiss and Indian contract manufacturing nodes, with downstream formulation and clinical development concentrating in North American and Western European markets where diagnostic infrastructure and reimbursement depth align.
United States
Academic medical centers in Boston and Baltimore generate treatment algorithms that diffuse to community urology practices nationwide. FDA's streamlined pathways for rare urological conditions compress development timelines for novel bladder pain candidates. The Interstitial Cystitis Association consolidates patient purchasing influence through dedicated pharmacy benefit structures that bypass traditional wholesale channels.
Germany
Heidelberg and Berlin anchor Europe's deepest concentration of interstitial cystitis specialist clinics with ambulatory infusion infrastructure for refractory case management. EMA bladder pain therapy pathways reduce approval friction, attracting developers to prioritize European submissions. Disease-specific health foundations hold formal consultation status with national payers, shaping reimbursement policy.
Japan
PMDA orphan drug pathways offer accelerated review and tax incentives that attract developers targeting interstitial cystitis prevalence thresholds. Tokyo and Osaka medical centers conduct biomarker validation studies that reshape regional trial designs. Premium pricing in the world's third-largest pharmaceutical market rewards first-mover entrants.
Switzerland
Basel and Zurich host contract manufacturers specializing in pentosan polysulfate sodium API production that feeds global formulation pipelines. Swissmedic maintains stringent substance safety dossier requirements that shape documentation standards across European market entry. Post-market surveillance systems here model compliance architecture for REACH and EU MDR alignment.
India
Hyderabad and Ahmedabad manufacturing clusters produce generic antihistamine and tricyclic compounds that compete with branded interstitial cystitis indications through off-label prescribing. CDSCO regulatory frameworks govern domestic market access while export-oriented facilities supply active pharmaceutical ingredients to European and North American formulators.
Global Interstitial Cystitis Drugs Market Competitive Landscape
Global majors compete with regional champions across regulatory access and specialist prescriber relationships, creating a tiered structure where scale-driven portfolios intersect with urology-focused development intensity. Market positions fragment across oral agent incumbents, intravesical delivery innovators, and neuropathic pain repurposers. Three archetypes dominate: diversified pharmaceutical conglomerates with established urology sales infrastructure, mid-cap specialists concentrating pelvic disorder research, and generic manufacturers capturing off-label substitution volume. Competitive moves center on M&A to acquire catheter-based delivery platforms and strategic partnerships with academic medical centers to shape treatment algorithms.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Johnson & Johnson occupy positions anchored by hospital network distribution reach and Janssen Pharmaceuticals' research intensity in pelvic disorder compounds. Astellas Pharma Inc. sits within the specialist tier, exemplifying concentrated expertise in urological therapeutic development that competes through depth rather than breadth.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson (Janssen Pharmaceuticals) |
| Astellas Pharma Inc. |
| Teva Pharmaceutical Industries |
| AbbVie Inc. |
| Eli Lilly and Company |
| Sandoz AG |
| Boehringer Ingelheim |
| Kyorin Pharmaceutical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Step-therapy mandates from United States commercial payers are forcing manufacturers to unbundle intravesical therapy administration services from drug pricing, compressing margins on device-drug combinations while shifting cost recovery toward separate catheter billing codes.
Pricing Analysis
Service bundling separates warranty-backed oral agents from unbundled intravesical delivery systems that carry separate facility fees. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA approval status and prescriber familiarity, with pentosan polysulfate sodium occupying the premium tier due to decades of reimbursement history. Cost compression in oral generic substitutes is intensifying because off-label antihistamine prescribing captures step-therapy volume before branded access. Retail pharmacy patients in high-deductible plans exhibit highest price sensitivity, while urology center infusion patients show lowest sensitivity due to captive dispensing within integrated delivery networks.
Supply Chain Analysis
REACH and EU MDR certification requirements gate European market entry for pentosan polysulfate sodium API, forcing documentation investments that smaller formulators cannot absorb. Swiss and Indian contract manufacturers anchor global API supply, with downstream formulation concentrating in United States and German facilities that feed hospital pharmacy networks. Raw material dependencies include heparin analogues, dimethyl sulfoxide, and specialized catheter polymers that draw from chemical suppliers in Basel and Hyderabad. Single-source vulnerability concentrates at Swiss pentosan polysulfate sodium API nodes where disruptions would cascade through multiple branded pipelines. Distribution runs through hospital pharmacies capturing 340B pricing advantages, with retail and online channels handling stable maintenance prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neurogenic inflammation research is displacing mast-cell-centric development paradigms, with peripheral nerve stimulation devices replacing oral-only protocols as the standard of care for refractory cases at academic medical centers.
For Market Incumbents: To counter intravesical delivery innovators capturing refractory case premium pricing, Pfizer and Johnson & Johnson should deepen backward integration into Swiss API supply through captive manufacturing partnerships or long-term offtake agreements with Basel contract manufacturers. Janssen Pharmaceuticals must accelerate biomarker validation investments to secure FDA-qualified surrogate endpoints that compress trial timelines against generic substitution threats. For New Entrants and Emerging Players: Catheter-administered combination protocols offer the most penetrable white space, particularly in German specialized clinics where ambulatory infusion infrastructure investments create sticky prescriber relationships. Japan's PMDA orphan pathways present regulatory arbitrage opportunities for developers willing to prioritize Tokyo and Osaka medical center partnerships over European submissions. A technology-first go-to-market angle pairs device-drug combinations with digital adherence platforms that integrate with Epic and Cerner electronic health record systems. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with concentrated urology development depth rather than diversified pharmaceutical conglomerates where pelvic disorder research competes for capital allocation. Acquisition targets should demonstrate established catheter-based delivery platforms and active academic medical center investigator relationships in Boston or Heidelberg. The signal to watch is FDA biomarker qualification announcements that would reshape trial economics and elevate valuations for developers with validated patient stratification assays.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Biomarker-based endpoints attract FDA qualification that compresses development timelines against subjective pain scales. |
| Regulatory Approval Pathway | PMDA orphan designation unlocks accelerated review and tax incentives in Japan's premium-priced market. |
| Manufacturing Scale-Up | Swiss API capacity expansion buffers single-source vulnerability that threatens global pentosan polysulfate sodium supply. |
| Pipeline Diversification | Neurogenic inflammation targets reduce reliance on mast cell mechanisms that generic antihistamines address symptomatically. |
| Strategic Partnership | Academic medical center alliances in Boston and Heidelberg shape treatment algorithms that diffuse to community urology practices. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were triangulated against primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. FDA 510(k) submissions, EMA marketing authorization applications, ClinicalTrials.gov entries, and Medicare formulary databases provided structured validation points. Bottom-up patient population modeling and top-down pharmaceutical spending analysis were reconciled to produce volume and value estimates.
Granularity-level modeling tracked oral versus intravesical administration routes, first-line versus refractory treatment lines, and regional regulatory clusters spanning FDA, EMA, and PMDA jurisdictions across the analysis window. CAGRs were derived from epidemiological prevalence projections, pricing elasticity assumptions, and reimbursement pathway penetration curves. Forecast inputs included biomarker validation timelines, catheter-based therapy adoption rates at urology centers, and step-therapy policy evolution at major United States commercial payers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA biomarker qualification delays or Swiss API supply disruptions. Projections reflect assumptions regarding reimbursement code stability, prescriber training diffusion rates, and competitive entry sequencing that could revise trajectory materially. A model refresh is warranted upon material change in FDA surrogate endpoint guidance or EMA bladder pain therapy pathway restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Amlodipine Besylate Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Montelukast Market