
 Germany Pharmaceutical Cold Chain Logistics Market | 2026-2036
Germany Pharmaceutical Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Pharmaceutical Cold Chain Logistics Market Insights
The EU Green Deal is shifting pharmaceutical logistics toward lower-emission refrigerated transport fleets across Germany. DHL anchors its cold chain dominance through extensive last-mile temperature-controlled networks serving biologics manufacturers. Kuehne + Nagel leverages digital twin technology to monitor thermal integrity across its German pharmaceutical warehousing footprint. Trans-o-flex (ThermoMed) specializes in same-day courier services for temperature-sensitive therapies, competing on speed where standard freight operators cannot operate.
Germany pharmaceutical cold chain logistics encompasses the temperature-controlled movement and storage of medicinal products requiring maintenance between 2°C and 8°C or cryogenic conditions below -150°C, utilizing validated thermal packaging, continuous data loggers, and redundant cooling systems to prevent potency degradation. The primary commercial purpose centers on preserving pharmacological efficacy from manufacturing release through patient administration. Refrigerated transport occupies the largest value share within the service type dimension, driven by lane density between Rhine-Main and Rhine-Ruhr pharmaceutical corridors. Passive systems dominate the temperature control method segment for last-mile vaccine delivery, while active systems capture premium margins in biologics distribution where excursion tolerance approaches zero. Specialty pharmaceuticals within the product type category represent the fastest-growing margin pool, reflecting personalized medicine payloads with ultra-narrow temperature bands.
BfArM enforces GDP compliance through unannounced inspections of German pharmaceutical distribution sites, while the EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in transport cooling units. The Bundesamt für Güterverkehr coordinates with BfArM to align road transport licensing with pharmaceutical carriage standards. Stakeholders must monitor emerging MDR traceability requirements that will mandate serialized cold chain documentation for implantable biologics entering German hospitals.
Market Dynamics
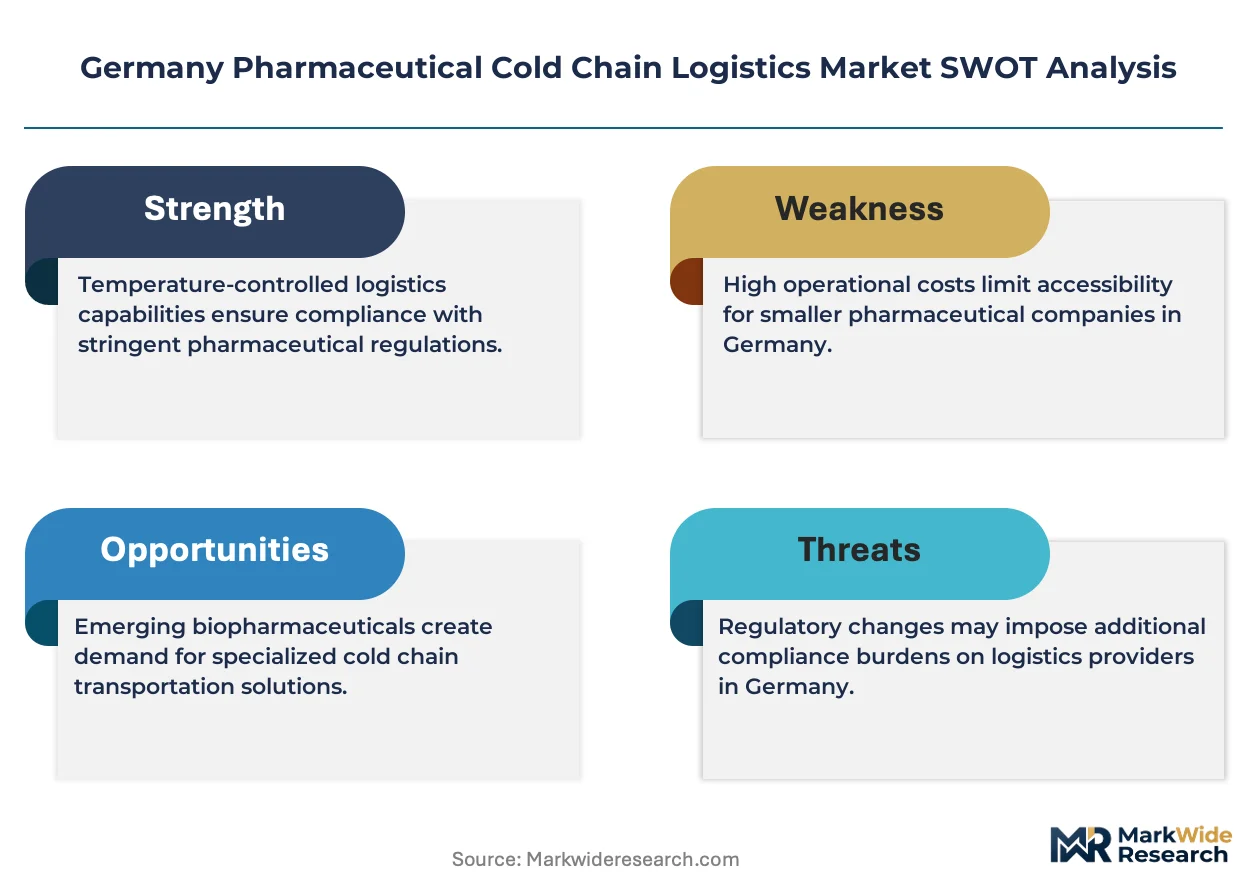
The EU F-Gas Regulation is forcing German pharmaceutical logistics operators to retrofit refrigerated vehicle fleets with lower-global-warming-potential refrigerants, compressing equipment replacement cycles and reshaping capital allocation across temperature-controlled transport networks.
Growth Catalysts
- Cell and gene therapy pipeline expansion:Bavarian biotech clusters in Munich are driving demand for cryogenic distribution infrastructure below minus 150 degrees Celsius.
- EU MDR traceability mandates:Serialized cold chain documentation requirements for implantable biologics are creating compliant service premiums for hospital-facing distributors.
- BfArM GDP enforcement intensity:Unannounced inspections of German pharmaceutical distribution sites are consolidating volume toward certified operators with validated quality management systems.
Market Restraints
- Refrigerant input cost volatility:Hydrofluorocarbon phase-down schedules under EU F-Gas Regulation are compressing margins on legacy cooling unit maintenance.
- Specialized vehicle supply concentration:German refrigerated truck body manufacturing clusters in North Rhine-Westphalia face capacity constraints extending equipment delivery timelines.
- Cryogenic packaging technical limitation:Passive thermal protection duration caps at 96 hours for ultra-low temperature payloads, constraining intercontinental lane options.
Strategic Opportunities
- Baden-Württemberg manufacturing corridor:Underpenetrated cold storage capacity around Stuttgart pharmaceutical production sites offers greenfield development potential.
- Real-time data monetization:Continuous temperature logger streams are enabling outcome-based logistics contracts with biologics manufacturers seeking excursion liability transfer.
- Last-mile autonomous integration:Convergence of drone delivery frameworks with validated thermal containers is opening rural patient access corridors.
Industry Challenges
- Qualified personnel scarcity:GDP-certified warehouse operators and thermal packaging engineers face recruitment gaps in Saxony and Thuringia logistics hubs.
- Legacy warehouse reconfiguration:Existing pharmaceutical storage facilities require redundant cooling system upgrades to meet tightening BfArM temperature mapping standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Pharmaceutical Cold Chain Logistics Market |
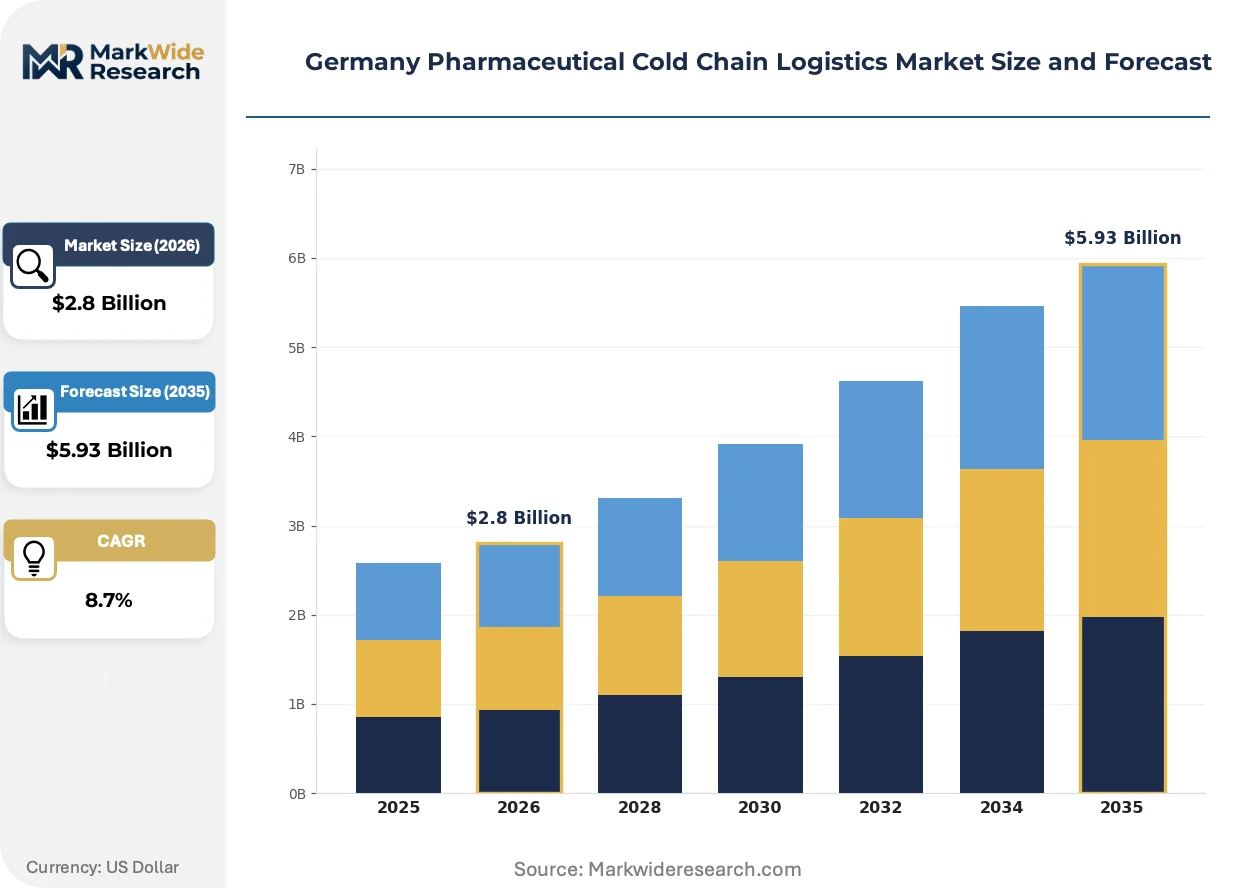
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Tracking Temperature Control Method: Refrigerated Transport, Cryogenic Shipping, Active Systems, Passive Systems Product Type: Vaccines, Biologics, Blood Products, Specialty Pharmaceuticals End User: Pharmaceutical Manufacturers, Hospitals, Clinics, Distributors |
| Companies Covered | Trans-o-flex (ThermoMed), DHL, GDP Network Solutions GmbH, Transmed Transport GmbH, Kuehne + Nagel, DB Schenker, Rhenus Logistics, Ceva Logistics, Pfenning Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Pharmaceutical Cold Chain Logistics Market Trends and Innovations
Digital twin architectures are compressing thermal excursion response times from hours to minutes across German pharmaceutical distribution networks. Three interconnected developments are restructuring competitive capability requirements.
IoT-enabled sensor networks are expanding into active refrigerated transport units, generating sub-minute temperature deviation alerts. Biologics manufacturers with zero-excursion tolerance requirements are adopting these systems fastest. Real-time telemetry is expanding into contractual service level agreements, compressing liability windows for German cold chain operators.
EU CSRD sustainability reporting mandates are forcing disclosure of refrigerated transport emissions across Scope 3 categories. German pharmaceutical distributors must now document fleet carbon intensity per temperature-controlled lane. Large biologics manufacturers with net-zero commitments are responding by tendering logistics contracts exclusively to operators with electric or hydrogen-powered cold chain vehicles.
Hospital pharmacy consolidation is concentrating purchasing power among regional German healthcare networks. Smaller clinics and independent pharmacies are losing direct access to temperature-sensitive specialty pharmaceuticals. This concentration is most visible in North Rhine-Westphalia, where university hospital networks are absorbing community oncology infusion centers and centralizing cold chain procurement.
Germany Pharmaceutical Cold Chain Logistics Market Segmentation
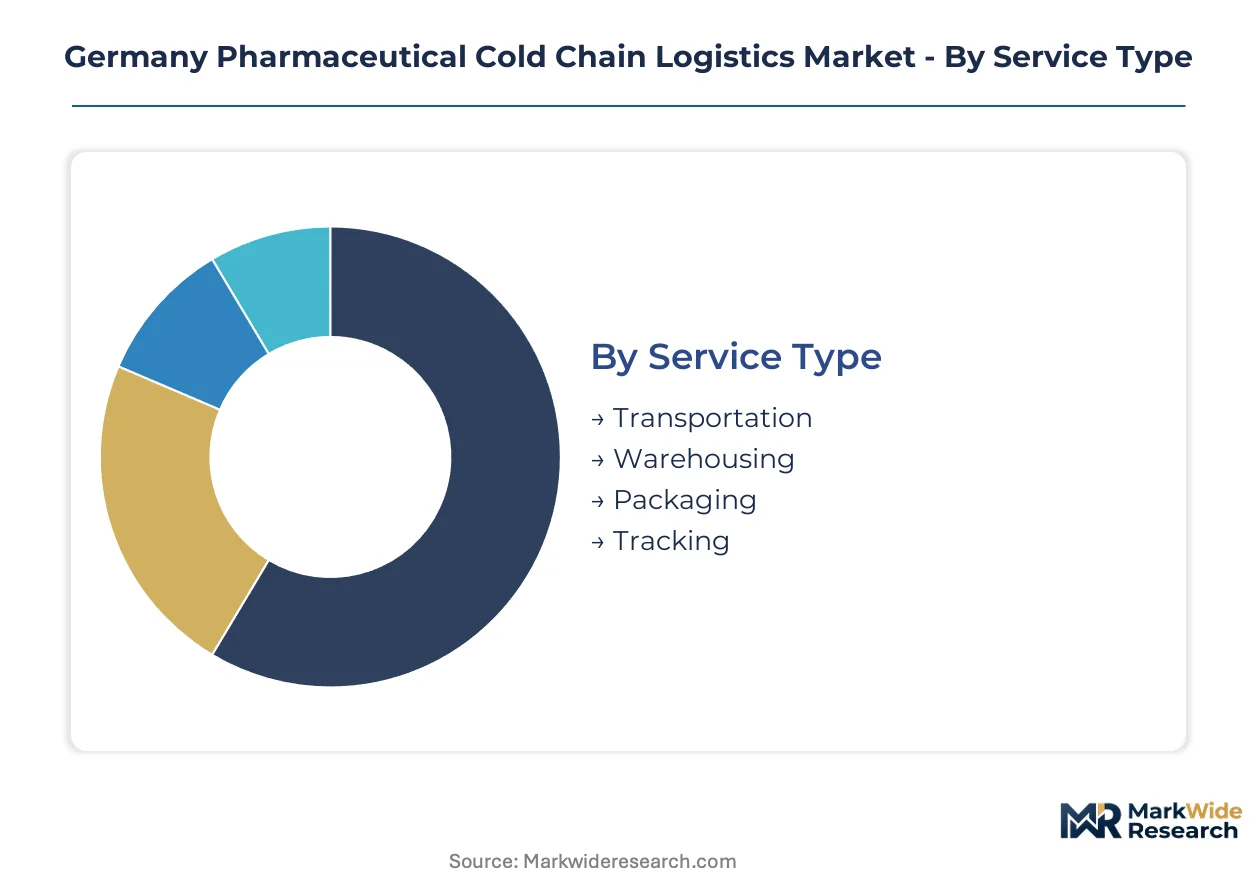
Temperature band requirements and payload value density determine capital allocation across German pharmaceutical cold chain segments. Service providers configure asset portfolios around excursion tolerance thresholds and lane density patterns.
Service Type:
Capital intensity peaks in segments requiring dedicated vehicle fleets and redundant cooling infrastructure.
- Transportation:Validated refrigerated vehicles and cryogenic tankers dominate capital deployment across Rhine-Main and Rhine-Ruhr pharmaceutical corridors. Bavarian cell therapy manufacturers are contracting dedicated lane capacity to Munich biotech clusters.
- Warehousing:Multi-temperature pharmaceutical distribution centers require redundant cooling systems and continuous temperature mapping under BfArM GDP standards. Baden-Württemberg storage capacity lags Stuttgart manufacturing demand.
- Packaging:Thermal container validation and qualification protocols absorb R&D expenditure for passive and active system developers.
- Tracking:IoT sensor networks and real-time telemetry platforms enable excursion liability transfer to logistics operators.
Most installed capacity flows through Transportation. Expansion is steepest in Tracking.
Temperature Control Method:
Application criticality separates premium-priced active systems from commodity passive protection.
- Refrigerated Transport:Diesel-electric and fully electric cooling units maintain 2°C to 8°C across German road networks. EU F-Gas Regulation is accelerating fleet retrofit cycles for hydrofluorocarbon phase-down compliance.
- Cryogenic Shipping:Liquid nitrogen and dry ice systems sustain temperatures below -150°C for cell and gene therapy payloads. Bavarian biotech corridors anchor specialized tanker demand.
- Active Systems:Powered refrigeration with battery backup eliminates excursion risk for high-value biologics.
- Passive Systems:Insulated containers with phase-change materials dominate last-mile vaccine delivery where cost minimization outweighs duration constraints.
Passive systems carry the highest shipment volume. Active systems command the steepest margin expansion trajectory.
Product Type:
Payload value concentration and temperature band narrowness determine service pricing tiers.
- Specialty Pharmaceuticals:Personalized medicine with ultra-narrow temperature tolerances and patient-specific dosing protocols. German hospital networks are consolidating procurement for these high-margin therapies.
- Biologics:Monoclonal antibodies and recombinant proteins requiring uninterrupted cold chain integrity from manufacturing release through administration. Zero-excursion tolerance drives premium logistics contracting.
- Vaccines:Large-volume 2°C to 8°C distribution with established passive packaging protocols.
- Blood Products:Plasma and cellular components with specialized handling requirements through German blood bank networks.
Biologics absorb the largest share of validated cold chain infrastructure. Specialty pharmaceuticals are climbing the fastest in revenue contribution.
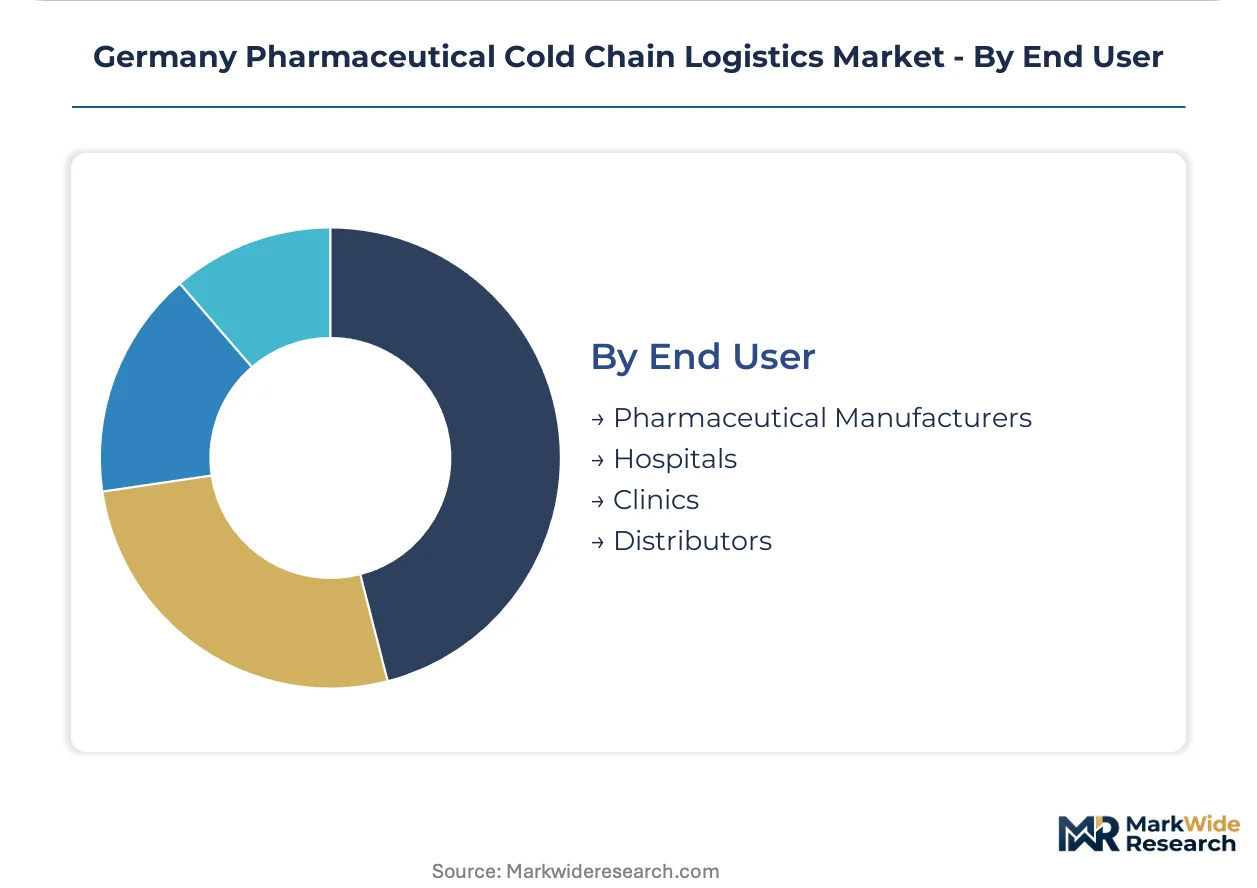
End User:
Procurement sophistication and compliance burden scale with organizational scale and regulatory exposure.
- Pharmaceutical Manufacturers:Bayer and Boehringer Ingelheim operations anchor outbound logistics demand from German production sites. These sponsors tender multi-year contracts requiring GDP certification and serialized documentation.
- Hospitals:University medical centers in North Rhine-Westphalia are absorbing community oncology infusion centers and centralizing cold chain procurement.
- Clinics:Smaller independent practices face exclusion from direct specialty pharmaceutical access as hospital networks consolidate purchasing power.
- Distributors:Wholesale operations buffer inventory and manage last-mile fragmentation to dispersed pharmacy endpoints.
Pharmaceutical Manufacturers deploy the most capital-intensive logistics specifications. Hospitals are gaining share fastest in total cold chain spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical cold chain logistics industry traces its modern lineage to post-war reconstruction of chemical and pharmaceutical manufacturing along the Rhine corridors. Bavarian biotech clusters subsequently pioneered cryogenic distribution infrastructure for emerging cell therapies. Regional specialization now concentrates validated cold storage capacity around manufacturing density patterns.
Bavaria
Munich anchors Germany's cell and gene therapy manufacturing corridor, with Bavarian biotech clusters driving demand for liquid nitrogen distribution below minus 150 degrees Celsius. BfArM enforces GDP compliance through unannounced inspections of pharmaceutical distribution sites. The Greater Munich region concentrates specialized tanker fleets and cryogenic warehousing investment.
North Rhine-Westphalia
University hospital networks in Cologne and Düsseldorf are consolidating community oncology infusion centers, centralizing cold chain procurement for temperature-sensitive biologics. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in transport cooling units. Rhine-Ruhr pharmaceutical corridors maintain the densest lane capacity for 2°C to 8°C distribution.
Baden-Württemberg
Stuttgart pharmaceutical production sites face underpenetrated cold storage capacity relative to manufacturing output. The Bundesamt für Güterverkehr coordinates road transport licensing with BfArM pharmaceutical carriage standards. Greenfield development potential exists for multi-temperature distribution centers serving southwestern manufacturing clusters.
Hesse
Rhine-Main logistics hubs connect Frankfurt airport pharmaceutical cargo terminals to continental distribution networks. EU MDR traceability mandates are creating compliant service premiums for serialized cold chain documentation. The Frankfurt-Rhine-Main metropolitan region anchors air freight integration with validated ground transport.
Lower Saxony
Hanover logistics corridors buffer inventory for northern German hospital networks and wholesale distribution. Legacy warehouse facilities require redundant cooling system upgrades to meet tightening BfArM temperature mapping standards. The region's pharmaceutical storage infrastructure is undergoing GDP-certified reconfiguration.
Germany Pharmaceutical Cold Chain Logistics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across temperature-band specialization and GDP certification depth. DHL and Kuehne + Nagel occupy consolidated positions through extensive last-mile networks and digital twin technology deployment. Three archetypes structure competition: integrated global forwarders with pharmaceutical divisions, specialized temperature-controlled couriers, and regional GDP-certified operators. Capacity expansion and strategic partnerships represent dominant competitive moves, with operators retrofitting refrigerated fleets for F-Gas Regulation compliance.
Among Germany-based specialists, Trans-o-flex (ThermoMed) exemplifies the same-day courier archetype for temperature-sensitive therapies, occupying a position where speed competes against standard freight economies. DHL represents integrated global forwarding at scale, anchoring cold chain dominance through network density. Kuehne + Nagel sits within the technology-enabled tier, with digital twin deployment exemplifying real-time thermal integrity monitoring. GDP Network Solutions GmbH and Transmed Transport GmbH occupy regional certified-operator positions, representing compliance-focused service models.
| Leading Market Players |
|---|
| Trans-o-flex (ThermoMed) |
| DHL |
| GDP Network Solutions GmbH |
| Transmed Transport GmbH |
| Kuehne + Nagel |
| DB Schenker |
| Rhenus Logistics |
| Ceva Logistics |
| Pfenning Logistics |
| Others |
Pricing and Supply Chain Analysis
Refrigerant input costs cascade through German pharmaceutical cold chain pricing tiers as EU F-Gas Regulation phase-down schedules compress margins on legacy cooling unit maintenance and accelerate capital redeployment toward lower-global-warming-potential alternatives. Bavarian biotech clusters absorb premium pricing for cryogenic distribution infrastructure while standard 2°C to 8°C lanes compete on lane density economies across Rhine-Ruhr corridors.
Pricing Analysis
Three-tier pricing structure across GDP-certified premium, qualified standard, and commodity economy levels governs German pharmaceutical logistics contracting. Premium tiers attach to active temperature control systems with real-time telemetry and excursion liability transfer, while economy tiers rely on passive thermal protection for vaccine last-mile delivery. Price differentiation hinges on BfArM certification depth and serialized documentation capability under EU MDR traceability mandates. Cost compression in standard refrigerated transport is intensifying because F-Gas retrofit cycles accelerate equipment replacement timelines. Hospital networks consolidating procurement in North Rhine-Westphalia demonstrate lowest price sensitivity; independent clinics face exclusion from specialty pharmaceutical access and highest effective cost burden.
Supply Chain Analysis
Regional distribution centers cluster around Munich biotech corridors, Rhine-Ruhr pharmaceutical manufacturing belts, and Frankfurt-Rhine-Main air freight gateways. Manufacturing concentration in Germany, Netherlands, and Switzerland feeds validated cold storage demand across Central European lanes. Liquid nitrogen supply, hydrofluorocarbon refrigerants, and qualified thermal packaging materials constitute critical input dependencies. Single-source vulnerability concentrates in specialized refrigerated vehicle body manufacturing clusters facing capacity constraints extending equipment delivery timelines. Distribution runs through hub-and-spoke configurations anchored by multi-temperature pharmaceutical distribution centers with redundant cooling systems under continuous BfArM temperature mapping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German pharmaceutical cold chain logistics functions as a geographic-arbitrage play where EU MDR traceability mandates and BfArM GDP enforcement intensity create compliant service premiums unavailable in less regulated neighboring markets. Cost differentials between certified German operators and cross-border competitors sustain margin pools for validated quality management systems.
For Market Incumbents: Hedge refrigerant transition risk by accelerating fleet retrofit cycles ahead of F-Gas Regulation phase-down deadlines and securing captive supply agreements for lower-global-warming-potential cooling systems. DHL and Kuehne + Nagel anchor positions through digital twin deployment; smaller certified operators must defend against technology-enabled displacement by investing in redundant cooling infrastructure and real-time telemetry platforms that enable outcome-based contracting with biologics manufacturers. For New Entrants and Emerging Players: Capture greenfield development potential in Baden-Württemberg where Stuttgart pharmaceutical production sites face underpenetrated cold storage capacity relative to manufacturing output. Same-day courier specialization for temperature-sensitive therapies offers penetrable white space where speed competes against standard freight economies that cannot operate. Position through GDP certification investment and partnerships with Bavarian cell therapy manufacturers seeking dedicated cryogenic lane capacity. For Investors and Strategic Acquirers: Consolidation pressure builds where BfArM unannounced inspection regimes and tightening temperature excursion reporting requirements concentrate volume toward certified operators with validated quality management systems. Long-term viability over the coming decade favors technology-enabled mid-cap specialists with digital twin capabilities and regional GDP-certified operators in underpenetrated southwestern corridors. Watch for inflection signals in electric and hydrogen-powered cold chain vehicle tendering patterns among large biologics manufacturers with net-zero commitments.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | BfArM unannounced inspections consolidate volume toward compliant operators with validated quality systems. |
| Digital Twin Deployment | Real-time thermal integrity monitoring compresses excursion response times from hours to minutes across distribution networks. |
| Refrigerant Fleet Retrofit | EU F-Gas Regulation compliance secures operational continuity as hydrofluorocarbon phase-down accelerates equipment cycles. |
| Baden-Württemberg Capacity Expansion | Greenfield multi-temperature distribution centers address Stuttgart manufacturing demand exceeding regional cold storage supply. |
| Cryogenic Lane Specialization | Liquid nitrogen distribution infrastructure below minus 150 degrees Celsius captures Bavarian cell and gene therapy pipeline expansion. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with cold chain logistics executives, pharmaceutical distribution site managers, BfArM regulatory compliance officers, and hospital procurement directors with secondary validation against EU GDP guideline documentation, BfArM inspection protocols, EU F-Gas Regulation implementation schedules, and pharmaceutical trade association capacity surveys. Bottom-up segmentation modeling and top-down macroeconomic anchoring triangulated market size estimates.
Comparable historical reference periods anchored the projection horizon to observed growth trajectories in biologics distribution and cell therapy commercialization. Segmentation dimensions spanned service type, temperature control method, product category, and end-user procurement sophistication, with regional regulatory cluster effects modeled separately. CAGRs derived from trend extrapolation adjusted for policy intervention timing and technology substitution curves, incorporating F-Gas retrofit cycle acceleration and EU MDR traceability mandate implementation as industry-specific forecast inputs.
Underlying measurement precision varies by segment; active temperature control systems and cryogenic shipping carry tighter precision than commodity passive packaging due to equipment registration and specialized tanker fleet tracking. Forecasts reflect documented assumptions about regulatory enforcement intensity and refrigerant transition timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Powder-Filled Hard Gelatin Capsules Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Global Fondaparinux Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market