
 Vascular Endothelial Growth Factor (VEGF) Inhibitors Market | 2026-2036
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market Analytics
Biosimilar formulation science is recalibrating cost structures across the VEGF inhibitor landscape. Roche sustains dominance in intravitreal delivery through its specialized manufacturing infrastructure for large-molecule biologics. Regeneron Pharmaceuticals leverages dual-target antibody engineering to differentiate its portfolio in neovascular age-related macular degeneration. Bayer anchors its position through backward integration into recombinant protein production and European distribution networks.
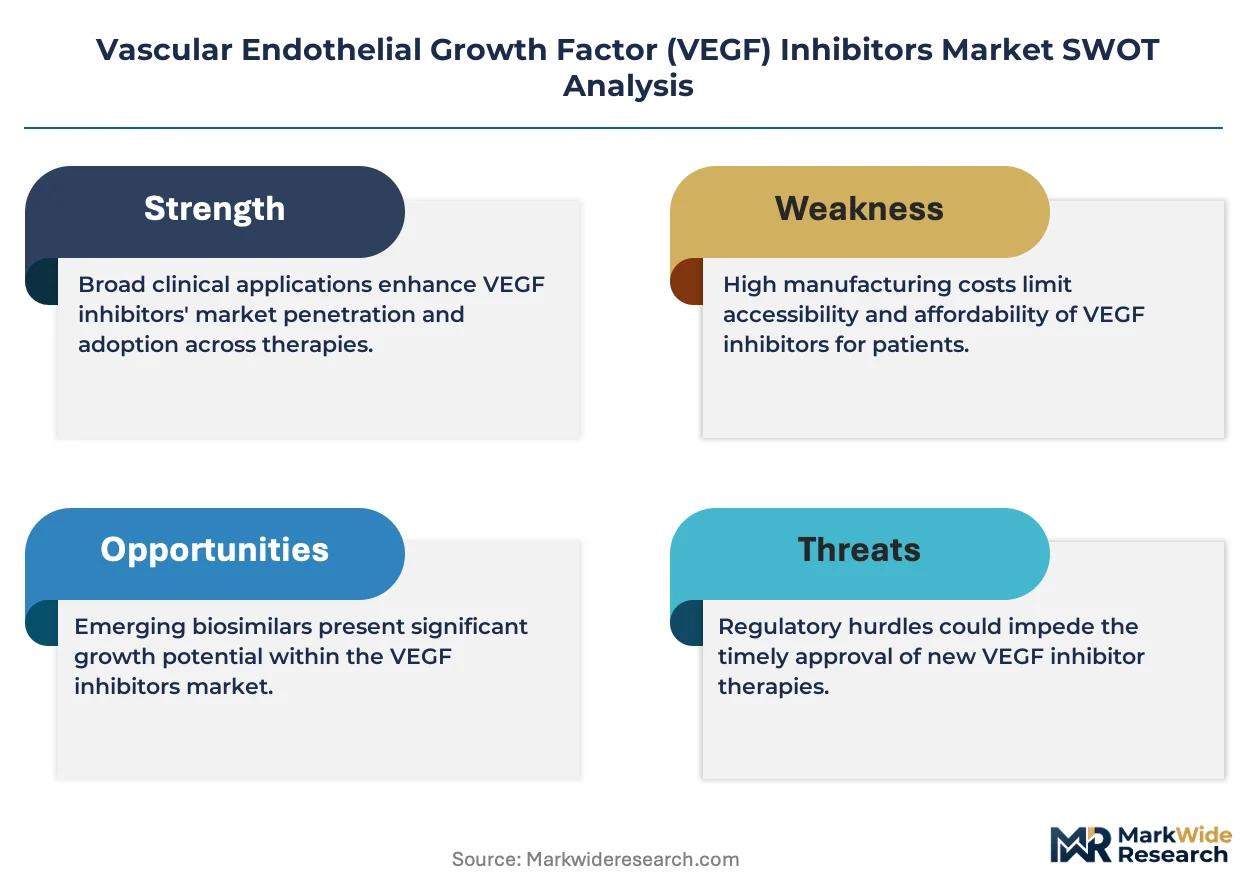
Vascular endothelial growth factor inhibitors comprise biologic and small-molecule agents that block VEGF-A signaling through receptor antagonism or ligand sequestration, typically requiring cold-chain distribution and parenteral administration at doses calibrated by indication and body surface area. Monoclonal antibodies occupy the largest revenue pool due to established intravitreal protocols in ophthalmology, while biosimilars represent the fastest-expanding category as patent cliffs for reference products open substitution pathways in Europe and North America. Small molecules retain niche positioning in oral oncology regimens where patient compliance and outpatient administration drive formulary decisions.
The FDA, EMA, and WHO set divergent standards for biosimilar interchangeability and immunogenicity monitoring that fragment market access timelines across jurisdictions. The FDA's oncology center of excellence emphasizes real-world evidence requirements for supplemental indications, while EMA's biosimilar guidelines under the EU pharmaceutical strategy accelerate competitive entry in European markets. Stakeholders must monitor evolving pharmacovigilance mandates for combination therapy safety signals as VEGF inhibitors expand into adjuvant cancer settings beyond established metastatic indications.
Market Dynamics
Patent expirations for reference biologics are compressing pricing power while accelerating biosimilar substitution pathways across oncology and ophthalmology protocols. This structural shift is redistributing margin pools from originator manufacturers to formulation specialists and contract development organizations.
Growth Catalysts
- Intravitreal injection protocols:Retinal disease management in tertiary ophthalmology centers sustains high treatment volumes through Medicare reimbursement frameworks in the United States.
- EMA biosimilar guidelines:The EU pharmaceutical strategy accelerates competitive entry timelines for interchangeable biologics across European markets.
- Real-world evidence mandates:FDA oncology center requirements for supplemental indications expand addressable patient populations in adjuvant cancer settings.
Market Restraints
- Cold-chain distribution costs:Parenteral biologics require continuous temperature-controlled logistics that inflate per-dose delivery expenses.
- Immunogenicity monitoring requirements:Divergent FDA and EMA standards for biosimilar interchangeability fragment regulatory submission timelines.
- Small-molecule oral substitutes:Tyrosine kinase inhibitors compete for outpatient oncology regimens where patient compliance favors non-injectable administration.
Strategic Opportunities
- Dual-target antibody engineering:Convergence of VEGF-A and angiopoietin-2 blockade creates differentiation potential in neovascular age-related macular degeneration.
- Indian CDSCO accelerated pathways:The country's national pharmaceutical regulator offers expedited review for biosimilars referencing approved reference products.
- Recombinant protein production integration:Captive upstream biomanufacturing capacity secures supply security and margin control for high-volume biologics.
Industry Challenges
- Pharmacovigilance signal detection:Combination therapy safety monitoring for VEGF inhibitors in adjuvant settings demands expanded post-market surveillance infrastructure.
- Large-molecule formulation expertise:Specialized manufacturing competencies for intravitreal biologics concentrate among limited contract development organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Endothelial Growth Factor (VEGF) Inhibitors Market |
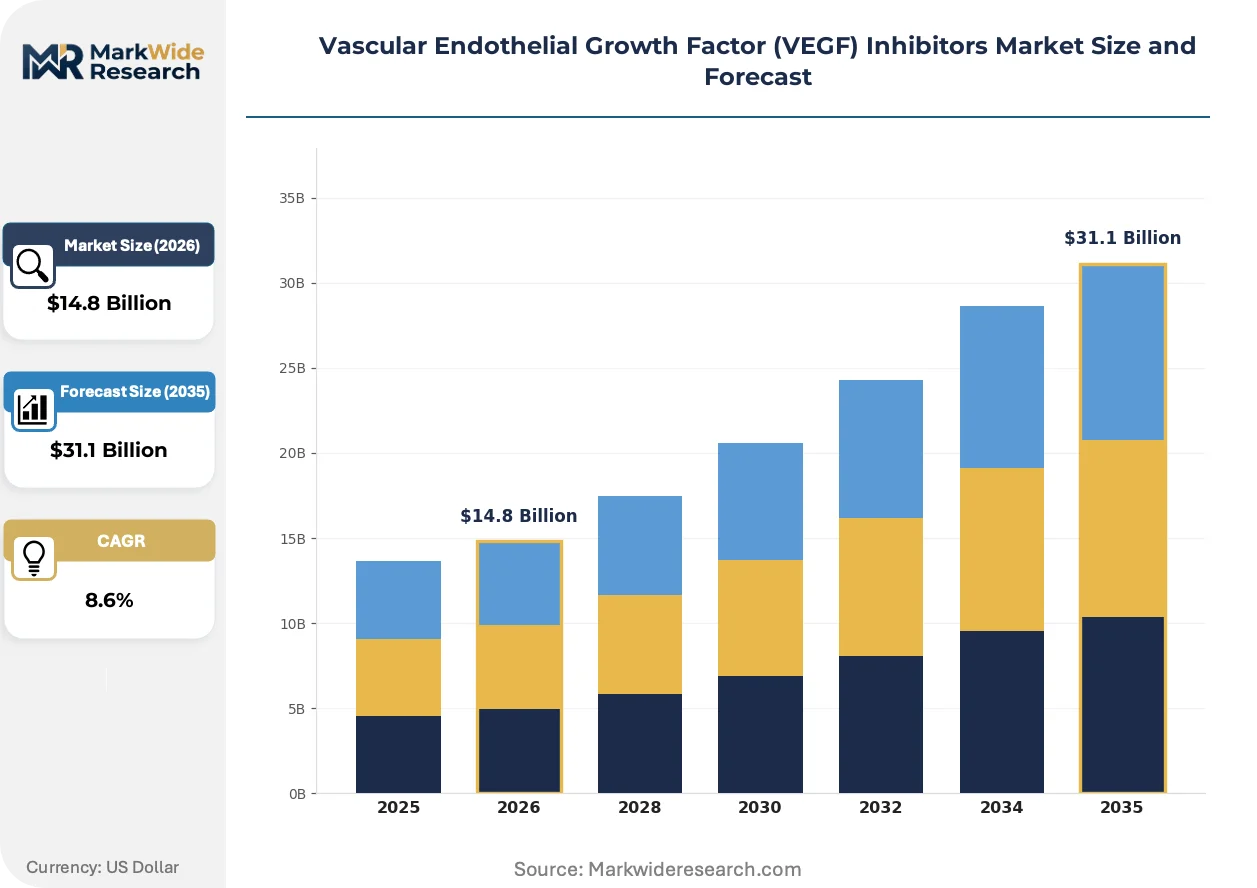
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecules, Biosimilars, Combination Therapies Indication: Ocular Diseases, Cancer, Cardiovascular Disorders, Diabetic Retinopathy Administration Route: Intravenous, Subcutaneous, Topical, Oral End User: Hospitals, Clinics, Research Laboratories, Homecare Settings |
| Companies Covered | Regeneron Pharmaceuticals Inc., Roche (F. Hoffmann-La Roche Ltd.), Bayer AG, Novartis AG, AstraZeneca, Pfizer Inc., Amgen Inc., Biogen, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market Evolving Landscape
Sustained-release drug delivery systems are compressing injection frequencies for chronic retinal diseases. These innovations promise to reshape patient adherence economics and clinic throughput models across ophthalmology practices.
Polymeric sustained-release implants are electrifying treatment paradigms by extending therapeutic intervals from monthly to quarterly or semi-annual administration. Retina specialists in academic medical centers are adopting these devices faster than community ophthalmology practices. This technology is electrifying competitive positioning for manufacturers with proprietary formulation platforms.
EMA's biosimilar interchangeability guidance under the EU pharmaceutical strategy is harmonizing substitution protocols across member states. The framework removes prescriber-consent requirements for pharmacy-level switching in several European markets. Oncology and ophthalmology segments are responding with tender-based procurement models that favor cost-competitive alternatives.
Site-of-care migration is fragmenting traditional hospital-centric distribution for intravitreal therapies. Physician office-based infusion centers and ambulatory surgery facilities are capturing volume previously concentrated in hospital outpatient departments. This shift is most visible in United States markets where Medicare reimbursement differentials favor non-hospital settings.
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market Segmentation
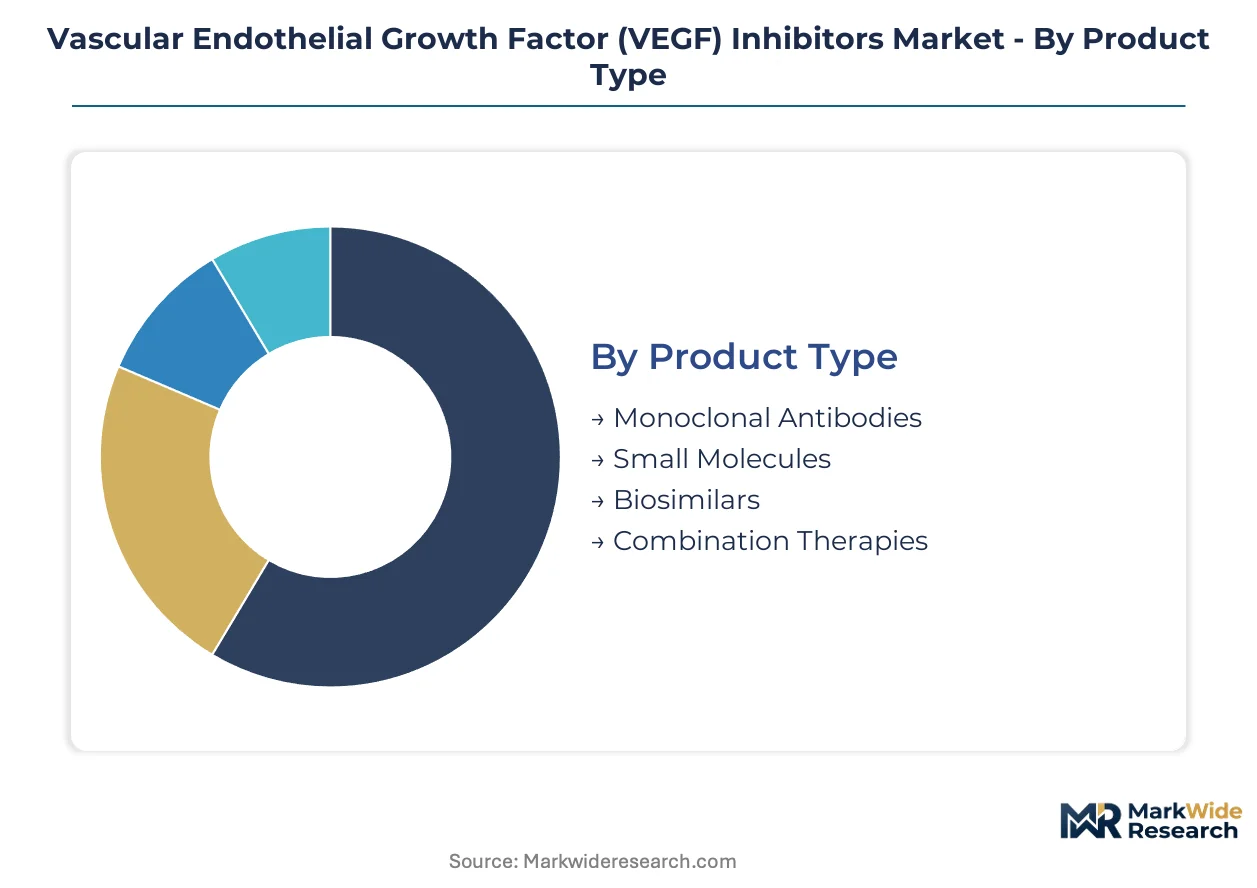
VEGF inhibitor segmentation reveals divergent regulatory pathways and margin structures across therapeutic modalities. Each category carries distinct cold-chain requirements, reimbursement codes, and manufacturing complexity that shape competitive entry barriers.
Product Type:
FDA oncology center and EMA biosimilar guidelines impose tiered approval burdens: originator biologics demand full immunogenicity packages, biosimilars require abbreviated comparability studies, small molecules follow standardized ANDA pathways.
- Monoclonal Antibodies:Large-molecule biologics targeting VEGF-A with high binding affinity and extended half-lives. Tertiary ophthalmology centers in the United States concentrate demand for intravitreal protocols under Medicare reimbursement frameworks. Cold-chain distribution and parenteral administration inflate per-dose delivery costs.
- Small Molecules:Oral tyrosine kinase inhibitors blocking VEGF receptor signaling through ATP-competitive mechanisms. Outpatient oncology regimens favor these agents where patient compliance drives formulary placement over injectable alternatives. Manufacturing scale economies compress unit costs versus biologics.
- Biosimilars:Interchangeable biologics referencing approved originator products with demonstrated analytical and clinical similarity. EMA's EU pharmaceutical strategy accelerates competitive entry timelines across European tender-based procurement markets.
- Combination Therapies:Co-formulated or sequential regimens pairing VEGF inhibition with chemotherapy or immunotherapy agents. Adjuvant cancer settings expand addressable populations under FDA real-world evidence mandates for supplemental indications.
Leading the category by volume: Monoclonal Antibodies. Expanding most quickly: Biosimilars.
Indication:
Ophthalmology and oncology applications split reimbursement pathways between physician-administered drug models and hospital outpatient prospective payment systems.
- Ocular Diseases:Neovascular age-related macular degeneration and retinal vein occlusion management through intravitreal injection protocols. United States Medicare sustains high treatment volumes in academic medical centers and community retina practices.
- Cancer:Metastatic colorectal, lung, and renal cell carcinoma first-line combination regimens. Tertiary hospital oncology departments expand protocols as FDA accelerated approval pathways compress development timelines.
- Cardiovascular Disorders:Peripheral artery disease and coronary microvascular dysfunction applications with emerging clinical evidence. Research laboratories dominate current utilization pending definitive trial outcomes.
- Diabetic Retinopathy:Proliferative and non-proliferative disease modification through anti-angiogenic intervention. Homecare settings in European markets pilot self-administration models for selected patient cohorts.
Dominant by revenue concentration: Ocular Diseases. Steepest expansion trajectory: Cancer.
Administration Route:
Route selection determines site-of-care economics and patient adherence profiles across chronic versus acute treatment paradigms.
- Intravenous:Infusion-center delivery for oncology indications requiring dose calibration by body surface area. United States site-of-care migration shifts volume from hospital outpatient departments to physician office-based infusion centers under Medicare reimbursement differentials.
- Subcutaneous:Self-administration potential for selected biologics with optimized formulation buffers. Homecare settings capture growth as patients and payors favor reduced clinic visit burden.
- Topical:Corneal neovascularization and superficial vascular anomalies with limited penetration depth. Niche positioning in specialty ophthalmology clinics with compounded formulation availability.
- Oral:Small-molecule tyrosine kinase inhibitors enabling outpatient compliance without cold-chain dependency. Clinics in India leverage CDSCO accelerated pathways for expanded access programs.
Highest procedure volume: Intravenous. Gaining share fastest: Subcutaneous.
End User:
Customer type dictates procurement scale, formulary control, and post-market surveillance infrastructure requirements.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics committees controlling high-volume biologic purchasing. Tertiary centers anchor clinical trial recruitment for novel indication expansion.
- Clinics:Retina specialty and oncology practice groups with direct buy-and-bill reimbursement exposure. United States ambulatory surgery facilities capture intravitreal injection volume through procedure-based payment structures.
- Research Laboratories:Academic medical centers and contract research organizations conducting pharmacokinetic and combination therapy safety studies. Expanded post-market surveillance infrastructure demands intensify with adjuvant setting expansion.
- Homecare Settings:Self-administration models for subcutaneous biologics and oral small molecules. Patient adherence economics reshape clinic throughput models as sustained-release formulations extend therapeutic intervals.
Leading by absolute spend: Hospitals. Climbing the fastest: Homecare Settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Medicare reimbursement frameworks sustain the highest intravitreal injection volumes worldwide. Tertiary ophthalmology centers and hospital outpatient departments anchor demand concentration. Cold-chain distribution networks radiate from Indianapolis, Memphis, and Louisville logistics clusters.
United States
Medicare Part B physician-administered drug reimbursement sustains high treatment volumes in neovascular age-related macular degeneration. FDA accelerated approval pathways for oncology biologics compress development timelines for metastatic colorectal cancer protocols. Retina specialists in academic medical centers across the Northeast Corridor adopt sustained-release implant technologies faster than community practices.
Germany
EMA biosimilar interchangeability guidance under the EU pharmaceutical strategy accelerates competitive entry timelines. Tender-based procurement models in statutory health insurance favor cost-competitive alternatives to originator biologics. The Rhine-Main biotech cluster around Frankfurt anchors recombinant protein production capacity for European distribution.
Japan
PMDA regulatory frameworks emphasize real-world evidence requirements for supplemental oncology indications. Aging demographics expand addressable patient populations in diabetic retinopathy and wet age-related macular degeneration. The Kanto region surrounding Tokyo concentrates intravitreal injection protocols in university hospital ophthalmology departments.
India
CDSCO accelerated approval pathways for biosimilars referencing approved reference products attract formulation specialists. Outpatient oncology regimens favor oral small-molecule tyrosine kinase inhibitors where patient compliance drives formulary decisions. The Hyderabad-Visakhapatnam pharmaceutical corridor expands recombinant protein manufacturing capacity for export markets.
Switzerland
Swissmedic regulatory standards align with EMA guidelines while offering expedited review for breakthrough-designated biologics. Specialized manufacturing competencies for large-molecule intravitreal formulations concentrate in the Basel biotech cluster. Captive upstream biomanufacturing capacity secures supply security for high-volume ophthalmology products.
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator biologics defending premium positioning in intravitreal ophthalmology while biosimilar specialists capture oncology volume through tender-based procurement. The market structure concentrates manufacturing expertise among limited contract development organizations with large-molecule formulation capabilities. Three archetypes dominate: integrated biopharma conglomerates with captive production, mid-cap antibody engineering specialists, and emerging biosimilar pure-plays. Competitive dynamics center on backward integration into recombinant protein production and dual-target antibody engineering differentiation.
Among integrated biopharma conglomerates, Roche and Novartis occupy positions exemplifying captive manufacturing scale and specialized distribution infrastructure. Regeneron Pharmaceuticals sits within the antibody engineering specialist tier, representing dual-target VEGF-A and angiopoietin-2 blockade approaches. These three companies anchor the competitive landscape through distinct strategic postures rather than overlapping capability sets.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals Inc. |
| Roche (F. Hoffmann-La Roche Ltd.) |
| Bayer AG |
| Novartis AG |
| AstraZeneca |
| Pfizer Inc. |
| Amgen Inc. |
| Biogen |
| Eli Lilly and Company |
| Others |
Value Network & Pricing Analysis
Tender-based procurement models in European statutory health insurance systems are compressing originator margins and forcing supply chain reconfiguration toward lower-cost manufacturing geographies. This buyer consolidation dynamic accelerates biosimilar substitution while redistributing formulation expertise to contract development organizations with captive biomanufacturing capacity.
Pricing Analysis
High-volume intravitreal protocols in United States Medicare programs sustain premium pricing for originator monoclonal antibodies, while oncology biosimilars compete on unit cost in tender-based European markets. Price differentiation rests on regulatory exclusivity duration and cold-chain reliability certification rather than clinical efficacy differentiation. Cost compression in oncology segments intensifies as interchangeable biologics capture hospital formulary placements. Community ophthalmology practices exhibit highest price sensitivity due to buy-and-bill reimbursement exposure, whereas academic medical centers prioritize sustained-release formulation access over per-dose economics.
Supply Chain Analysis
Specialized workforce pools in Basel, Frankfurt, and Hyderabad anchor recombinant protein production and large-molecule formulation capacity for intravitreal biologics. Upstream bioprocessing draws from Chinese-sourced cell culture media, German-engineered single-use bioreactor systems, and Indian-trained process development specialists. Single-source vulnerability concentrates in proprietary sustained-release polymer platforms controlled by limited contract manufacturers. Distribution runs through temperature-controlled logistics networks radiating from Indianapolis, Memphis, and Louisville cold-chain hubs to tertiary ophthalmology centers and hospital outpatient departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patent cliff compression and biosimilar interchangeability mandates are consolidating competitive positions around backward-integrated manufacturers with captive bioproduction assets. Weaker formulation specialists without upstream control face margin erosion and acquisition pressure.
For Market Incumbents: Hedge biosimilar substitution risk by securing captive recombinant protein production in the Hyderabad-Visakhapatnam corridor and accelerating dual-target antibody engineering programs for neovascular age-related macular degeneration differentiation. Prioritize EMA interchangeability certification to defend European tender positioning against emerging pure-play biosimilar entrants. For New Entrants and Emerging Players: Launch via physician office-based infusion center partnerships in United States markets where Medicare reimbursement differentials favor non-hospital site-of-care migration. Target subcutaneous self-administration formulations for diabetic retinopathy homecare settings in European pilot markets, leveraging CDSCO accelerated pathways for analytical comparability studies referencing approved reference products. For Investors and Strategic Acquirers: The window for entry favors mid-cap antibody engineering specialists with proprietary sustained-release platforms and established EMA regulatory relationships. Long-term viability hinges on convergence toward combination therapy safety data packages for adjuvant oncology indications. Watch FDA real-world evidence mandate expansion as the signal for portfolio valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Target Antibody Engineering | Regeneron's VEGF-A and angiopoietin-2 blockade creates differentiation in neovascular AMD protocols. |
| Backward Integration into Recombinant Protein Production | Roche's captive biomanufacturing secures supply security and margin control for high-volume ophthalmology products. |
| Sustained-Release Implant Development | Polymeric formulation platforms compress injection frequencies and reshape clinic throughput economics. |
| EMA Interchangeability Certification | Biosimilar specialists accelerate European tender capture through pharmacy-level substitution protocols. |
| Site-of-Care Migration Partnerships | Ambulatory surgery facilities capture intravitreal volume through Medicare reimbursement differentials favoring non-hospital settings. |
Research Methodology
Document review covered FDA oncology center guidance documents, EMA biosimilar interchangeability frameworks, and ClinicalTrials.gov registration data, complemented by interviews with formulary directors at integrated delivery networks, regulatory affairs leads at biopharma conglomerates, and procurement managers at hospital outpatient departments. Secondary validation drew from CMS Medicare reimbursement databases, EU pharmaceutical strategy implementation reports, and SEC 10-K filings for listed biopharma entities. Bottom-up patient volume modeling and top-down revenue triangulation anchored market size estimation across the analysis window.
Segmentation outputs reflect treatment line stratification, administration route economics, and regional regulatory cluster differentiation modeled throughout the projection horizon. CAGRs were derived from patent expiration timelines, biosimilar entry assumptions, and indication expansion trajectories in adjuvant cancer settings. Forecast inputs incorporated cold-chain distribution cost inflation, sustained-release adoption curves in academic medical centers, and tender-based procurement penetration in European statutory health insurance systems.
Regulatory approval delays, biosimilar immunogenicity signal detection, and combination therapy safety monitoring infrastructure expansion are the dominant revision risks to modeled projections. Forecasts reflect documented assumptions regarding interchangeability guideline harmonization and site-of-care migration velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Netupitant-Palonosetron FDC Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Cortisone Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Plasma Protein Therapeutics Market
Pharmaceuticals
Alirocumab Market
Pharmaceuticals
Soft Capsules Drugs CMO Market