
 Rosuvastatin Market | 2026-2036
Rosuvastatin Market Size, Share, and Industry Trends Forecast 2026-2036
Rosuvastatin Market Outlook
US FDA bioequivalence certification under the ANDA pathway is rotating competitive advantage toward manufacturers with proven dissolution profiles and stable supply chains. AstraZeneca leverages its original formulation expertise and brand recognition in developed markets. Sun Pharmaceuticals anchors its position through backward integration into active pharmaceutical ingredient production. Teva Pharmaceutical Industries competes across multiple dosage strengths with established distribution networks.
Rosuvastatin is a synthetic hydroxymethylglutaryl-coenzyme A reductase inhibitor with a molecular weight of 481.5 g/mol, formulated as calcium salt for oral administration to reduce low-density lipoprotein cholesterol and triglyceride levels in patients with hyperlipidemia. Tablet formulations dominate volume due to patient familiarity and reimbursement alignment, while cardiovascular therapy areas capture the largest share of prescribing activity. Homecare and pharmacy end-user segments are expanding as chronic disease management shifts away from acute hospital settings.
US FDA, EMA, and India's CDSCO enforce varying bioequivalence and good manufacturing practice standards that determine which manufacturers gain market access in each geography. These regulatory frameworks create tiered entry barriers where facilities meeting multiple jurisdictional requirements capture disproportionate contract volumes. Stakeholders must monitor evolving pharmacovigilance reporting obligations and local content requirements that could reroute sourcing decisions across major supply corridors.
Market Dynamics
FDA bioequivalence certification under the ANDA pathway is concentrating competitive advantage among manufacturers with validated dissolution profiles and multi-jurisdictional GMP compliance, reshaping how generic entrants capture contract volumes.
Growth Catalysts
- Preventive cardiology protocols:Hospital systems in the United States, India, and China are expanding statin regimens for early cardiovascular intervention, driving volume prescriptions into outpatient settings.
- EMA bioequivalence harmonization:Streamlined generic approval pathways across European member states are accelerating manufacturer entry and expanding patient access to lower-cost formulations.
- Active pharmaceutical ingredient backward integration:Producers with captive supply of rosuvastatin calcium salt intermediates are securing cost advantages and supply continuity against raw material volatility.
Market Restraints
- Atorvastatin substitution pressure:Clinicians in cost-sensitive markets are switching patients to generic atorvastatin where lipid targets are achieved, compressing rosuvastatin volume in primary prevention.
- Indian API supply concentration:Dependence on Hyderabad and Ahmedabad manufacturing clusters for key intermediates creates vulnerability to localized environmental compliance shutdowns or logistics disruptions.
- FDA dissolution specification tightening:Enhanced bioequivalence testing requirements for modified-release formulations are extending ANDA approval timelines and raising development costs for new entrants.
Strategic Opportunities
- Fixed-dose combination expansion:Pairing rosuvastatin with ezetimibe or antihypertensive agents addresses polypharmacy adherence gaps in aging populations across Japan and Western Europe.
- Homecare channel penetration:Direct-to-patient pharmacy models and chronic disease management platforms are capturing refill volumes previously routed through hospital outpatient departments.
- India CDSCO local manufacturing incentives:Production-linked incentive schemes for pharmaceutical ingredients are attracting greenfield API investments that could rebalance supply geography.
Industry Challenges
- Pharmacovigilance reporting scale-up:Post-market surveillance obligations under EMA and FDA frameworks require dedicated safety databases that strain mid-tier generic houses.
- Multi-jurisdictional GMP audit complexity:Facilities must simultaneously satisfy FDA, EMA, and CDSCO inspection standards to capture cross-border contract manufacturing, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rosuvastatin Market |
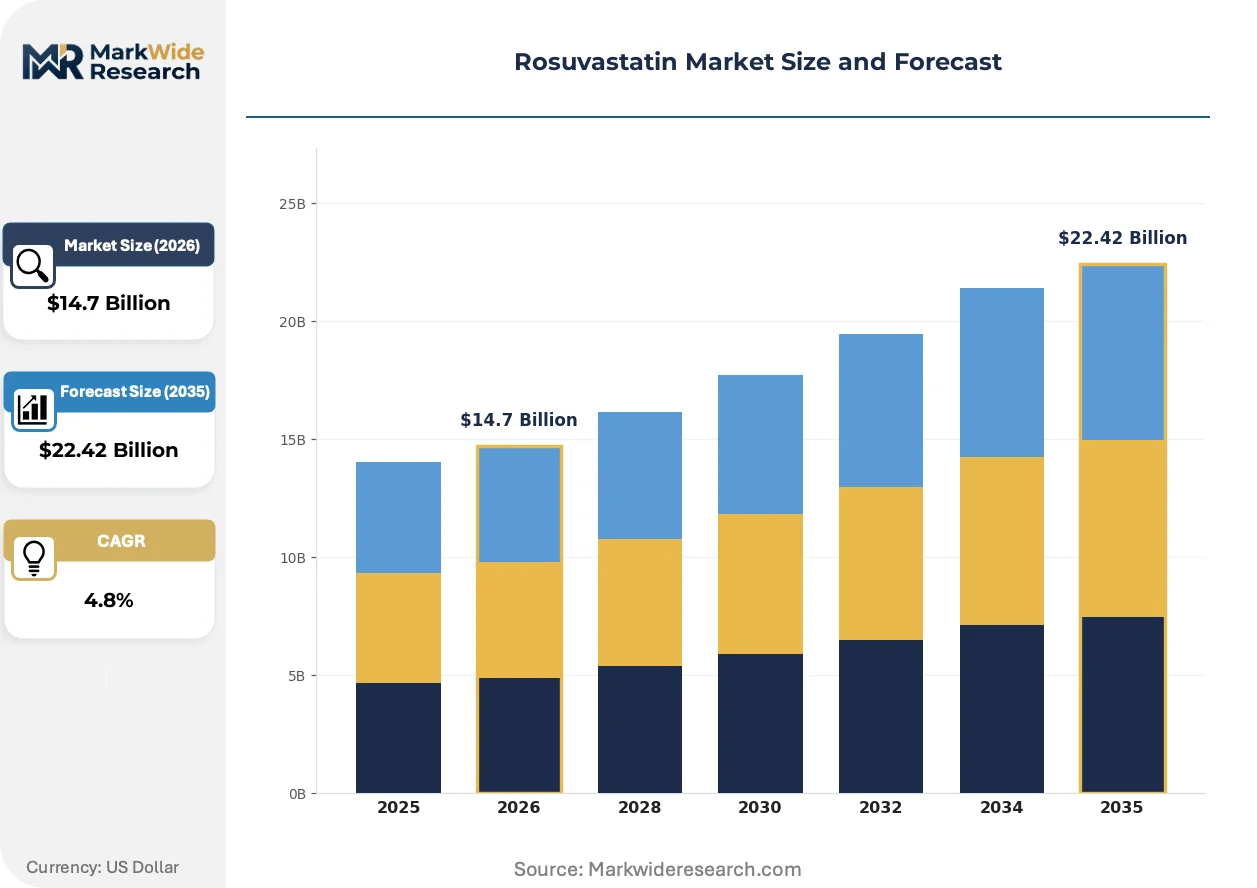
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Oral Suspension, Injectables Therapy Area: Cardiovascular, Dyslipidemia, Hypertension, Metabolic Disorders End User: Hospitals, Clinics, Pharmacies, Homecare Distribution Channel: Retail, Wholesale, Online, Direct to Consumer |
| Companies Covered | Cadila Pharmaceuticals, CTX Life Sciences, AstraZeneca, Sun Pharmaceuticals, HEC Pharm, Teva Pharmaceutical Industries, Lunan Pharmaceutical, Biocon Ltd., MSN Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rosuvastatin Market Strategic Shifts
Continuous manufacturing technologies and real-time release testing are compressing batch cycle times while regulatory data integrity requirements are forcing facility upgrades across the supplier base.
Continuous direct compression technology is bifurcating the tablet manufacturing landscape. Facilities in Ireland and Singapore are adopting integrated powder-to-tablet lines that reduce processing steps from seven to three. This compression is enabling 40% throughput gains while collapsing quality control hold times, allowing adopters to bid aggressively on tender volumes.
EMA's updated guideline on quality equivalence for generic medicinal products is tightening dissolution profile matching requirements. Manufacturers must now demonstrate statistical equivalence across multiple media pH conditions rather than single-point testing. High-strength rosuvastatin formulations face the steepest compliance burden, with several ANDA resubmissions pending additional biostudy data.
Hospital procurement consortia are consolidating formulary decisions into centralized pharmacy and therapeutics committees. Independent community pharmacies are losing direct prescriber influence as integrated delivery networks in the United States negotiate exclusive distribution agreements with single-source generic suppliers, compressing available channels for non-aligned manufacturers.
Rosuvastatin Market Segmentation
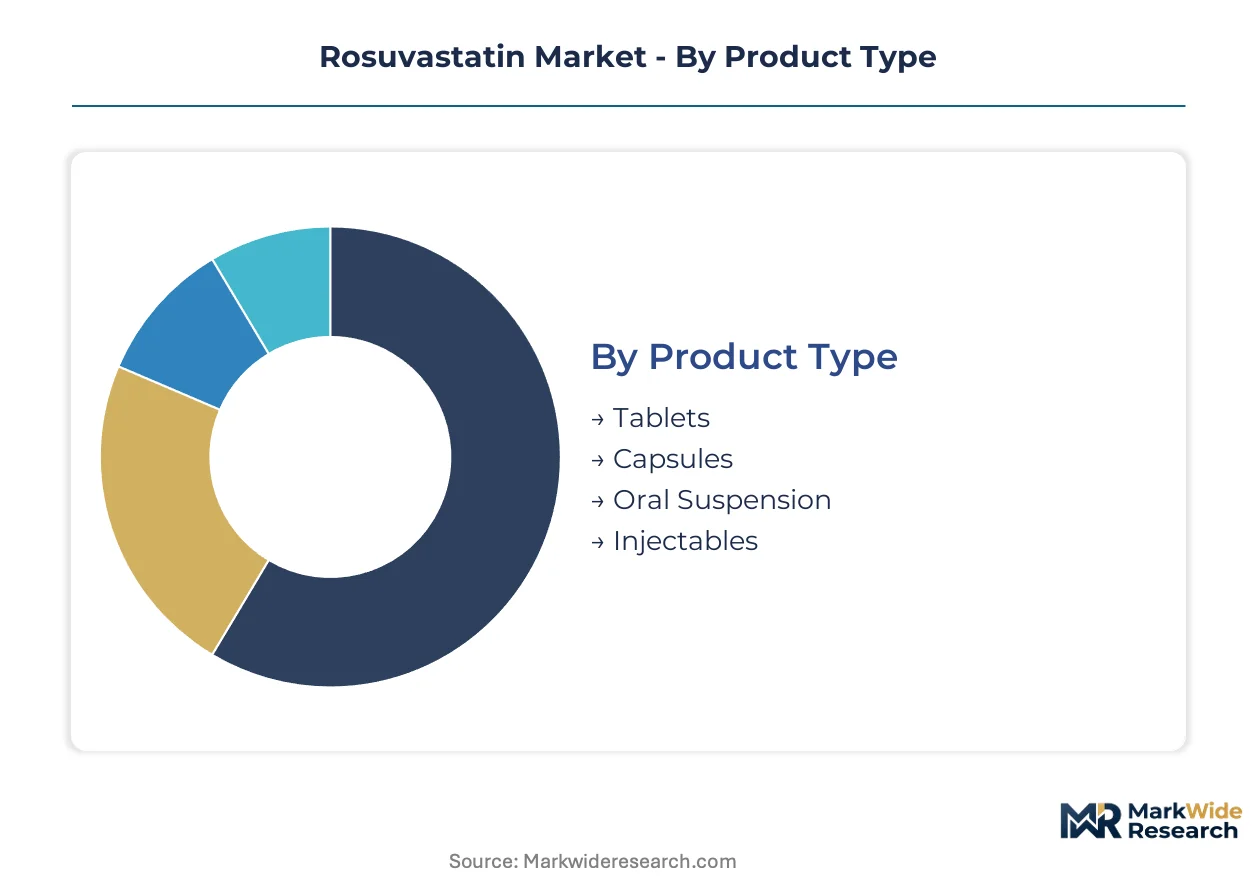
Rosuvastatin prescribing patterns fragment across dosage forms, clinical settings, and procurement channels. Each segment carries distinct reimbursement codes, supply chain requirements, and patient adherence profiles that reshape manufacturer go-to-market priorities.
Product Type:
Tablet formulations flow through retail pharmacy and hospital outpatient channels, while oral suspension concentrates in pediatric and geriatric homecare settings where swallowing difficulties drive formulation choice.
- Tablets:Calcium salt formulations in 5mg, 10mg, 20mg, and 40mg strengths dominate outpatient prescribing. Hospital formularies in the United States and India standardize on 10mg and 20mg strengths for primary prevention protocols, with 40mg reserved for high-risk secondary prevention cases.
- Capsules:Modified-release capsule formats address patient cohorts reporting myalgia with immediate-release tablets. EMA markets show stronger capsule uptake where pharmacovigilance databases track muscle-related adverse events more systematically.
- Oral Suspension:Liquid formulations serve pediatric dyslipidemia cases and elderly patients with dysphagia. Compounding pharmacies in Germany and the United Kingdom produce suspension variants where commercial supply remains limited.
- Injectables:Intravenous statin formulations remain investigational for acute coronary syndrome settings. Clinical trial supply chains in Japan and the United States currently represent the sole addressable demand.
By volume, tablets lead. By growth pace, oral suspension is ahead.
Therapy Area:
Cost tier differentiation separates acute cardiovascular intervention from chronic metabolic management, with reimbursement intensity varying threefold across these clinical applications.
- Cardiovascular:Post-myocardial infarction and stroke prevention protocols drive the largest prescription volumes. American College of Cardiology guidelines mandate high-intensity statin therapy for secondary prevention, anchoring demand in United States hospital systems.
- Dyslipidemia:Primary hypercholesterolemia management captures the broadest patient population. Generic substitution pressures intensify in this segment as payers prioritize atorvastatin for patients achieving lipid targets on lower-efficacy regimens.
- Hypertension:Fixed-dose combinations with antihypertensive agents address comorbid cardiovascular risk. Japan's Ministry of Health, Labour and Welfare reimbursement list favors combination products for elderly polypharmacy reduction.
- Metabolic Disorders:Diabetic dyslipidemia and non-alcoholic fatty liver disease represent emerging off-label prescribing. Endocrinology practices in China and India are expanding statin use for metabolic syndrome management.
Cardiovascular applications command premium pricing. Metabolic disorders show the steepest expansion trajectory.
End User:
Customer type determines procurement modality, with hospitals negotiating tender contracts while homecare channels rely on retail reimbursement and direct patient payment.
- Hospitals:Integrated delivery networks in the United States consolidate purchasing through pharmacy and therapeutics committees. Tender volumes concentrate in cardiology and emergency medicine departments with protocol-driven prescribing.
- Clinics:Outpatient cardiology and primary care practices generate refill prescriptions. India's urban clinic networks in Mumbai and Delhi drive volume through physician-brand relationships.
- Pharmacies:Community and hospital outpatient pharmacies handle the majority of dispensed tablets. China's retail pharmacy chains are capturing share from hospital outpatient departments under drug markup reform policies.
- Homecare:Direct-to-patient delivery models serve chronic disease management programs. Western European markets show stronger homecare penetration where long-term care insurance covers medication management services.
Pharmacies move the most units. Homecare is climbing the fastest.
Distribution Channel:
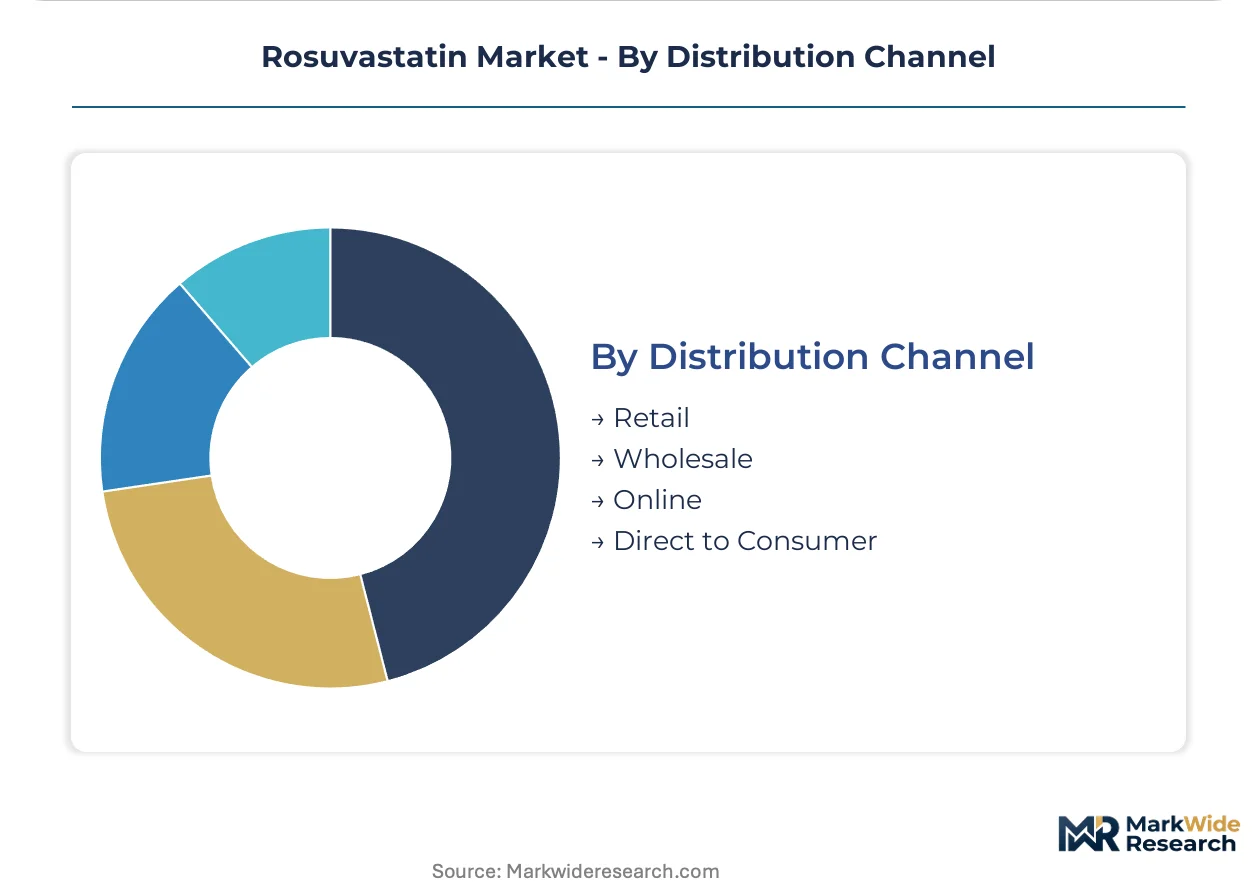
Supply concentration varies by channel maturity, with wholesale networks dominating emerging markets while direct contracting reshapes developed market access.
- Retail:Brick-and-mortar pharmacies handle prescription fulfillment and generic substitution. United States retail chains negotiate rebate structures with manufacturers based on volume tiers.
- Wholesale:Distributors manage inventory and logistics for hospital and pharmacy networks. India's wholesale channel concentrates in Ahmedabad and Hyderabad distribution hubs serving domestic and export markets.
- Online:E-pharmacy platforms capture refill prescriptions and chronic disease management subscriptions. China's Alibaba Health and JD Health platforms are expanding into prescription drug delivery under NMPA e-commerce guidelines.
- Direct to Consumer:Manufacturer-direct programs bypass traditional distribution for cash-pay patients. Telehealth platforms in the United States are integrating statin prescribing with direct fulfillment.
Wholesale channels carry the volume base. Online distribution is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes for pharmaceutical ingredients are redirecting manufacturing investments across major supply corridors. CDSCO local manufacturing mandates and FDA bioequivalence certification create divergent entry pathways that reshape competitive positioning in each geography.
United States
Hospital outpatient departments and integrated delivery networks drive statin prescribing volumes through protocol-driven cardiovascular programs. FDA ANDA pathway requirements for dissolution profile validation extend approval timelines for new generic entrants. New Jersey and North Carolina manufacturing clusters host facilities with multi-jurisdictional GMP compliance serving domestic hospital procurement consortia.
India
Hyderabad and Ahmedabad API manufacturing clusters supply key rosuvastatin calcium salt intermediates to domestic formulation units and export markets. CDSCO production-linked incentive schemes for pharmaceutical ingredients attract greenfield investments that rebalance supply geography away from concentrated coastal zones. Maharashtra and Gujarat formulation facilities capture tender volumes through backward integration into active pharmaceutical ingredient production.
China
NMPA drug markup reform policies shift dispensing volumes from hospital outpatient departments to retail pharmacy chains and e-pharmacy platforms. Yangtze River Delta manufacturing bases produce rosuvastatin calcium salt for domestic consumption and contract export supply. Zhejiang and Jiangsu province facilities face intensifying environmental compliance inspections that intermittently disrupt intermediate production schedules.
Germany
EMA quality equivalence guidelines for generic medicinal products mandate statistical dissolution profile matching across multiple media pH conditions. Compounding pharmacies in Bavaria and North Rhine-Westphalia manufacture suspension variants for pediatric and geriatric populations where commercial liquid supply remains limited. German hospital pharmacy and therapeutics committees consolidate formulary decisions into centralized procurement frameworks.
Japan
PMDA reimbursement lists favor fixed-dose combination products combining rosuvastatin with antihypertensive agents for elderly polypharmacy reduction. Kansai and Kanto region medical institutions anchor demand through preventive cardiology protocols targeting metabolic syndrome management. Osaka and Tokyo-based distributors manage inventory for hospital networks with protocol-driven high-intensity statin prescribing for secondary cardiovascular prevention.
Rosuvastatin Market Competitive Environment
Player mix skews toward vertically integrated generic manufacturers with captive API supply and originator-brand incumbents with formulation expertise. Market structure concentrates contract volumes among facilities holding simultaneous FDA, EMA, and CDSCO GMP certifications. Three archetypes dominate: backward-integrated Indian API-to-formulation houses, multi-jurisdictional generic specialists with dissolution validation capabilities, and originator-brand holders leveraging clinical trial data for premium positioning. Competitive moves center on capacity expansion in CDSCO incentive zones and strategic partnerships for fixed-dose combination development.
Within the backward-integrated tier, Sun Pharmaceuticals and MSN Laboratories represent manufacturers with captive rosuvastatin calcium salt production securing supply continuity against raw material volatility. AstraZeneca occupies the originator-brand position, anchoring premium-tier demand in developed markets through original formulation expertise. Teva Pharmaceutical Industries sits within the multi-jurisdictional generic specialist archetype, competing across dosage strengths with established distribution networks meeting FDA bioequivalence standards.
| Leading Market Players |
|---|
| Cadila Pharmaceuticals |
| CTX Life Sciences |
| AstraZeneca |
| Sun Pharmaceuticals |
| HEC Pharm |
| Teva Pharmaceutical Industries |
| Lunan Pharmaceutical |
| Biocon Ltd. |
| MSN Laboratories |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Indian API manufacturers and United States generic formulation houses lock in rosuvastatin calcium salt supply visibility while capping price volatility against raw material swings. These arrangements tether Hyderabad and Ahmedabad production clusters to hospital procurement consortia through multi-year volume commitments.
Pricing Analysis
Cost-plus contracts indexed to acetone and pyridine derivative spot markets govern rosuvastatin calcium salt transactions. Three-tier pricing structure across originator-brand, FDA-certified generic, and non-certified economy suppliers separates tiers by bioequivalence validation status and GMP certification breadth. Cost compression in the economy tier is intensifying because CDSCO production-linked incentives expand domestic Indian capacity. Hospital procurement committees exhibit lowest price sensitivity due to protocol-mandated high-intensity statin prescribing, while retail pharmacy substitution drives maximum pressure on generic tablet margins.
Supply Chain Analysis
Environmental compliance inspections at Zhejiang and Jiangsu province intermediates plants create chokepoints that intermittently constrain global rosuvastatin calcium salt flow. Active pharmaceutical ingredient production concentrates in India, China, and Ireland, drawing from fermentation-derived starting materials and synthetic organic chemistry inputs. Single-source vulnerability characterizes the supply architecture due to concentrated Hyderabad and Ahmedabad manufacturing clusters. Distribution runs through wholesale networks anchored in Ahmedabad and North Carolina distribution hubs serving hospital and retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rosuvastatin market expansion qualifies as high-growth disruption justified by EMA quality equivalence guideline tightening that accelerates manufacturer consolidation around validated dissolution capabilities.
For Market Incumbents: Shield formulation market share by deepening backward integration into rosuvastatin calcium salt API production and securing simultaneous FDA-EMA-CDSCO GMP certifications. Atorvastatin substitution pressure in primary prevention segments threatens volume retention, making captive intermediate supply the priority defensive lever.
For New Entrants and Emerging Players: Differentiate on fixed-dose combination development pairing rosuvastatin with ezetimibe or antihypertensive agents. Oral suspension formulations for pediatric and geriatric dysphagia patients in Germany and the United Kingdom represent the most penetrable white-space segment. Pursue direct-to-patient pharmacy partnerships for chronic disease management platform integration.
For Investors and Strategic Acquirers: Multi-jurisdictional generic specialists with validated dissolution profiles and established hospital procurement relationships represent the optimal acquisition target archetype. Long-term viability over the next decade hinges on continuous manufacturing technology adoption and real-time release testing capabilities. Monitor EMA biostudy resubmission volumes for high-strength formulations as the signal indicating regulatory barrier elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Captive rosuvastatin calcium salt supply insulates against Hyderabad cluster disruption and raw material volatility. |
| Fixed-Dose Combination Development | Ezetimibe-rosuvastatin pairings address polypharmacy adherence gaps in Japan's aging patient population. |
| Continuous Manufacturing Adoption | Integrated powder-to-tablet lines in Ireland and Singapore compress batch cycle times by 40 percent. |
| Multi-Jurisdictional GMP Certification | Simultaneous FDA, EMA, and CDSCO compliance unlocks cross-border contract manufacturing volumes. |
| Homecare Channel Penetration | Direct-to-patient pharmacy models capture refill volumes shifting from hospital outpatient departments. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads, formulary directors at United States hospital systems, API procurement managers at Indian formulation houses, and CDSCO compliance officers; alongside secondary validation through FDA ANDA filings, EMA quality equivalence guidelines, ClinicalTrials.gov rosuvastatin protocol records, and Indian pharmaceutical export customs data. Bottom-up prescription volume modeling and top-down market sizing triangulated against manufacturer capacity disclosures.
Across the analysis window, the analytical framework segmented by dosage form, therapy area, end-user channel, and regional regulatory cluster. CAGRs derived from prescription volume trajectories, pricing trend extrapolation, and capacity expansion announcements. Forecast inputs incorporated EMA dissolution specification evolution, CDSCO production-linked incentive uptake rates, and United States hospital procurement consolidation patterns.
Material uncertainties — FDA bioequivalence testing requirement changes, environmental compliance shutdowns at Chinese intermediate plants, atorvastatin substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and supply chain continuity. Practitioners should keep alternative scenarios live as EMA pharmacovigilance reporting obligations and Indian local manufacturing incentives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Global Narcolepsy Drugs Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Advanced Therapy Medicinal Products CDMO Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Marburg Virus Disease Therapeutics Market