
 Emedastine Difumarate Market | 2026-2036
Emedastine Difumarate Market Size, Share, and Industry Trends Forecast 2026-2036
Emedastine Difumarate Market Insights
A shortage of specialized ophthalmic formulation chemists is unwinding production capacity across generic API manufacturers. Bausch + Lomb leverages its vertically integrated eye care platform to sustain raw material throughput for difumarate salt production. Alcon AG anchors premium positioning through controlled-release ophthalmic delivery systems. Jiudian Pharmaceutical competes on cost-optimized synthesis routes for active pharmaceutical ingredient supply.
Emedastine difumarate is a histamine H1 receptor antagonist formulated as the difumarate salt of emedastine, typically administered as 0.05% ophthalmic solution for topical ocular application to relieve allergic conjunctivitis symptoms through mast cell stabilization and competitive histamine blockade. Eye drops dominate current volume flows due to immediate symptom relief and established reimbursement codes, while tablet formulations capture expanding share in systemic allergy management protocols where oral antihistamine convenience matters. The therapy area segmentation shows allergic conjunctivitis maintaining the largest addressable patient base, with allergic rhinitis representing the fastest-growing indication as combination therapy protocols gain physician acceptance.
FDA ophthalmic guidance documents and NMPA generic equivalence standards shape formulation development timelines and bioavailability benchmarks for new market entrants. Japan's PMDA enforces stringent stability testing for multi-dose preservative systems, directly influencing packaging technology investments by Shiratori Pharmaceutical and Daito Pharmaceutical. Stakeholders must monitor evolving pharmacopeial monograph revisions for difumarate salt purity specifications, as these will determine which manufacturers retain active supplier qualifications without reformulation costs.
Market Dynamics
Specialized formulation chemist scarcity is compressing generic API production capacity while NMPA pathway streamlining accelerates domestic Chinese manufacturer entry, creating a supply-demand asymmetry that rewards vertically integrated ophthalmic specialists with captive synthesis capabilities.
Growth Catalysts
- Allergic Conjunctivitis Prevalence:East Asian metropolitan hospital networks are expanding chronic allergy management protocols for aging populations, driving prescription volume expansion for topical antihistamine therapies.
- NMPA Generic Equivalence Standards:China's streamlined approval pathways for ophthalmic formulations reduce time-to-market for domestic manufacturers, accelerating competitive supply expansion.
- Combination Therapy Protocols:Physician acceptance of systemic-plus-topical allergy regimens is broadening emedastine difumarate addressability beyond ocular applications into allergic rhinitis management.
Market Restraints
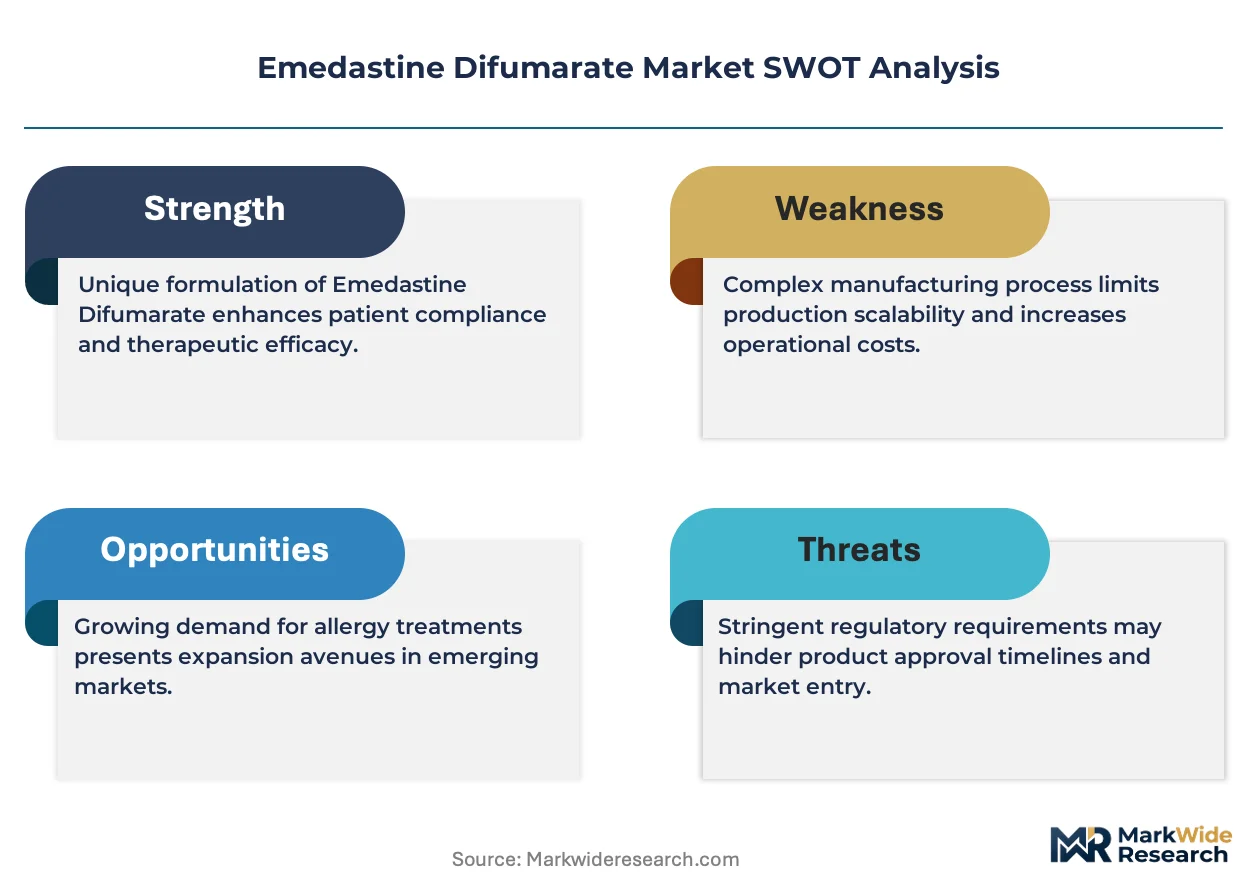
- Formulation Chemist Scarcity:The specialized talent pool for ophthalmic salt synthesis is concentrated among legacy API manufacturers, creating production bottlenecks for new entrants.
- PMDA Stability Requirements:Japan's stringent multi-dose preservative testing mandates force packaging technology investments that elevate fixed costs for regional suppliers.
- Oral Antihistamine Substitution:Second-generation systemic H1 antagonists with once-daily dosing convenience capture patient preference in mild-to-moderate allergy cases.
Strategic Opportunities
- Rural China Penetration:County-level hospital networks in China's interior provinces remain underpenetrated for prescription ophthalmic therapies, offering volume expansion potential for cost-optimized suppliers.
- Controlled-Release Delivery Convergence:Integration of polymer matrix technology with difumarate salt formulation enables extended-duration ocular application, differentiating premium positioning.
- Japan's Generic Promotion Framework:METI incentives for generic ophthalmic substitution create reimbursement tailwinds for domestic manufacturers with PMDA-approved equivalence.
Industry Challenges
- Ophthalmic Formulation Expertise Gap:API synthesis capability without sterile formulation competency forces reliance on contract manufacturers, compressing margin capture for mid-tier suppliers.
- Pharmacopeial Monograph Uncertainty:Pending revisions to difumarate salt purity specifications by national compendia create reformulation risk for manufacturers with legacy qualification status.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emedastine Difumarate Market |
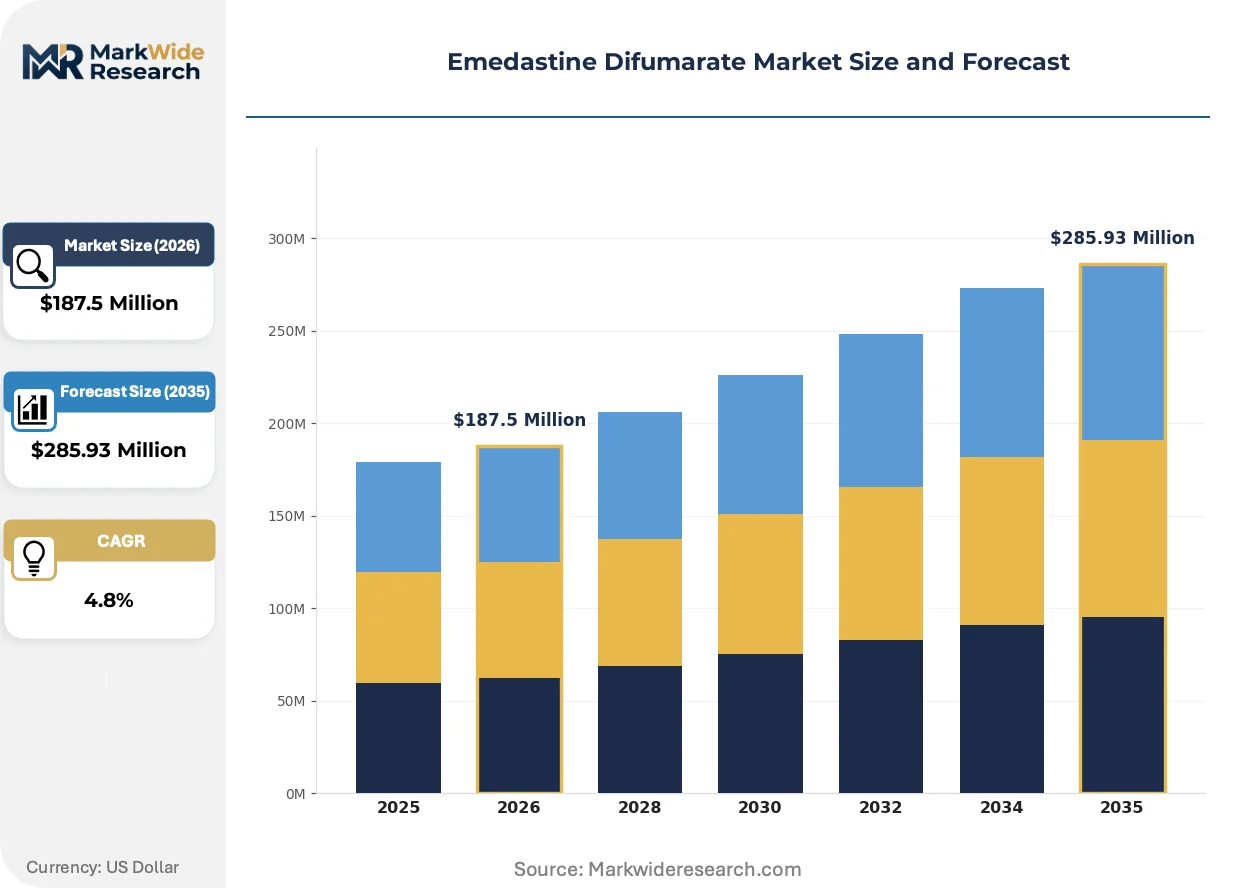
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $285.93 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Eye Drops, Ointment, Solution Therapy Area: Allergic Conjunctivitis, Allergic Rhinitis, Urticaria, Eye Inflammation Delivery Mode: Topical, Oral, Injectable, Transdermal End User: Hospitals, Clinics, Pharmacies, Homecare |
| Companies Covered | Bausch + Lomb, Alcon AG, Jiudian Pharmaceutical, Yifan Pharmaceutical, Minsheng Pharmaceutical, BAL PHARMA, Daito Pharmaceutical, Shandong Octagon Chemicals Limited, Shiratori Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emedastine Difumarate Market Trends and Innovations
Preservative-free unit-dose packaging is reshaping ophthalmic antihistamine competitive positioning, while regulatory convergence on bioequivalence standards and shifting procurement centralization in hospital networks are reconfiguring distribution economics.
Novel multi-dose preservative systems with ionic-buffered stabilization are supplanting traditional benzalkonium chloride formulations in Japanese and European ophthalmic markets. Metropolitan hospital networks in Tokyo and Osaka are adopting these systems at accelerated pace to reduce corneal toxicity reporting. This technology shift is enabling premium pricing stratification while compressing acceptance of legacy preserved formulations in reimbursement-sensitive segments.
PMDA's 2023 guidance on ophthalmic generic bioequivalence has tightened aqueous humor concentration benchmarks for new market entrants. The regulation forces extended clinical validation timelines and elevated analytical method investments for domestic Japanese manufacturers. Generic sponsors targeting Japan's hospital procurement consortia are responding with dedicated stability chambers and accelerated aging protocols to compress approval cycles.
Hospital network procurement centralization is consolidating ophthalmic antihistamine purchasing decisions into regional pharmacy and therapeutics committees. Independent ophthalmology clinics in South Korea and Taiwan are losing formulary autonomy as purchasing migrates to health system-level contracts. This behavioral shift is most visible in Seoul's metropolitan hospital networks, where generic substitution rates for topical antihistamines have compressed brand retention.
Emedastine Difumarate Market Segmentation
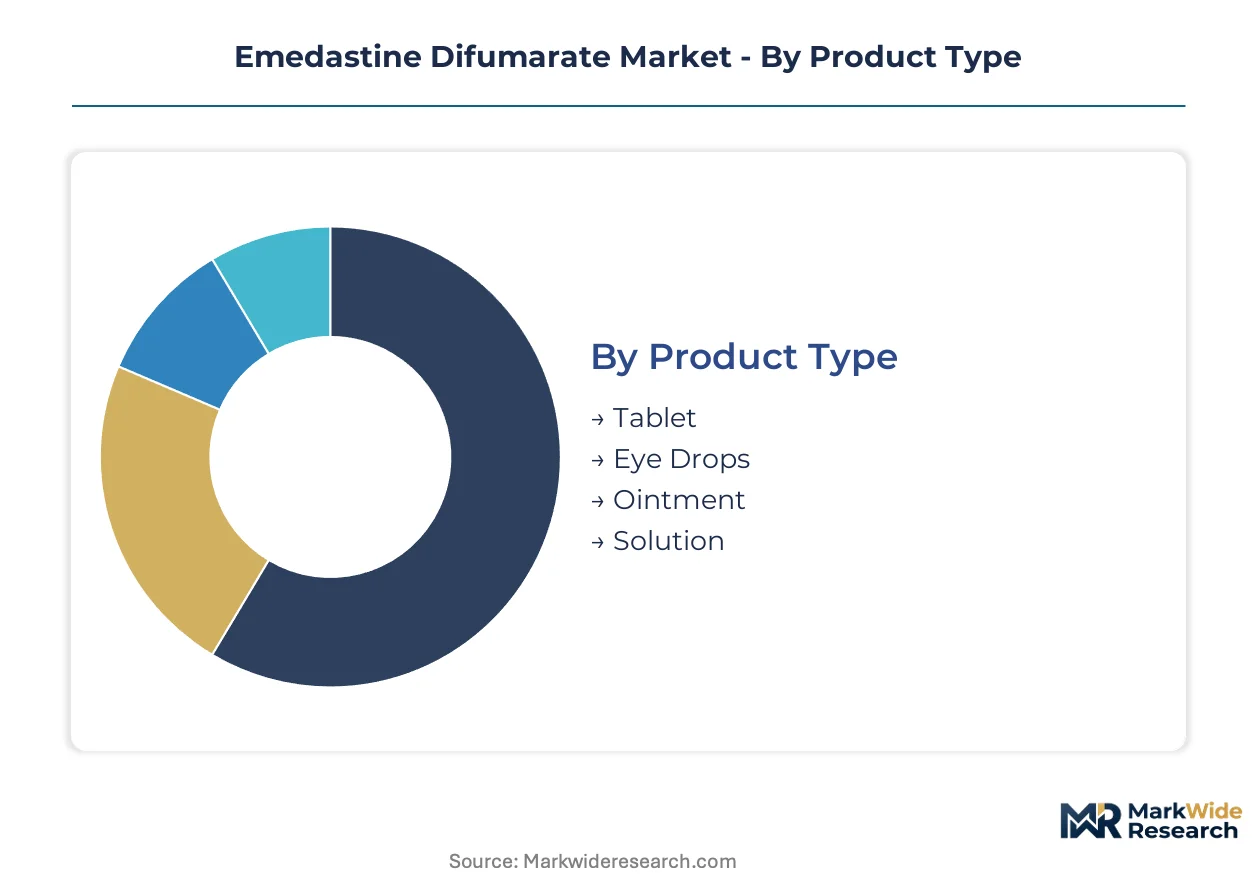
Segmentation in emedastine difumarate markets reveals how formulation technology and reimbursement pathways fragment commercial opportunity. Understanding where volume concentrates versus where margins expand enables targeted resource allocation across diverse patient access points.
Product Type:
Margin pools concentrate in sterile ophthalmic formulations where regulatory barriers protect pricing power, while commoditized oral tablets compete on manufacturing scale.
- Eye Drops:Aqueous 0.05% ophthalmic solution delivered via multi-dose or unit-dose containers dominates prescription volumes in Japan's metropolitan hospital networks. Aging populations with chronic allergic conjunctivitis drive repeat dispensing, while PMDA stability requirements for preservative systems elevate technical barriers that sustain premium positioning for compliant manufacturers.
- Tablet:Oral difumarate salt formulation enables systemic histamine blockade for allergic rhinitis protocols where patient convenience outweighs topical efficacy advantages. Jiudian Pharmaceutical and domestic Chinese suppliers compete on cost-optimized synthesis routes as NMPA generic equivalence standards accelerate market entry.
- Ointment:Semi-solid ocular preparation offers prolonged contact time for severe inflammation cases, capturing niche demand in specialized ophthalmology clinics.
- Solution:Non-ophthalmic liquid formulations serve institutional compounding and research applications with limited commercial scale.
The dominant share belongs to Eye Drops, while Tablet is closing the gap fastest as combination therapy protocols gain physician acceptance.
Therapy Area:
Application focus determines clinical validation investment and reimbursement code access, with ocular indications commanding specialized distribution channels.
- Allergic Conjunctivitis:Mast cell stabilization and competitive H1 receptor blockade in topical ocular application represents the original approved indication with established pharmacoeconomic data. East Asian ophthalmology clinics expand prescription volumes as pollution-related allergy prevalence rises in urban China and South Korea.
- Allergic Rhinitis:Systemic antihistamine delivery through oral administration broadens addressability beyond ocular specialists into primary care and ENT protocols. This segment climbs fastest as combination therapy regimens integrate topical-plus-systemic approaches for refractory seasonal allergies.
- Urticaria:Off-label histamine antagonist use for chronic hive management captures dermatology clinic volume with variable reimbursement support.
- Eye Inflammation:Adjunctive anti-inflammatory application in post-surgical ocular care generates hospital pharmacy demand tied to cataract procedure volumes.
Allergic Conjunctivitis retains the largest patient base, though Allergic Rhinitis gains share most rapidly through protocol expansion.
Delivery Mode:
Route of administration shapes manufacturing complexity, with sterile topical production requiring specialized infrastructure that limits supplier participation.
- Topical:Direct ocular or nasal surface application demands aseptic formulation capability and preservative system validation, concentrating supply among legacy ophthalmic specialists with captive synthesis operations.
- Oral:Tablet and capsule delivery offers manufacturing flexibility that enables generic API producers to enter without sterile processing investment.
- Injectable:Parenteral histamine blockade serves acute allergic emergency protocols with limited addressable volume.
- Transdermal:Patch-based delivery remains experimental for antihistamine molecules with poor skin permeation characteristics.
Topical delivery commands the highest unit economics, while Oral routes expand volume fastest through manufacturing accessibility.
End User:
Customer type determines purchasing behavior, with institutional procurement centralization reshaping competitive dynamics across access points.
- Hospitals:Metropolitan hospital networks in Tokyo, Seoul, and Shanghai consolidate ophthalmic antihistamine purchasing through pharmacy and therapeutics committees, compressing brand retention as generic substitution rates rise.
- Clinics:Independent ophthalmology practices in South Korea and Taiwan lose formulary autonomy as purchasing migrates to health system-level contracts, though rural China county-level hospitals remain underpenetrated.
- Pharmacies:Retail dispensing captures refill prescriptions and over-the-counter transitions where reimbursement permits.
- Homecare:Direct patient administration of chronic allergy regimens supports subscription-style dispensing models.
Hospitals control the dominant procurement volume, while Clinics in underserved geographies offer the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese metropolitan hospital networks while Chinese domestic manufacturers compete on cost-optimized synthesis routes, creating a regional asymmetry that rewards PMDA-compliant suppliers with premium positioning against NMPA-accelerated generic entrants.
Japan
Tokyo and Osaka metropolitan hospital networks drive prescription volumes for chronic allergy management protocols among aging populations. PMDA enforces stringent stability testing for multi-dose preservative systems, elevating technical barriers for market participation. Shiratori Pharmaceutical and Daito Pharmaceutical anchor supply from Chubu and Kanto industrial clusters, capturing premium positioning through compliant packaging technology investments.
China
County-level hospital networks in interior provinces remain underpenetrated for prescription ophthalmic therapies, offering volume expansion potential. NMPA streamlined approval pathways for generic ophthalmic formulations, accelerating domestic manufacturer entry. Jiudian Pharmaceutical and Yifan Pharmaceutical leverage cost-optimized synthesis routes from Shandong and Jiangsu manufacturing bases to compete on API supply economics.
South Korea
Seoul metropolitan hospital networks consolidate ophthalmic antihistamine purchasing through pharmacy and therapeutics committees, compressing brand retention. MFDS bioequivalence standards for generic ophthalmic formulations shape local development timelines. Independent ophthalmology clinics in Busan-Ulsan region lose formulary autonomy as procurement migrates to health system-level contracts.
United States
Specialized ophthalmology clinics and ambulatory surgical centers sustain demand for topical antihistamine therapies in urban coastal markets. FDA ophthalmic guidance documents establish bioavailability benchmarks and formulation development timelines for new entrants. Bausch + Lomb leverages vertically integrated manufacturing from Rochester, New York operations to sustain raw material throughput for difumarate salt production.
India
Domestic API manufacturers expand ophthalmic formulation capacity to serve export markets and local hospital pharmacy demand. CDSCO approval pathways for generic ophthalmic products align with pharmacopeial monograph standards for difumarate salt purity. BAL PHARMA occupies a position among Mumbai-Pune pharmaceutical corridor suppliers targeting cost-sensitive institutional procurement segments.
Emedastine Difumarate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with sterile formulation capability concentrating supply among legacy ophthalmic specialists while API synthesis accessibility enables generic manufacturer participation. The market structure fragments across vertically integrated eye care platforms, domestic Chinese API suppliers, and regional Japanese pharmaceutical specialists. Three archetypes dominate: captive synthesis ophthalmic specialists, cost-optimized API manufacturers, and controlled-release delivery innovators. Competitive moves center on backward integration into raw material supply and polymer matrix technology licensing for extended-duration applications.
Among Japan-based pharmaceutical specialists, Daito Pharmaceutical and Shiratori Pharmaceutical exemplify the PMDA-compliant formulation archetype with sterile processing investments. Bausch + Lomb represents the vertically integrated eye care platform model with captive supply chain control. Jiudian Pharmaceutical anchors the cost-optimized API manufacturer tier competing on synthesis route efficiency. Alcon AG occupies a position on the premium delivery system vector with controlled-release ophthalmic technology.
| Leading Market Players |
|---|
| Bausch + Lomb |
| Alcon AG |
| Jiudian Pharmaceutical |
| Yifan Pharmaceutical |
| Minsheng Pharmaceutical |
| BAL PHARMA |
| Daito Pharmaceutical |
| Shandong Octagon Chemicals Limited |
| Shiratori Pharmaceutical |
| Others |
Pricing and Supply Chain Analysis
Multi-dose preservative system capacity utilization at 85-90% across Chubu and Kanto manufacturing clusters creates scale economies that compress unit costs for PMDA-compliant suppliers while elevating price floors for new entrants lacking sterile formulation infrastructure.
Pricing Analysis
The customization-premium spread separates preservative-free unit-dose formulations from benzalkonium chloride-preserved multi-dose alternatives. Pricing stratifies across premium, standard, and economy tiers driven by PMDA stability certification and volume procurement scale. Cost compression in the standard tier is intensifying because NMPA-accelerated Chinese generic entrants compete on API synthesis efficiency. Metropolitan hospital networks in Japan show lowest price sensitivity due to bundled reimbursement protocols, while county-level Chinese clinics exhibit highest sensitivity to out-of-pocket cost exposure.
Supply Chain Analysis
Container availability constraints on Shanghai-Yokohama trade lanes elevate inbound logistics costs for raw fumaric acid and specialized packaging polymers. API synthesis concentrates in China, Japan, and India, with sterile formulation capability anchored in Japanese and South Korean facilities. Raw material dependencies rest on difumarate salt precursors, multi-dose bottle assemblies, and ionic-buffered preservative compounds. Single-source vulnerability persists for PMDA-validated stability testing services. Distribution runs through hospital procurement consortia in metropolitan networks and regional pharmaceutical distributors in interior provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The emedastine difumarate market functions as a defensive-moat structure where PMDA regulatory entrenchment creates switching costs that protect incumbent positioning against cost-optimized entrants.
For Market Incumbents: Shield market share by deepening backward integration into difumarate salt precursor supply and accelerating controlled-release polymer matrix R&D to differentiate against Jiudian Pharmaceutical's cost-optimized synthesis routes. Prioritize certification investment for preservative-free unit-dose formats before PMDA guidance tightens further.
For New Entrants and Emerging Players: Differentiate on delivery system innovation rather than API cost parity. Target county-level hospital networks in China's Shandong and Jiangsu provinces where formulary access remains underpenetrated for prescription ophthalmic therapies. Pursue white-label manufacturing partnerships with established sterile processors to bypass formulation expertise gaps.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among PMDA-compliant sterile formulation specialists with captive hospital procurement contracts. Long-term viability favors acquirers of Japanese pharmaceutical specialists with validated stability chambers and established METI generic promotion framework positioning. Watch MFDS bioequivalence guidance tightening as the inflection signal for Korean market entry barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Difumarate Salt Synthesis | Captive API supply secures margin protection against NMPA-accelerated Chinese generic competition. |
| Preservative-Free Unit-Dose Format Development | PMDA-aligned packaging technology captures premium positioning in Tokyo metropolitan hospital networks. |
| Controlled-Release Polymer Matrix Licensing | Extended-duration ocular application differentiates Alcon AG's premium delivery system portfolio. |
| County-Level Hospital Network Penetration | Shandong and Jiangsu manufacturing bases enable cost-optimized supply to underpenetrated interior China. |
| PMDA Stability Chamber Infrastructure Investment | Accelerated aging protocols compress approval cycles for generic sponsors targeting hospital consortia. |
Research Methodology
A spread of perspectives from sterile formulation chemists, hospital pharmacy directors, regulatory affairs specialists, and ophthalmology clinic procurement managers converged on the working assumptions underlying supply-demand modeling. Primary fieldwork combined structured interviews with secondary validation against FDA ophthalmic guidance documents, NMPA generic equivalence standards, PMDA stability testing protocols, and MFDS bioequivalence benchmarks. Bottom-up prescription volume triangulation against top-down API production capacity estimates anchored the analytical framework.
Segmentation dimensions modeled span product type, therapy area, delivery mode, and end user across the analysis window. Dosage form differentiation and regional regulatory cluster variations shaped volume allocation. CAGRs derived from historical prescription trajectory analysis and capacity expansion announcements. Forecast inputs incorporated PMDA guidance revision probability and NMPA approval pathway velocity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained PMDA regulatory stringency and NMPA streamlining continuity would require recalibration. Forecasts reflect assumptions regarding sterile formulation chemist availability and pharmacopeial monograph stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Human Immunodeficiency Virus Therapeutics Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Germany Diabetes Drugs Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Leukotriene Inhibitors Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Middle East and Africa Psychedelic Drugs Market
Pharmaceuticals
Global Antiemetic Drugs Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
US Pharmaceutical CMO Market