
 Intravitreal (IVT) Injectables Market | 2026-2036
Intravitreal (IVT) Injectables Market Size, Share, and Industry Trends Forecast 2026-2036
Intravitreal (IVT) Injectables Market Outlook
High-viscosity, preservative-free formulation tiers are rotating toward clinical preference as retinal specialists prioritize safety margins and extended dosing intervals. Regeneron Pharmaceuticals leverages its dual-chain antibody engineering to sustain leadership in wet age-related macular degeneration. Novartis anchors European supply through its manufacturing scale in Switzerland and Austria. EyePoint Pharmaceuticals differentiates with its proprietary sustained-release microsphere technology for chronic retinal conditions.
Intravitreal (IVT) injectables are sterile, biologically active pharmaceutical preparations administered directly into the vitreous humor of the eye, typically at volumes of 0.05 mL to 0.1 mL using 30-gauge or smaller needles to minimize trauma. These formulations deliver therapeutic agents to the posterior segment to treat retinal vascular diseases, macular edema, and inflammatory conditions with localized, high-concentration dosing that bypasses systemic circulation. Anti-VEGF agents dominate current prescription volumes and revenue pools across hospital and clinic settings. Sustained-release delivery systems represent the fastest-expanding delivery mode segment as physicians seek to reduce injection frequency and treatment burden for chronic retinal patients. Combination therapy approaches are gaining structural attention where monotherapies show diminishing returns in complex diabetic eye disease.
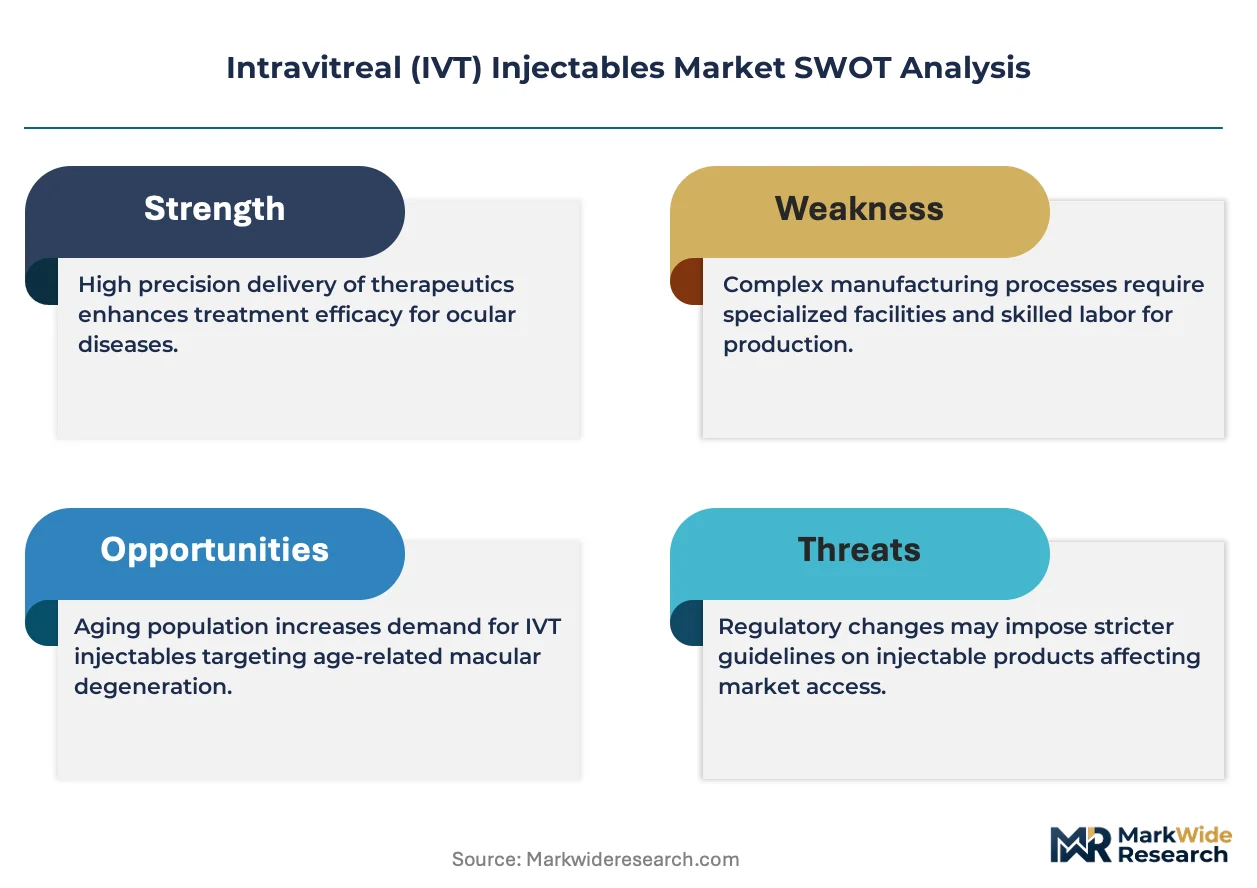
FDA oversight of ophthalmic biologics, EMA's MDR requirements for Class III implantable devices, and ISO 13485 quality management standards collectively shape manufacturing compliance, clinical trial design, and market access pathways for new entrants. The FDA's accelerated approval pathway for breakthrough therapies in retinal disease creates competitive pressure on European and Asian regulators to harmonize review timelines. Stakeholders must monitor biosimilar interchangeability rulings and sustained-release formulation patent cliffs to time portfolio investments and geographic expansion decisions.
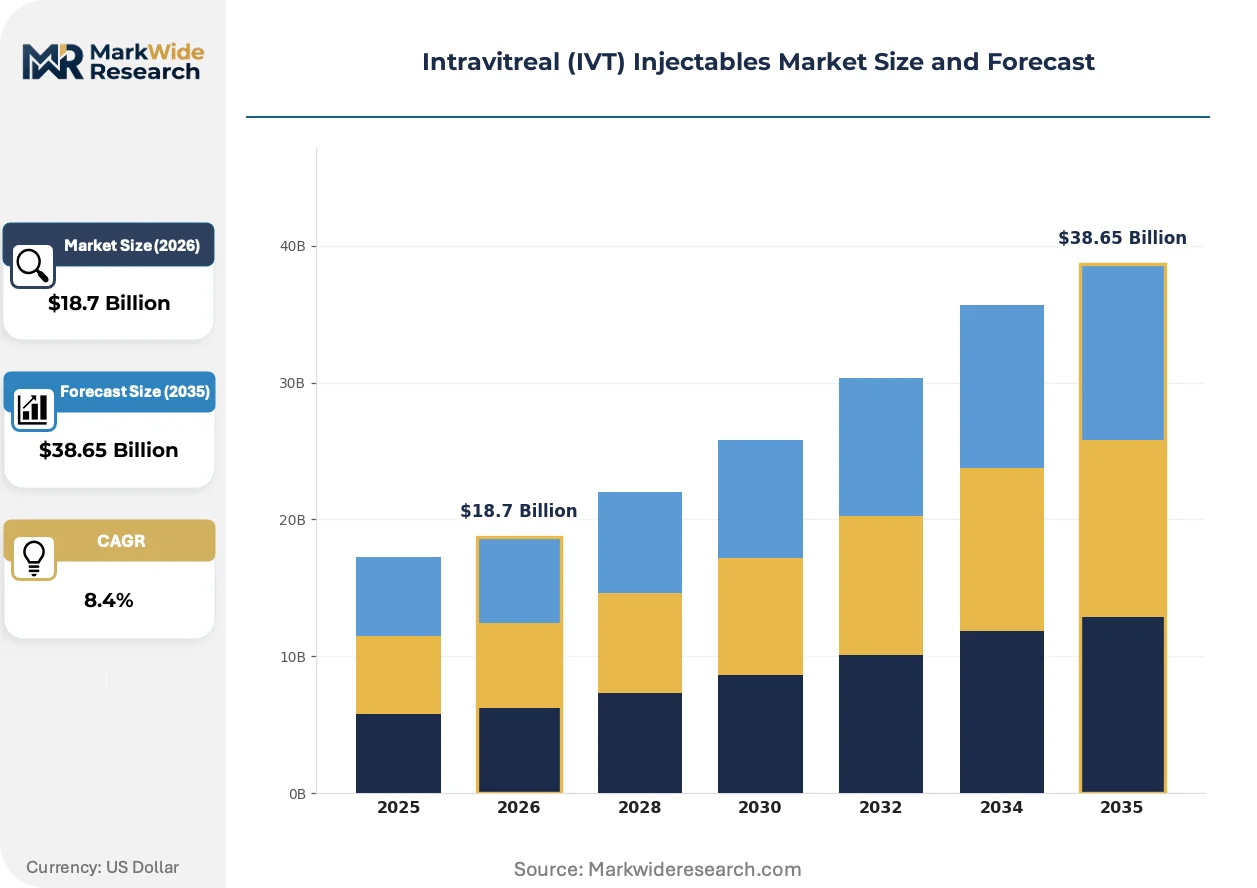
Market Dynamics
Sustained-release delivery platforms are compressing injection frequency for chronic retinal patients while FDA biosimilar rulings restructure competitive access economics across ophthalmology clinics.
Growth Catalysts
- EMA MDR Class III pathways:Streamlined conformity assessment for implantable ocular devices accelerates European market entry for sustained-release formulations.
- Anti-VEGF biosimilar interchangeability:US FDA determinations on switching protocols expand formulary access and reduce payer resistance to alternative therapies.
- German reimbursement frameworks:Statutory health insurance coverage for diabetic macular edema therapies concentrates demand volume in outpatient retinal centers.
Market Restraints
- Silicone oil raw material concentration:Three specialty chemical suppliers control pharmaceutical-grade silicone for intravitreal tamponade, creating input vulnerability.
- ISO 13485 certification timelines:Quality management system audits for sterile injectable manufacturing extend 14-18 months for new facility qualification.
- Office-based surgical substitution:Ambulatory surgical centers capture complex vitrectomy cases that previously required hospital-based intravitreal therapy.
Strategic Opportunities
- Japan's aging retina patient pool:METI-targeted medical device innovation zones offer tax incentives for localized sustained-release manufacturing.
- Gene therapy convergence with IVT delivery:Viral vector platforms paired with intravitreal injection open inherited retinal disease applications beyond vascular indications.
- Direct-to-clinic distribution channels:Specialty pharmaceutical logistics bypass wholesale consolidation, preserving margin for high-value biologic formulations.
Industry Challenges
- Ocular pharmacokinetic modeling expertise:Sparse qualified scientists bridge vitreous humor dynamics with formulation design, constraining R&D throughput.
- Legacy EHR integration:Retinal imaging systems and injection scheduling platforms require costly interoperability upgrades for outcome tracking mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravitreal (IVT) Injectables Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF, Corticosteroids, Antibiotics, Combination Therapy Therapy Area: Macular Degeneration, Diabetic Retinopathy, Uveitis, Retinal Vein Occlusion Delivery Mode: Single Injection, Sustained Release, Pre-filled Syringe, Custom Delivery Systems End User: Hospitals, Eye Clinics, Outpatient Departments, Research Institutions |
| Companies Covered | Genentech, Alcon, Regeneron Pharmaceuticals, EyePoint Pharmaceuticals, AbbVie, Novartis, Bausch & Lomb, Alimera Sciences, Allergan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravitreal (IVT) Injectables Market Strategic Shifts
Bioresorbable polymer matrices are redefining dosing intervals while regulatory harmonization pressures compress approval timeline differentials between major jurisdictions.
Port delivery systems with refillable reservoirs are decomposing the monthly injection paradigm for wet age-related macular degeneration. Retinal specialists in US academic medical centers are adopting these implants at accelerating pace. The technology is decomposing revenue concentration among anti-VEGF agents by enabling device-plus-drug bundled economics.
FDA's breakthrough therapy designation for retinal disease is compressing Phase II-to-approval intervals for novel mechanisms. EMA has responded with parallel scientific advice programs to prevent European launch lags. Sustained-release formulations with complex device constituents face the steepest regulatory scrutiny under this competitive pressure.
Retinal practices are unbundling injection services from global capitation contracts with Medicare Advantage plans. Fee-for-service billing for each intravitreal procedure is displacing bundled diabetic eye care payments in southeastern US markets. Ophthalmology management companies are consolidating independent practices to negotiate these reimbursement terms at scale.
Intravitreal (IVT) Injectables Market Segmentation
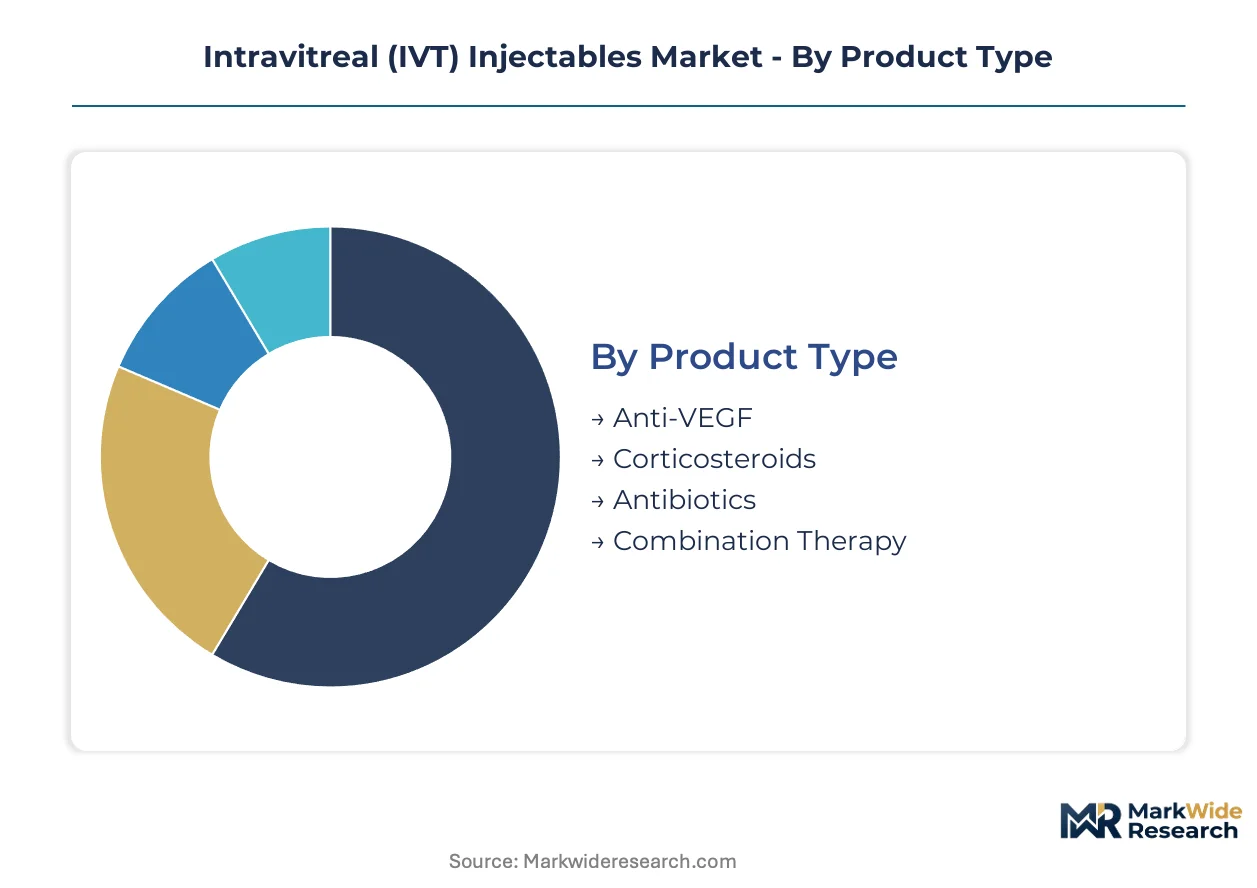
Segmentation in intravitreal injectables determines reimbursement pathways, manufacturing scale requirements, and clinical training investments. Channel dynamics vary sharply across product types and delivery modes, with sustained-release platforms commanding premium logistics while single-injection volumes dominate prescription counts.
Product Type:
Hospital formularies and specialty distributors channel distinct product categories through separate procurement workflows, with biologics requiring cold-chain custody and small-molecule steroids flowing through standard pharmaceutical wholesalers.
- Anti-VEGF:Recombinant protein formulations targeting vascular endothelial growth factor dominate hospital purchasing committees and retinal specialist prescribing patterns. Wet age-related macular degeneration patients in Germany and the United States drive concentrated demand through academic medical center infusion centers, where EMA MDR Class III pathways and FDA breakthrough therapy designations accelerate access for novel entrants.
- Corticosteroids:Synthetic glucocorticoid suspensions address macular edema and inflammatory indications with established reimbursement codes. Eye clinics in Japan and outpatient departments across Switzerland favor these agents for diabetic eye disease protocols where anti-VEGF monotherapy shows incomplete response, constrained by cataract progression risks that limit repeat dosing.
- Antibiotics:Intravitreal vancomycin and ceftazidime formulations target endophthalmitis prophylaxis and treatment. These products move through hospital pharmacy emergency stock systems.
- Combination Therapy:Co-formulated or sequential anti-VEGF and steroid protocols address complex diabetic macular edema. Research institutions in Austria pilot these regimens.
By volume, Anti-VEGF leads. By growth pace, Combination Therapy is expanding most quickly.
Therapy Area:
Cost tiers stratify sharply across indications, with chronic maintenance therapies for degenerative conditions consuming disproportionate reimbursement budgets versus acute intervention segments.
- Macular Degeneration:Age-related and myopic variants constitute the highest-value addressable population, requiring indefinite treatment cycles. Wet AMD patients in the United States and Germany generate the steepest per-capita expenditure curves, where port delivery systems are displacing monthly injection burdens and restructuring practice economics toward device-plus-drug bundles.
- Diabetic Retinopathy:Proliferative and non-proliferative disease stages drive volume concentration in Medicare Advantage and statutory health insurance systems. Indian and Chinese patient pools are expanding fastest as diabetes prevalence climbs, though reimbursement fragmentation constrains anti-VEGF penetration outside tier-one cities.
- Uveitis:Intermediate, posterior, and panuveitis variants require immunomodulatory intravitreal therapy. Corticosteroid implants dominate this segment.
- Retinal Vein Occlusion:Branch and central occlusion variants generate acute presentation volumes. Hospital emergency departments capture initial therapy decisions.
Macular Degeneration commands the highest per-patient lifetime value. Diabetic Retinopathy is gaining share fastest as emerging markets expand treatment access.
Delivery Mode:
Manufacturing complexity and margin profiles diverge radically across delivery technologies, with device-constituent formulations requiring ISO 13485 certification timelines that extend 14-18 months versus standard aseptic fill-finish operations.
- Single Injection:Conventional bolus administration via 30-gauge needles remains the volume foundation across all geographies. Eye clinics in France and outpatient departments in Spain rely on this modality for treatment-naive patients and acute presentations where sustained-release eligibility has not been established.
- Sustained Release:Bioresorbable polymer matrices and refillable reservoir implants compress injection frequency from monthly to quarterly or semi-annual intervals. US academic medical centers and German retinal centers are adopting these platforms fastest, driven by patient compliance gains and practice efficiency metrics that align with value-based reimbursement pilots.
- Pre-filled Syringe:Ready-to-use unit-dose presentations reduce compounding errors and preparation time. Hospital pharmacies in the United Kingdom favor this format for operating room efficiency.
- Custom Delivery Systems:Patient-specific dosing configurations and combination device platforms. Research institutions in Switzerland evaluate these technologies.
Single Injection retains volume leadership. Sustained Release exhibits the steepest expansion trajectory as patent cliffs and biosimilar entry pressure innovator portfolios toward differentiation.
End User:
Customer type determines purchasing authority, with integrated delivery networks consolidating procurement for hospital systems while independent specialists retain autonomy in clinic settings.
- Hospitals:Inpatient and emergency ophthalmology departments manage acute presentations, surgical complications, and complex multi-morbidity cases. Tertiary centers in Italy and the United Kingdom concentrate expensive sustained-release inventory and gene therapy trial access, where centralized pharmacy governance standardizes formulary decisions across affiliated clinics.
- Eye Clinics:Independent and corporate-affiliated retinal practices generate the majority of chronic maintenance injection volumes. Southeastern US markets and western German outpatient centers are unbundling injection services from global capitation contracts, shifting toward fee-for-service billing that rewards procedure frequency.
- Outpatient Departments:Hospital-affiliated non-admitted care units blend emergency access with chronic follow-up. These settings bridge referral pathways.
- Research Institutions:Academic medical centers and contract research organizations conduct pivotal trials. Japanese METI innovation zones and Austrian clinical trial hubs concentrate early-phase activity.
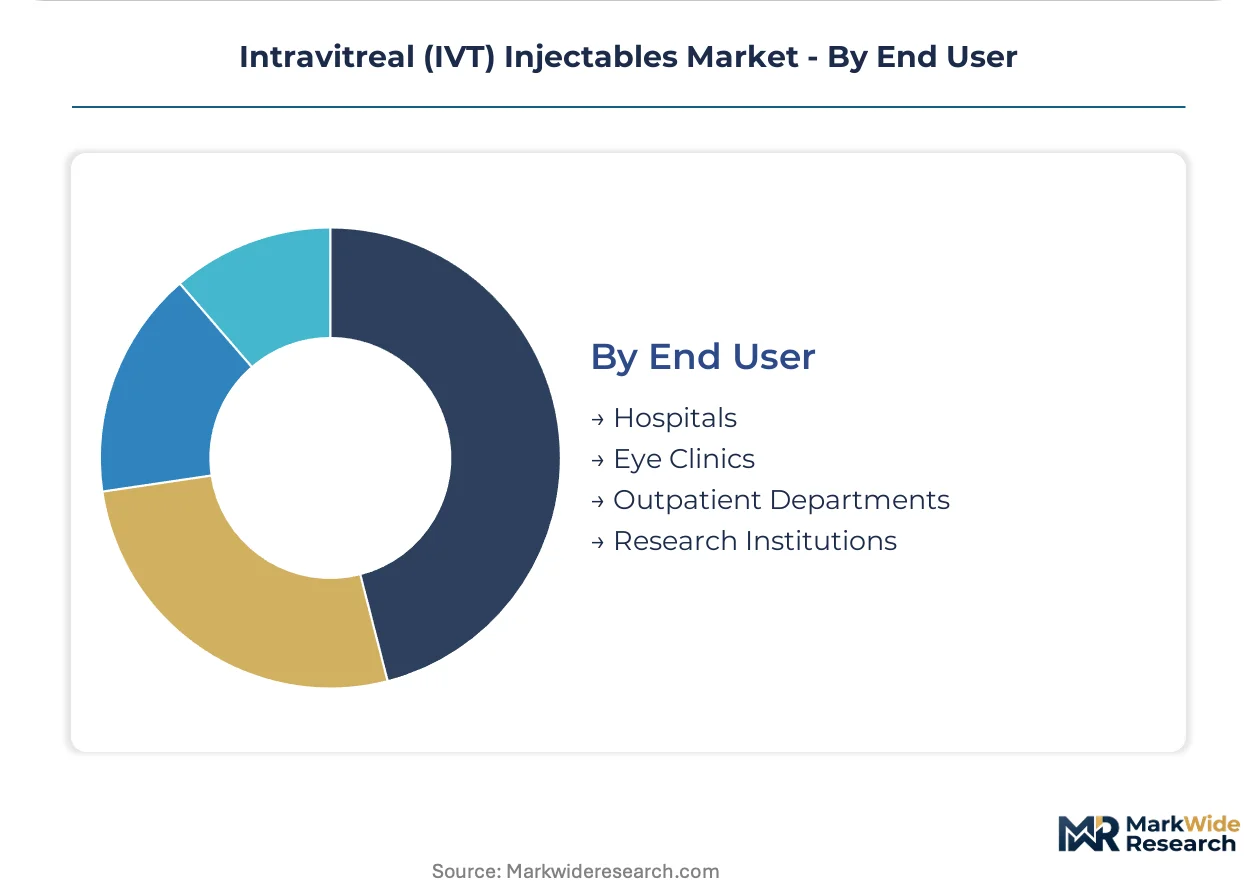
Eye Clinics handle the greatest injection volume. Research Institutions are expanding fastest as gene therapy and sustained-release pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical supply for pharmaceutical-grade silicone concentrates among three dominant suppliers, creating geographic vulnerability for device-constituent manufacturing. Retinal therapy demand clusters in aging populations with statutory reimbursement frameworks. Regulatory harmonization pressures are compressing approval timeline differentials between FDA and EMA jurisdictions.
United States
Wet age-related macular degeneration patients drive concentrated demand through academic medical center infusion centers. FDA breakthrough therapy designations accelerate access timelines for novel sustained-release entrants. Port delivery system adoption is accelerating fastest in southeastern retinal practices unbundling injection services from Medicare Advantage capitation contracts.
Germany
Statutory health insurance coverage for diabetic macular edema therapies concentrates outpatient retinal center volumes. EMA MDR Class III pathways streamline conformity assessment for implantable ocular devices. Bavarian and Baden-Württemberg retinal centers are adopting sustained-release platforms ahead of national averages, driven by value-based reimbursement pilots.
Japan
METI-targeted medical device innovation zones offer tax incentives for localized sustained-release manufacturing. PMDA review timelines for retinal biologics are compressing under regulatory harmonization pressure. The Kanto region around Tokyo anchors gene therapy trial activity and early-phase clinical development for viral vector platforms.
Switzerland
Swissmedic oversight of ophthalmic biologics maintains stringent quality benchmarks that shape European manufacturing standards. Novartis manufacturing scale in Basel and Austrian facilities anchors continental supply chains. Research institutions in Zurich and Geneva evaluate patient-specific dosing configurations and combination device platforms.
India
Diabetic retinopathy patient pools are expanding fastest as diabetes prevalence climbs, though reimbursement fragmentation constrains anti-VEGF penetration outside tier-one cities. CDSCO regulatory pathways for biosimilar ophthalmic biologics are maturing. Maharashtra and Karnataka hospital systems are consolidating procurement for intravitreal antibiotics and emergency endophthalmitis protocols.
Intravitreal (IVT) Injectables Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with sustained-release device engineering separating premium-tier innovators from commodity biologic suppliers. The market structure tiers across three concentration levels: integrated pharmaceutical conglomerates with ophthalmology divisions, mid-cap retinal specialists with platform technologies, and regional generic manufacturers. Dominant competitive moves include strategic partnerships for gene therapy vector platforms and geographic licensing arrangements for sustained-release manufacturing.
Among integrated pharmaceutical conglomerates, Novartis and AbbVie occupy positions spanning biologic supply and device-constituent partnerships. Regeneron Pharmaceuticals exemplifies the mid-cap specialist archetype with focused retinal therapeutic development. EyePoint Pharmaceuticals sits within the platform-technology tier, representing sustained-release delivery innovation through proprietary microsphere engineering.
| Leading Market Players |
|---|
| Genentech |
| Alcon |
| Regeneron Pharmaceuticals |
| EyePoint Pharmaceuticals |
| AbbVie |
| Novartis |
| Bausch & Lomb |
| Alimera Sciences |
| Allergan |
| Others |
Value Chain & Pricing Dynamics
Bioresorbable polymer matrices substituting for conventional bolus formulations are redrawing manufacturing geography toward Switzerland and Austria while compressing price premiums for sustained-release tiers. This substitution dynamic simultaneously elevates raw material purity requirements and fragments procurement leverage across hospital formularies and specialty distributors.
Pricing Analysis
FDA breakthrough therapy designation dictates the pricing tier structure for novel intravitretinal entrants, stratifying reimbursement across premium sustained-release implants, standard anti-VEGF biologics, and economy-tier corticosteroid suspensions. Price differentiation hinges on ISO 13485 certification grade and dosing interval extension, with German statutory insurers showing lowest sensitivity to premium tiers and Indian hospital systems most responsive to per-dose economics. Cost compression in the standard biologic tier is intensifying because biosimilar interchangeability rulings expand formulary substitution protocols.
Supply Chain Analysis
Strategic stockpiling of pharmaceutical-grade silicone oil dominates inventory strategy among device-constituent manufacturers, contrasting with just-in-time preferences for single-injection anti-VEGF vials. Raw material sourcing draws from Swiss, Austrian, and Japanese specialty chemical suppliers, with bioresorbable polymers and viral vector feedstocks anchoring cost structures. Single-source vulnerability concentrates in pharmaceutical-grade silicone tamponade inputs, where three suppliers control global pharmaceutical-grade output. Distribution runs through specialty pharmaceutical logistics channels for cold-chain biologics and standard wholesale networks for small-molecule steroids.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified ocular pharmacokinetic modelers remain scarce relative to pipeline expansion, constraining R&D throughput and elevating acquisition premiums for teams bridging vitreous humor dynamics with formulation engineering.
For Market Incumbents: Consolidate manufacturing scale in Swiss and Austrian corridors to capture EMA MDR Class III pathway efficiencies, while securing backward integration into pharmaceutical-grade silicone supply to mitigate raw material concentration risk. Lock in long-term contracts with retinal specialist networks before sustained-release patent cliffs accelerate price erosion in the anti-VEGF standard tier. For New Entrants and Emerging Players: Differentiate on refillable reservoir engineering for wet AMD maintenance protocols, targeting Japanese METI innovation zones for tax-advantaged manufacturing scale. White-space opportunity concentrates in gene therapy vector platforms paired with intravitreal delivery, where viral vector manufacturing partnerships offer the most penetrable entry path against entrenched anti-VEGF incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sustained-release device specialists holding ISO 13485 certifications but lacking commercial scale. Long-term viability favors platforms with quarterly-to-annual dosing interval extension and reimbursement codes locked in German statutory frameworks. Watch FDA biosimilar interchangeability determinations as the inflection signal for margin compression timelines in the standard biologic tier.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Class III Certification | Streamlines European market entry for implantable ocular devices in German retinal centers. |
| Sustained-Release Manufacturing Scale-Up | Captures value-based reimbursement pilots in Bavarian outpatient clinics seeking reduced injection frequency. |
| Gene Therapy Vector Licensing | Opens inherited retinal disease applications beyond vascular indications through viral vector partnerships. |
| Direct-to-Clinic Distribution Buildout | Bypasses wholesale consolidation to preserve margin on high-value biologic formulations in US southeastern markets. |
| Anti-VEGF Biosimilar Pipeline Advancement | Accelerates formulary access under FDA interchangeability protocols reshaping competitive access economics. |
Study Parameters
Initial hypotheses were tested against primary input from retinal specialists, hospital formulary directors, regulatory affairs leads at ophthalmic device manufacturers, and payer access specialists, then refined through secondary validation against FDA filings, EMA MDR submission databases, ClinicalTrials.gov records, and CMS Medicare reimbursement data. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to constrain variance.
Variance decomposition across the projection horizon isolates contribution from product type segments, delivery mode technologies, therapy area indications, and regional regulatory clusters. CAGRs were derived from patient population epidemiology, treatment penetration curves, and dosing interval evolution assumptions, with specific weighting applied to sustained-release adoption rates in US academic medical centers and German statutory insurance frameworks.
The analysis sits within stated boundaries; outcomes outside sustained-release manufacturing scale achievements or biosimilar interchangeability rulings would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline compression and reimbursement code stability. Revision becomes warranted when pharmaceutical-grade silicone supply concentration crosses critical disruption thresholds or when gene therapy convergence accelerates beyond modeled adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
Global Atrial Fibrillation Drugs Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market