
 Ocular Drug Delivery System Market | 2026-2036
Ocular Drug Delivery System Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Drug Delivery System Market Outlook
Hospital procurement of conventional eye drops is collapsing as ophthalmology clinics and ambulatory surgical centers gain share in advanced delivery modalities. EyePoint Pharmaceuticals leverages its proprietary Durasert technology to sustain long-acting intravitreal therapies. Novartis competes through its geographic dominance in European ophthalmology markets. Clearside Biomedical specializes in suprachoroidal microinjection, a niche that differentiates its portfolio from conventional intravitreal approaches.
An ocular drug delivery system comprises engineered devices and formulations designed to transport therapeutic agents across ocular barriers with specified release kinetics, typically achieving bioavailability thresholds below five percent for topical formulations due to tear turnover and corneal impermeability. These systems serve the primary commercial purpose of extending drug residence time, reducing dosing frequency, and enabling posterior segment access for retinal diseases. Drops remain the mature volume leader across home care and primary ophthalmology settings, while implants capture the fastest expansion in hospital and surgical environments where six-month release profiles justify premium positioning. Intravitreal delivery dominates value pools in retinal therapy, though periocular routes are gaining structural attention from developers seeking safer alternatives to direct vitreal injection.
The FDA oversees combination product classifications that determine whether ocular implants face drug or device review pathways, directly shaping development timelines and clinical trial requirements. EMA's MDR framework and CE marking obligations govern European market access for Class III implantable ophthalmic devices. The EU AI Act introduces emerging compliance dimensions for diagnostic-linked delivery systems. Stakeholders must monitor how regulator convergence on sustained-release safety databases reshapes competitive barriers and partnership structures between device specialists and pharmaceutical developers.
Market Dynamics
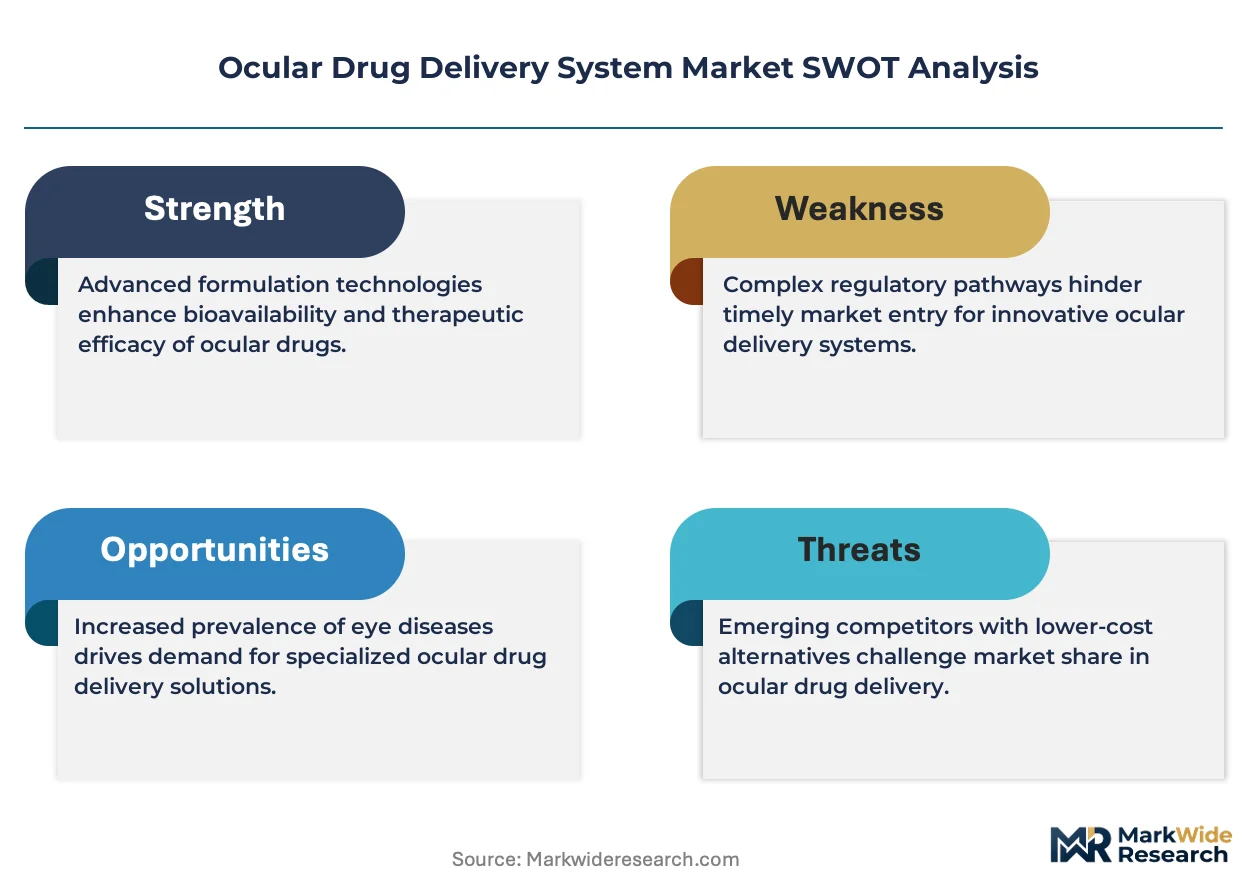
Sustained-release implant technologies are compressing dosing frequencies from monthly to semi-annual intervals, fundamentally restructuring the economics of retinal disease management and redistributing value from pharmaceutical volume toward device-enabled delivery premiums.
Growth Catalysts
- MDR Framework Acceleration:The European Union's Medical Device Regulation streamlines CE marking pathways for Class III ophthalmic implants, reducing time-to-market for combination products in Germany, France, and Italy.
- Ambulatory Surgical Center Expansion:Outpatient facilities in the United States are deploying intravitreal implant suites, capturing procedures previously reserved for hospital ophthalmology departments.
- Suprachoroidal Microinjection:This periocular delivery route accesses the posterior segment without direct vitreal puncture, attracting developers seeking safer alternatives to conventional intravitreal injection protocols.
Market Restraints
- Silicone Oil Supply Concentration:Three specialty chemical manufacturers in Japan and Germany control pharmaceutical-grade silicone oil for intravitreal tamponade, creating vulnerability in implant excipient security.
- Biodegradable Polymer Cost Volatility:PLGA and PCL resin prices fluctuate with caprolactone feedstock availability, compressing margins for long-acting depot formulations.
- FDA Combination Product Friction:Uncertainty over whether novel delivery systems trigger drug or device review pathways extends clinical development timelines and capital requirements.
Strategic Opportunities
- Indian Ophthalmology Infrastructure:Tier-2 cities in Maharashtra and Tamil Nadu lack sustained-release capabilities, presenting first-mover positioning for implant-delivery networks.
- Gene Therapy Convergence:AAV vectors paired with suprachoroidal delivery devices enable non-vitreal access to retinal pigment epithelium, opening inherited retinal disease applications.
- IRA Price Negotiation Exclusion:Medicare drug pricing reforms exempt certain implantable devices, creating reimbursement advantages for qualifying delivery technologies in United States markets.
Industry Challenges
- Ocular Pharmacokinetic Modeling Talent:The specialized intersection of vitreous humor dynamics and controlled-release engineering faces acute recruitment constraints across Boston and Basel clusters.
- ISO 13485 Certification Timelines:Quality management system audits for implantable ophthalmic devices stretch 18-24 months, delaying manufacturing scale-up for novel delivery platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Drug Delivery System Market |
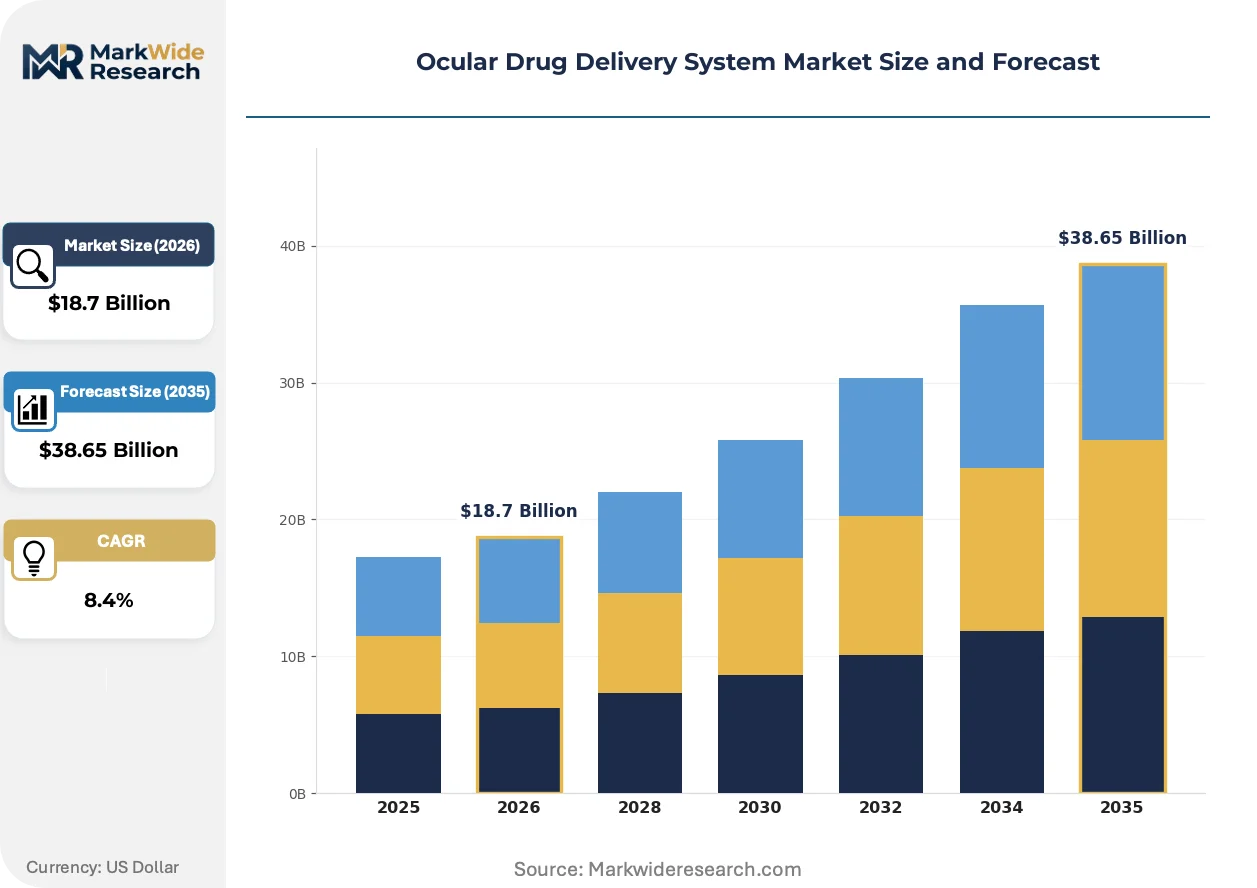
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drops, Implants, Gels, Inserts Delivery Mode: Topical, Intravitreal, Periocular, Systemic End User: Hospitals, Clinics, Home Care, Research Institutes Formulation Type: Suspensions, Solutions, Ointments, Emulsions |
| Companies Covered | Clearside Biomedical, EyePoint Pharmaceuticals, Inc., Ocular Therapeutix Inc., Novartis AG, Bausch Health Companies Inc., Allergan plc, AptarGroup, Inc., Regeneron Pharmaceuticals Inc., Santen Pharmaceutical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Drug Delivery System Market Strategic Shifts
Bioresorbable scaffold technologies and non-invasive transscleral delivery methods are converging to displace conventional intravitreal injection protocols, compressing the boundary between surgical and pharmaceutical intervention models.
Microfluidic implant fabrication is fragmenting manufacturing scale assumptions in ocular drug delivery. These precision-molded reservoirs achieve zero-order release kinetics through laser-drilled orifice control. Contract manufacturers in Minnesota and Bavaria are installing cleanroom capacity to serve pharmaceutical partners. The technology is fragmenting the traditional division between high-volume drop manufacturing and low-volume surgical implant production.
The EU AI Act introduces compliance dimensions for diagnostic-linked delivery systems that integrate imaging-guided injection robotics. Manufacturers must document algorithmic transparency and clinical decision-support validation for CE marking renewal. Ophthalmology suites in the Netherlands and Sweden are piloting these integrated platforms, though full deployment awaits notified body guidance interpretation.
Hospital purchasing cooperatives are consolidating procurement authority for ophthalmic delivery devices, displacing individual clinic autonomy. Group Purchasing Organizations in Texas and California now negotiate implant contracts covering multiple health systems. This concentration is most visible in retinal surgery segments where six-month release profiles justify bulk commitment structures.
Ocular Drug Delivery System Market Segmentation
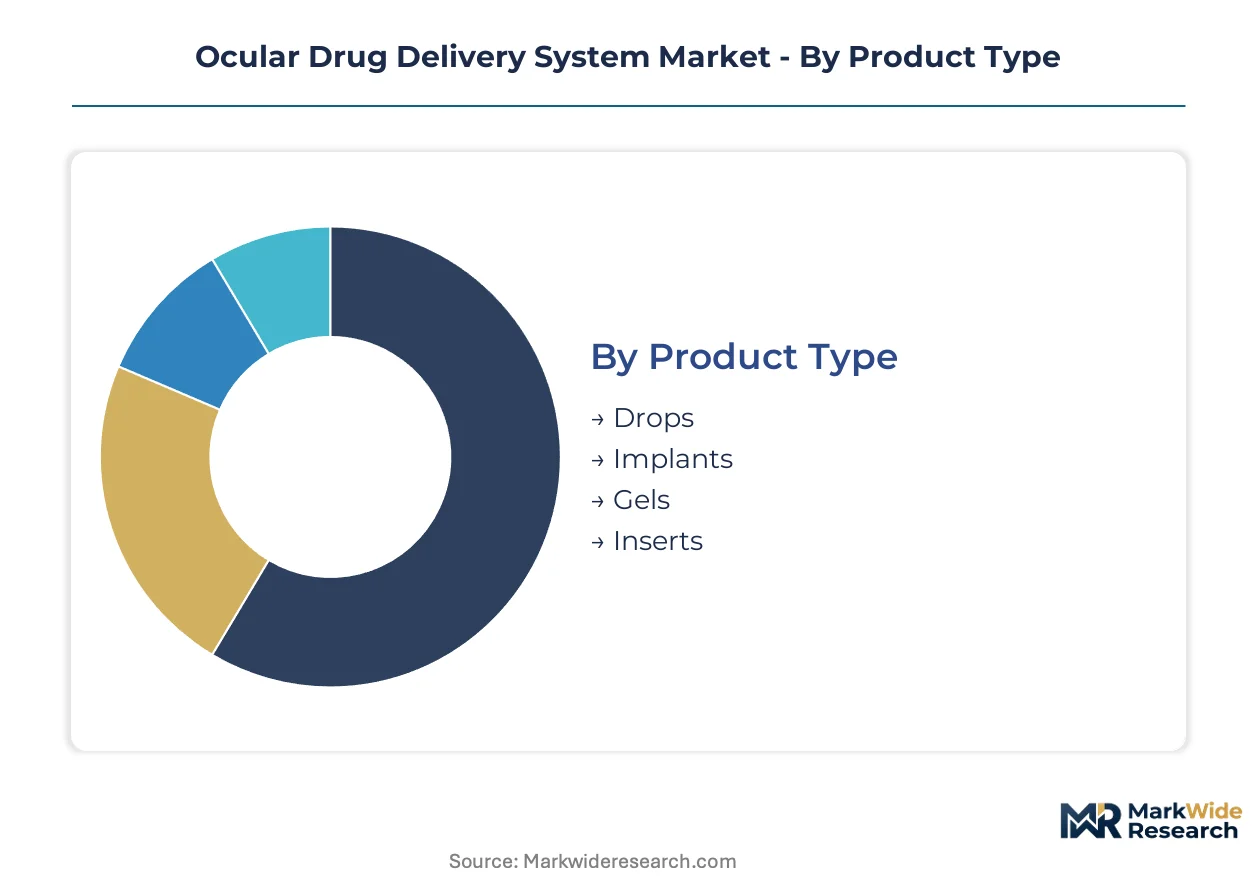
Segmentation in ocular drug delivery reveals how formulation physics and administration setting determine pricing power. Product architecture separates commodity drops from surgical implants with six-month release profiles. Delivery mode selection dictates regulatory pathway and reimbursement tier.
Product Type:
Drops dominate domestic pharmacy channels across the United States and India, while implants command export premiums through European and Japanese surgical networks.
- Drops:Aqueous or oil-based solutions requiring frequent instillation due to tear turnover and nasolacrimal drainage. Demand concentrates in United States retail pharmacies and Indian primary care settings where patient self-administration and low unit cost sustain volume leadership despite bioavailability below five percent.
- Implants:Biodegradable or non-biodegradable reservoirs inserted surgically to achieve sustained release over months. German and Japanese ophthalmology clinics drive export demand for six-month release profiles that justify premium positioning and reduce injection burden in retinal disease management.
- Gels:Viscous formulations extending precorneal residence time through mucoadhesive properties.
- Inserts:Solid devices placed in conjunctival sac or punctal canaliculus for extended drug release.
Drops hold the largest share; momentum sits with implants.
Delivery Mode:
Cost tiers separate home-administered topical therapy from surgical intravitreal intervention requiring specialized facility infrastructure.
- Topical:Direct application to ocular surface for anterior segment diseases. Home care settings in Maharashtra and Tamil Nadu absorb volume for glaucoma and dry eye management, constrained by corneal impermeability and the need for preservative-free formulations in chronic use.
- Intravitreal:Direct injection into vitreous cavity for posterior segment access. United States ambulatory surgical centers and hospital ophthalmology departments command this highest-cost tier, where anti-VEGF therapy frequency drives demand for sustained-release alternatives.
- Periocular:Administration adjacent to sclera accessing posterior segment without vitreal puncture.
- Systemic:Oral or intravenous routes with limited ocular penetration due to blood-retinal barrier.
Intravitreal commands premium pricing; periocular routes are expanding most quickly as safety-conscious developers seek alternatives to direct vitreal puncture.
End User:
Application criticality separates emergency hospital intervention from chronic home management, with margin concentration in surgical settings.
- Hospitals:Acute intervention facilities handling complex retinal detachment and endophthalmitis cases. United States academic medical centers and German university hospitals anchor demand for combination product implants requiring surgical suite infrastructure.
- Clinics:Outpatient facilities managing chronic disease with injection or implant capabilities. Ambulatory surgical centers in Texas and California are capturing procedures previously reserved for hospital departments, restructuring procurement through group purchasing organization consolidation.
- Home Care:Patient or caregiver administration of topical therapies.
- Research Institutes:Preclinical and clinical trial sites testing novel delivery platforms.
Hospitals hold the largest share; momentum sits with clinics as surgical volume shifts to outpatient settings.
Formulation Type:
Maturity curves separate established solution chemistry from complex emulsion engineering requiring specialized manufacturing.
- Suspensions:Solid particles dispersed in liquid vehicle requiring resuspension before instillation. United States compounding pharmacies and Indian generic manufacturers dominate production, with particle size distribution controlling sedimentation stability and dosing consistency.
- Solutions:Homogeneous molecular dispersions in aqueous or non-aqueous vehicles. Volume leadership in European retail channels reflects manufacturing simplicity and compatibility with preservative systems, though limited to lipophilic drugs crossing corneal epithelium.
- Ointments:Semi-solid hydrocarbon bases extending contact time through viscosity.
- Emulsions:Oil-in-water dispersions improving lipophilic drug delivery.
Solutions hold the largest share; emulsions are gaining share fastest as lipid-based delivery expands for poorly soluble actives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German implant manufacturers export sustained-release devices to Japanese ophthalmology clinics, establishing the primary trade corridor for premium delivery technologies. This bilateral flow shapes regional investment patterns and regulatory alignment priorities.
United States
Retinal disease prevalence and Medicare reimbursement infrastructure drive demand for six-month release implants. The FDA's combination product classification pathways determine whether novel devices face drug or device review timelines. Ambulatory surgical centers in Texas and California capture procedures previously reserved for hospital departments, restructuring procurement through group purchasing organization consolidation.
Germany
University hospitals in Heidelberg and Tübingen anchor demand for Class III implantable devices requiring surgical suite infrastructure. The EU MDR framework streamlines CE marking pathways for ophthalmic combination products. Bavarian contract manufacturers are installing cleanroom capacity to serve pharmaceutical partners developing microfluidic reservoir technologies.
Japan
Specialty chemical manufacturers in Osaka and Tokyo control pharmaceutical-grade silicone oil supply for intravitreal tamponade applications. The PMDA oversees market access for sustained-release implants through pharmaceutical review pathways. Kansai-based ophthalmology clinics drive adoption of biodegradable polymer depot formulations for retinal disease management.
India
Tier-2 cities in Maharashtra and Tamil Nadu lack sustained-release capabilities, presenting first-mover positioning for implant-delivery networks. The CDSCO regulates combination products under pharmaceutical approval frameworks. Mumbai and Chennai-based generic manufacturers dominate aqueous solution production for domestic pharmacy channels despite bioavailability constraints.
Switzerland
Basel clusters face acute recruitment constraints for ocular pharmacokinetic modeling talent at the intersection of vitreous humor dynamics and controlled-release engineering. Swissmedic governs market access for implantable ophthalmic devices through medical device review pathways. Geneva-based research institutes pilot diagnostic-linked delivery systems integrating imaging-guided injection robotics.
Ocular Drug Delivery System Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and manufacturing scale dimensions. The vendor base separates into three tiers: diversified pharmaceutical conglomerates with ophthalmology divisions, device-centric specialists with proprietary delivery platforms, and contract manufacturers scaling cleanroom capacity for pharmaceutical partnerships. Dominant competitive moves include strategic partnerships between device specialists and pharmaceutical developers, plus backward integration into polymer resin supply to control biodegradable formulation costs.
Within the device-specialist tier, Clearside Biomedical and EyePoint Pharmaceuticals exemplify archetypes pursuing differentiated delivery routes—suprachoroidal microinjection versus intravitreal sustained-release implants respectively. Novartis occupies a position representing pharmaceutical conglomerate diversification into combination product development through geographic dominance in European ophthalmology markets.
| Leading Market Players |
|---|
| Clearside Biomedical |
| EyePoint Pharmaceuticals, Inc. |
| Ocular Therapeutix Inc. |
| Novartis AG |
| Bausch Health Companies Inc. |
| Allergan plc |
| AptarGroup, Inc. |
| Regeneron Pharmaceuticals Inc. |
| Santen Pharmaceutical Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German implant manufacturers and Japanese silicone oil suppliers lock in both pharmaceutical-grade excipient access and eighteen-month price visibility for sustained-release depot formulations. These bilateral contracts insulate Bavarian cleanroom operators from spot market volatility in caprolactone feedstocks while committing Kansai-based chemical producers to volume floors.
Pricing Analysis
Current-generation intravitreal implants command three-to-four-fold premiums over prior-generation biodegradable depots, while next-generation suprachoroidal microinjection devices are priced at pilot-scale premiums awaiting manufacturing scale proof points. Three-tier pricing structure across premium, standard, and economy levels separates six-month release profiles from monthly formulations from conventional drops, with ISO 13485 certification tier and geographic delivery cost as primary differentiation drivers. Cost compression in biodegradable polymer formulations is intensifying because PLGA resin prices fluctuate with caprolactone availability. Home care settings in Maharashtra absorb the most price-sensitive volume, while United States ambulatory surgical centers show lowest sensitivity where reimbursement covers device premiums.
Supply Chain Analysis
Japan and Germany anchor pharmaceutical-grade silicone oil production for intravitreal tamponade applications, with Osaka-based specialty chemical manufacturers feeding Bavarian contract manufacturers. The supply chain draws from PLGA and PCL resin feedstocks, laser-drilled microfluidic orifice components, and cleanroom assembly capacity. Single-source vulnerability concentrates in Japanese silicone oil supply, where three manufacturers control global pharmaceutical-grade output. Distribution runs through hospital purchasing cooperatives in Texas and California, displacing individual clinic procurement autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as retinal disease prevalence climbs and sustained-release technologies displace frequent injection protocols, with Medicare reimbursement stability providing cyclical support.
For Market Incumbents: Consolidate manufacturing scale through backward integration into polymer resin supply, capturing captive PLGA and PCL feedstock security against caprolactone volatility. Expand cleanroom capacity in Minnesota and Bavaria to serve pharmaceutical partnership demand for microfluidic reservoir fabrication. EyePoint Pharmaceuticals and Novartis face emerging pressure from suprachoroidal delivery specialists seeking to bypass intravitreal injection infrastructure entirely.
For New Entrants and Emerging Players: Lead with suprachoroidal microinjection platforms targeting Tier-2 Indian cities in Maharashtra and Tamil Nadu where sustained-release capabilities remain absent. The most penetrable segment lies in gene therapy convergence applications pairing AAV vectors with periocular delivery devices for inherited retinal diseases. A go-to-market angle anchored in safety differentiation from direct vitreal puncture protocols opens hospital formulary access faster than incremental intravitreal improvements.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors device-specialist acquisition targets with proprietary delivery platforms and regulatory pathway clarity. Long-term viability across the next decade rests on convergence between diagnostic imaging and injection robotics under EU AI Act compliance frameworks. The signal to watch is FDA combination product classification guidance convergence, which would compress development timelines and capital requirements for novel delivery systems.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR streamlines Class III ophthalmic implant approval for German and Swiss manufacturers. |
| Hospital System Partnership | Group purchasing organization consolidation in Texas and California locks in multi-year implant contracts. |
| Backward Integration | Captive PLGA resin production insulates margins from caprolactone feedstock price swings. |
| Reimbursement Strategy | IRA exclusion for qualifying implantable devices creates Medicare pricing advantages in United States markets. |
| Software Companion Development | EU AI Act compliance for imaging-guided injection robotics enables diagnostic-linked delivery platform renewal. |
Study Parameters
Cross-validation between primary interviews with ophthalmology clinic directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EMA CE marking databases, ClinicalTrials.gov entries, and CMS Medicare reimbursement schedules. Bottom-up and top-down triangulation reconciles device shipment data with pharmaceutical revenue disclosures across the analysis window.
Sensitivity analysis tests forecast robustness across alternative scenarios for regulatory pathway timing, polymer resin cost trajectories, and ambulatory surgical center adoption curves. The analytical framework models segmentation across product architecture, delivery mode, end-user setting, and regional regulatory cluster throughout the forecast period. CAGRs derive from logarithmic trend fitting to historical volume data, adjusted for technology substitution elasticities and reimbursement policy inflection points.
The analysis sits within stated boundaries; outcomes outside sustained FDA-EMA regulatory convergence or stable Medicare device reimbursement would require recalibration. Forecasts reflect documented assumptions regarding biodegradable polymer cost trajectories and ambulatory surgical center procedure migration rates. Recalibration cycles align with material shifts in combination product classification guidance and EU AI Act notified body interpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Prothrombin Complex Concentrate (PCC) Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Vaginal Antifungals Market