
 Apalutamide API Market | 2026-2036
Apalutamide API Market Size, Share, and Industry Trends Forecast 2026-2036
Apalutamide API Market Insights
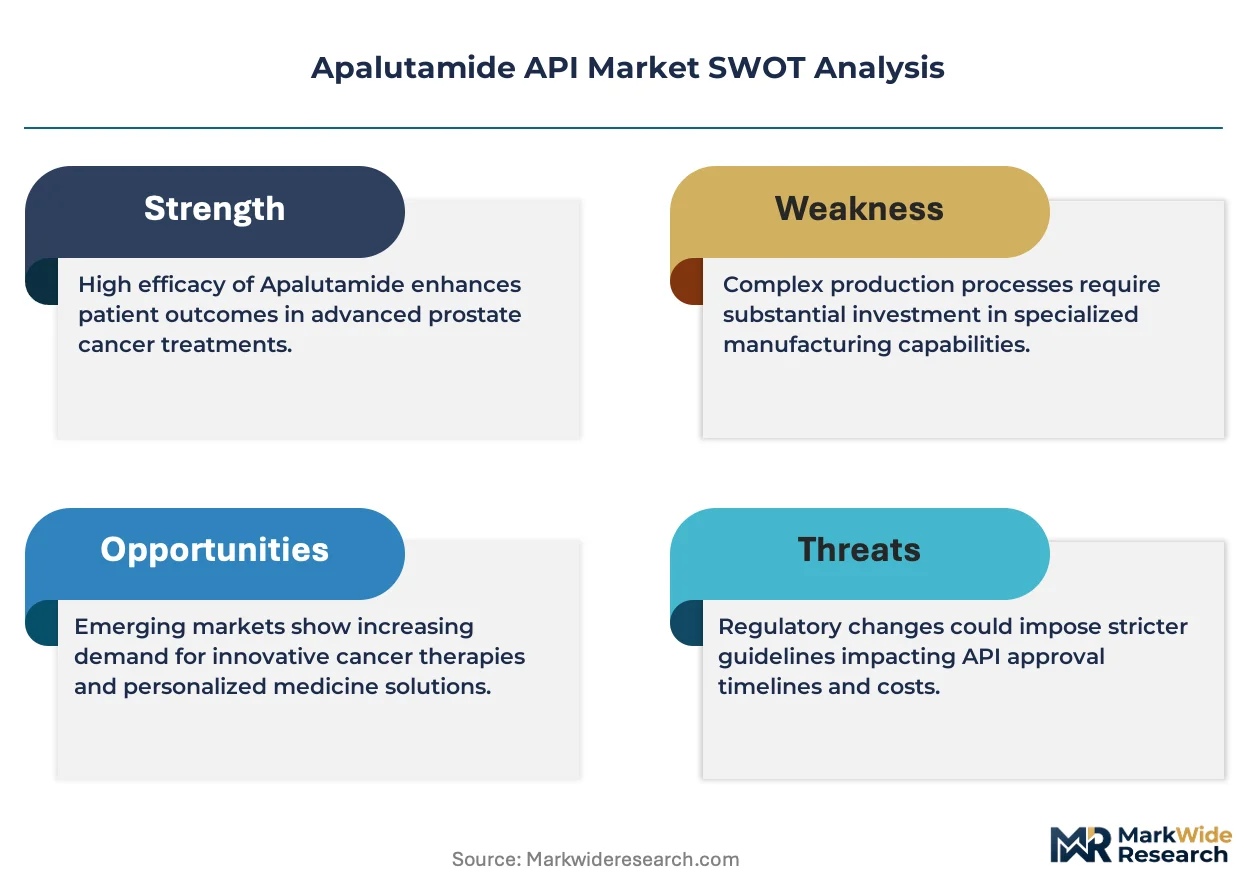
ICH Q7 Good Manufacturing Practice certification for active pharmaceutical ingredients is redrawing competitive boundaries in apalutamide API production. Viatris leverages its vertically integrated manufacturing footprint across North American and European facilities to sustain cost advantages in high-purity synthesis. Dr. Reddy's Laboratories anchors its position through dedicated oncology API capacity in Indian regulatory zones with USFDA and EMA accreditations. Sun Pharmaceutical Industries differentiates via backward integration into key starting materials, reducing exposure to intermediate supply volatility.
Apalutamide API refers to the synthetic active pharmaceutical ingredient of a non-steroidal androgen receptor inhibitor, typically manufactured through multi-step organic synthesis involving chiral resolution and crystallization to achieve pharmaceutical-grade purity exceeding 99.5%. The compound serves as the critical therapeutic component in oral formulations targeting androgen receptor signaling in prostate cancer. Tablet formulations occupy the largest volume share among product types due to established bioavailability profiles and patient compliance advantages in chronic oncology administration. Nanoformulations within the formulation dimension represent the fastest-expanding segment, driven by solubility enhancement demands for improved pharmacokinetic performance in combination therapies. Hospital end users command the dominant procurement position, though home care channels are gaining traction as oral oncology protocols shift toward decentralized administration models.
FDA oversight through Current Good Manufacturing Practice enforcement and the EMA's ICH Q11 guideline on development and manufacture of drug substances collectively elevate barrier thresholds for market participation. The Drug Enforcement Administration's controlled-substance scheduling protocols for precursor chemicals further constrain synthesis pathway choices available to manufacturers. CDSCO in India imposes parallel import licensing requirements that shape export-oriented production strategies for subcontinent-based suppliers. Stakeholders must monitor evolving pharmacopeial monograph revisions and bioequivalence study requirements as regulatory convergence between major health authorities accelerates.
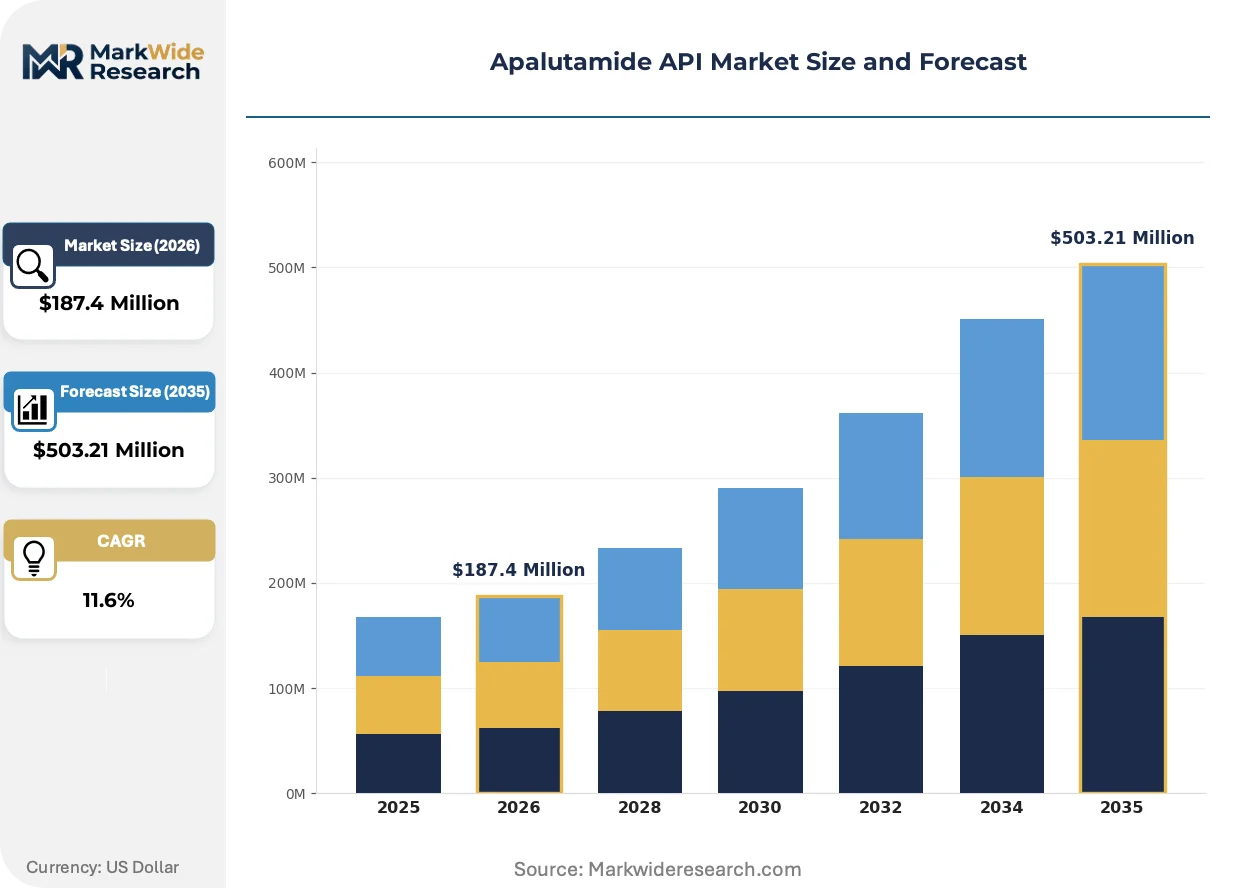
Market Dynamics
FDA tightening of ICH Q7 purity standards for active pharmaceutical ingredients is compressing margins for non-certified manufacturers while rewarding vertically integrated producers with multi-jurisdictional accreditations.
Growth Catalysts
- Metastatic castration-resistant prostate cancer protocols:Hospital oncology departments in the United States are expanding prescription volumes for next-generation androgen receptor inhibitors, directly expanding API demand.
- EMA ICH Q11 guideline harmonization:Convergence between FDA and European regulatory frameworks is reducing duplicative compliance burdens for accredited manufacturers, accelerating cross-border supply expansion.
- Nanoformulation solubility demands:Combination therapy development is driving investment in advanced particle engineering technologies for enhanced pharmacokinetic performance.
Market Restraints
- Precursor chemical scheduling:DEA controlled-substance protocols constrain synthesis pathway choices, limiting flexibility in route selection and elevating security compliance costs.
- Chiral resolution input volatility:Fluctuating availability and pricing of specialized chiral auxiliaries creates margin pressure for non-integrated manufacturers dependent on external intermediate sourcing.
- High-purity crystallization technical barriers:Achieving pharmaceutical-grade purity exceeding 99.5% requires capital-intensive equipment and specialized expertise that excludes smaller synthesis operations.
Strategic Opportunities
- Home care channel expansion:Decentralized oral oncology administration models are creating direct-to-patient distribution pathways that bypass traditional hospital procurement hierarchies.
- Indian CDSCO export licensing alignment:Streamlined parallel import requirements for USFDA-accredited facilities are enabling faster market access for subcontinent-based production capacity.
- Continuous flow synthesis convergence:Integration of flow chemistry with process analytical technology is opening pathways for real-time quality assurance and reduced batch failure rates.
Industry Challenges
- ICH Q7 certification timeline compression:Extended audit cycles and documentation requirements for new manufacturing facilities delay revenue generation by 18-24 months.
- Specialized oncology API workforce scarcity:Shortages of experienced synthetic organic chemists with GMP environment expertise constrain production scale-up velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apalutamide API Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable Solutions, Oral Solids End User: Hospitals, Clinics, Pharmacies, Home Care Therapy Area: Oncology, Urology, Hematology, Endocrinology Formulation: Immediate Release, Extended Release, Sustained Release, Nanoformulations |
| Companies Covered | Viatris, Hangzhou Synbest Biotech, Dr. Reddy's Laboratories, Sun Pharmaceutical Industries, Chengdu Zensunda Biopharmaceutical, Teva Pharmaceutical Industries, Shandong Haohong Biotechnology, Cipla Limited, Olon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apalutamide API Market Trends and Innovations
Manufacturing technology evolution and regulatory convergence are restructuring competitive advantage around real-time quality verification and flexible production architectures rather than batch-scale economies alone.
Continuous flow chemistry systems are displacing traditional batch reactors in high-value API synthesis. Contract development and manufacturing organizations serving oncology portfolios are adopting these platforms for improved heat transfer control and reduced solvent volumes. This displacement is compressing minimum efficient scale thresholds and enabling regionalized production footprints closer to formulation sites.
EMA's ICH Q11 guideline on development and manufacture of drug substances is harmonizing technical requirements across European and FDA jurisdictions. Manufacturers must now demonstrate enhanced process understanding and control strategy robustness from early development phases. Oncology API specialists with dual USFDA-EMA accreditations are capturing disproportionate share of new product introductions as sponsors prioritize streamlined regulatory pathways.
Hospital procurement consortiums are consolidating purchasing authority for oral oncology APIs through centralized tender mechanisms. Traditional distributor networks serving individual oncology centers are losing volume to direct manufacturer-contracting models. This concentration is most visible in United States health system alliances, where three to five procurement entities now control majority addressable spend for next-generation hormonal therapies.
Apalutamide API Market Segmentation
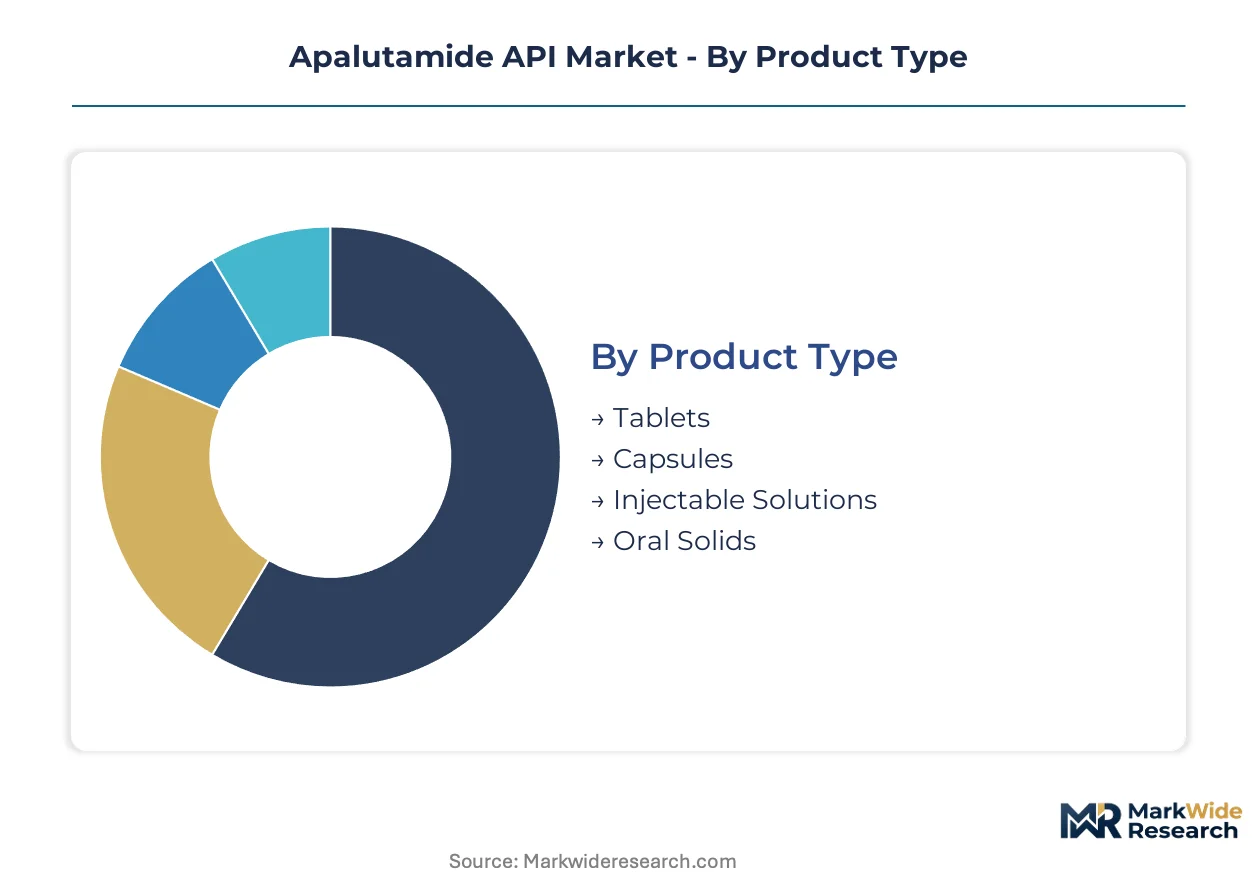
Apalutamide API demand fragments across four structural dimensions that shape procurement patterns and manufacturing priorities. Each category carries distinct technical specifications, regulatory pathways, and customer concentration profiles that determine competitive positioning.
Product Type:
Domestic consumption concentrates in oral solid formats favored by US hospital formularies, while export-led demand from European and Asian markets shows rising interest in alternative delivery systems.
- Tablets:Compressed oral dosage forms with established dissolution profiles dominate hospital oncology procurement in the United States. FDA bioequivalence requirements for generic entrants reinforce incumbent API supplier relationships.
- Capsules:Gelatin or HPMC shell delivery systems enable flexible dosing titration for combination therapy protocols. European EMA filings increasingly specify capsule formulations to accommodate patient-specific dosing regimens in Germany and France.
- Injectable Solutions:Parenteral formats for acute care settings requiring rapid therapeutic onset.
- Oral Solids:Granules and powders for compounding pharmacies serving specialized patient populations.
Tablets command the established base. The steepest expansion runs through Nanoformulations.
End User:
Procurement authority clusters differently across cost tiers, with premium-priced hospital networks demanding certified supply chains and economy channels prioritizing volume discounts.
- Hospitals:Integrated health systems with centralized purchasing control the majority volume in the United States. Three to five procurement consortiums now direct majority addressable spend for next-generation hormonal therapies.
- Clinics:Outpatient oncology centers with direct physician dispensing authority capture growing share as oral oncology administration decentralizes.
- Pharmacies:Retail and specialty pharmacy networks serving insured patient populations with prior authorization requirements.
- Home Care:Direct-to-patient distribution channels bypassing traditional institutional procurement hierarchies, gaining traction as oral protocols enable remote administration.
Hospitals retain volume leadership. Home Care channels are climbing the fastest.
Therapy Area:
Application maturity varies sharply, with oncology commanding specialized manufacturing investments while adjacent therapeutic areas leverage existing hormonal synthesis capacity.
- Oncology:Metastatic castration-resistant prostate cancer treatment protocols drive specialized high-purity synthesis requirements. US hospital oncology departments are expanding prescription volumes for next-generation androgen receptor inhibitors.
- Urology:Benign prostatic hyperplasia and localized prostate cancer applications with overlapping androgen pathway targeting.
- Hematology:Investigational applications in androgen-sensitive hematologic malignancies with emerging clinical trial demand.
- Endocrinology:Hormonal modulation applications outside oncologic indications with lower purity grade requirements.
Oncology anchors manufacturing specialization. Urology offers the most accessible expansion pathway.
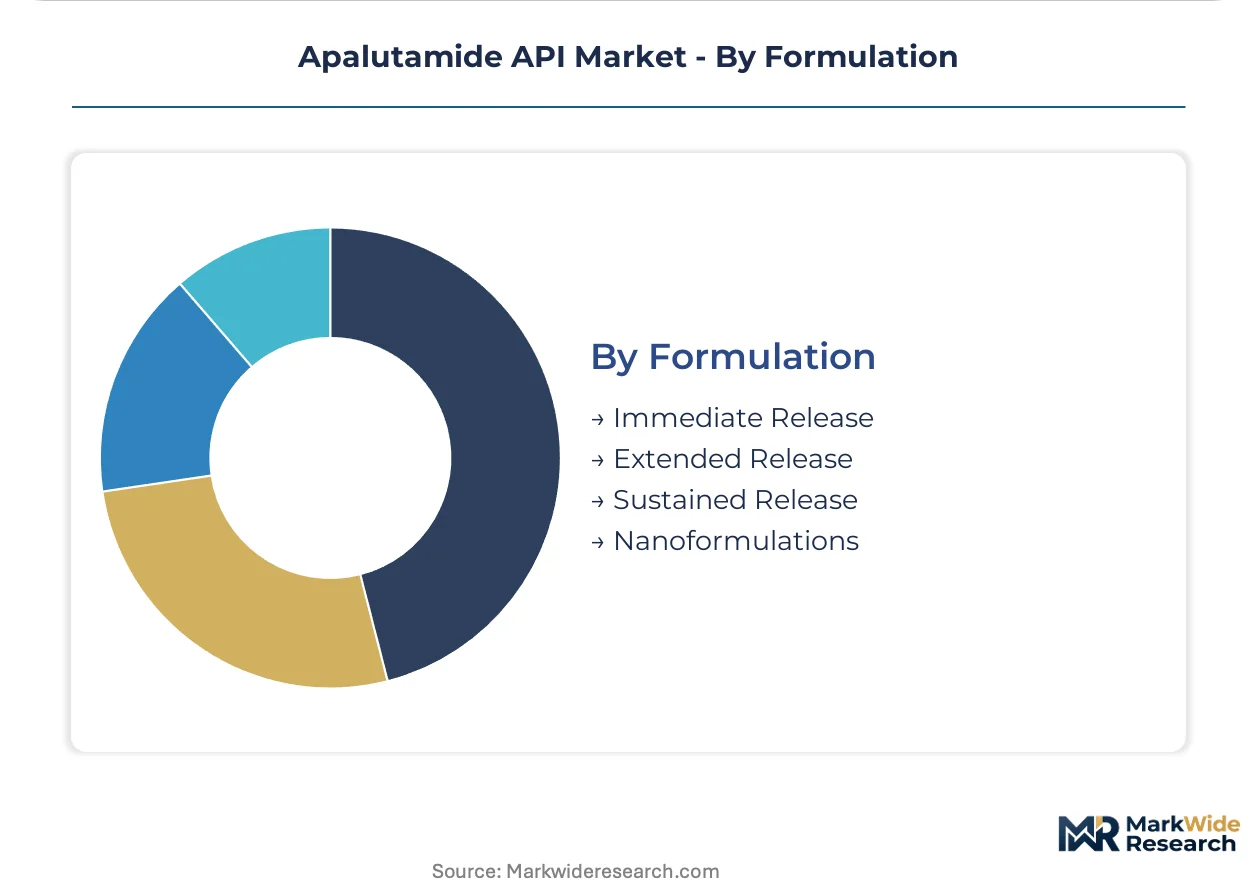
Formulation:
Supply concentration favors immediate-release platforms with established equipment footprints, while advanced delivery technologies require capital-intensive particle engineering investments.
- Immediate Release:Conventional dissolution profiles with shortest development timelines and lowest regulatory burden. Majority of current ANDA filings specify this format for fastest market entry.
- Extended Release:Matrix or reservoir systems enabling reduced dosing frequency for improved patient compliance in chronic administration.
- Sustained Release:Polymeric delivery systems with zero-order kinetics for stable plasma concentration maintenance.
- Nanoformulations:Advanced particle engineering for solubility enhancement and improved pharmacokinetic performance in combination therapies. Investment is accelerating as sponsors pursue bioavailability advantages for difficult-to-formulate compounds.
Immediate Release dominates current production capacity. Nanoformulations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites European distribution of high-purity oncology APIs, while direct container routes from Mumbai and Shanghai connect Asian synthesis hubs to North American formulation sites.
United States
Hospital oncology consortiums in Texas and Florida are expanding formulary access to next-generation androgen receptor inhibitors. FDA's ICH Q7 enforcement through 2024 facility inspections has disqualified three non-compliant API suppliers. The New Jersey-Philadelphia corridor hosts the densest concentration of USFDA-accredited contract manufacturers serving oral oncology.
India
CDSCO's streamlined export licensing for USFDA-accredited facilities is accelerating shipments to European formulation sites. The Hyderabad-Bengaluru pharmaceutical belt now accounts for the majority of Indian oncology API capacity additions. Dr. Reddy's Laboratories anchors dedicated synthesis operations in this zone with dual USFDA-EMA accreditations.
Germany
EMA's ICH Q11 guideline harmonization has reduced duplicative documentation burdens for Frankfurt and Munich-based formulation sponsors. The country's national pharmaceutical regulator enforces batch-release protocols that exceed baseline EU requirements. Bavaria's chemical-industrial complex supports specialized chiral intermediate production for API manufacturers.
China
NMPA's 2024 revision to drug substance registration rules is elevating documentation standards for domestic API exporters. The Yangtze River Delta concentration of fine chemical producers supplies key starting materials to global apalutamide synthesis networks. Zhejiang and Jiangsu provinces are upgrading cGMP infrastructure to meet FDA inspection frequency.
Switzerland
Swissmedic's convergence with EMA centralized procedures is attracting sponsor companies seeking streamlined European market access. Basel's pharmaceutical cluster specializes in high-potency API containment and handling for oncology applications. The country's bilateral recognition agreements with FDA reduce redundant facility audits for qualified manufacturers.
Apalutamide API Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded pharmaceutical conglomerates holding scale advantages in multi-jurisdictional regulatory filings while private entities capture niche high-purity synthesis contracts. The vendor base organizes around three archetypes: vertically integrated innovators with captive raw material supply, regulatory specialists holding dual USFDA-EMA accreditations, and regional cost-optimized producers serving emerging market formulation sites. Dominant competitive moves include strategic partnerships for continuous flow technology licensing and geographic expansion through CDSCO-aligned Indian export licensing.
Among US- and India-based manufacturers, Viatris, Dr. Reddy's Laboratories, and Sun Pharmaceutical Industries occupy positions across distinct competitive vectors. Viatris represents the integrated multinational archetype with North American and European manufacturing footprints. Dr. Reddy's Laboratories exemplifies the regulatory specialist model through dedicated oncology API capacity in Indian zones with dual accreditation status. Sun Pharmaceutical Industries anchors a position emphasizing backward integration into key starting materials.
| Leading Market Players |
|---|
| Viatris |
| Hangzhou Synbest Biotech |
| Dr. Reddy's Laboratories |
| Sun Pharmaceutical Industries |
| Chengdu Zensunda Biopharmaceutical |
| Teva Pharmaceutical Industries |
| Shandong Haohong Biotechnology |
| Cipla Limited |
| Olon |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for chiral intermediates concentrate pricing power among manufacturers with captive key starting material production, while spot-market buyers absorb volatility from DEA-controlled precursor scheduling. Contract structures stratify across ICH Q7-certified premium tiers, standard multi-jurisdictional grades, and economy batches serving emerging market formulation sites.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with FDA-EMA dual-accredited facilities commanding 15-20% spreads over single-jurisdiction suppliers. Price differentiation rests on certification tier and volume scale, with hospital consortiums leveraging centralized tender authority for annual offtake commitments. Cost compression in the economy tier is intensifying because Indian CDSCO export licensing has expanded qualified supplier pools. Retail pharmacy networks exhibit highest price sensitivity due to prior authorization friction, while integrated health systems prioritize supply security over unit cost.
Supply Chain Analysis
Strait of Malacca transit routes anchor 60% of global chiral auxiliary shipments, creating vulnerability concentration for non-integrated synthesis operations. Manufacturing gravity centers on India, China, and the United States, with the Hyderabad-Bengaluru belt and Yangtze River Delta feeding key starting materials to European formulation sites. Raw material dependencies draw from specialized chiral resolution agents, palladium catalysts, and controlled-substance precursors subject to DEA quota allocation. Single-source vulnerability runs through Swiss-German chiral intermediate specialists. Distribution runs through Rotterdam cold-chain hubs for European hospital networks and direct container routes from Mumbai to New Jersey-Philadelphia corridor formulation sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as continuous flow synthesis interoperability standards enable modular manufacturing networks, replacing fixed-batch asset dominance with flexible capacity orchestration.
For Market Incumbents: Consolidate through selective acquisition of CDSCO-aligned Indian export licensees to secure volume positions in decentralized oral oncology channels. Prioritize ICH Q11 documentation investments to accelerate EMA-FDA pathway convergence for combination therapy nanoformulations. Vertical integration into palladium catalyst recovery systems defends margin positions against precious metal price volatility.
For New Entrants and Emerging Players: Differentiate on continuous flow technology platforms offering real-time quality verification to contract development organizations serving mid-tier oncology sponsors. Target home care channel distribution partnerships bypassing hospital procurement consortiums. Penetrate European capsule formulation demand through EMA-aligned regulatory specialists with flexible dosing titration capabilities.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical conglomerates divesting non-core oncology API assets to refocus on novel biologic platforms. Long-term viability hinges on dual-accreditation maintenance costs versus regional cost-optimized competitor expansion. Monitor DEA precursor quota expansion decisions as inflection signal for synthesis pathway economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Technology Licensing | Enables real-time process analytical technology integration for batch failure reduction. |
| Dual USFDA-EMA Accreditation Investment | Captures disproportionate share of sponsor new product introductions. |
| Backward Integration into Chiral Intermediates | Reduces exposure to Swiss-German specialist supply volatility. |
| Home Care Channel Partnership Development | Bypasses consolidated hospital procurement consortium purchasing authority. |
| Nanoformulation Particle Engineering Scale-Up | Addresses solubility enhancement demands for combination therapy protocols. |
Research Methodology
Initial hypotheses were tested against primary input from oncology API manufacturing executives, hospital formulary directors, regulatory affairs leads, and CDSCO licensing officers and refined through secondary validation against FDA 483 inspection records, EMA centralized procedure filings, and Indian pharmaceutical export trade data. Bottom-up capacity assessments across Hyderabad-Bengaluru and Yangtze River Delta production zones were triangulated with top-down prescription volume projections from Medicare Part D claims and hospital procurement consortium tender awards.
Variance decomposition across the projection horizon isolates volume, price, and mix contributions to value expansion, with segmentation dimensions spanning product type, end user channel, therapy area, and formulation complexity. CAGRs were derived from regression-adjusted prescription growth curves and capacity utilization assumptions. Forecast inputs incorporate DEA controlled-substance scheduling protocols, ICH Q7 audit cycle durations, and nanoformulation bioequivalence study completion rates.
Material uncertainties — regulatory inspection disqualifications, precursor chemical quota revisions, and pharmacopeial monograph updates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding accreditation maintenance and channel shift velocity. Practitioners should keep alternative scenarios live as FDA-EMA inspection harmonization and Indian export licensing streamlining evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Wujibaifeng Pills Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Asia Pacific Drug Development Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Throat Sprays Market
Pharmaceuticals
Stomach Cancer Drugs Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Global Viral Vaccines Market