
 H2-Receptor Antagonists Market | 2026-2036
H2-Receptor Antagonists Market Size, Share, and Industry Trends Forecast 2026-2036
H2-Receptor Antagonists Market Foresight
FDA ranitidine withdrawal mandates and EMA contamination alerts are consolidating the competitive landscape around residual H2-receptor antagonist suppliers. Pfizer Inc. leverages its manufacturing scale to sustain tablet and injectable famotidine supply across hospital networks. Boehringer Ingelheim International GmbH anchors European distribution through its established gastrointestinal therapeutic portfolio. GlaxoSmithKline plc competes in retail pharmacy channels with differentiated over-the-counter positioning.
H2-receptor antagonists are competitive histamine H2-receptor blockers that suppress gastric acid secretion by inhibiting parietal cell proton pump activation, with famotidine offering superior receptor binding affinity and longer duration of action than cimetidine. These agents serve primary commercial purposes in managing acid-related disorders where proton pump inhibitor therapy is contraindicated or cost-prohibitive. Tablet dosage forms dominate volume due to outpatient prescribing convenience, while injection formulations command premium positioning in acute hospital settings. Gastroesophageal reflux disease represents the largest therapy area by patient volume, though peptic ulcer disease applications retain stronger reimbursement profiles in several markets.
FDA bioequivalence standards, EMA good manufacturing practice inspections, and national pharmacovigilance reporting requirements collectively elevate compliance costs for active pharmaceutical ingredient sourcing and finished dose production. Health Canada and WHO prequalification programs further shape export market access for manufacturers targeting regulated procurement channels. Stakeholders must monitor evolving impurity testing protocols and therapeutic guideline revisions that could redirect prescribing between H2 antagonists and alternative acid suppression therapies.
Market Dynamics
Ranitidine withdrawals have triggered a supply-side consolidation that concentrates procurement power among residual famotidine manufacturers serving hospital networks and retail pharmacy chains.
Growth Catalysts
- FDA bioequivalence mandates:Accelerated generic famotidine approvals are expanding therapeutic access while compressing pricing premiums for originator products.
- Hospital formulary restructuring:P&T committees are systematically replacing ranitidine-based protocols with famotidine alternatives across emergency and surgical departments.
- Injectable formulation demand:Acute care settings are prioritizing intravenous H2 antagonists where proton pump inhibitor therapy carries bleeding risk contraindications.
Market Restraints
- Active pharmaceutical ingredient concentration:Chinese and Indian API suppliers control over 70% of famotidine chemical precursor output, creating single-source vulnerability.
- Nitrosamine impurity surveillance:FDA and EMA testing protocols for NDMA-related contaminants impose batch-level analytical costs that erode margin structures for finished dose manufacturers.
- Proton pump inhibitor substitution:Omeprazole and esomeprazole generics have captured maintenance therapy prescriptions previously held by H2 antagonists in ambulatory settings.
Strategic Opportunities
- Pediatric indication expansion:Neonatal intensive care units represent an underpenetrated segment where famotidine pharmacokinetics offer advantages over acid suppression alternatives.
- EMA centralized procedure acceleration:Mutual recognition pathways are reducing time-to-market for generic injectable formulations seeking European hospital procurement contracts.
- Direct-to-hospital distribution:Bypassing wholesale intermediaries allows manufacturers to capture margin and secure multi-year tender agreements with integrated delivery networks.
Industry Challenges
- Analytical chemistry talent scarcity:Nitrosamine detection and method validation require specialized chromatography expertise that contract laboratories struggle to staff.
- Legacy equipment retrofitting:Continuous manufacturing transitions demand capital deployment that mid-scale generic facilities cannot access at competitive cost.
- Cross-reference dossier complexity:ANDA submissions citing withdrawn ranitidine comparators trigger additional FDA clinical pharmacology review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | H2-Receptor Antagonists Market |
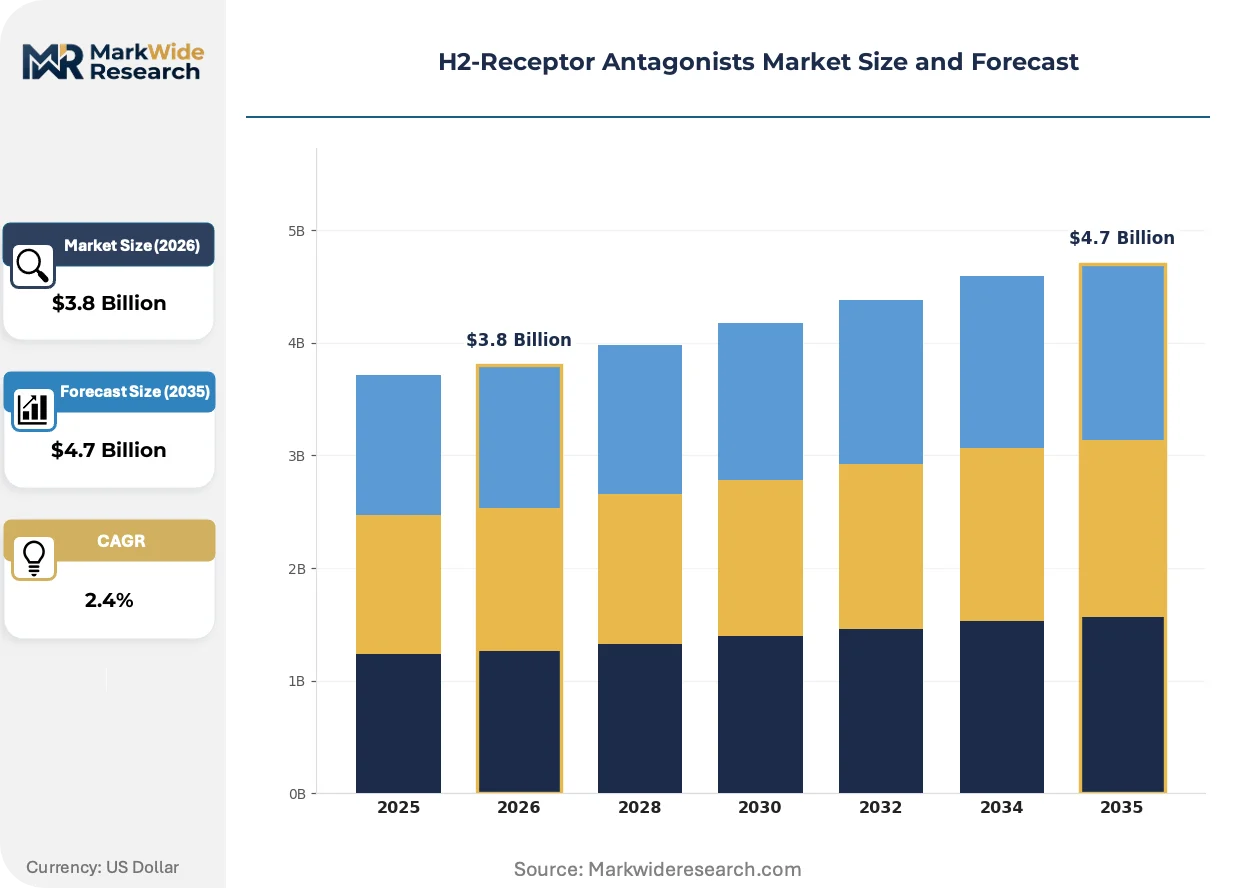
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ranitidine, Famotidine, Nizatidine, Cimetidine Dosage Form: Tablet, Injection, Oral Solution, Capsule End User: Hospitals, Clinics, Online Pharmacies, Retail Pharmacies Therapy Area: Gastroesophageal Reflux Disease, Peptic Ulcer Disease, Zollinger-Ellison Syndrome, Others |
| Companies Covered | Sanofi S.A., Boehringer Ingelheim International GmbH, Pfizer Inc., Takeda Pharmaceutical Company Limited, Novartis AG, GlaxoSmithKline plc, Johnson & Johnson, Abbott Laboratories, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
H2-Receptor Antagonists Market Shifts & Advancements
Formulation science and regulatory chemistry are converging to redefine competitive advantage in acid suppression therapeutics, with impurity control and delivery mechanism innovation displacing traditional marketing-led differentiation.
Modified-release famotidine tablet technologies are rewriting outpatient therapy adherence patterns. Extended-duration formulations reduce dosing frequency from twice-daily to single-daily administration. Hospital discharge planners are prioritizing these products for transitional care protocols where compliance failures drive readmission risk.
EMA nitrosamine risk assessment guidelines are forcing reformulation investments across the European generic landscape. Manufacturers must demonstrate absence of genotoxic impurities through enhanced analytical procedures. German and French hospital procurement consortia are now requiring Certificates of Suitability that document validated control strategies.
Specialty pharmacy channels are capturing H2 antagonist volume previously flowing through retail chains. Patients with complex gastrointestinal comorbidities receive coordinated medication management through these platforms. United States integrated delivery networks are consolidating outpatient prescribing through captive specialty pharmacy arrangements that favor contracted manufacturers.
H2-Receptor Antagonists Market Segmentation
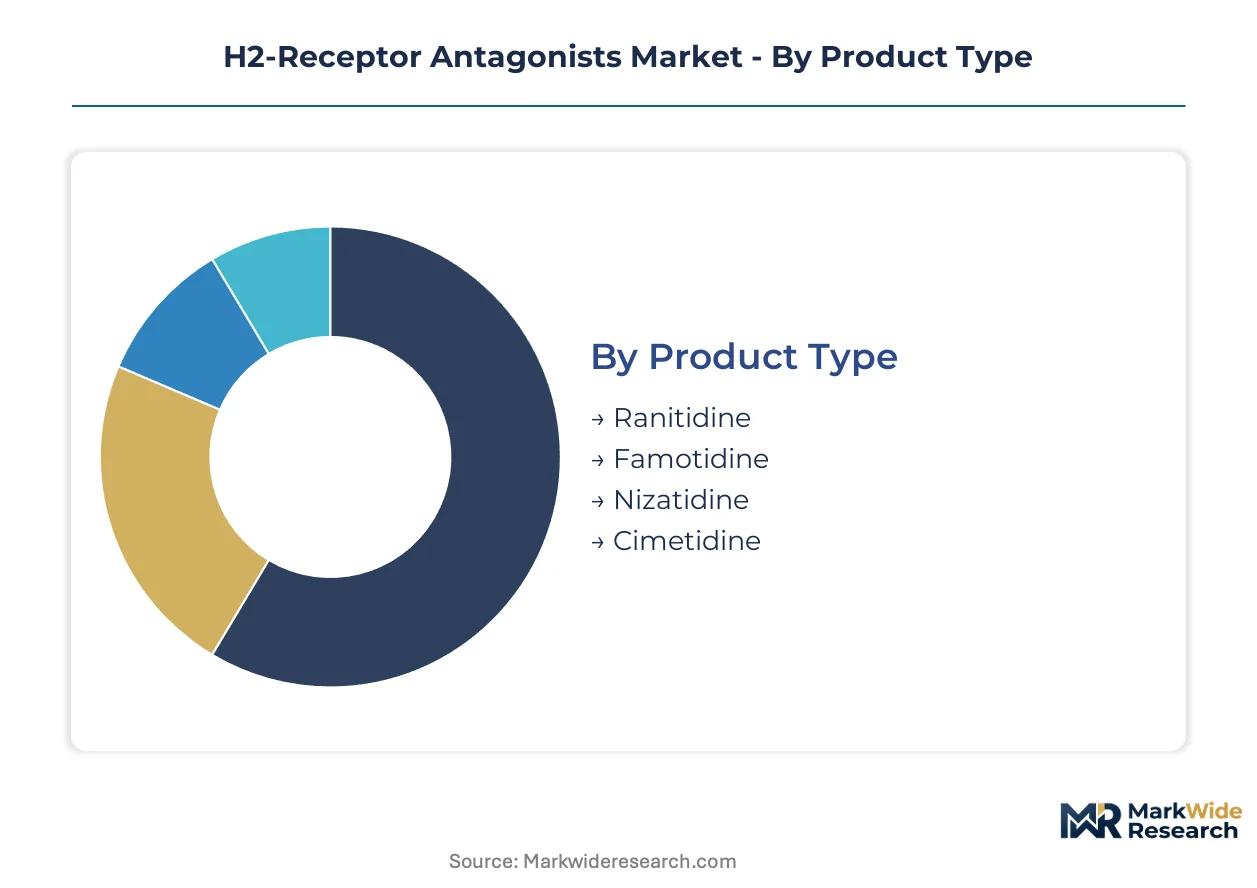
H2-receptor antagonist procurement patterns diverge sharply across clinical settings and patient acuity levels. Hospital formulary decisions, retail pharmacy substitution dynamics, and specialty distribution channels each favor distinct product configurations and dosage forms.
Product Type:
Prescriber confidence and regulatory clearance status now determine molecule selection more than historical market share.
- Famotidine:Superior receptor binding affinity and established cardiovascular safety profile position this agent as the default replacement for withdrawn ranitidine protocols. Hospital P&T committees in the United States have systematically adopted famotidine as the standard-of-care H2 antagonist across emergency departments and surgical units.
- Ranitidine:Regulatory withdrawals by FDA and EMA have eliminated commercial viability, though residual inventory monitoring continues for pharmacovigilance purposes. Trace contamination concerns with NDMA and related nitrosamines triggered complete market exit.
- Cimetidine:First-generation H2 blocker retains niche utility where drug interaction profiles are manageable and cost constraints dominate prescribing decisions.
- Nizatidine:Limited commercial presence concentrates in specific managed care formularies where prior authorization pathways favor this molecule over alternatives.
Famotidine sits at the top of the volume ranking, with cimetidine climbing the fastest among residual alternatives in cost-sensitive procurement channels.
Dosage Form:
Route of administration directly correlates with care setting reimbursement rates and clinical urgency requirements.
- Tablet:Outpatient prescribing convenience drives volume dominance, with modified-release formulations gaining traction in transitional care protocols. United States retail pharmacy chains prioritize tablet SKUs for maintenance therapy prescriptions.
- Injection:Intravenous famotidine commands premium positioning in acute care settings where proton pump inhibitor therapy carries bleeding risk contraindications. Hospital procurement consortia negotiate multi-year tender agreements for injectable supply security.
- Oral Solution:Pediatric and geriatric populations with swallowing difficulties generate concentrated demand through specialty pharmacy channels.
- Capsule:Limited differentiation from tablets restricts capsule adoption to specific regional preferences and legacy formulary listings.
Tablet formulations capture the highest prescription volumes, while injectable demand is expanding most quickly as hospital protocols shift toward acute-care H2 antagonist administration.
End User:
Channel consolidation and vertical integration are reshaping how manufacturers reach prescriber decision-makers.
- Hospitals:Integrated delivery networks consolidate purchasing power through centralized procurement offices that negotiate multi-year therapeutic contracts. Formulary restriction policies increasingly limit H2 antagonist selection to single-source famotidine agreements.
- Retail Pharmacies:Generic substitution mandates and therapeutic interchange programs drive volume toward lowest-cost famotidine suppliers. Major chains leverage scale to extract pricing concessions through direct manufacturer relationships.
- Clinics:Ambulatory surgical centers and gastrointestinal specialty practices represent fragmented demand with limited bargaining leverage.
- Online Pharmacies:Direct-to-consumer channels capture maintenance therapy refills, though regulatory scrutiny of telehealth prescribing patterns is intensifying.
Hospitals command the largest procurement volumes, with online pharmacies gaining share fastest as patient convenience preferences reshape refill behavior.
Therapy Area:
Reimbursement coding and clinical guideline positioning determine which indications support viable commercial returns.
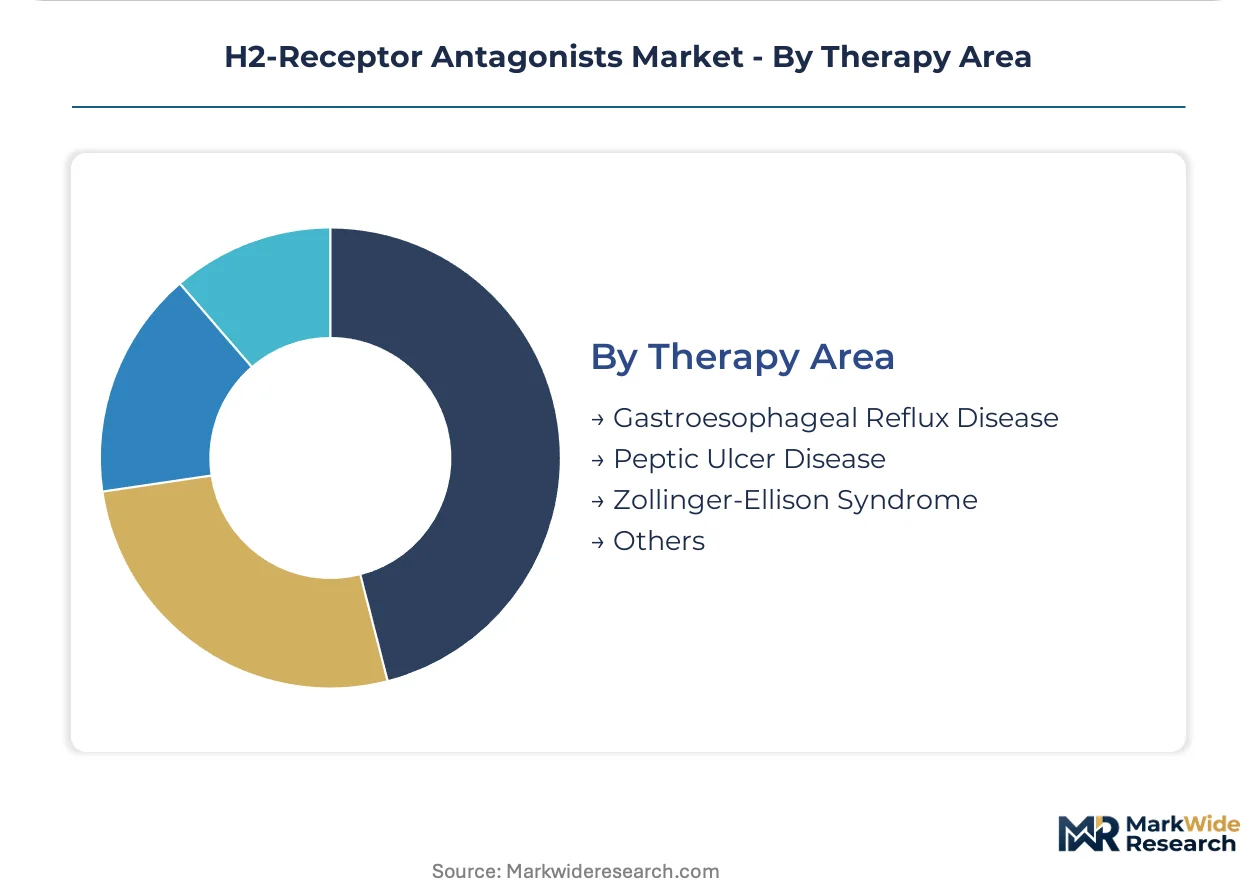
- Gastroesophageal Reflux Disease:Largest patient population by volume, though proton pump inhibitor substitution has eroded maintenance therapy market share. Step-therapy protocols in United States commercial insurance plans often require H2 antagonist failure before PPI authorization.
- Peptic Ulcer Disease:Stronger reimbursement profiles persist in several markets where H. pylori eradication protocols incorporate H2 antagonists as adjunctive therapy. Hospital inpatient DRG coding favors ulcer diagnoses for resource allocation.
- Zollinger-Ellison Syndrome:Rare indication with ultra-orphan pricing potential, though limited patient counts constrain commercial significance.
- Others:Stress ulcer prophylaxis in critical care and NSAID-associated gastropathy prevention represent secondary applications with variable guideline support.
Gastroesophageal reflux disease sits at the top of the volume ranking, with Zollinger-Ellison syndrome demonstrating the steepest expansion trajectory on a percentage basis from minimal base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical manufacturing clusters and hospital procurement networks anchor famotidine production and distribution across concentrated geographic zones. Regulatory divergence between FDA, EMA, and national pharmacovigilance agencies shapes market access patterns. Manufacturing scale and formulary influence concentrate competitive positioning in specific metropolitan hubs.
United States
Hospital procurement consortia and integrated delivery networks drive concentrated demand for injectable famotidine formulations. FDA bioequivalence mandates and ranitidine withdrawal protocols have accelerated generic substitution rates. The New Jersey-Pennsylvania pharmaceutical corridor hosts active pharmaceutical ingredient synthesis and finished dose manufacturing for domestic hospital supply.
Germany
EMA centralized marketing authorization procedures position German hospital networks as reference markets for European famotidine procurement. The country's national pharmaceutical regulator enforces stringent nitrosamine impurity testing protocols that exceed baseline EU requirements. The Rhine-Main manufacturing belt concentrates sterile injectable production facilities serving hospital tenders across Central Europe.
Japan
PMDA post-marketing surveillance requirements and geriatric dosing guidelines sustain distinct famotidine formulation preferences. The country's national health insurance reimbursement system maintains separate pricing categories for originator and generic H2 antagonists. The Kansai region's Osaka-Kobe pharmaceutical cluster specializes in modified-release tablet technologies for outpatient maintenance therapy.
India
CDSCO manufacturing facility inspections and WHO prequalification programs govern export-oriented famotidine API production. The country's pharmaceutical regulator has intensified oversight of nitrosamine control strategies at active pharmaceutical ingredient sites. Gujarat's Ahmedabad-Vadodara corridor dominates chemical precursor synthesis for global generic formulation supply.
United Kingdom
NHS England formulary restriction policies have systematically consolidated H2 antagonist prescribing toward single-source famotidine agreements. The Medicines and Healthcare products Regulatory Agency maintains accelerated review pathways for generic injectable formulations. The Southeast England pharmaceutical corridor supports hospital network distribution through specialized cold-chain logistics infrastructure.
H2-Receptor Antagonists Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established hospital contracting infrastructure. Market concentration remains moderate as ranitidine withdrawals eliminated a major therapeutic option while expanding residual supplier market share. Three archetypes dominate: originator manufacturers with legacy brand equity, generic specialists with API-to-finished-dose integration, and hospital-focused contract manufacturers. Capacity rationalization and direct-to-hospital distribution partnerships represent the primary competitive vectors reshaping supplier relationships.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Boehringer Ingelheim International GmbH exemplify the hospital-contracting archetype through established gastrointestinal therapeutic portfolios. Sanofi S.A. occupies a position reflecting originator-scale manufacturing and European distribution reach. These entities anchor competitive positioning through formulary influence and multi-year tender agreements with integrated delivery networks.
| Leading Market Players |
|---|
| Sanofi S.A. |
| Boehringer Ingelheim International GmbH |
| Pfizer Inc. |
| Takeda Pharmaceutical Company Limited |
| Novartis AG |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Abbott Laboratories |
| AstraZeneca plc |
| Others |
Supply & Pricing Matrix
EMA nitrosamine risk assessment guidelines gate qualified supply for European hospital procurement, permitting premium-tier pricing access only to manufacturers with validated Certificates of Suitability demonstrating impurity control strategies. Chinese and Indian API producers without enhanced analytical capabilities face exclusion from German and French hospital tender agreements, compressing their pricing power to commodity generic channels.
Pricing Analysis
Bundled service agreements covering nitrosamine testing and regulatory documentation command 15-25% premiums over unbundled product-only transactions in hospital procurement. Pricing stratifies across premium, standard, and economy tiers based on certification grade and geographic delivery cost, with FDA-approved facilities capturing the top tier. Cost compression in economy-grade tablet supply is intensifying because retail pharmacy chains leverage generic substitution mandates to extract volume discounts. Hospital procurement consortia demonstrate least price sensitivity due to formulary restriction policies, while retail pharmacies exhibit highest sensitivity driven by therapeutic interchange programs.
Supply Chain Analysis
Workforce availability constraints in analytical chemistry constrain batch-release capacity at Gujarat and Hyderabad manufacturing clusters, extending lead times for validated famotidine API. Supply concentrates in India and China for chemical precursor synthesis, with the United States and Germany hosting finished dose formulation. Raw material dependencies include acetic anhydride, sulfur-containing intermediates, and specialized chromatography resins for impurity detection. Single-source vulnerability from concentrated Chinese API output creates structural risk. Distribution runs through hospital procurement consortia and wholesale intermediaries serving retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as hospital formularies shift demand toward premium-certified famotidine suppliers with demonstrated nitrosamine control. The withdrawal of ranitidine has eliminated low-cost alternatives, elevating specification compliance above price in procurement decisions.
For Market Incumbents: Deepen backward integration into API production to secure supply continuity against Indian and Chinese precursor concentration. Pfizer and Boehringer Ingelheim should expand sterile injectable capacity in the Rhine-Main corridor to capture EMA centralized procedure acceleration. Investment in pediatric indication dossiers creates defensive moats against proton pump inhibitor substitution in neonatal intensive care.
For New Entrants and Emerging Players: Specialty pharmacy channel partners offer the most accessible entry pathway for differentiated oral solution formulations targeting geriatric and pediatric populations. White-space targets include direct-to-hospital distribution bypassing wholesale intermediaries, and modified-release tablet technologies for transitional care protocols. The United Kingdom's NHS England single-source tender structure presents the most penetrable geography for contracted supply agreements.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale generic manufacturers with API-to-finished-dose integration because hospital procurement consolidation favors suppliers with captive supply security. Long-term viability hinges on nitrosamine testing infrastructure and EMA regulatory access. Acquisition targets should demonstrate validated control strategies and existing hospital tender relationships. The signal to watch is FDA enforcement action against residual ranitidine inventory, which would accelerate famotidine demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Centralized Procedure Acceleration | Reduces time-to-market for generic injectables seeking German hospital procurement contracts. |
| Pediatric Indication Expansion | Captures neonatal intensive care volume where famotidine pharmacokinetics outperform alternatives. |
| Direct-to-Hospital Distribution | Bypasses wholesale intermediaries to secure multi-year tender agreements with integrated delivery networks. |
| Modified-Release Formulation Development | Addresses hospital discharge planner priorities for transitional care compliance. |
| Nitrosamine Testing Infrastructure Investment | Enables Certificates of Suitability required by French and German procurement consortia. |
Research Methodology
Direct dialogue with hospital formulary directors, pharmaceutical procurement managers, regulatory affairs specialists, and contract manufacturing executives grounded qualitative insights. Secondary validation drew from FDA bioequivalence filings, EMA centralized marketing authorization records, CDSCO manufacturing facility inspection reports, and hospital procurement database aggregators. Bottom-up prescription volume modeling and top-down therapeutic category sizing were triangulated against manufacturer-reported segment revenues.
Segmentation outputs across molecule type, dosage form, end user channel, and therapy area were generated through the analytical framework applied across the projection horizon. CAGRs were derived from regression analysis against historical substitution patterns and regulatory event impacts. Forecast inputs included P&T committee adoption timelines for famotidine protocols, nitrosamine testing protocol implementation rates, and proton pump inhibitor generic erosion curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA enforcement actions on residual ranitidine inventory, EMA impurity guideline revisions, and Chinese API supply disruptions. Forecasts reflect assumptions regarding hospital formulary restructuring velocity and therapeutic guideline positioning. Material deviation in ranitidine withdrawal compliance timelines or nitrosamine detection methodology changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Global Combination Vaccine Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Drug Designing Tools Market
Pharmaceuticals
Inotropic Agent Market
Pharmaceuticals
Trulicity Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
North America Anesthesia Drugs Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market