
 Myasthenia Gravis Therapeutics Market | 2026-2036
Myasthenia Gravis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Myasthenia Gravis Therapeutics Market Foresight
Biologic drug substances are consolidating position against small-molecule immunosuppressants in myasthenia gravis treatment economics. Novartis AG leverages its neuroscience franchise to sustain commercial infrastructure across neurology centers. argenx SE anchors its presence through FcRn inhibitor specialization, while Alexion Pharmaceuticals competes via complement pathway expertise.
Myasthenia gravis therapeutics comprise pharmaceutical and procedural interventions targeting autoimmune-mediated neuromuscular transmission failure, with monoclonal antibodies engineered to specific immunoglobulin G half-life extension or complement cascade interruption. These therapies restore acetylcholine receptor signaling integrity in voluntary muscle tissue. Monoclonal antibodies command premium positioning due to targeted mechanism and infusion-based administration protocols. Intravenous delivery mode carries concentrated margin pools owing to hospital-based administration requirements and reimbursement structures. Oral anticholinesterase inhibitors occupy mature volume leadership through decades of clinical precedent and generic availability.
The FDA orphan drug program shapes development economics through tax credits and market exclusivity provisions for novel indications. EMA's centralized marketing authorization pathway determines commercial access across European Union member states, while WHO inclusion criteria influence national formulary decisions in emerging markets. Stakeholders must monitor biosimilar entry timelines and evolving payer evidence requirements for maintenance therapy positioning.
Market Dynamics
FcRn inhibitor commercialization is restructuring competitive positioning in myasthenia gravis therapeutics, with hospital-based infusion centers capturing disproportionate margin pools from subcutaneous formulation transitions.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and seven-year market exclusivity provisions accelerate novel monoclonal antibody development timelines for rare autoimmune indications.
- Neuromuscular Center Expansion:Specialized academic medical centers in the United States consolidate patient volume and drive biologic therapy adoption through protocol standardization.
- Complement Pathway Science:Advances in C5 inhibition mechanisms expand addressable patient populations beyond acetylcholine receptor antibody-positive subgroups.
Market Restraints
- Biologic Manufacturing Concentration:Single-source contract manufacturing organizations in Ireland and Singapore create supply vulnerability for monoclonal antibody drug substances.
- Infusion Infrastructure Bottlenecks:Limited chair capacity at hospital outpatient departments constrains patient throughput for intravenous maintenance regimens.
- Reimbursement Compression:Medicare's hospital outpatient prospective payment system applies fixed reimbursement rates regardless of biologic acquisition cost fluctuations.
Strategic Opportunities
- Subcutaneous Self-Administration:Device-enabled home injection protocols bypass infusion center capacity constraints and capture patient convenience premiums.
- Japan's Sakigake Pathway:Japan's PMDA priority review system offers accelerated approval timelines for innovative neurology therapies addressing unmet need.
- Neonatal Fc Receptor Biosensor Diagnostics:Convergence of pharmacokinetic monitoring and point-of-care IgG level testing enables personalized dosing algorithms.
Industry Challenges
- Specialized Immunology Nursing Shortages:Infusion center expansion outpaces trained neurology nurse practitioner supply in tertiary care markets.
- Biosimilar Transition Complexity:Reference product exclusivity cliff preparations require inventory management and physician education coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myasthenia Gravis Therapeutics Market |
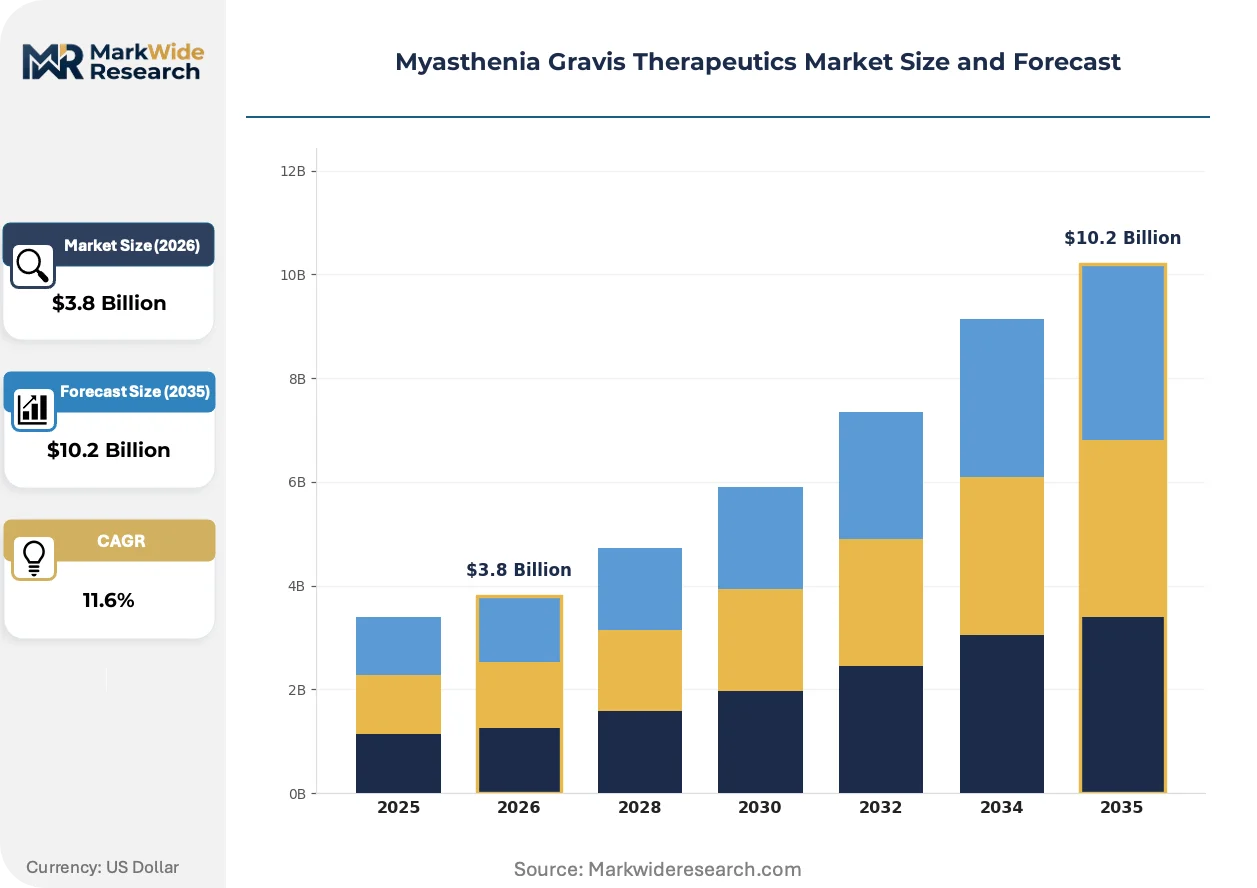
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticholinesterase Inhibitors, Immunosuppressants, Monoclonal Antibodies, Plasmapheresis Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Specialty Clinics, Home Healthcare, Research Institutions Therapy Area: Neurology, Autoimmune Disorders, Infectious Diseases, Hematology |
| Companies Covered | Novartis AG, Alexion Pharmaceuticals, argenx SE, Immunovant Sciences, Horizon Therapeutics, UCB Pharma, AstraZeneca, Cartesian Therapeutics, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myasthenia Gravis Therapeutics Market Shifts & Advancements
Neonatal Fc receptor biology is reshaping therapeutic development trajectories, with half-life extension mechanisms enabling dosing interval compression that alters site-of-care economics and patient adherence profiles.
Subcutaneous monoclonal antibody delivery is expanding into maintenance therapy protocols previously restricted to intravenous infusion. Community-based specialty pharmacies are adopting cold-chain distribution capabilities to support home administration. This modality shift is compressing hospital outpatient revenue capture and redistributing margin pools toward pharmacy benefit managers.
The FDA's Breakthrough Therapy designation pathway compresses Phase 2-to-approval timelines for novel mechanism autoimmune therapies. EMA's PRIME eligibility criteria create parallel European accelerated assessment opportunities. Small-cap biotechnology developers are prioritizing US-first filing strategies to leverage orphan drug exclusivity stacking.
Integrated delivery networks are consolidating myasthenia gravis patient funneling through designated center-of-excellence contracts with manufacturers. Risk-sharing arrangements based on treatment response biomarkers are displacing traditional buy-and-bill reimbursement. This procurement evolution concentrates volume at United States academic medical centers with established neuromuscular registry infrastructure.
Myasthenia Gravis Therapeutics Market Segmentation
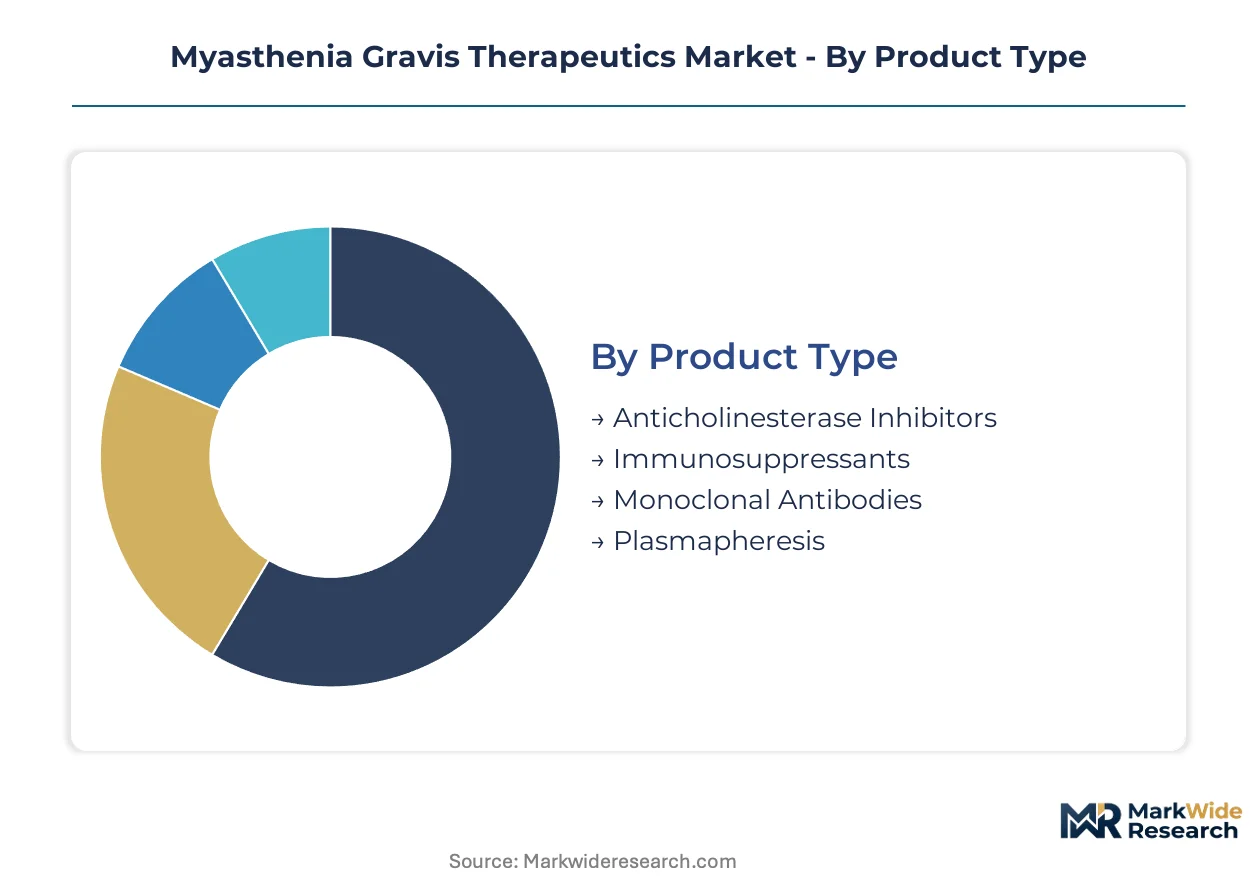
Treatment modality selection in myasthenia gravis hinges on disease severity staging, antibody serostatus, and site-of-care capacity. Segmentation reveals how biologic penetration is restructuring traditional pharmacoeconomics across hospital and ambulatory settings.
Product Type:
Prescribing patterns track acetylcholine receptor antibody status and prior immunosuppressive exposure, with mechanism of action driving reimbursement tier placement.
- Monoclonal Antibodies:Engineered immunoglobulins target FcRn-mediated IgG recycling or terminal complement cascade activation. United States academic medical centers with neuromuscular registries concentrate demand for efgartigimod and ravulizumab protocols.
- Anticholinesterase Inhibitors:Pyridostigmine and neostigmine formulations inhibit acetylcholinesterase enzyme activity at neuromuscular junctions. Generic pricing and decades of clinical precedent sustain volume leadership across outpatient neurology practices in Germany and France.
- Immunosuppressants:Azathioprine, mycophenolate mofetil, and tacrolimus suppress T-cell and B-cell mediated autoimmunity through purine synthesis inhibition or calcineurin pathway blockade.
- Plasmapheresis:Extracorporeal filtration removes circulating autoantibodies and immune complexes, reserved for myasthenic crisis stabilization.
Volume sits with anticholinesterase inhibitors; growth tilts toward monoclonal antibodies.
Delivery Mode:
Administration route determines site-of-care economics, with infusion center capacity constraints reshaping manufacturer formulation strategies.
- Intravenous:Hospital outpatient departments administer biologic therapies under buy-and-bill reimbursement structures. Medicare's hospital outpatient prospective payment system creates margin pressure when acquisition costs exceed fixed reimbursement rates.
- Subcutaneous:Prefilled syringe and autoinjector devices enable home administration by patients or caregivers. Japan's PMDA Sakigake pathway accelerates approval for device-enabled formulations addressing unmet convenience needs.
- Oral:Tablet and syrup formulations of anticholinesterase inhibitors and corticosteroids dominate maintenance therapy.
- Intramuscular:Depot injections of immunosuppressive agents serve bridging protocols during biologic initiation.
Intravenous captures concentrated margin pools; subcutaneous formulations are climbing the fastest.
End User:
Patient acuity and therapy complexity dictate care setting selection, with integrated delivery networks consolidating volume through center-of-excellence designation.
- Hospitals:Tertiary care centers manage acute exacerbations, myasthenic crisis, and biologic infusion protocols. United States academic medical centers with dedicated neuromuscular units drive adoption of novel monoclonal antibodies through protocol standardization.
- Specialty Clinics:Outpatient neurology practices coordinate long-term immunosuppression and monitor treatment response. France's ANSM regional pharmacovigilance networks support adverse event surveillance for high-risk biologic therapies.
- Home Healthcare:Nursing services support subcutaneous administration and patient education for self-injection protocols.
- Research Institutions:Academic centers conduct Phase II and Phase III trials for novel mechanism therapies under FDA and EMA accelerated pathways.
Hospitals anchor current revenue; specialty clinics represent the steepest expansion trajectory.
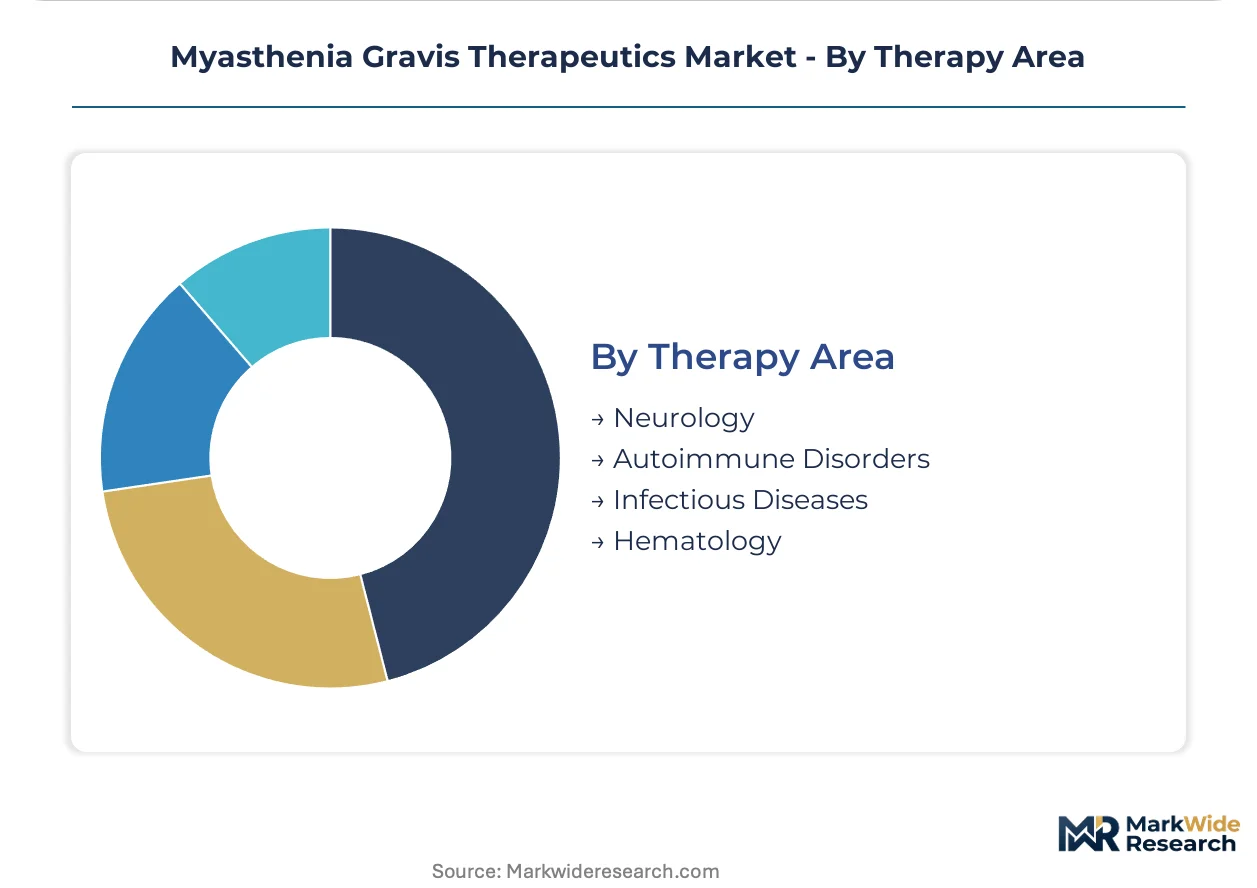
Therapy Area:
Diagnostic coding and specialty referral patterns channel patients into discrete treatment pathways with distinct reimbursement frameworks.
- Neurology:Neuromuscular specialists direct comprehensive management including immunotherapy and symptomatic treatment. Germany's university hospital networks concentrate subspecialty expertise and clinical trial access.
- Autoimmune Disorders:Cross-disciplinary protocols address comorbid rheumatologic and dermatologic conditions. United Kingdom NHS integrated care systems coordinate biologic prescribing across specialty boundaries.
- Infectious Diseases:Prophylaxis and treatment of opportunistic infections complicating immunosuppressive therapy.
- Hematology:Plasmapheresis and immunoadsorption protocols leverage apheresis infrastructure shared with hematologic indications.
Neurology commands premium positioning; autoimmune disorder coding is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized autoimmune treatment demand concentrates in the United States, where academic medical centers with neuromuscular registries drive biologic therapy volume. Secondary markets in Germany and Japan follow distinct regulatory pathways for orphan drug commercialization. Emerging adoption in China and India reflects expanding neurology infrastructure.
United States
Academic medical centers in Boston, New York, and California anchor biologic therapy adoption through established neuromuscular registry infrastructure. The FDA's orphan drug designation pathway accelerates monoclonal antibody development with seven-year market exclusivity provisions. Mayo Clinic and Cleveland Clinic concentrate patient volume for FcRn inhibitor protocols.
Germany
University hospital networks in Munich, Heidelberg, and Berlin consolidate subspecialty expertise and clinical trial access for complement pathway therapies. The country's national pharmaceutical regulator operates under EMA centralized marketing authorization for cross-border commercial access. Baden-Württemberg's pharmaceutical cluster supports contract manufacturing for monoclonal antibody drug substances.
Japan
PMDA's Sakigake priority review system compresses approval timelines for innovative neurology therapies addressing unmet convenience needs. The Kanto region around Tokyo concentrates neuromuscular specialist density and hospital outpatient infusion capacity. Osaka-based specialty clinics coordinate subcutaneous self-administration training for device-enabled formulations.
China
NMPA's accelerated review pathways for rare disease therapies expand market access for imported biologics in tier-one cities. The Yangtze River Delta region around Shanghai anchors neurology department expansion at tertiary hospitals. Beijing's national reimbursement negotiation mechanism determines formulary inclusion for high-cost monoclonal antibodies.
India
CDSCO's orphan drug framework remains under development, with import-dependent supply chains constraining biologic penetration outside metro hospitals. Maharashtra and Karnataka concentrate neurology specialist training programs at government medical colleges. Delhi-NCR's private hospital networks pioneer plasmapheresis infrastructure for myasthenic crisis management.
Myasthenia Gravis Therapeutics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated leadership in monoclonal antibodies and fragmented supply in generic immunosuppressants. Large-cap pharmaceutical conglomerates anchor commercial infrastructure through neuroscience franchise integration. Mid-cap biotechnology developers concentrate on single-mechanism specialization. Competitive moves center on subcutaneous formulation transitions and center-of-excellence contracting with integrated delivery networks.
Within the large-cap tier, Novartis AG and AstraZeneca represent diversified pharmaceutical conglomerates with cross-indication immunology infrastructure. Among FcRn inhibitor specialists, argenx SE occupies a position exemplifying mechanism-focused development strategy. Alexion Pharmaceuticals anchors the complement pathway archetype with established neurology center relationships. These three companies collectively illustrate the market's tripartite structure: diversified conglomerates, mechanism specialists, and pathway-focused developers.
| Leading Market Players |
|---|
| Novartis AG |
| Alexion Pharmaceuticals |
| argenx SE |
| Immunovant Sciences |
| Horizon Therapeutics |
| UCB Pharma |
| AstraZeneca |
| Cartesian Therapeutics |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Captive biologic manufacturing in Ireland and Singapore anchors supply positions for FcRn inhibitors and complement pathway monoclonal antibodies, concentrating pricing power with sponsors who control drug substance production and hospital outpatient administration networks. This vertical integration into drug substance and finished dose production insulates premium positioning from generic immunosuppressant competition while exposing margins to single-source manufacturing risk.
Pricing Analysis
Volume sits with oral anticholinesterase inhibitors at generic price points; margins concentrate in intravenous monoclonal antibodies administered through hospital outpatient departments. Price differentiation rests on mechanism specificity and site-of-care control, with FcRn inhibitors commanding premium positioning against small-molecule immunosuppressants. Pricing pressure stems from Medicare's hospital outpatient prospective payment system applying fixed reimbursement rates regardless of biologic acquisition cost fluctuations. Community neurology practices exhibit highest price sensitivity; academic medical centers with neuromuscular registries demonstrate lowest sensitivity due to protocol standardization and center-of-excellence contracting.
Supply Chain Analysis
Single-source vulnerability sits with contract manufacturing organizations in Ireland and Singapore for monoclonal antibody drug substance production. Active pharmaceutical ingredient sourcing draws from Chinese and Indian chemical synthesis hubs, while fill-finish capacity concentrates in European and North American facilities. Tariff exposure on imported drug substances threatens margin stability for developers without captive manufacturing. Distribution runs through hospital outpatient departments and specialty pharmacy channels, with cold-chain logistics requirements constraining community-based dispensing options.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subcutaneous self-administration devices are displacing intravenous infusion protocols as the dominant delivery modality, compressing hospital outpatient revenue capture and redistributing margin pools toward pharmacy benefit managers and home healthcare channels.
For Market Incumbents: Acquire subcutaneous formulation capabilities and autoinjector device platforms to defend against biosimilar entry and infusion center capacity constraints. Backward integration into drug substance manufacturing in Ireland or Singapore reduces single-source vulnerability from contract manufacturing organization concentration. Center-of-excellence contracting with integrated delivery networks preserves volume concentration against community-based specialty pharmacy expansion.
For New Entrants and Emerging Players: Capture subcutaneous maintenance therapy positioning in Japan through PMDA's Sakigake priority review pathway, where device-enabled convenience claims accelerate approval timelines. Target neurology practices in Germany and France with oral formulation alternatives to intravenous biologics, leveraging ANSM and EMA pharmacovigilance infrastructure for adverse event differentiation. Partner with community specialty pharmacies for cold-chain distribution rather than competing for hospital outpatient department access.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by large-cap pharmaceutical conglomerates seeking neuroscience franchise expansion through orphan drug exclusivity assets. Long-term viability hinges on subcutaneous formulation transitions and biosimilar defense strategies rather than intravenous infusion dependence. Watch for FDA Breakthrough Therapy designation announcements as inflection indicators for accelerated approval timelines and valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Device-enabled home administration bypasses hospital infusion center capacity constraints and captures patient convenience premiums. |
| Center-of-Excellence Contracting | Integrated delivery network partnerships concentrate patient volume at academic medical centers with neuromuscular registry infrastructure. |
| Orphan Drug Exclusivity Stacking | FDA seven-year market exclusivity provisions accelerate development timelines and defend against early biosimilar entry. |
| Neonatal Fc Receptor Biosensor Diagnostics | Pharmacokinetic monitoring convergence enables personalized dosing algorithms and treatment response optimization. |
| Japan Sakigake Pathway Filing | PMDA priority review system compresses approval timelines for innovative neurology therapies addressing unmet convenience needs. |
Research Methodology
Multi-period observation of FDA orphan drug designations, EMA centralized marketing authorizations, and hospital outpatient biologic administration volumes anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and Medicare hospital outpatient prospective payment system data. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation reconciled volume and value estimates.
Input-output matrix analysis connected treatment modality adoption rates to site-of-care economics across intravenous, subcutaneous, and oral administration routes. Segmentation dimensions included product type, delivery mode, end user, and therapy area, with regional regulatory clusters modeled separately. CAGRs were derived from fitted trend extrapolation anchored by historical biologic penetration patterns and immunosuppressant generic substitution rates. Forecast inputs incorporated neuromuscular center expansion trajectories and biosimilar entry timeline assumptions.
The model holds under stable orphan drug incentive frameworks and continued hospital outpatient reimbursement; deviation in Medicare payment system restructuring or biosimilar accelerated approval pathways would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
Advanced Therapy Medicinal Products CDMO Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Clozapine Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Peptic Ulcer Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Dyslipidemia Drugs Market