
 Global Floor and Wall Glazed Tiles Market | 2026-2036
Global Floor and Wall Glazed Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Floor and Wall Glazed Tiles Market Analysis
The EU Green Deal is expanding demand for low-carbon building materials across European construction supply chains. Mohawk Industries leverages its North American manufacturing footprint to sustain distribution density in residential renovation channels. RAK Ceramics anchors Middle Eastern and South Asian supply through integrated production complexes in the UAE and Bangladesh. Kajaria Ceramics dominates India's domestic market with specialized distributor networks spanning tier-two and tier-three cities.
Floor and wall glazed tiles are thin, flat surfacing units manufactured from clay, feldspar, silica, and mineral oxides, fired at temperatures exceeding 1,000°C to form a vitreous, non-porous body with a glass-like surface coating. Their primary commercial purpose is to provide durable, moisture-resistant, and aesthetically finished surfaces for interior and exterior building applications. Porcelain tiles lead product-type value pools due to superior density and through-body color consistency, while large-format slabs command premium positioning in commercial and luxury residential installations. The renovation installation type is expanding faster than new construction in mature European and North American markets, driven by aging housing stock and energy-efficiency retrofit programs.
REACH regulates chemical content in ceramic glazes across European manufacturing and imports, while the EU Green Deal's embodied-carbon benchmarks are forcing reformulation of kiln fuels and raw-material sourcing. India's BIS certification mandates dimensional and water-absorption standards for domestic tile sales, creating compliance barriers for unorganized regional producers. China's GB standards and dual carbon goals are reshaping export-oriented manufacturing in Guangdong and Fujian provinces. Stakeholders must monitor how tightening carbon-border adjustments and evolving national building codes alter competitive access across major demand centers.
Market Dynamics
Embodied-carbon thresholds from the EU Green Deal are forcing reformulation of kiln fuels and raw-material sourcing across manufacturing bases, compressing margins for high-emission producers while rewarding low-carbon innovators with preferential procurement access.
Growth Catalysts
- India's urban housing programs:Government-subsidized affordable housing and metro rail expansion are accelerating tile consumption in residential and commercial infrastructure across tier-two and tier-three cities.
- REACH chemical compliance:European glaze-content regulations are creating competitive moats for certified producers, filtering out informal manufacturers from import channels.
- Large-format porcelain technology:Continuous roller-kiln advances enable slab sizes exceeding 1.6 meters, opening specification opportunities in luxury hospitality and retail fit-outs.
Market Restraints
- Natural gas price volatility:Kiln operations depend on natural gas for 60-70% of thermal energy; European and Asian price spikes directly compress manufacturing margins.
- Guangdong supply concentration:China's export-oriented tile production clusters in Guangdong and Fujian provinces, creating geographic risk from regional power rationing or trade-policy shifts.
- Engineered stone substitution:Sintered stone and quartz surfacing materials are capturing premium kitchen and bathroom specification from traditional glazed ceramics.
Strategic Opportunities
- Vietnam manufacturing expansion:Labor-cost advantages and pending EU free-trade agreements are attracting greenfield tile production investments for export-oriented capacity.
- Photovoltaic-integrated facades:Building-integrated solar tiles combining glazed ceramic substrates with thin-film photovoltaic layers open new building-envelope applications.
- Digital specification platforms:Architect and interior-designer procurement is migrating to BIM-integrated material libraries, enabling direct manufacturer-to-specifier relationships bypassing traditional distribution.
Industry Challenges
- Digital inkjet technician scarcity:High-resolution glaze-printing systems require specialized calibration expertise; workforce gaps in emerging manufacturing regions delay line commissioning.
- BIS certification timelines:India's mandatory testing and factory-audit procedures for dimensional and water-absorption standards extend product-launch cycles by four to six months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Floor and Wall Glazed Tiles Market |
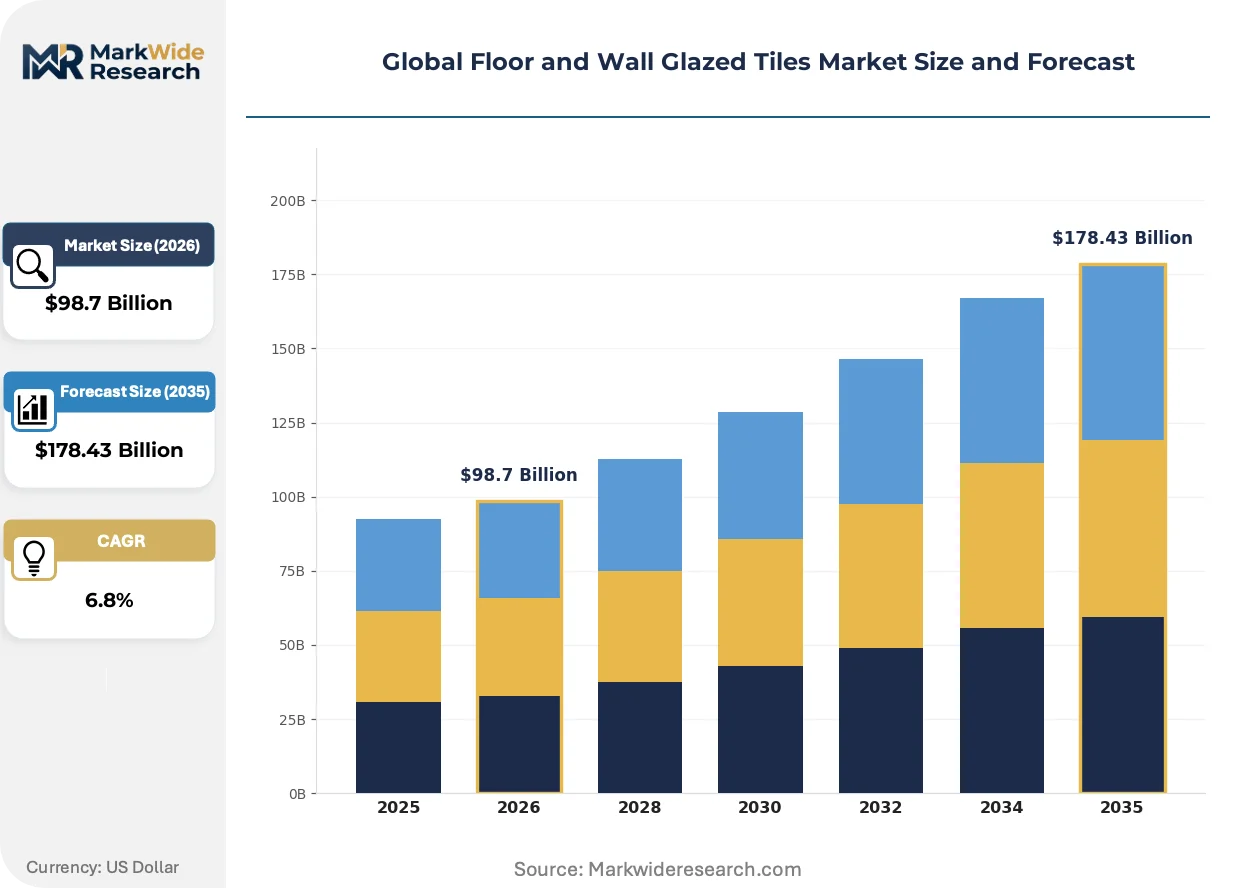
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Tiles, Porcelain Tiles, Glass Tiles, Mosaic Tiles End User: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Renovation, Remodeling, DIY Size: Small Format, Large Format, Slab, Custom |
| Companies Covered | Mohawk Industries, RAK Ceramics, SCG Ceramics, Grupo Lamosa, Kajaria Ceramics, Pamesa Ceramica, Porcelanosa Grupo, Ceramica Carmelo Fior, Grupo Cedasa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Floor and Wall Glazed Tiles Market Emerging Trajectories
Digital manufacturing workflows and low-carbon process innovations are compressing traditional production economics while enabling mass-customization capabilities that reshape competitive differentiation in specification-driven segments.
Thin large-format porcelain slabs are absorbing specification share from natural stone and traditional thick-body tiles in commercial facades and interior surfacing. Hospitality developers in the Middle East and Southeast Asia specify these materials for reduced dead-load and seamless aesthetic continuity. The technology is absorbing premium-positioning value pools previously captured by marble and granite suppliers.
The EU Green Deal's embodied-carbon benchmarks are forcing kiln-fuel switching from natural gas to hydrogen blends and biomass-derived syngas. European manufacturers face compliance deadlines that require capital-intensive burner retrofits and supply-chain requalification. Italian and Spanish producers are responding fastest, leveraging existing R&D infrastructure to certify low-carbon product lines ahead of border-adjustment mechanisms.
Architects and interior designers increasingly source tiles through BIM-integrated material platforms that embed technical specifications, sustainability certifications, and real-time inventory availability. Traditional distributor showrooms in Germany and France are losing specification influence to these digital channels. The shift is most visible in commercial new-build projects where design-consultant procurement authority concentrates decision-making.
Global Floor and Wall Glazed Tiles Market Segmentation
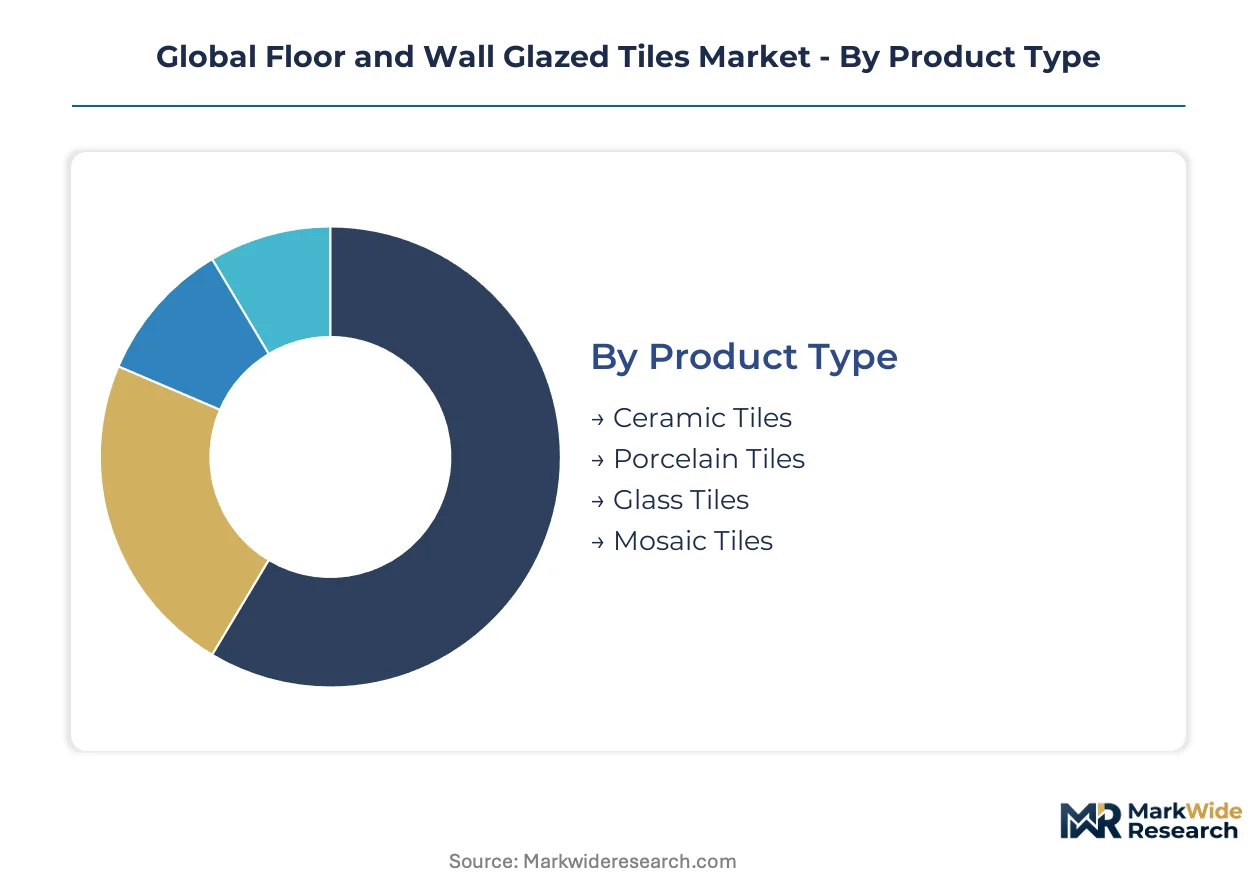
Tile specification varies sharply across building types, with embodied-carbon thresholds and installation complexity dictating product selection. Manufacturers align certification portfolios to segment-specific compliance burdens, from residential BIS mandates to commercial LEED documentation.
Product Type:
Porcelain tiles carry the heaviest certification load, requiring ISO 13006 density ratings and EU Green Deal carbon disclosures for European import eligibility. Ceramic tiles face lighter REACH glaze-content scrutiny, while glass and mosaic variants trigger additional safety testing for fragmentation resistance.
- Porcelain Tiles:Dense, vitreous bodies fired above 1,200°C deliver through-body color consistency and sub-0.5% water absorption. Demand concentrates in German and French commercial facades where thermal-mass regulations favor high-performance envelopes. Italian producers leverage roller-kiln advances to capture premium hospitality specification.
- Ceramic Tiles:Porous earthenware bodies with glazed surfaces dominate India's affordable housing programs. Uttar Pradesh and Gujarat housing boards specify these for cost-driven mass installation. BIS certification timelines compress margin for unorganized regional competitors.
- Glass Tiles:Tempered or cast glass units with rear-mounted color layers serve specialized backsplash and accent applications.
- Mosaic Tiles:Small-format tesserae mounted on mesh backing enable complex patterning in pool and spa environments.
Leading the category by volume: Ceramic Tiles. Growing fastest: Porcelain Tiles.
End User:
Cost tiers separate specification authority, with institutional and commercial buyers commanding bulk procurement leverage against fragmented residential demand.
- Residential:Single-family and multi-family housing drives volume through renovation cycles and new construction in Indian tier-two cities. Developer-specified large-format porcelain absorbs share from natural stone in Mumbai and Delhi luxury apartments. Energy-efficiency retrofits in Italian and Spanish housing stock accelerate glazed tile replacement.
- Commercial:Retail, hospitality, and office fit-outs specify thin porcelain slabs for reduced structural dead-load. Dubai and Riyadh hotel developers source 1.6-meter formats for seamless lobby and bathroom surfacing.
- Industrial:Chemical-resistant quarry tile and heavy-duty porcelain serve manufacturing floor applications.
- Institutional:Healthcare and education procurement mandates antimicrobial glazes and slip-resistance certification.
Highest margin concentration: Commercial. Steepest expansion trajectory: Residential.
Installation Type:
Customer type dictates channel structure, with professional contractors dominating new construction and DIY segments fragmenting through retail hardware.
- Renovation:Aging housing stock across Germany, France, and the United States drives replacement demand for moisture-resistant bathroom and kitchen surfacing. Energy-efficiency subsidy programs in Italy accelerate facade recladding with ventilated tile systems.
- New Construction:Developer-specified materials in Indian urban housing programs concentrate demand for standardized ceramic formats. Metro rail station construction in Bangalore and Hyderabad specifies heavy-traffic porcelain for platform and concourse areas.
- Remodeling:Design-consultant-led residential upgrades favor imported Italian and Spanish premium lines.
- DIY:Home improvement retailers in the United States and United Kingdom stock click-lock and peel-adhesive formats for consumer self-installation.
Dominant volume share: Renovation. Gaining share fastest: New Construction.
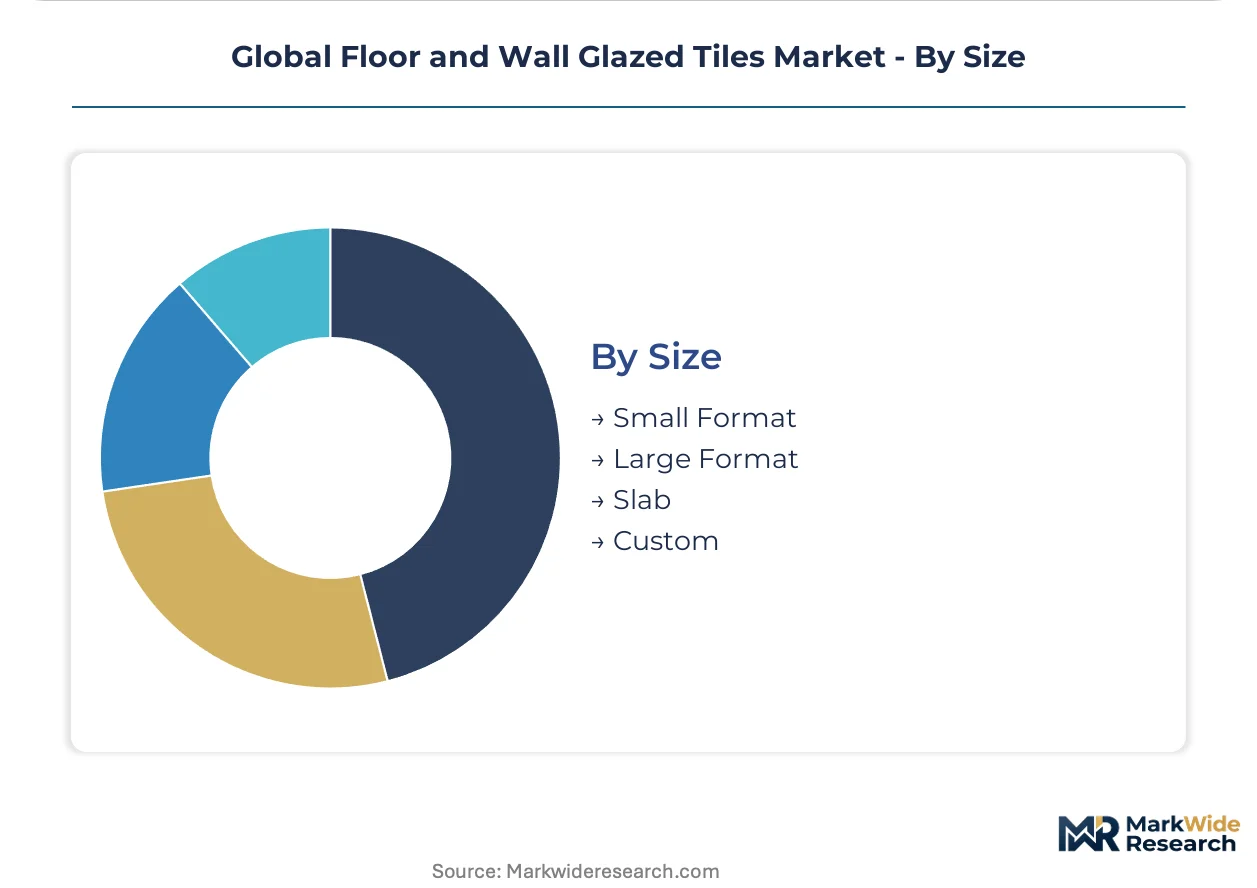
Size:
Supply concentration clusters around large-format production, where continuous roller-kiln investments create scale barriers for small-format specialists.
- Large Format:Dimensions exceeding 60×120 centimeters enable reduced grout lines and seamless aesthetic continuity. Saudi hospitality developers and Southeast Asian retail chains specify these for premium positioning against natural stone.
- Slab:Thin porcelain sheets above 1.6 meters in length absorb specification from marble and granite in commercial facades and interior cladding. Spanish producers lead technical development through Sacmi continuous pressing systems.
- Small Format:Traditional 30×30 and 40×40 centimeter tiles serve cost-sensitive mass housing and repair markets.
- Custom:Architect-specified dimensions and cut-to-size finishing serve bespoke commercial and residential projects.
Volume leader: Large Format. Fastest climb: Slab.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foshan anchors global glazed tile manufacturing capacity, clustering over 2,000 producers across Guangdong's Pearl River Delta with annual output exceeding 10 billion square meters.
China
Urban renewal programs in Shanghai and Beijing accelerate replacement demand for moisture-resistant bathroom surfacing. GB standards and dual carbon goals from MEE are forcing kiln-fuel switching in Guangdong and Fujian production bases. Zibo's ceramics corridor in Shandong province is absorbing capacity migration from power-rationed southern clusters.
India
Pradhan Mantri Awas Yojana housing subsidies and metro rail expansion in Bangalore and Hyderabad drive ceramic tile consumption through tier-two and tier-three cities. BIS certification mandates dimensional and water-absorption standards that filter unorganized regional competitors. Morbi in Gujarat concentrates 70% of domestic production in a single industrial belt.
Italy
Energy-efficiency retrofit programs across Lombardy and Veneto accelerate facade recladding with ventilated tile systems. EU Green Deal embodied-carbon benchmarks force Sacmi roller-kiln retrofits and biomass fuel adoption. Sassuolo's ceramics district maintains R&D leadership through continuous pressing technology advances.
Spain
Hospitality developers in Barcelona and Madrid specify thin porcelain slabs for reduced structural dead-load in luxury fit-outs. REACH glaze-content regulations create competitive moats for certified Castellón producers. Alcora's manufacturing cluster leads large-format slab development for Middle Eastern export markets.
United States
Aging housing stock across Texas and Florida drives renovation demand for peel-adhesive and click-lock formats. EPA emissions guidelines affect natural gas-fired kiln operations in Tennessee and Ohio production corridors. Dalton, Georgia anchors North American distribution density through rail-linked warehousing infrastructure.
Global Floor and Wall Glazed Tiles Market Vendor Landscape
The competitive structure tilts toward vertically integrated multinationals with captive raw-material sourcing and kiln technology ownership. Italian and Spanish producers cluster around premium specification through continuous roller-kiln advances, while Indian and Chinese players compete on ceramic tile volume for affordable housing programs. Three archetypes dominate: integrated multinationals controlling quarry-to-distribution chains, technology licensors monetizing kiln and press patents, and regional specialists serving protected domestic markets. M&A activity concentrates on distributor network acquisition and digital inkjet technology licensing.
Among North American integrated producers, Mohawk Industries exemplifies scale-driven manufacturing footprint consolidation. In the Middle Eastern supply anchor position, RAK Ceramics occupies a position bridging UAE production complexes with South Asian distribution. Kajaria Ceramics represents the India-focused archetype with specialized network penetration into tier-two and tier-three urban centers.
| Leading Market Players |
|---|
| Mohawk Industries |
| RAK Ceramics |
| SCG Ceramics |
| Grupo Lamosa |
| Kajaria Ceramics |
| Pamesa Ceramica |
| Porcelanosa Grupo |
| Ceramica Carmelo Fior |
| Grupo Cedasa |
| Others |
Supply Flow & Price Mechanics
Natural gas kiln-fuel costs cascade through glazed tile pricing tiers from Morbi's ceramic belt to European distribution channels, compressing margins for gas-dependent producers while rewarding biomass-fuel adopters with premium positioning in EU Green Deal procurement.
Pricing Analysis
Throughput-based pricing anchors large-format porcelain slabs to project-scale specification value, with Italian Sacmi roller-kiln outputs commanding premium positioning against standard ceramic grades. Price differentiation stratifies across ISO 13006 density certification, EU embodied-carbon disclosure tiers, and brand equity accumulated through hospitality reference projects. Cost compression in Indian mass-housing ceramic segments is intensifying because BIS certification timelines extend product-launch cycles for new entrants. Developer procurement in Mumbai and Delhi luxury residential shows least price sensitivity; Uttar Pradesh housing board tenders exhibit highest.
Supply Chain Analysis
Direct-to-specifier digital platforms are displacing traditional distributor showrooms in German and French commercial new-build procurement. Manufacturing gravity centers on China's Guangdong and Fujian provinces, India's Gujarat belt, and Italy's Sassuolo district. Raw material sourcing draws from Rajasthan feldspar, Ukrainian ball clay, and Spanish mineral oxides. Single-source vulnerability concentrates in Guangdong's power-rationing exposure. Distribution runs through rail-linked warehousing at Dalton, Georgia for North American density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive raw-material sourcing and kiln technology ownership separate margin leaders from price-takers in carbon-regulated procurement.
For Market Incumbents: Hedge gas-price volatility through biomass-fuel burner retrofits ahead of EU border-adjustment deadlines. Deepen upstream control over Rajasthan feldspar and Ukrainian ball clay to defend margin position against engineered stone substitution in premium kitchen specification. For New Entrants and Emerging Players: Begin with Vietnam greenfield capacity positioned for pending EU free-trade agreement access. Target tier-two Indian cities where BIS certification barriers filter unorganized regional competitors; pursue architect-direct digital specification relationships bypassing traditional distribution. For Investors and Strategic Acquirers: Sacmi continuous pressing technology licensing announcements are the leading indicator that large-format slab capability is concentrating among capital-intensive players. Five-to-ten year viability favors integrated producers with captive quarry-to-distribution chains and certified low-carbon product portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Biomass Fuel Retrofit | EU Green Deal compliance secures preferential procurement access ahead of carbon-border adjustments. |
| Digital Specification Platform Integration | BIM-embedded material libraries enable direct manufacturer-to-architect relationships bypassing distributor margins. |
| Large-Format Slab Capacity Expansion | Sacmi roller-kiln investments capture premium hospitality specification from natural stone substitution. |
| Backward Integration into Raw Materials | Captive Rajasthan feldspar and Ukrainian ball clay sourcing defends margin against commodity volatility. |
| Photovoltaic-Integrated Facade Development | Building-integrated solar tiles open new building-envelope applications beyond traditional surfacing markets. |
Methodological Framework
Independent corroboration across plant managers at Guangdong and Morbi manufacturing clusters, procurement leads at Dubai hospitality developers, and technical R&D directors in Sassuolo underwrites the qualitative findings. Secondary validation draws from Chinese customs export data, Indian BIS certification registries, Italian ceramic industry association reports, and SEC filings of North American listed producers. Bottom-up capacity estimates triangulate against top-down construction spend allocations across residential, commercial, and institutional end-use segments.
Historical reference periods anchor the projection horizon to pre-pandemic baseline capacity utilization and post-regulatory-shift demand patterns. Segmentation dimensions span product type density grades, installation type renovation versus new construction splits, end-user cost tiers, and regional regulatory clusters. CAGRs derive from elasticity-adjusted demand curves incorporating natural gas price scenarios and carbon-border adjustment implementation timelines. Forecast inputs include metro rail construction pipelines in Indian tier-two cities and EU energy-efficiency retrofit program allocations.
Underlying measurement precision varies by segment; large-format porcelain slabs and EU-certified low-carbon product lines carry tighter precision than fragmented ceramic mass-housing grades. Forecasts reflect assumptions around kiln-fuel switching timelines, BIS certification enforcement intensity, and engineered stone substitution rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Drywall and Gypsum Board Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Prefabricated Building System Market
Building & Construction Materials
Asphalt Modifiers Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
Global Concrete Surface Retarders Market
Building & Construction Materials
Steep Slope Roofing Materials Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Construction Sustainable Materials Market