
 Bahrain Construction Market | 2026-2036
Bahrain Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Construction Market Analysis
Multi-source procurement is consolidating as Bahrain's largest developers diversify contractor rosters to de-risk megaproject delivery. Nass Corporation anchors heavy civil and marine works through its integrated engineering and fabrication capabilities. Kooheji Contractors leverages long-standing relationships with government agencies to sustain a steady pipeline of institutional builds. Dadabhai Construction competes on speed-to-market in residential towers, differentiating through modular construction techniques that compress schedules.
Construction in Bahrain encompasses the erection, renovation, and finishing of buildings and civil structures using reinforced concrete, structural steel, and curtain-wall assemblies designed to withstand seismic zone II-B requirements and extreme saline corrosion conditions. Its primary purpose is creating habitable, productive, and transport infrastructure that supports population growth and economic diversification beyond hydrocarbons. Residential and infrastructure project types lead current volume, with infrastructure pulling ahead as the Bahrain Metro expansion and Causeway-linked logistics corridors advance. Concrete dominates material consumption given local ready-mix supply density, though steel framing gains share in commercial high-rises where faster floor-cycle times command premium pricing.
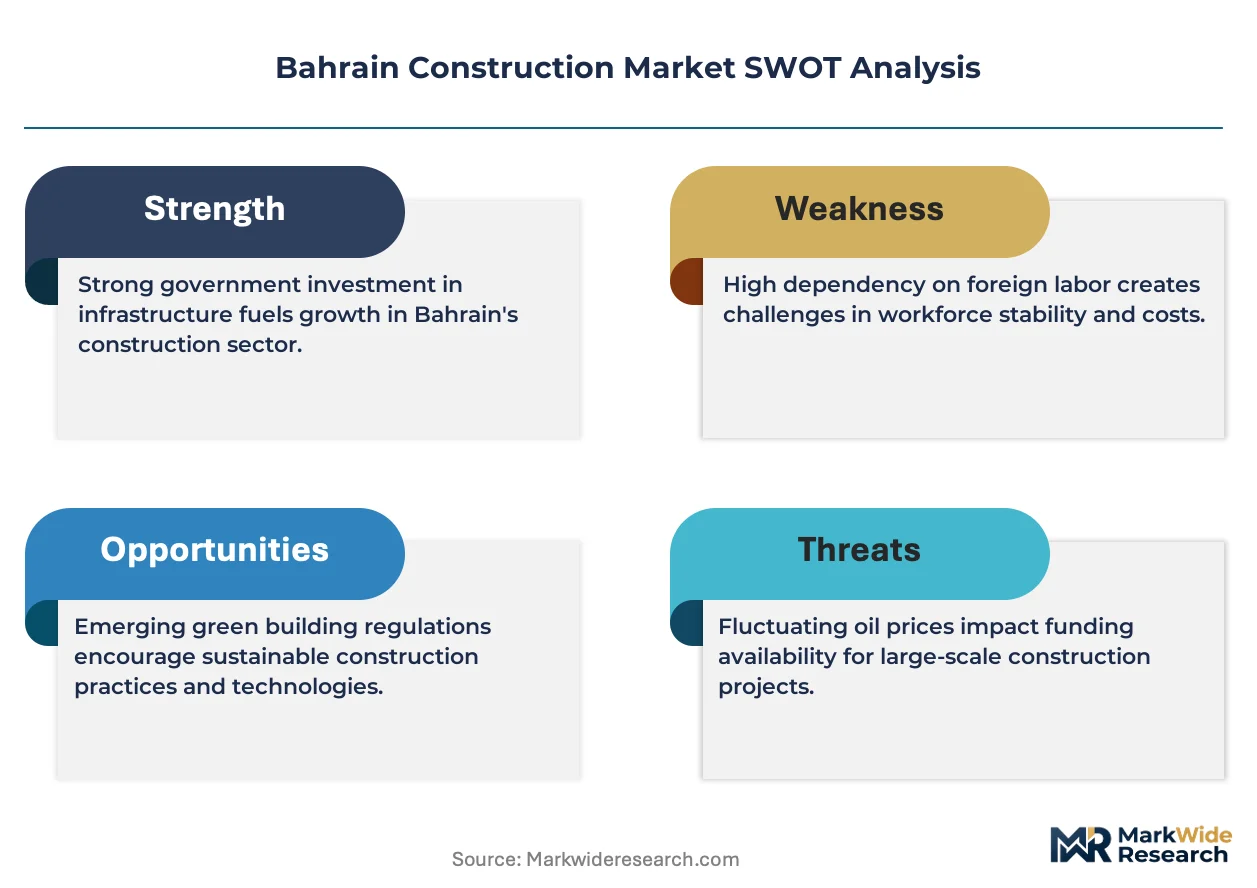
Bahrain's Ministry of Works enforces the Bahrain National Building Code, which mandates fire-resistance ratings and accessibility compliance that shape material selection and design fees. The country's national green building rating system, administered through the Sustainable Energy Authority, conditions permit approvals on energy modeling and water recycling provisions that filter contractor eligibility. The central bank's real estate exposure limits and the Ministry of Housing's subsidized finance programs jointly steer demand toward affordable and mid-market residential segments. Stakeholders must monitor how evolving sovereign debt levels and foreign labor quota adjustments reshape project feasibility and workforce availability.
Market Dynamics
Government infrastructure commitments are compressing project timelines while Bahrain's Sustainable Energy Authority tightens energy performance mandates, forcing contractors to recalibrate material specifications and delivery models simultaneously.
Growth Catalysts
- Bahrain Metro Phase 2:The Ministry of Transportation's rail expansion is mobilizing specialized civil contractors for tunneling and station complex construction across Manama and Muharraq.
- Salman City affordable housing zone:Ministry of Housing subsidized finance is channeling demand toward mid-market residential clusters with standardized designs that accelerate permit approvals.
- Building-integrated photovoltaics:Solar facade systems are qualifying projects for expedited green certification under the national rating system, reducing approval cycles by several months.
Market Restraints
- Steel price volatility:Rebar and structural sections face input cost swings tied to Persian Gulf scrap metal flows and shipping lane disruptions through the Strait of Hormuz.
- Labor quota rigidity:The Labor Market Regulatory Authority's foreign worker permit caps constrain workforce scaling during peak construction phases.
- Saline corrosion specifications:Coastal exposure zones mandate premium-grade concrete additives and stainless steel reinforcement that inflate material budgets by substantial margins.
Strategic Opportunities
- Modular precast expansion:Factory-built volumetric units are penetrating the Northern Governorate's hospitality sector, compressing on-site assembly from months to weeks.
- Water recycling mandates:The Sustainable Energy Authority's greywater reuse requirements are opening specification windows for integrated plumbing and treatment system contractors.
- Causeway logistics corridor:King Fahd Causeway-linked industrial zones are attracting bonded warehouse and cold storage developers seeking proximity to Saudi import flows.
Industry Challenges
- Seismic engineering specialization:Zone II-B structural calculations require certified engineers in short supply, creating bottlenecks during design review phases.
- Permit synchronization:Concurrent approvals from the Ministry of Works, Civil Defense, and municipal authorities generate timeline uncertainty that disturbs subcontractor scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Construction Market |
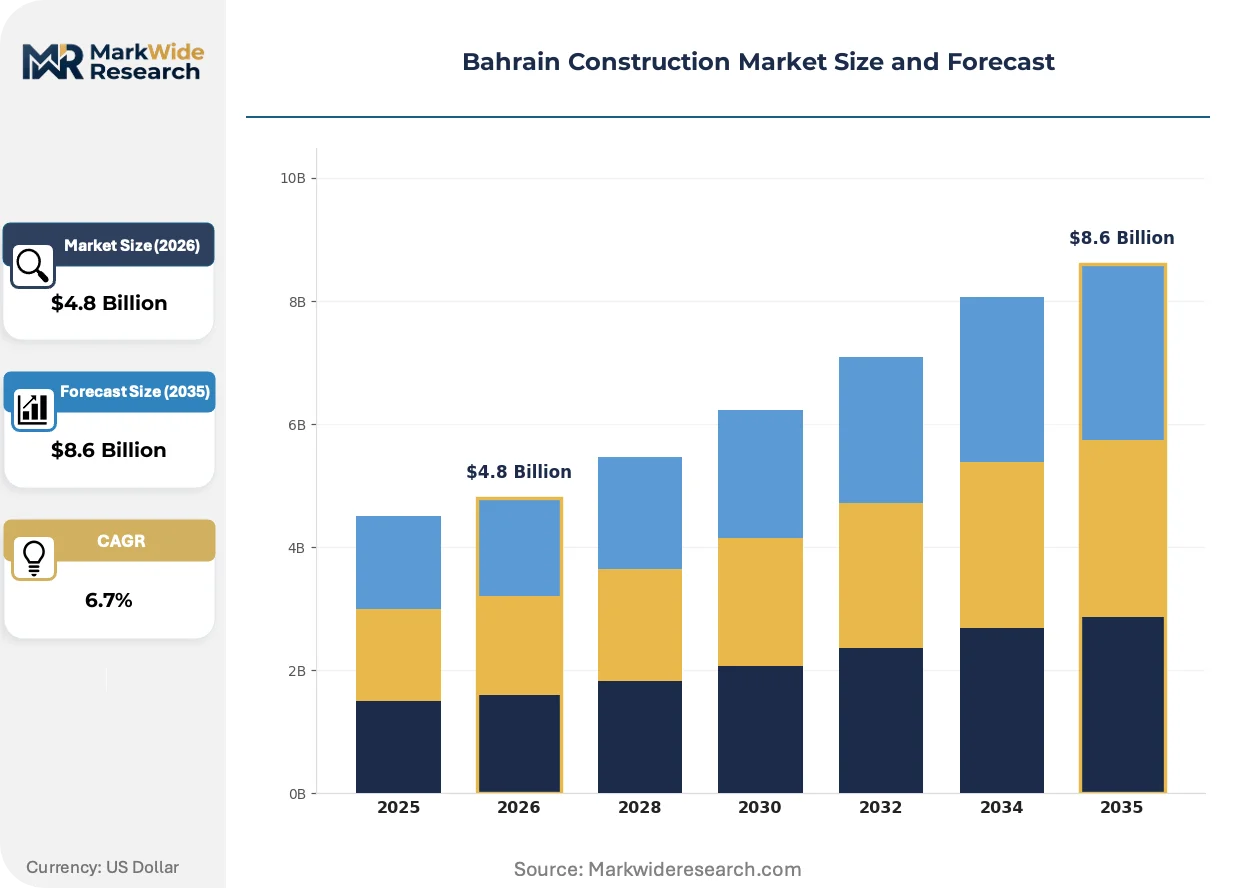
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Material Type: Concrete, Steel, Wood, Glass End User: Government, Private Sector, Developers, Contractors Contracting Model: Design-Bid-Build, Design-Build, Construction Manager at Risk, Integrated Project Delivery |
| Companies Covered | Dadabhai Construction, Kooheji Contractors, Nass Corporation, Larsen & Toubro Bahrain, Projects Holding Company, Haji Hassan Group, Delta Construction Co., Parsons Bahrain, Almoayyed Contracting Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Construction Market Emerging Trajectories
Digital fabrication and regulatory tightening are converging to reshape how Bahraini contractors source materials, document compliance, and structure project delivery teams.
Building information modeling is rewriting coordination protocols between architects and MEP subcontractors. Large mixed-use developers in Seef District are mandating clash-detection workflows before concrete pours, compressing rework cycles and reducing field change orders. The technology is enabling design-build contracts that transfer risk to contractors with in-house digital capabilities.
Bahrain National Building Code amendments are mandating enhanced fire-resistance ratings for high-rise residential cores. The Civil Defense Directorate now requires third-party testing documentation for curtain-wall assemblies, adding certification layers that filter out smaller facade contractors. Commercial tower projects in the Capital Governorate are absorbing these costs through extended pre-construction phases.
Developer procurement panels are consolidating contractor rosters for megaproject portfolios. Multi-source bidding is displacing single-contractor relationships as Bahrain's largest real estate investment trusts seek to de-risk schedule slippage across simultaneous tower launches. This pattern concentrates award volumes with firms demonstrating cross-project resource flexibility, particularly visible in the Northern Governorate's residential pipeline.
Bahrain Construction Market Segmentation
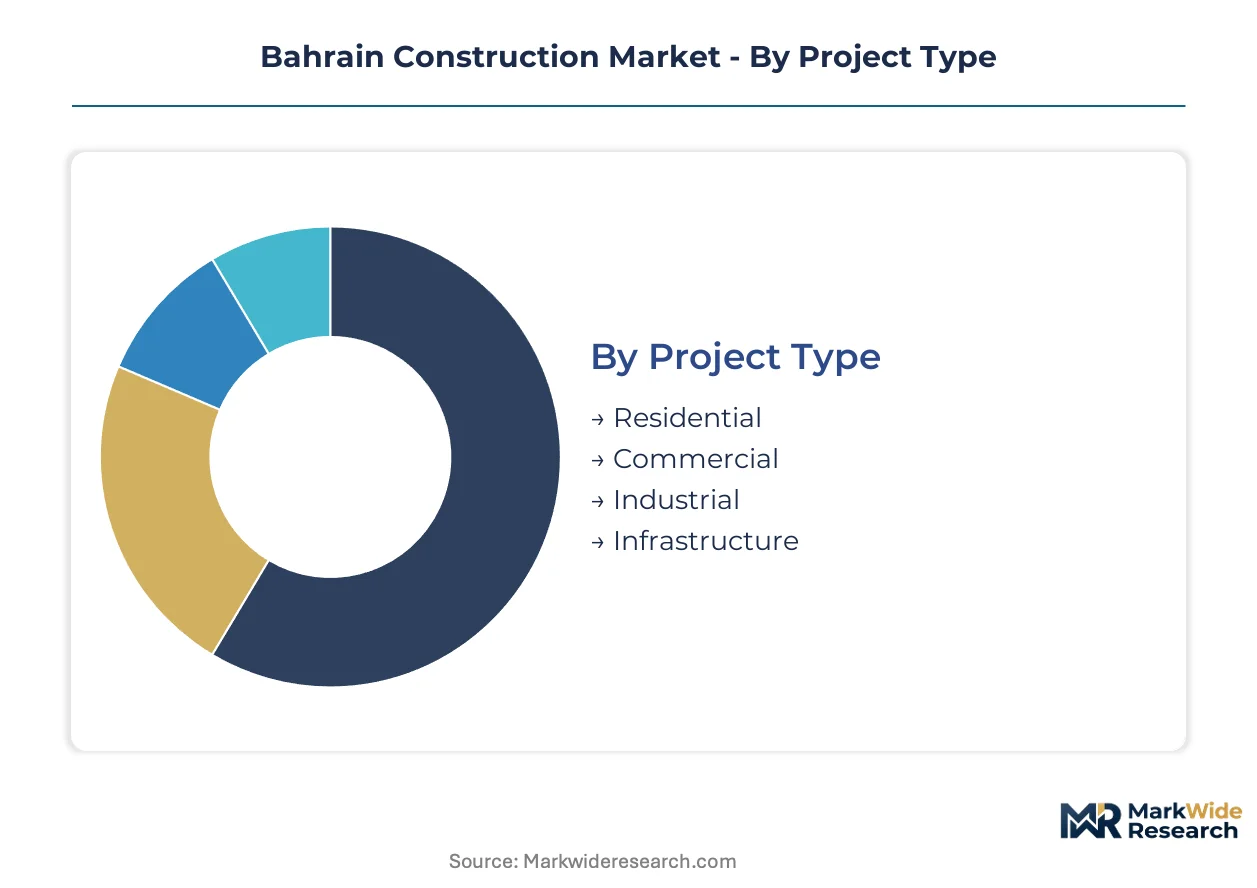
Segmentation reveals how capital deployment, regulatory exposure, and delivery risk distribute across Bahrain's construction pipeline. Project sponsors use these categories to match financing structures with asset durability requirements.
Project Type:
Capital intensity varies sharply across project types, with infrastructure and industrial builds demanding the longest capital lock-up periods.
- Infrastructure:Heavy civil works including metro tunnels, causeway logistics corridors, and port modernization require sovereign-backed financing and multi-year construction windows. Demand concentrates in Manama and Muharraq where the Ministry of Transportation is advancing rail and highway interchanges, though foreign labor quota constraints compress peak workforce deployment.
- Residential:Mid-rise towers and affordable housing clusters in Salman City deploy standardized designs that accelerate permit cycles through the Ministry of Housing's subsidized finance programs. Concrete frame construction dominates given local ready-mix supply density.
- Commercial:Mixed-use developments in Seef District and the Capital Governorate integrate office, retail, and hospitality functions with curtain-wall assemblies meeting Civil Defense Directorate fire-resistance mandates.
- Industrial:Bonded warehouses and cold storage facilities near King Fahd Causeway-linked zones serve Saudi import flows with steel framing for faster floor-cycle completion.
Most installed capacity flows through Residential. Expansion is steepest in Infrastructure.
Material Type:
Material selection tracks exposure to Bahrain's saline coastal conditions and seismic Zone II-B engineering requirements.
- Concrete:Ready-mix formulations with corrosion-inhibiting additives dominate foundation and structural work across all project types. The Northern Governorate's hospitality pipeline absorbs premium-grade mixes for coastal durability.
- Steel:Rebar and structural sections face price volatility tied to Persian Gulf scrap flows, though faster erection schedules command premium pricing in commercial high-rises where floor-cycle speed determines returns.
- Glass:Curtain-wall assemblies require third-party fire-resistance certification under amended Bahrain National Building Code provisions, filtering specification eligibility to tested suppliers.
- Wood:Limited structural application given humidity and termite exposure; confined to interior finishes and temporary works.
Concrete commands the largest volume share. Steel is gaining specification share fastest in vertical commercial construction.
End User:
End-user type determines procurement rigor, payment security, and design flexibility latitude.
- Government:Ministry of Works and Ministry of Housing projects enforce Bahrain National Building Code compliance through staged milestone payments, with green certification from the Sustainable Energy Authority conditioning final approvals.
- Private Sector:Real estate investment trusts and corporate owners in Seef District prioritize speed-to-market, accepting design-build contracts that transfer risk to contractors with in-house digital capabilities.
- Developers:Mixed-use portfolio sponsors consolidate multi-source contractor rosters to de-risk simultaneous tower launches across the Northern Governorate.
- Contractors:Self-performed developments by integrated firms like Nass Corporation leverage captive engineering and fabrication capacity for marine and heavy civil works.
Government contracts anchor payment security standards. Private sector projects are expanding most quickly in the Capital Governorate.
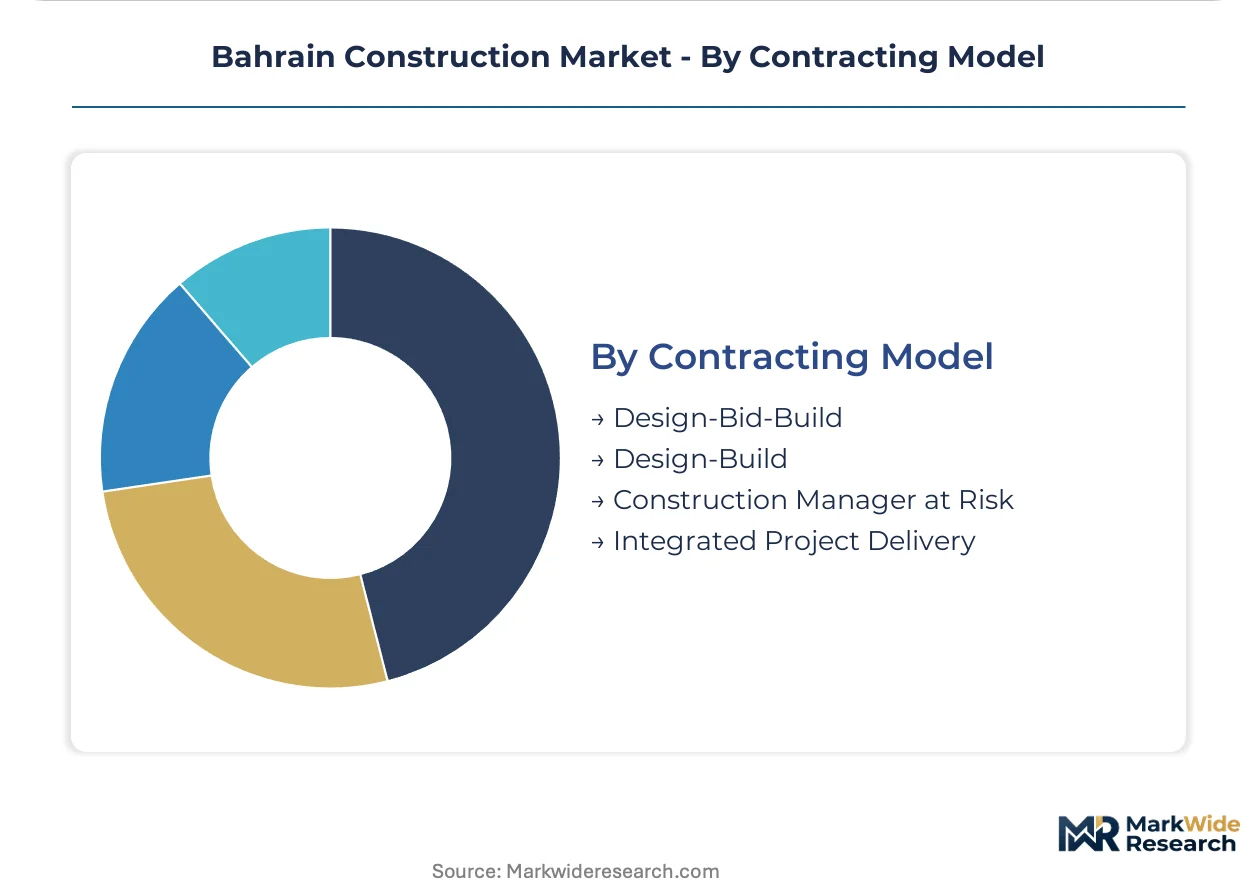
Contracting Model:
Model selection reflects risk allocation preferences and the availability of design-phase data for coordination.
- Design-Build:Single-source responsibility compresses timelines for commercial towers where clash-detection workflows and BIM coordination reduce field change orders. The model transfers seismic engineering liability to contractors.
- Design-Bid-Build:Traditional sequential procurement persists in government infrastructure where Ministry of Works specifications mandate discrete design review phases before tender.
- Construction Manager at Risk:Guaranteed maximum price contracts appeal to developers seeking cost certainty across multi-phase residential clusters.
- Integrated Project Delivery:Early contractor involvement with shared risk pools remains nascent, constrained by limited pool of certified engineers for Zone II-B structural calculations.
Design-Bid-Build retains the largest contract volume. Design-Build is climbing the fastest as private developers accelerate mixed-use delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manama and the Northern Governorate anchor Bahrain's construction pipeline, with mixed-use developments and port modernization projects clustering along these coastal zones. Government infrastructure programs are expanding adoption across transportation and utility corridors. The analysis examines four sub-regions where capital deployment concentrates.
Manama
The Capital Governorate absorbs the densest commercial tower activity, with Seef District developers mandating clash-detection workflows before concrete pours. The Ministry of Works enforces Bahrain National Building Code compliance through staged milestone payments. Civil Defense Directorate fire-resistance mandates for curtain-wall assemblies are filtering specification eligibility to tested suppliers in this zone.
Northern Governorate
Affordable housing clusters in Salman City and hospitality pipelines along the coast are deploying standardized designs that accelerate permit approvals. The Ministry of Housing's subsidized finance programs channel demand toward mid-market residential segments. Modular precast units are penetrating the hospitality sector here, compressing on-site assembly timelines.
Muharraq
The Ministry of Transportation is advancing Bahrain Metro Phase 2 tunneling and station complex construction across this island governorate. Specialized civil contractors are mobilizing for rail expansion works. The Labor Market Regulatory Authority's foreign worker permit caps are constraining workforce scaling during these peak construction phases.
Southern Governorate
Industrial zones near the King Fahd Causeway are attracting bonded warehouse and cold storage developers seeking proximity to Saudi import flows. Steel framing dominates these facilities for faster floor-cycle completion. The Sustainable Energy Authority's greywater reuse requirements are opening specification windows for integrated plumbing contractors in this logistics corridor.
Bahrain Construction Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular fabrication and digital coordination capabilities. The market structures around heavy civil specialists, government-aligned contractors, and speed-focused residential builders. Three archetypes dominate: integrated engineering-fabrication firms, relationship-driven institutional builders, and modular technique adopters. Competitive moves concentrate on multi-source procurement consolidation and design-build risk transfer.
Within the integrated engineering tier, Nass Corporation anchors heavy civil and marine works through captive capabilities. Kooheji Contractors exemplifies the government-relationship archetype, sustaining institutional build pipelines through agency proximity. Dadabhai Construction occupies the speed-to-market position, differentiating through modular construction techniques that compress residential tower schedules.
| Leading Market Players |
|---|
| Dadabhai Construction |
| Kooheji Contractors |
| Nass Corporation |
| Larsen & Toubro Bahrain |
| Projects Holding Company |
| Haji Hassan Group |
| Delta Construction Co. |
| Parsons Bahrain |
| Almoayyed Contracting Group |
| Others |
Supply Flow & Price Mechanics
Multi-source procurement consolidation by Bahrain's largest developers is forcing contractors to absorb price volatility on long-dated material commitments while maintaining bid competitiveness. This buyer-driven compression of contractor margins feeds back into supply chain choices, accelerating regional sourcing from Saudi Arabia and the UAE to reduce freight exposure and currency risk.
Pricing Analysis
Input-cost pass-through dominates Bahrain's construction pricing, with rebar and structural steel quotations tracking Persian Gulf scrap metal flows on weekly adjustment cycles. Price differentiation separates government-backed infrastructure tiers from speculative commercial developments, where Ministry of Works milestone payments reduce contractor working-capital costs. Pricing pressure stems from foreign labor quota caps that constrain workforce scaling during peak phases, inflating overtime premiums. Private developers in Seef District exhibit lowest price sensitivity, prioritizing speed-to-market over material cost optimization.
Supply Chain Analysis
Regional distribution centers in Dammam and Dubai anchor Bahrain's construction material flows, with hub-and-spoke patterns feeding ready-mix plants and steel fabrication yards across Manama and the Northern Governorate. Geographic supply concentration draws from Saudi Arabia, the UAE, and Oman for cement and aggregates, while structural steel hinges on Turkish and Chinese mill shipments. Single-source vulnerability runs through the Strait of Hormuz shipping lane, where disruptions cascade into rebar delivery delays. Distribution runs through bonded warehouse facilities near Khalifa Bin Salman Port, enabling just-in-time delivery for modular precast units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bahrain's construction market reads as a late-cycle quality story, with Sustainable Energy Authority green certification mandates shifting specification preferences toward premium-grade concrete additives and corrosion-resistant reinforcement.
For Market Incumbents: Deepen captive engineering capabilities for Zone II-B seismic calculations, creating bottlenecks that filter out smaller competitors during design review phases. Anchor multi-project resource flexibility to secure consolidated procurement panels, defending against modular fabrication entrants penetrating the hospitality sector. Prioritize certification investment with the Civil Defense Directorate for curtain-wall assemblies, raising specification barriers. For New Entrants and Emerging Players: Small-to-mid industrial developers near King Fahd Causeway-linked zones represent an underserved buyer archetype, with greywater recycling mandates opening specification windows for integrated plumbing contractors. Target bonded warehouse and cold storage segments where steel framing expertise transfers from commercial high-rise experience. Pursue design-build contracts with early BIM coordination capabilities to differentiate from traditional sequential procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated engineering-fabrication firms holding captive marine and heavy civil capabilities, as Bahrain Metro Phase 2 and port modernization programs extend capital deployment windows. Firms demonstrating cross-project resource flexibility across the Northern Governorate residential pipeline offer strongest acquisition profiles. Monitor foreign labor quota adjustment announcements from the Labor Market Regulatory Authority as inflection indicators for workforce cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Precast Expansion | Factory-built volumetric units compress Northern Governorate hospitality assembly from months to weeks. |
| Green Certification Investment | Sustainable Energy Authority compliance reduces Bahrain National Building Code approval cycles substantially. |
| Multi-Source Procurement Consolidation | Developer panels concentrate award volumes with cross-project resource flexible contractors. |
| Seismic Engineering Specialization | Zone II-B certified engineers create design-review bottlenecks filtering smaller competitors. |
| Regional Distribution Hub Development | Dammam-Dubai hub-and-spoke patterns reduce Strait of Hormuz freight exposure for critical inputs. |
Methodological Framework
Coverage spans Bahrain's four governorates with primary inputs from each, combining structured interviews with Ministry of Works procurement officers, Sustainable Energy Authority certification specialists, contractor project directors, and ready-mix supplier operations managers. Secondary validation draws from Bahrain National Building Code amendment filings, Labor Market Regulatory Authority permit statistics, Ministry of Transportation infrastructure announcements, and customs import records for steel and cement. Bottom-up project pipeline enumeration triangulates against top-down construction sector GDP contributions.
Rate-of-change decomposition separates volume growth from price effects across the projection horizon, with analytical framework modeling project type, material specification tier, end-user procurement rigor, and contracting model risk allocation. CAGRs derive from segment-level deployment curves adjusted for permit approval velocity and foreign labor quota constraints. Forecast inputs incorporate seismic engineering certification availability and green certification mandate phase-in schedules.
Underlying measurement precision varies by segment; government infrastructure with disclosed Ministry of Works budgets carries tighter precision than speculative private commercial developments. Forecasts reflect documented assumptions around sovereign debt capacity and labor policy continuity. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that permit synchronization delays and material price volatility can reshape project feasibility independently of demand fundamentals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
Gas Pipeline Infrastructure Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
Poland Transportation Infrastructure Construction Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market