
 Garage and Overhead Doors Market | 2026-2036
Garage and Overhead Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Garage and Overhead Doors Market Analysis
UL 325 safety certification is bifurcating the competitive landscape into qualified and non-qualified suppliers. Overhead Door Corporation leverages its vertically integrated manufacturing network to sustain cost advantages across residential and commercial channels. ASSA ABLOY anchors its position through advanced access control integration, while Hormann Group specializes in thermally efficient European panel designs that compete on building envelope performance.
Garage and overhead doors are engineered access systems comprising hinged or rolling panels, track hardware, and counterbalance mechanisms designed to seal building openings against weather, intrusion, and thermal transfer. Steel sectional doors with polyurethane foam cores typically achieve R-values between 12 and 18, serving primary functions in climate-controlled storage, vehicle protection, and facility security. Roller doors dominate commercial loading bay applications where space constraints and cycle frequency prioritize compact coiling action, while sectional doors retain margin strength in premium residential segments through customization and insulation upgrades. Electric operating mechanisms are displacing manual systems across industrial end users as labor costs and safety liability reshape procurement criteria.
FCC governs radio-frequency remote control devices, while UL 325 mandates entrapment protection for automatic operators sold in the United States. OSHA workplace safety standards further influence commercial and industrial installation requirements, particularly in facilities with high-cycle door usage. Stakeholders must monitor evolving building energy codes and smart building integration standards as these frameworks increasingly determine product qualification and project specification authority.
Market Dynamics
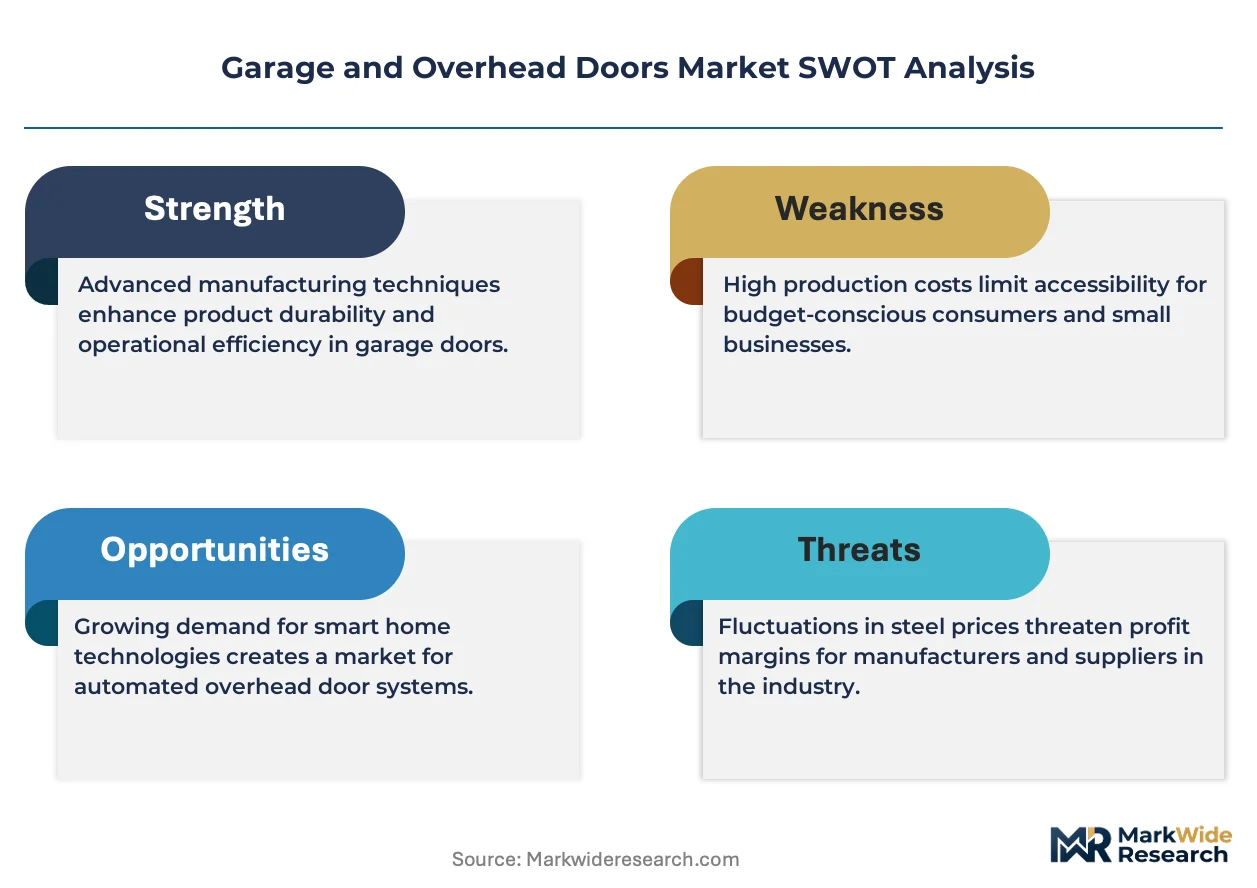
Energy efficiency mandates are restructuring procurement authority toward building envelope performance specifications, compressing margins for non-insulated product lines while rewarding thermal engineering capabilities.
Growth Catalysts
- OSHA workplace safety standards:High-cycle industrial facilities face liability exposure that accelerates automatic operator replacement of manual systems. Entrapment protection requirements expand addressable equipment value per door.
- Steel supply concentration in the United States:Domestic mill capacity expansion reduces lead time volatility for sectional panel manufacturers serving residential construction pipelines.
- Polyurethane foam core technology:Continuous lamination processes achieve R-18 thermal performance in thinner profiles, enabling compliance with stringent envelope codes without track hardware modifications.
Market Restraints
- Aluminum and steel input cost volatility:Coil pricing fluctuations compress fabrication margins for mid-tier suppliers lacking forward contract coverage.
- Spring counterbalance supply concentration:Torque spring manufacturing clusters in select Midwest industrial corridors create geographic vulnerability for national distribution networks.
- Manual operator substitution ceiling:Low-cycle residential detached garages retain cost-driven preference for torsion spring manual systems in price-sensitive segments.
Strategic Opportunities
- Smart building integration protocols:BACnet and Modbus connectivity standards create specification entry points for door operators within integrated facility management systems.
- Commercial retrofit channel development:Direct contractor relationships bypass traditional distribution markups in aging logistics facility upgrade cycles.
- IRA energy efficiency tax credits:Residential insulated door upgrades qualify for federal incentives that narrow premium product price gaps.
Industry Challenges
- UL 325 certification timeline compression:Third-party testing queue congestion delays product launch windows for entrapment protection system updates.
- Installation technician skill scarcity:Torsion spring calibration and automated control integration require training investments that independent dealers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garage and Overhead Doors Market |
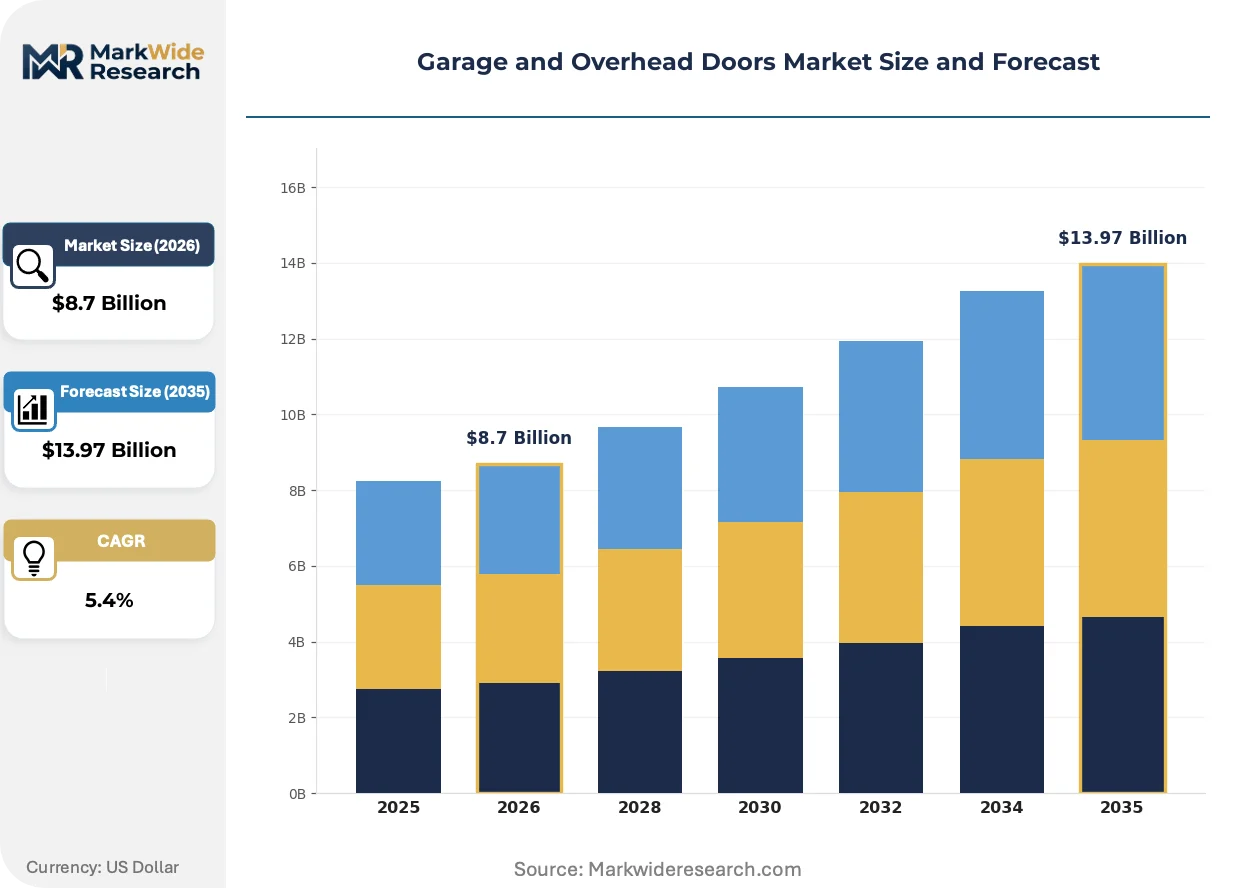
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sectional Doors, Roller Doors, Tilt-Up Doors, Swing-Out Doors Material: Steel, Aluminum, Wood, Fiberglass End User: Residential, Commercial, Industrial, Agricultural Operating Mechanism: Manual, Electric, Automatic, Remote-Controlled |
| Companies Covered | Overhead Door Corporation, ASSA ABLOY, Hormann Group, Clopay Corporation, Raynor Garage Doors, C.H.I. Overhead Doors, Wayne Dalton, Amarr Garage Doors, Griffon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garage and Overhead Doors Market Emerging Trajectories
Connected access systems and thermal performance engineering are converging to redefine competitive differentiation beyond hardware durability toward envelope intelligence and operational data integration.
Cellular polyurethane injection is supplanting slab foam cores in sectional door manufacturing. Logistics operators with climate-controlled storage mandates specify these panels for reduced thermal bridging. The technology is compressing cost premiums for high-R-value configurations toward standard product tiers.
Building energy codes in California and Massachusetts now mandate minimum R-values for conditioned garage spaces attached to residential structures. Code officials are rejecting permits for non-compliant door specifications. Manufacturers with pre-certified assemblies capture specification authority in permit-driven markets.
Facility managers now bundle door maintenance within comprehensive equipment service agreements rather than transactional repair calls. National property management firms centralize vendor selection through preferred provider networks. This concentration is visible in multi-site retail and distribution portfolios where standardization reduces procurement overhead.
Garage and Overhead Doors Market Segmentation
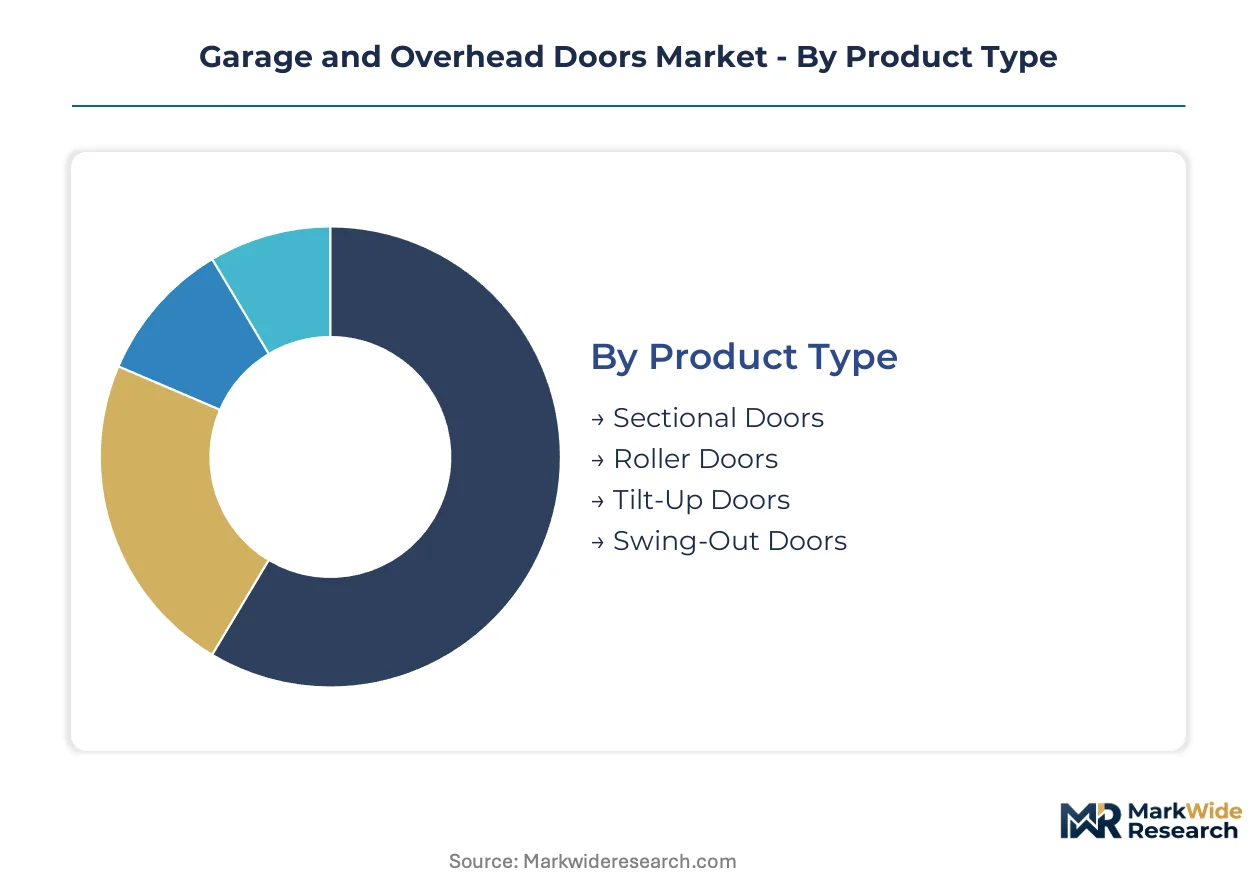
Door specification authority now flows through building envelope performance codes and automated facility integration requirements. Procurement decisions increasingly separate around thermal certification thresholds and smart building protocol compatibility rather than traditional hardware durability metrics.
Product Type:
UL 325 entrapment protection mandates and cycle-frequency requirements create divergent specification pathways across residential, commercial, and industrial installations.
- Sectional Doors:Hinged panel assemblies with polyurethane foam cores achieve R-12 to R-18 thermal performance through continuous lamination. United States residential construction pipelines concentrate specification volume here, with attached garage energy codes in California and Massachusetts rejecting non-compliant alternatives.
- Roller Doors:Coiling steel or aluminum slats operate within compact headroom envelopes ideal for loading bay constraints. Warehouse and logistics facilities with high-cycle operations prioritize these configurations where space optimization and durability under frequent use reshape procurement criteria.
- Tilt-Up Doors:Single rigid panels pivot on bottom-mounted hardware for cost-sensitive applications with moderate cycle requirements.
- Swing-Out Doors:Side-hinged carriage-style designs serve aesthetic-driven residential renovations and heritage building restoration projects.
Sectional doors handle the majority of throughput; roller doors are expanding most quickly on share as logistics automation accelerates.
Material:
Cost tier differentiation separates commodity coil-fed fabrication from premium thermal engineering and aesthetic customization capabilities.
- Steel:Galvanized coil stock with polyurethane injection cores dominates volume production through continuous roll-forming lines. Domestic United States mill capacity expansion reduces lead time volatility for sectional panel manufacturers serving construction pipelines.
- Aluminum:Extruded or roll-formed profiles with lower structural mass suit corrosive coastal environments and weight-restricted commercial retrofits.
- Wood:Solid or engineered lumber assemblies command premium positioning in custom residential segments through grain pattern and stain customization.
- Fiberglass:Composite skin constructions with foam cores deliver moisture immunity and thermal performance for climate-extreme applications.
Steel commands the volume base; fiberglass is climbing the fastest as envelope code stringency intensifies.
End User:
Application-specific cycle frequency and safety liability exposure determine operator mechanism selection and maintenance contract structures.
- Residential:Single-family and multi-family detached structures drive specification through permit-driven energy code compliance and aesthetic customization preferences.
- Commercial:Retail storefronts, office buildings, and service facilities balance access convenience with security integration requirements.
- Industrial:Manufacturing plants and distribution centers with high-cycle loading operations face OSHA workplace safety standards that accelerate automatic operator deployment.
- Agricultural:Barns, equipment storage, and livestock facilities prioritize weather sealing and large opening spans over thermal performance optimization.
Residential channels absorb the highest unit volume; industrial applications are gaining share fastest through automation mandates.
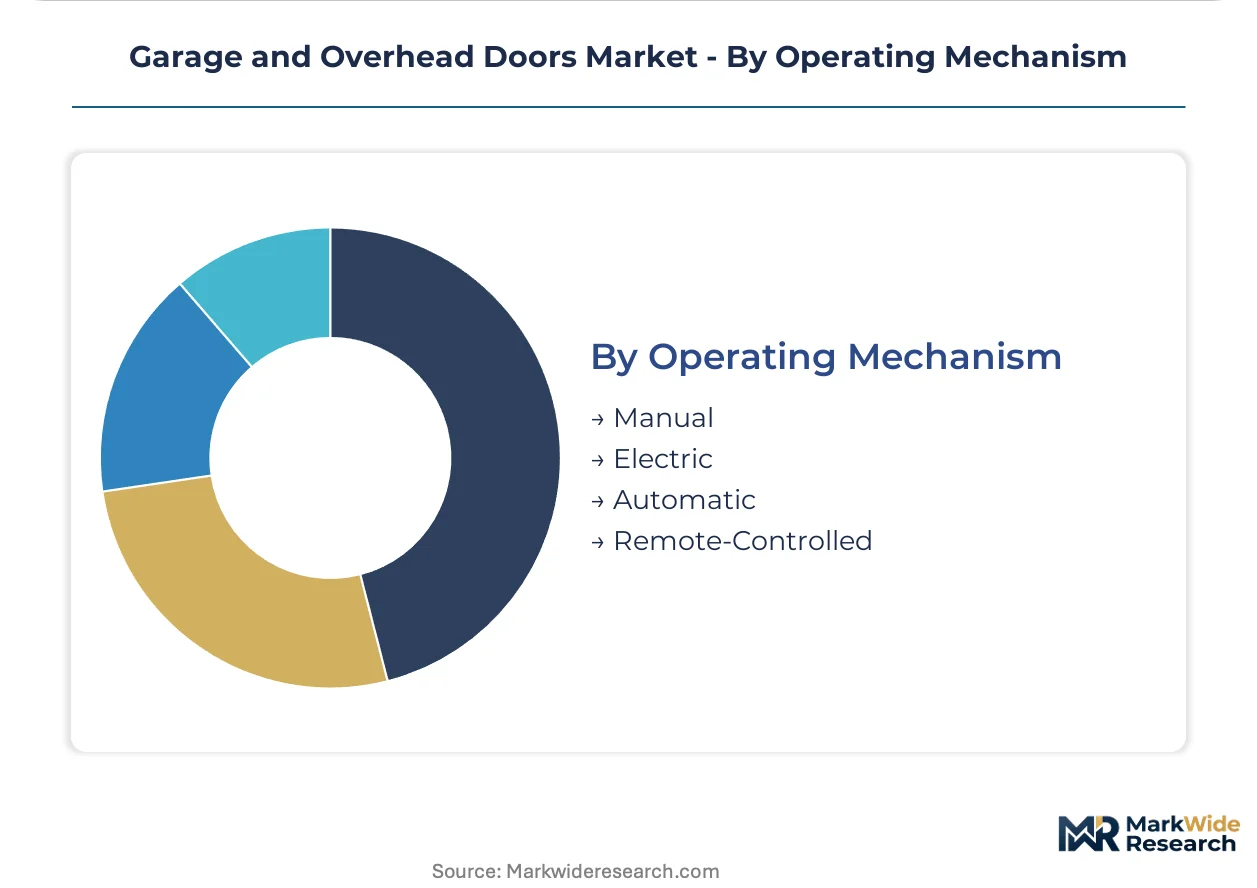
Operating Mechanism:
Customer type and facility maturity separate manual legacy installations from connected access system upgrades.
- Manual:Torsion spring counterbalance systems retain cost-driven preference in low-cycle residential detached garages where price sensitivity dominates.
- Electric:Motor-driven chain or belt operators with basic wall-switch control serve standard commercial and residential replacement cycles.
- Automatic:Sensor-activated systems with entrapment protection satisfy UL 325 certification requirements for high-traffic industrial and commercial facilities.
- Remote-Controlled:Radio-frequency and Wi-Fi enabled operators integrate with smart home and facility management platforms through BACnet and Modbus protocols.
Electric mechanisms maintain the installed base; remote-controlled systems show the steepest expansion trajectory as building automation convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy efficiency tax credits and building envelope codes are redirecting procurement authority toward thermally certified products in major construction markets. Residential retrofit incentives and logistics facility automation are expanding automatic door installations across diverse geographies.
United States
Residential construction pipelines and commercial retrofit activity concentrate demand in metropolitan construction corridors. The Inflation Reduction Act energy efficiency tax credits narrow premium insulated door price gaps for homeowner upgrades. Domestic steel mill capacity expansion near Chicago and Pittsburgh reduces lead time volatility for sectional panel manufacturers serving national distribution networks.
Germany
Thermally efficient building envelope standards drive specification toward high-R-value panel designs in residential and commercial applications. The EU Green Deal and national building energy codes mandate minimum thermal performance thresholds for conditioned structures. Manufacturing clusters in North Rhine-Westphalia and Baden-Württemberg specialize in precision-engineered hardware and continuous lamination processes for polyurethane-core assemblies.
China
Rapid logistics infrastructure expansion and warehouse automation accelerate high-cycle roller door deployment in coastal manufacturing zones. GB standards for building energy efficiency and industrial safety reshape product qualification requirements. Production gravity concentrates in Yangtze River Delta and Pearl River Delta regions where steel processing and door fabrication supply chains achieve scale economies.
Japan
Earthquake-resistant building codes and space-constrained urban construction favor compact coiling door mechanisms in commercial and industrial facilities. METI energy conservation standards for commercial buildings elevate thermal performance specifications. Industrial clusters in Kansai and Chubu regions maintain specialized manufacturing capabilities for precision track hardware and automated control systems.
Canada
Cold climate construction and energy efficiency codes drive demand for high-R-value insulated sectional doors in residential and agricultural applications. National building code updates and provincial energy regulations tighten thermal bridging requirements. Manufacturing and distribution networks concentrate in Southern Ontario and Quebec corridors serving cross-border residential construction pipelines.
Garage and Overhead Doors Market Vendor Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. The vendor base organizes into three tiers: multinational building products conglomerates with integrated access control portfolios, family-owned regional fabricators with deep contractor relationships, and specialized automation technology providers. Consolidation pressure operates through acquisition of regional installation networks and technology licensing arrangements for smart building protocol integration.
Among established North American manufacturers, Overhead Door Corporation and Clopay Corporation occupy positions within the scale-driven tier, while Hormann Group represents European thermal engineering specialization. These companies exemplify divergent strategic archetypes: vertically integrated manufacturing networks versus precision-engineered panel design capabilities versus continental brand distribution systems.
| Leading Market Players |
|---|
| Overhead Door Corporation |
| ASSA ABLOY |
| Hormann Group |
| Clopay Corporation |
| Raynor Garage Doors |
| C.H.I. Overhead Doors |
| Wayne Dalton |
| Amarr Garage Doors |
| Griffon Corporation |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day steel coil lead times concentrate procurement leverage with domestic mill contract holders, compressing margin buffers for spot-market buyers while insulating vertically integrated manufacturers from price volatility. This inventory positioning advantage translates directly into pricing power across residential construction channels where builders prioritize schedule certainty over unit cost optimization.
Pricing Analysis
Certification level creates the primary spread between qualified and non-qualified suppliers in this market. UL 325 entrapment protection compliance separates premium automatic operators from uncertified alternatives, while thermal performance tiering distinguishes R-18 insulated assemblies from basic non-insulated configurations. Pricing pressure stems from aluminum and steel input cost volatility that compresses fabrication margins for mid-tier suppliers lacking forward contract coverage. Residential detached garage segments exhibit highest price sensitivity, while industrial logistics operators prioritize cycle durability and safety liability reduction over unit economics.
Supply Chain Analysis
Just-in-time coil delivery preferences dominate residential panel manufacturing, while strategic spring stockpiling persists among operators mitigating torque spring supply concentration risks. Manufacturing gravity centers on the United States, Germany, and China, with domestic mill expansion near Chicago and Pittsburgh reducing lead time volatility for North American suppliers. Raw material dependencies encompass galvanized steel coil, polyurethane foam chemicals, and torsion spring wire. Single-source vulnerability in Midwest torque spring manufacturing corridors creates geographic risk for national distribution networks. Distribution runs through dealer-installer networks for residential channels and direct contractor relationships for commercial retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against smart building integration platforms that could displace standalone door operators with comprehensive access control ecosystems. Incumbents must navigate entrant pressure from connected home technology providers bundling garage access into broader automation suites.
For Market Incumbents: Consolidate regional installation networks to capture maintenance contract concentration trends among national property management firms. Deepen captive supply of polyurethane foam core lamination capacity to defend margin position against raw material volatility. Prioritize BACnet and Modbus protocol certification investments to maintain specification authority within integrated facility management systems.
For New Entrants and Emerging Players: Anchor in commercial retrofit channels where aging logistics facilities bypass traditional distribution markups through direct contractor relationships. Target mid-cycle agricultural applications currently underserved by thermal engineering specialists. Pursue smart home platform partnerships as the primary go-to-market angle rather than hardware-only positioning.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification authority is concentrating toward building envelope performance codes and smart building protocol compatibility. Acquisition targets should emphasize regional fabricators with deep contractor relationships and pre-certified thermal assemblies. Watch for inflection when IRA energy efficiency tax credit utilization rates cross thresholds indicating sustained premium product demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Building Protocol Certification | BACnet and Modbus integration secures specification entry within facility management platforms. |
| Regional Installation Network Acquisition | Captures maintenance contract concentration trends among multi-site property managers. |
| Polyurethane Core Lamination Scale-Up | Continuous R-18 production enables compliance with California and Massachusetts energy codes. |
| Direct Contractor Channel Development | Bypasses distribution markups in commercial logistics facility upgrade cycles. |
| Entrapment Protection System R&D | UL 325 compliance timelines create competitive moats against uncertified competitors. |
Methodological Framework
A spread of perspectives from door system manufacturers, installation contractor networks, commercial facility managers, and building code officials converged on the working assumptions driving this analysis. Primary fieldwork encompassed structured interviews with procurement leads at national property management firms, maintenance directors at distribution centers, and permitting officials in California and Massachusetts. Secondary validation drew from OSHA enforcement data, UL certification registries, building permit databases, and steel industry trade association reports. Bottom-up unit economics triangulated against top-down construction spending patterns across the analysis window.
Segmentation dimensions modeled include product type, material composition, end-user application, and operating mechanism complexity across the projection horizon. CAGRs were derived from installation volume trends, replacement cycle frequencies, and code adoption timelines rather than macroeconomic extrapolation. Industry-specific forecast inputs incorporated polyurethane foam chemical pricing indices and domestic steel mill capacity utilization rates.
Decision-makers should treat outputs as directional under sustained residential construction activity and logistics automation investment assumptions; material deviation would warrant model refresh. Revision becomes warranted when UL 325 certification queue congestion or spring supply disruption crosses thresholds affecting product availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
Italy Prefab Wood Buildings Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Angular Rubber Expansion Joints Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Curtain Wall Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Composite Roof Shingle Market