
 US Windows Market | 2026-2036
US Windows Market Size, Share, and Industry Trends Forecast 2026-2036
US Windows Market Insights
The US Southeast is tilting toward expanded vinyl extrusion and fiberglass pultrusion capacity to serve coastal and inland markets. Andersen Corporation leverages backward integration into wood composite sourcing to control material consistency across its supply chain. Pella Corporation sustains premium positioning through proprietary impermeable glazing systems and architect-specified product lines. JELD-WEN Holding, Inc. anchors volume production across its distributed plant network, competing aggressively on replacement cycle timing and contractor channel access.
Windows are transparent or translucent framed assemblies, typically incorporating single, double, or triple-pane glazing with low-emissivity coatings and inert gas fills, manufactured through glass cutting, spacer fabrication, and sash/frame assembly processes designed to control thermal transfer, daylight admission, and structural loads in building envelopes. Double-hung windows occupy the largest installed base in residential replacement, reflecting compatibility with existing rough openings and familiarity among regional contractors. Fiberglass frames represent the fastest-expanding material category as builders prioritize dimensional stability in extreme temperature swings and extended product lifecycle performance. Vinyl retains dominant volume share in new construction starter and mid-tier housing segments where cost thresholds govern specification decisions.
The Department of Energy enforces escalating thermal transmittance standards through model energy codes adopted at state and municipal levels, compelling manufacturers to reformulate spacer systems and coating stacks. EPA Energy Star certification operates as a de facto market access filter for products sold through retail and utility rebate channels, while local building departments in hurricane-prone jurisdictions enforce Miami-Dade County impact resistance protocols that limit supplier participation. Stakeholders must monitor code adoption divergence between states with aggressive decarbonization timelines and jurisdictions resisting federal stringency, as this fragmentation will determine where product portfolios require recertification investment versus standardization leverage.
Market Dynamics
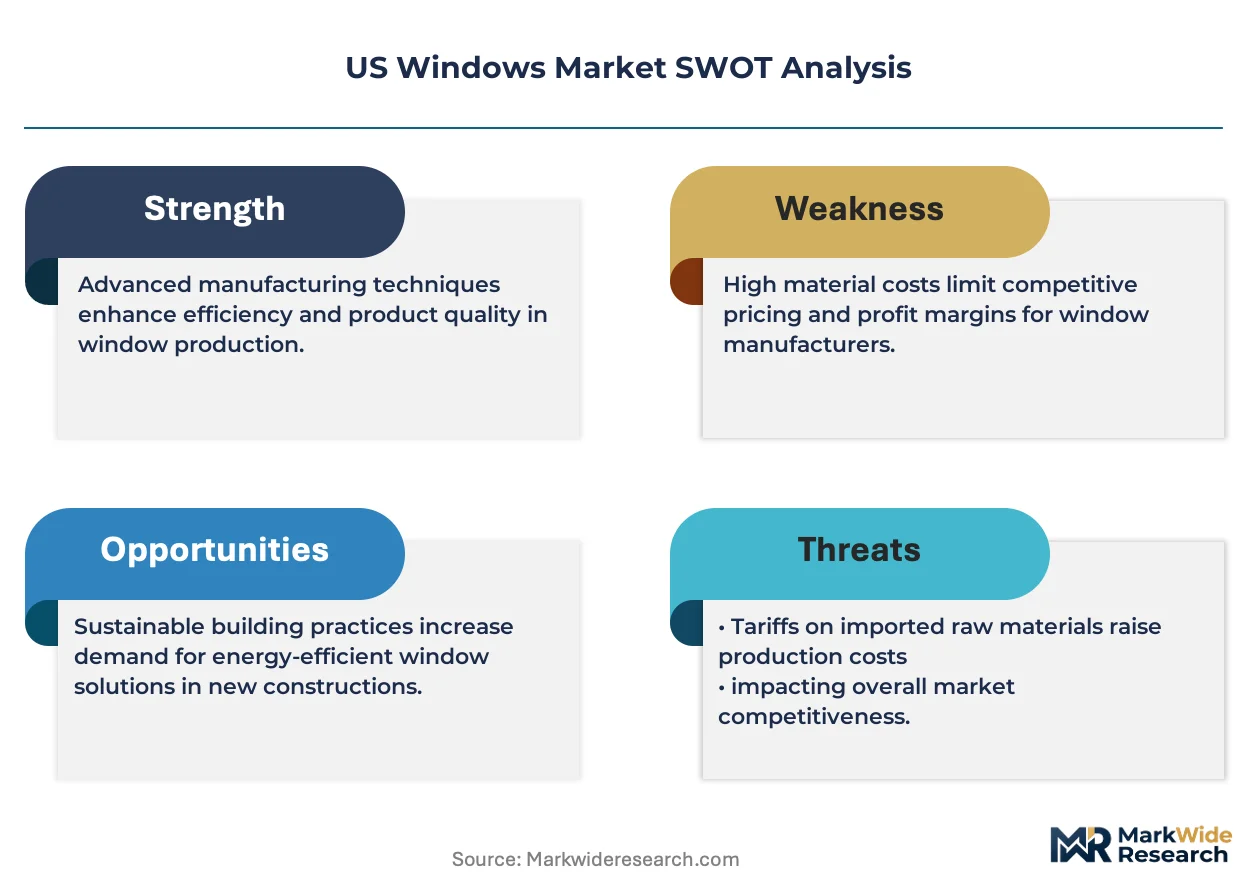
EPA Energy Star certification and DOE model energy code adoption are tightening thermal performance thresholds faster than manufacturing capacity can retool, forcing reformulation of spacer systems and coating stacks across the supply base.
Growth Catalysts
- DOE Building Code Escalation:State-level adoption of stricter thermal transmittance standards is compelling replacement demand in jurisdictions with aggressive decarbonization timelines.
- Fiberglass Pultrusion Capacity:Material suppliers are expanding dimensional-stable frame production to serve Sun Belt builders prioritizing lifecycle performance in extreme temperature swings.
- Texas-Arizona-Florida Permit Concentration:Elevated new housing starts in these three states are concentrating fenestration orders with regional fabricators.
Market Restraints
- Float Glass Input Volatility:Energy-intensive flat glass production faces natural gas price exposure that compresses margin predictability for integrated and non-integrated manufacturers alike.
- Miami-Dade Impact Certification Concentration:Hurricane-prone jurisdictions limit supplier participation through county-specific testing protocols that exclude smaller fabricators without capital for redundant certification.
- Aluminum Frame Substitution Ceiling:Commercial mid-rise developers in cost-sensitive submarkets retain specification preference for thermally-broken aluminum despite superior fiberglass performance metrics.
Strategic Opportunities
- IRA Residential Efficiency Rebates:Inflation Reduction Act tax credits for high-performance envelope upgrades are creating price-point elasticity for triple-pane and suspended-film systems in replacement channels.
- Utility-Administered Rebate Channels:Regional power distributors are expanding direct-to-contractor incentive programs that bypass traditional retail markup structures.
- Smart Glass Convergence:Integration of electrochromic and thermochromic technologies with conventional insulated glazing units is opening architect-specified premium segments.
Industry Challenges
- Spacer System Thermal Bridge Engineering:Warm-edge technology migration requires recalibration of automated assembly lines originally configured for aluminum box spacers.
- Multi-Jurisdictional Certification Timelines:Fabricators serving both Energy Star retail channels and Miami-Dade impact markets must maintain parallel testing documentation with divergent renewal cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Windows Market |
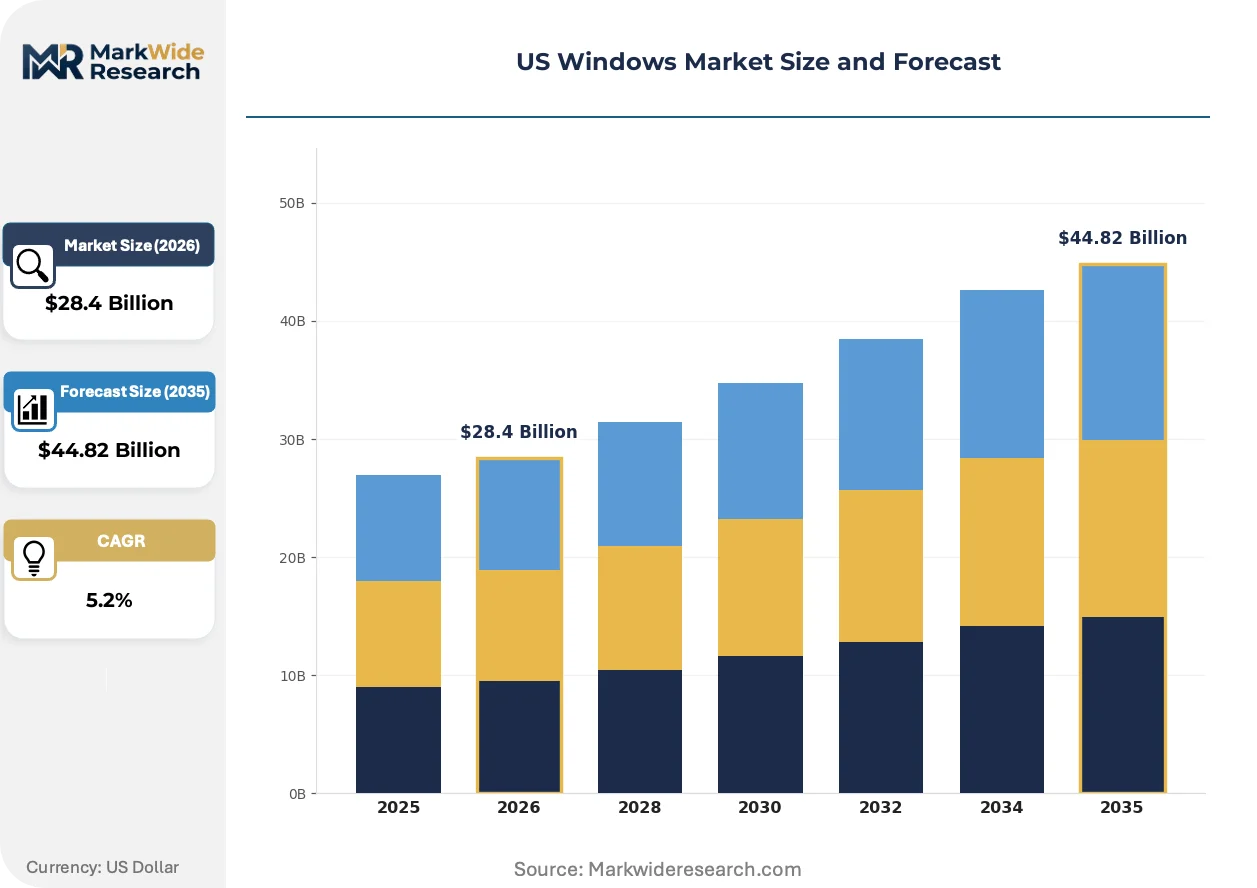
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $44.82 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Windows, Casement Windows, Awning Windows, Double-Hung Windows Material: Vinyl, Wood, Aluminum, Fiberglass Installation Type: New Construction, Replacement, Retrofit, Customized End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Andersen Corporation, Pella Corporation, Marvin Windows and Doors, JELD-WEN Holding, Inc., MI Windows and Doors, Milgard Manufacturing, Inc., PGT Innovation, Inc., Cornerstone Building Brands, Harvey Building Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Windows Market Trends and Innovations
Material science advances and procurement model compression are reshaping how fenestration products reach end-users. Three developments merit particular attention.
Vacuum-insulated glazing is collapsing the thermal performance gap between conventional triple-pane units and thinner, lighter assemblies. High-end residential architects in California and Pacific Northwest markets are specifying these systems for retrofit applications where rough opening depth constraints prohibit standard triple-pane thickness. The technology is collapsing the traditional trade-off between thermal performance and structural load requirements in historic renovation projects.
EPA Energy Star Most Efficient designation criteria are tightening faster than baseline certification, creating a two-tier access structure for retail and utility rebate channels. Manufacturers must now maintain separate product lines and testing documentation for baseline versus premium efficiency tiers. The Southeast and Southwest regional markets show the widest divergence in adoption timing, with Texas municipalities lagging California air districts by 18-24 months in stringency alignment.
Contractor-direct procurement platforms are consolidating order aggregation for regional production builders, compressing distributor margins and reordering channel economics. National production builders in Florida and Arizona are consolidating specification authority at corporate level, displacing local subcontractor autonomy in material selection. This concentration is most visible in starter and mid-tier housing segments where volume scale justifies dedicated production lines at fabricator plants.
US Windows Market Segmentation
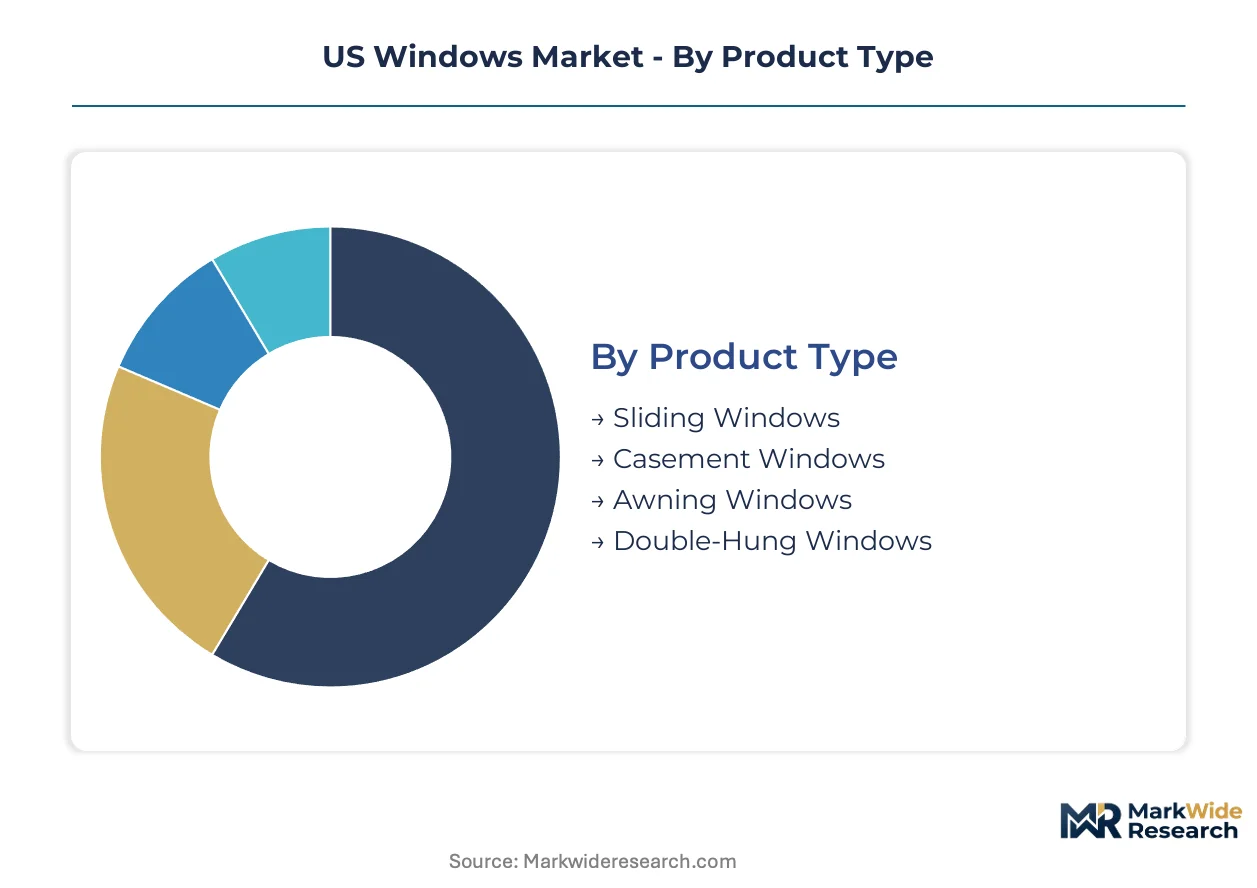
Window specification in the US market fragments across four intersecting dimensions that determine thermal performance thresholds, code compliance pathways, and channel economics. Builders, architects, and replacement contractors navigate these categories to align product selection with project-specific energy mandates, structural requirements, and lifecycle cost models.
Product Type:
Operating style governs ventilation capacity, weather sealing geometry, and compatibility with existing rough openings in renovation work.
- Double-Hung Windows:Vertical sliding sashes within a single frame accommodate traditional residential architecture and contractor familiarity. Demand concentrates in Midwest and Northeast replacement cycles where existing double-hung openings dominate housing stock age profiles.
- Sliding Windows:Horizontal travel paths maximize glass area-to-frame ratios and suit contemporary ranch and mid-century modern aesthetics. Texas and Florida new construction deploys these heavily in starter housing segments where cost-per-linear-foot governs specification.
- Casement Windows:Hinged sashes crank outward to capture cross-breezes and seal compression-tight against weatherstripping.
- Awning Windows:Top-hinged operation permits ventilation during precipitation events, common in Pacific Northwest residential retrofits.
Double-hung windows command the established base. The steepest expansion runs through sliding configurations in Sun Belt production housing.
Material:
Frame substrate selection trades thermal conductivity, dimensional stability, and first cost against regional climate stressors and code adoption timelines.
- Fiberglass:Pultruded profiles deliver coefficient of thermal expansion matching glass units, eliminating seal stress in extreme temperature swings. Arizona and Nevada builders specify these for elevated-altitude projects where diurnal temperature differentials exceed 40°F.
- Vinyl:Extruded PVC compounds dominate volume production through cost efficiency and corrosion immunity in coastal salt-air environments. Florida and Gulf Coast replacement channels absorb the majority of domestic vinyl sash production.
- Wood:Solid and composite lumber frames serve historic preservation mandates and premium architect-specified residential segments.
- Aluminum:Thermally-broken extrusions retain specification in commercial mid-rise construction where structural span requirements exceed polymer capabilities.
Vinyl frames anchor volume production across new construction tiers. Fiberglass posts the fastest share gains in high-performance residential and commercial segments.
Installation Type:
Project origin—ground-up versus existing envelope—determines measurement tolerance, lead time flexibility, and regulatory trigger points.
- New Construction:Pre-drywall installation permits full-frame integration with continuous air barriers and structural fastening access. Texas and Arizona permit elevations concentrate demand here with production builder volume contracts.
- Replacement:Insert or full-frame methods address failed units and energy upgrade economics in aging housing stock. IRA tax credits are accelerating Midwest and Northeast homeowner decisions in this channel.
- Retrofit:Secondary glazing and frame overlays improve thermal performance without full removal, common in historic district renovations.
- Customized:Non-standard dimensions and specialty glazing accommodate architect-driven commercial and high-end residential projects.
Replacement work commands the revenue base. New construction delivers the steepest order volume expansion in permit-heavy Sun Belt metros.
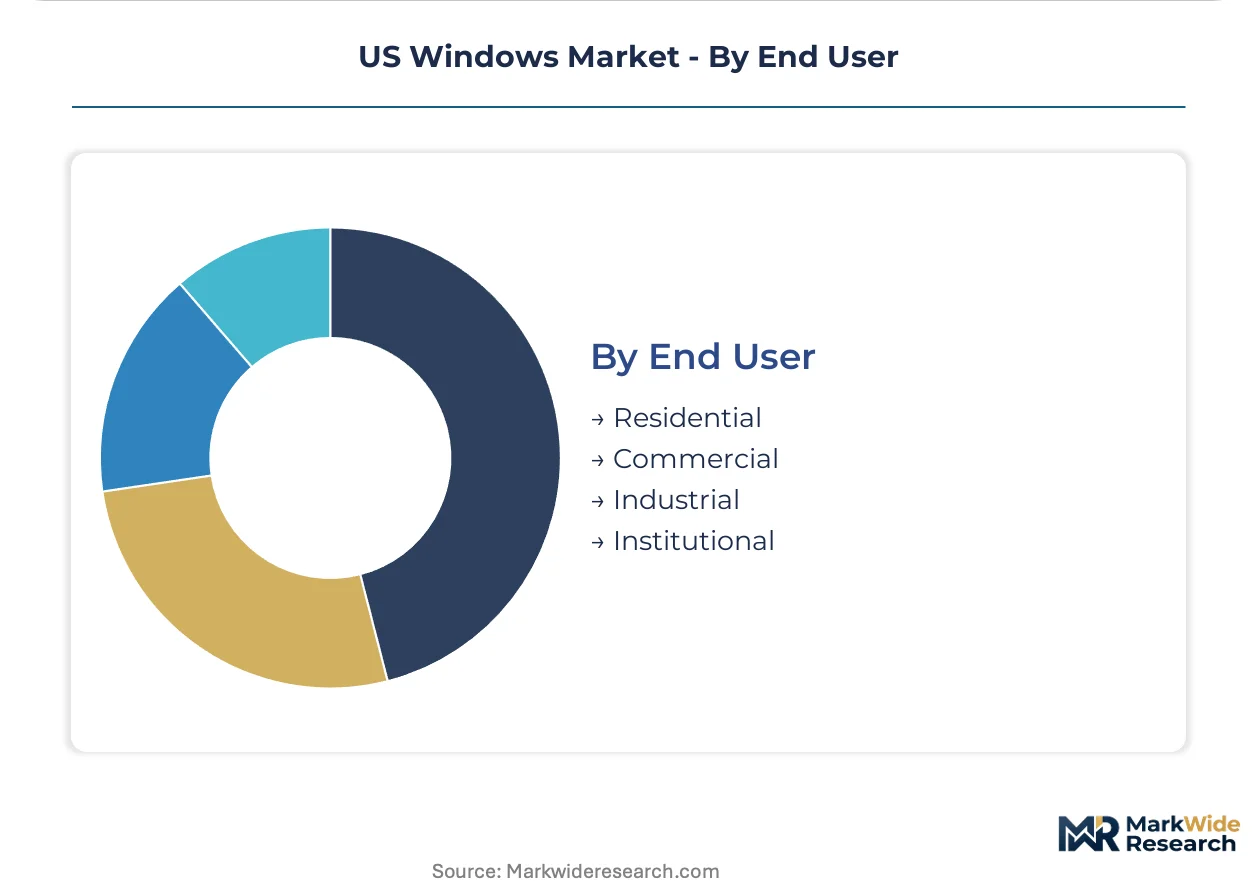
End User:
Building type segmentation separates residential lifecycle economics from commercial capital planning horizons and institutional procurement protocols.
- Residential:Single-family and multifamily builders drive specification through production schedules and homeowner association aesthetic controls. EPA Energy Star certification operates as a de facto market access filter in this segment.
- Commercial:Office, retail, and hospitality developers balance lease-rate premiums against envelope capital costs in pro forma underwriting.
- Industrial:Manufacturing and warehouse facilities prioritize daylighting area and ventilation operability over thermal performance metrics.
- Institutional:School districts and municipal governments navigate extended procurement cycles and prevailing wage requirements.
Residential channels absorb the dominant share of unit volume. Commercial segments deliver the highest average transaction values per opening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Energy Star certification and DOE model energy code adoption anchor demand concentration across the US, with state-level thermal performance mandates driving specification divergence between climate zones and housing market cycles.
Southwest
Texas and Arizona builders are accelerating orders for fiberglass-framed units to address extreme diurnal temperature swings exceeding 40°F at elevation. DOE building code escalation in these states compels reformulation of spacer systems and coating stacks. The Dallas-Fort Worth and Phoenix metros concentrate fenestration production capacity to serve production housing volume contracts.
Southeast
Florida residential builders prioritize vinyl extrusion capacity for corrosion immunity in coastal salt-air environments. Miami-Dade County enforces impact resistance protocols that limit supplier participation through county-specific testing requirements. The Tampa-Orlando corridor anchors replacement channel volume for hurricane-resistant glazing systems.
West
California architects specify vacuum-insulated glazing for historic retrofits where rough opening depth constraints prohibit standard triple-pane thickness. EPA Energy Star Most Efficient designation criteria tighten faster than baseline certification, creating two-tier access structures. The Los Angeles-San Diego corridor drives premium-tier demand for electrochromic integration.
Midwest
Illinois and Ohio replacement contractors favor double-hung configurations compatible with existing rough openings in aging housing stock. IRA residential efficiency rebates accelerate homeowner decisions for high-performance envelope upgrades. The Chicago metro anchors distributor networks serving the Great Lakes construction cycle.
Northeast
New York and Massachusetts multifamily developers navigate extended procurement cycles and prevailing wage requirements for institutional projects. State-level decarbonization timelines outpace federal stringency, forcing product portfolio recertification investments. The Boston-Washington corridor concentrates architect-specified commercial glazing demand.
US Windows Market Competitive Landscape
Backward-integrated wood composite specialists and distributed plant network operators split the market between premium specification authority and volume production efficiency. The vendor base organizes around three strategic archetypes: material-integrated manufacturers controlling substrate consistency, premium-positioned brands sustaining architect relationships, and scale-driven fabricators competing on replacement cycle timing. Dominant competitive moves include captive supply chain expansion for fiberglass pultrusion capacity and utility-administered rebate channel partnerships that bypass traditional retail markups.
Within the material-integrated tier, Andersen Corporation exemplifies backward integration into wood composite sourcing to govern consistency across production lines. Pella Corporation occupies a premium-positioned anchor role through proprietary glazing system development. JELD-WEN Holding, Inc. represents the scale-driven archetype with distributed manufacturing footprint and contractor channel density. These three fabricators collectively illustrate how strategic archetype selection determines competitive posture across new construction and replacement segments.
| Leading Market Players |
|---|
| Andersen Corporation |
| Pella Corporation |
| Marvin Windows and Doors |
| JELD-WEN Holding, Inc. |
| MI Windows and Doors |
| Milgard Manufacturing, Inc. |
| PGT Innovation, Inc. |
| Cornerstone Building Brands |
| Harvey Building Products |
| Others |
Pricing and Supply Chain Analysis
Float glass manufacturing concentration in Mexico and Canada governs where margin pools accumulate across the US fenestration supply base. Energy-intensive flat glass production faces natural gas price exposure that compresses margin predictability for integrated and non-integrated manufacturers alike, forcing downstream fabricators to absorb volatility or push price adjustments through contractor channels.
Pricing Analysis
Texas-Florida-Arizona permit concentration creates the widest geographic price spreads in residential new construction. Pricing stratifies across premium, standard, and economy tiers where EPA Energy Star certification and Miami-Dade impact resistance protocols operate as tier-separating filters. Cost compression in vinyl-framed starter housing is intensifying because national production builders are consolidating specification authority at corporate level. Replacement contractors in the Midwest and Northeast show the highest price sensitivity, while architect-specified commercial projects in California and the Pacific Northwest demonstrate the least.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for spacer systems and low-emissivity coating equipment. Manufacturing draws from domestic float glass production, Canadian raw glass imports, and Mexican fabricated component assembly. The supply chain rests on natural gas pricing for energy-intensive glass melting, vinyl resin feedstocks from Gulf Coast petrochemical complexes, and pultruded fiberglass profiles from specialized composite manufacturers. Single-source vulnerability concentrates in warm-edge spacer technology licensing. Distribution runs through contractor-direct procurement platforms that are consolidating order aggregation for regional production builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EPA Energy Star certification and Miami-Dade impact protocols create switching costs that lock out unqualified suppliers and protect incumbents with sunk certification investments.
For Market Incumbents: Build certification moats by maintaining parallel testing documentation for Energy Star retail channels and Miami-Dade impact markets with divergent renewal cycles. Expand captive supply of fiberglass pultrusion capacity to serve Sun Belt builders prioritizing lifecycle performance in extreme temperature swings. Defend against contractor-direct procurement platforms by deepening utility-administered rebate channel partnerships that bypass traditional retail markups.
For New Entrants and Emerging Players: Pursue white-space targets in vacuum-insulated glazing for historic retrofit applications where rough opening depth constraints prohibit standard triple-pane thickness. Target the Pacific Northwest and California architect-specified premium segments where electrochromic integration commands specification authority. Enter through smart glass convergence partnerships that open commercial mid-rise segments without competing on replacement cycle timing.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fiberglass pultrusion capacity and warm-edge spacer technology migration. Long-term viability favors fabricators with backward-integrated wood composite sourcing or distributed plant networks serving permit-heavy Sun Belt metros. Acquire targets with Miami-Dade impact certification and EPA Energy Star Most Efficient designation already in place. Monitor IRA residential efficiency rebate uptake rates as the inflection indicator for replacement channel price-point elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiberglass Pultrusion | Captures dimensional stability premiums from Arizona and Nevada elevated-altitude builders. |
| EPA Energy Star Most Efficient Certification | Unlocks utility-administered rebate channels and retail tier separation in California markets. |
| Miami-Dade Impact Resistance Recertification | Maintains supplier participation in Florida hurricane-prone jurisdictions with county-specific protocols. |
| Warm-Edge Spacer Assembly Line Retooling | Addresses DOE thermal transmittance escalation through automated migration from aluminum box spacers. |
| Contractor-Direct Procurement Platform Partnership | Bypasses traditional distributor margins for national production builder volume contracts in Texas and Arizona. |
Research Methodology
A standing panel of fenestration plant managers, regional contractor procurement leads, EPA certification specialists, and utility rebate program administrators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from DOE building code adoption databases, EPA Energy Star certified products listings, and state housing permit records. Bottom-up assembly of county-level permit data and top-down reconciliation against national production capacity estimates enabled triangulation of market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon, with high-low paths reflecting divergent state-level code adoption timelines. Segmentation dimensions modeled include operating style, frame material, installation type, and end-user category, with regional climate zone stringency as an additional cross-cutting dimension. CAGRs were derived from trend extrapolation of permit volumes and replacement cycle timing, incorporating float glass input cost trajectories and IRA rebate program uptake assumptions as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, mortgage rate levels, or single-family housing starts would shift the trajectory. Forecasts reflect assumptions about state-level DOE code adoption pace and EPA certification criteria evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Europe Faucet Market
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
PU Waterstops Market
Building & Construction Materials
North America Roofing Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
Facade Materials Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
US Ceiling Tiles Market