
 Cladding Market | 2026-2036
Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
Cladding Market Intelligence
Building Information Modeling (BIM) integration services are hardening the link between digital design and physical installation. Kingspan Group specializes in high-performance insulated panels for commercial and industrial structures. Compagnie de Saint-Gobain SA leverages its extensive material science portfolio across multiple cladding types. Arconic Corporation competes with its advanced aluminum composite materials, particularly for architectural facades.
Cladding refers to the non-structural outer layer applied to a building's exterior to provide weather resistance, thermal insulation, and aesthetic finish. These systems often function as a rainscreen, managing water infiltration and featuring materials like composite panels with a polyethylene or mineral-filled core. Metal cladding, particularly aluminum composite panels, dominates large-scale commercial end-user projects. In the residential segment, fiber cement is seeing increased use due to its durability and fire-resistant properties.
Regulatory mandates significantly influence material selection. The EU’s Construction Products Regulation and CE marking enforce strict performance declarations, while standards from the US National Fire Protection Association dictate fire resistance. These frameworks compel manufacturers to validate product safety and energy performance. Stakeholder decisions will increasingly focus on a supplier's capacity to provide full lifecycle data and certified sustainable materials.
Market Dynamics
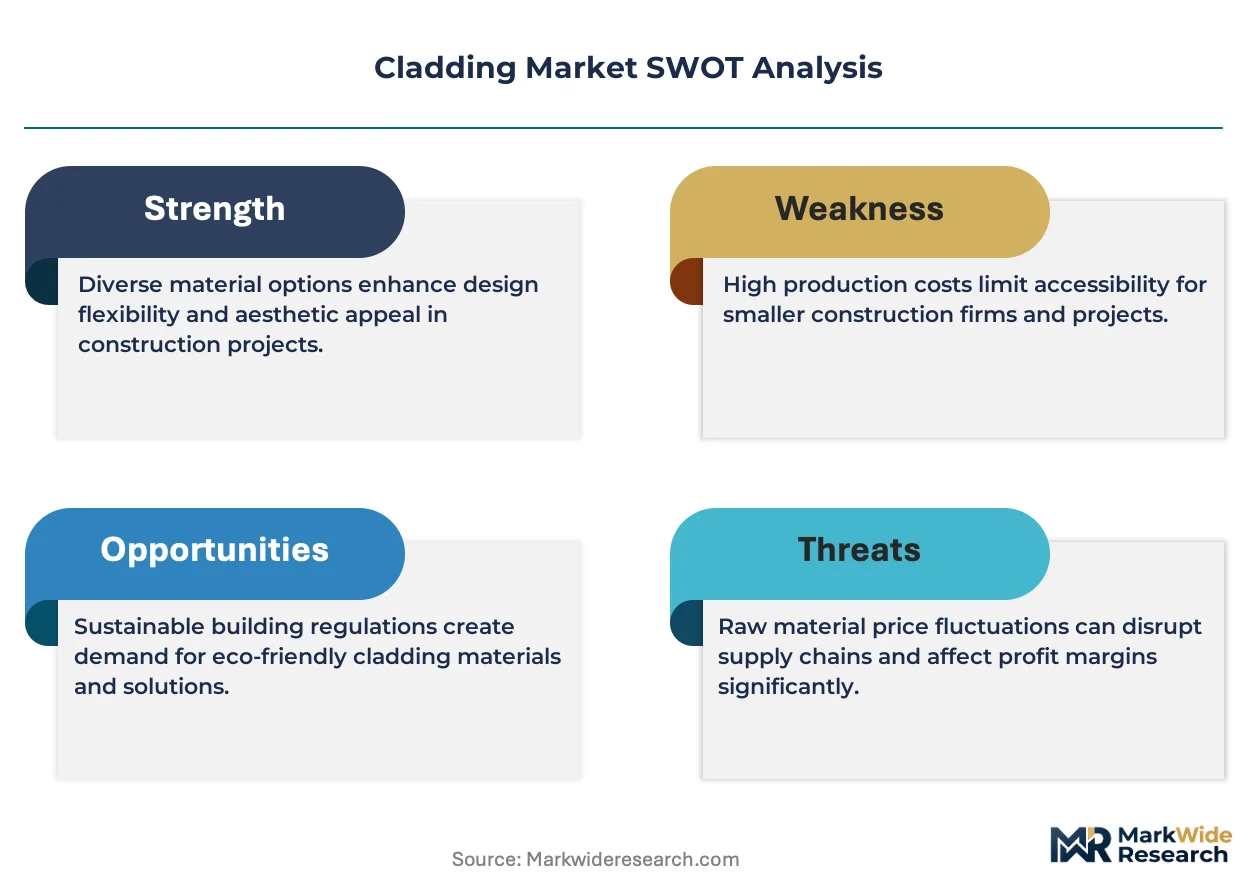
Stricter building codes, particularly fire safety standards following high-profile incidents, are the central force shaping the cladding market. This regulatory tightening compels a rapid material substitution away from combustible composites toward certified non-combustible alternatives, altering the entire value chain.
Growth Catalysts
- Energy Efficiency Mandates:The EU Green Deal accelerates adoption of insulated panels and advanced rainscreen systems to meet stringent building energy performance targets.
- Urbanization in Emerging Economies:High-density construction in cities across India and Brazil creates volume demand for materials like fiber cement and aluminum composite panels.
- Digital Fabrication:Building Information Modeling (BIM) enables complex facade designs, increasing specification for customized cladding systems on high-value commercial projects.
Market Restraints
- Input Cost Volatility:Price fluctuations for raw materials like aluminum and polyethylene create margin pressure and unpredictable bidding for cladding system contractors.
- Competition from EIFS:Exterior Insulation and Finish Systems (EIFS) offer a lower-cost alternative, competing with fiber cement in residential and light commercial applications.
- Fragmented Fire Codes:Divergent standards, like US NFPA versus European CE marking, complicate product certification and add costs for manufacturers operating globally.
Strategic Opportunities
- Building Retrofit Market:Energy upgrade mandates for aging buildings in Europe create a large market for over-cladding with insulated metal panels.
- Sustainable Material Development:Cladding from recycled composites or bio-based resins meets ESG-driven demand from architects for certified sustainable building products.
- Modular Construction Integration:Supplying pre-clad panels for modular building projects streamlines on-site labor, creating a high-efficiency channel for manufacturers.
Industry Challenges
- Skilled Labor Shortages:Shortages of trained installers for complex rainscreen and unitized facade systems cause project delays and raise labor costs.
- Complex Certification Pathways:Navigating lengthy and expensive fire and weather performance testing for certifications like CE marking is a major hurdle for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cladding Market |
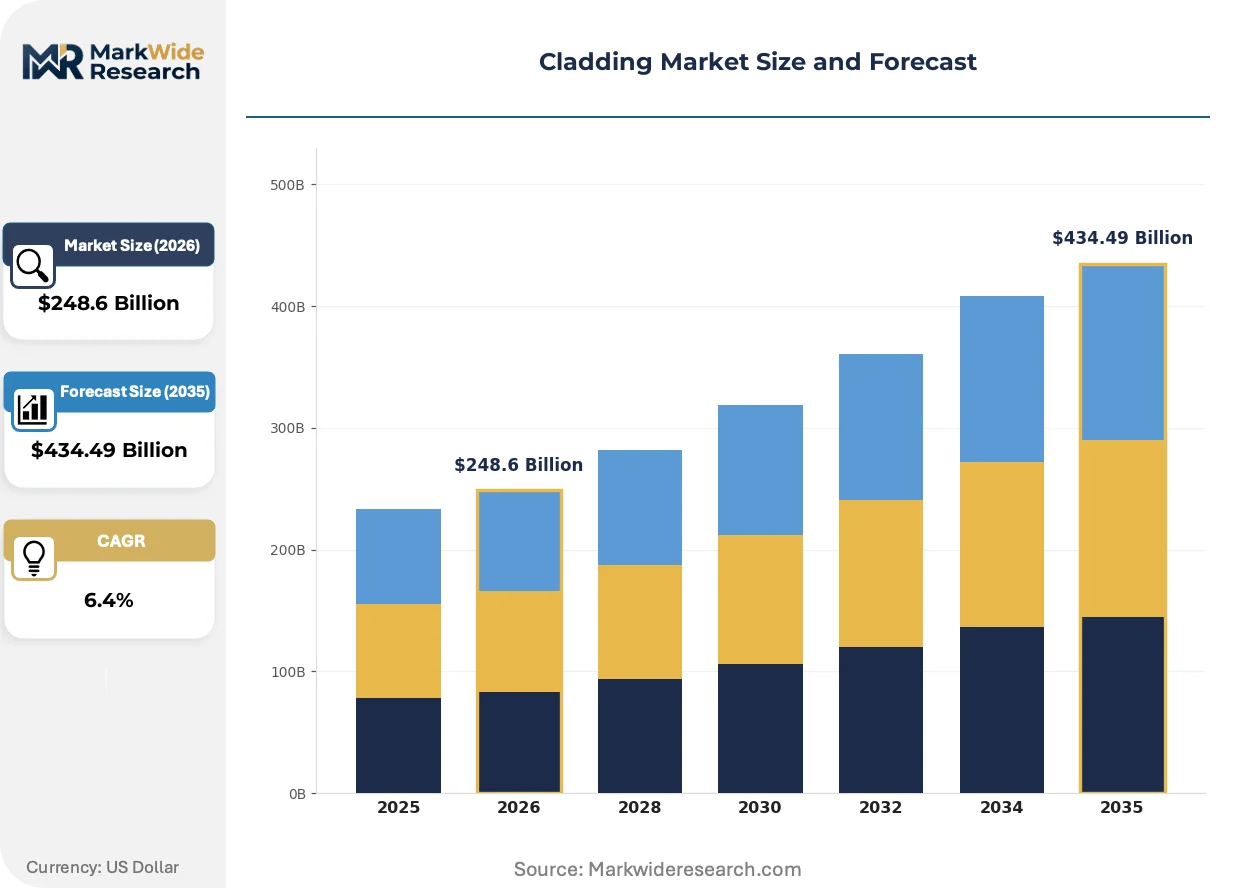
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $434.49 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Metal, Wood, Vinyl, Fiber Cement Installation Type: Mechanical Fixed, Adhesive Bonded, Clip System, Ventilated End User: Residential, Commercial, Industrial, Institutional Application: Facade, Roof, Interior, Sound Barrier |
| Companies Covered | Kingspan Group, Compagnie de Saint-Gobain SA, Arconic Corporation, Etex Group, Tata Steel Ltd, James Hardie Industries, Centria, SFS Group, Trespa International B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cladding Market Strategic Shifts & Innovations
A dual focus on material science and data-driven lifecycle management defines performance in the cladding market. Competition now centers on certified safety, environmental transparency, and integration with digital construction workflows.
High-performance insulated panels provide a single-component solution for structure, insulation, and weather barrier. Commercial and industrial developers are rapidly adopting these systems to accelerate construction schedules and improve building energy efficiency. This prefabricated panel technology is converging with smart sensor integration, enabling real-time monitoring of thermal performance and moisture levels within the building envelope.
India's Bureau of Indian Standards (BIS) is tightening its codes for building materials, including fire performance standards for facades on high-rise structures. This move compels manufacturers to invest in local testing and certification, often mirroring stricter international protocols. The commercial real estate sector in metropolitan areas like Mumbai and Delhi is most affected, driving a shift toward non-combustible materials.
Asset owners now demand full lifecycle data for building materials, including Environmental Product Declarations (EPDs). This emphasis on transparency disrupts sales based on aesthetics and initial cost, favoring suppliers with verifiable sustainability metrics. The trend is most prominent in large corporate projects in Europe seeking high BREEAM or DGNB certification ratings.
Cladding Market Segmentation
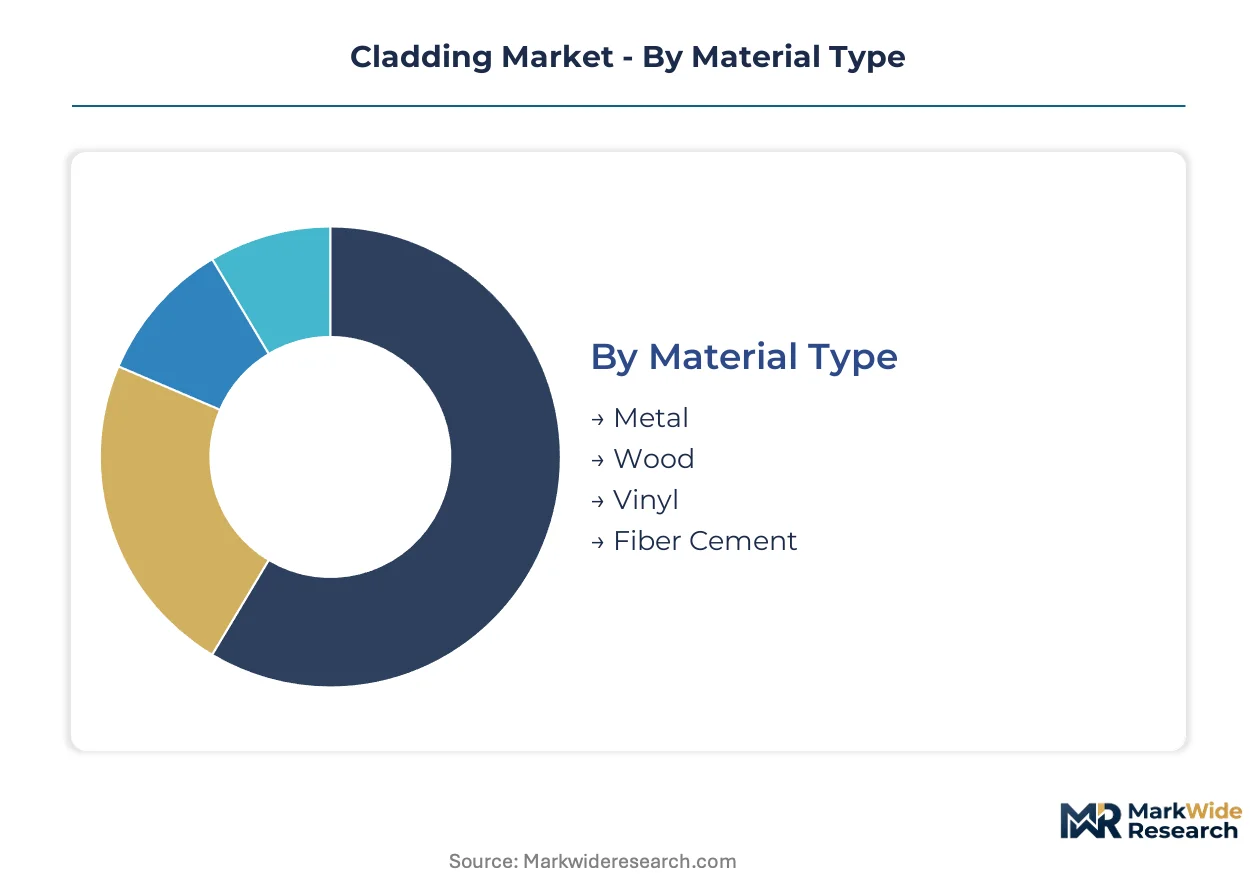
The cladding market's segmentation reveals diverse product offerings and application methods. Understanding these distinctions helps stakeholders identify specific demand patterns and regulatory influences across different building types. Material innovation and installation efficiency remain central to market evolution.
Material Type:
The material type segmentation spans a spectrum from highly customizable architectural finishes to standardized, high-volume solutions.
- Metal:This category includes aluminum composite panels and steel, valued for their durability, low maintenance, and design flexibility. Large-scale commercial projects in urban centers like Mumbai extensively specify metal cladding for its aesthetic appeal and structural performance.
- Fiber Cement:Composed of cement, cellulose fibers, and sand, fiber cement offers fire resistance and weather durability, often mimicking natural wood or stone. Residential construction, particularly in regions with stringent fire safety codes, increasingly adopts fiber cement for its long lifespan.
- Wood:Natural timber and engineered wood products provide aesthetic warmth and sustainability credentials, often used in bespoke architectural designs.
- Vinyl:Lightweight and cost-effective, vinyl cladding offers a low-maintenance exterior solution for budget-sensitive residential applications.
Leading the category by volume: Metal. Growing fastest: Fiber Cement.
Installation Type:
Cost tiering significantly influences the choice of cladding installation methods, balancing initial outlay against long-term performance.
- Mechanical Fixed:This method involves physically attaching cladding panels to the building structure using brackets, screws, or rails, ensuring robust structural integrity. High-rise commercial buildings in regions like Europe frequently utilize mechanical fixed systems for their proven reliability and compliance with wind load standards.
- Ventilated:Ventilated cladding systems create an air gap between the insulation and the exterior panel, improving thermal performance and moisture management. Energy efficiency mandates under the EU Green Deal accelerate the adoption of ventilated systems for both new builds and retrofits.
- Adhesive Bonded:Panels are directly adhered to the substrate, offering a smooth finish and reduced thermal bridging in specific applications.
- Clip System:Proprietary clip systems provide efficient and concealed panel attachment, often used for modular and prefabricated cladding assemblies.
Volume is concentrated in Mechanical Fixed. Ventilated shows the steepest expansion trajectory.
End User:
Application complexity varies significantly across end-user segments, dictating material specifications and installation requirements.
- Commercial:This segment encompasses offices, retail spaces, and hospitality buildings, demanding high-performance, aesthetically sophisticated, and often custom-designed cladding solutions. High-growth urban centers in countries such as India drive substantial demand for commercial cladding, focusing on energy efficiency and fire safety.
- Residential:Single-family homes and multi-unit dwellings form this segment, prioritizing cost-effectiveness, durability, and ease of installation. The residential segment increasingly adopts materials like fiber cement due to its fire-resistant properties and low maintenance requirements.
- Industrial:Factories, warehouses, and logistics centers require robust, functional cladding systems focused on insulation, security, and rapid construction.
- Institutional:Schools, hospitals, and government buildings specify cladding solutions that meet strict regulatory standards for safety, durability, and environmental performance.
Demand for Commercial drives the largest share. Residential exhibits the most dynamic expansion.
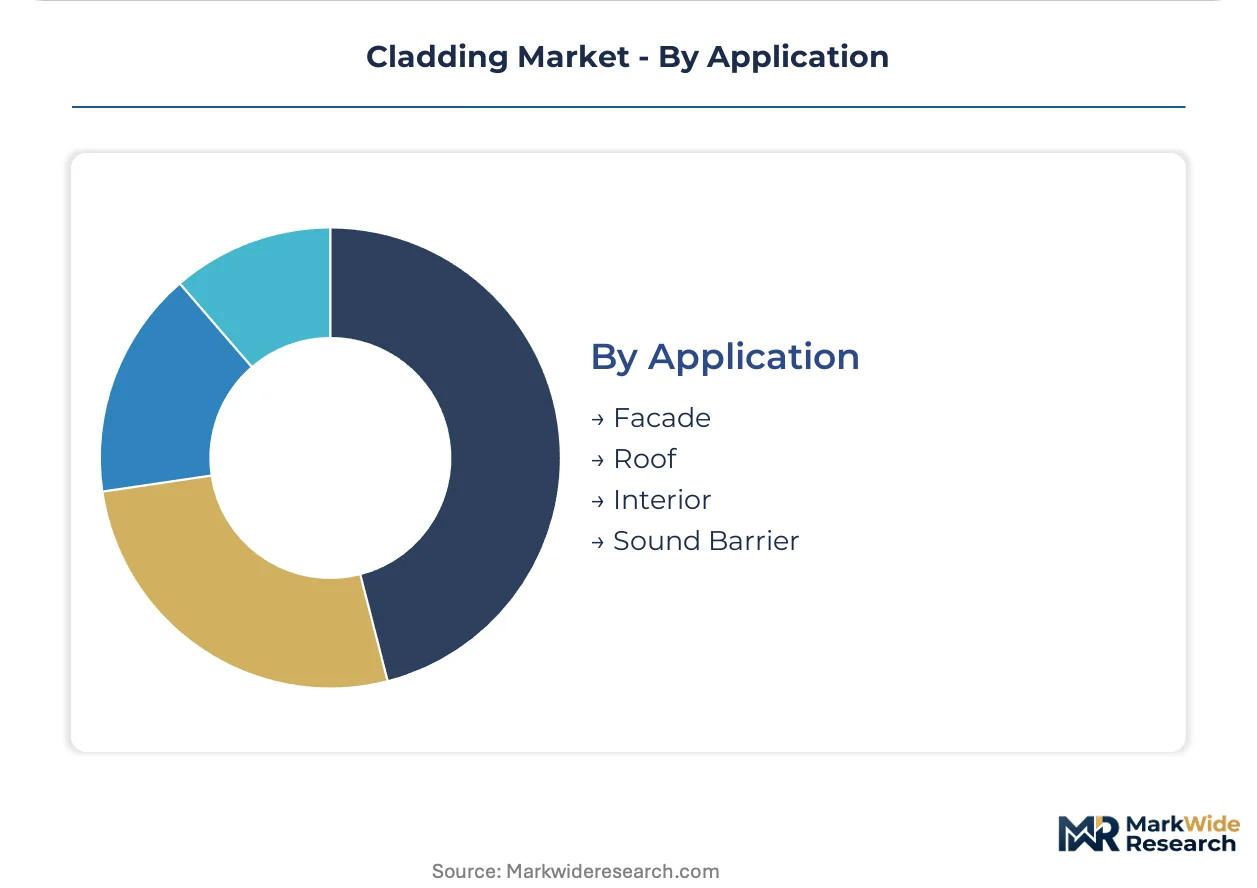
Application:
Supply concentration for cladding applications reflects specialized manufacturing capabilities and distinct performance requirements.
- Facade:The exterior face of a building, facades integrate aesthetic design with critical weather protection, thermal insulation, and fire safety functions. Architectural firms in European markets frequently specify advanced facade systems to achieve stringent BREEAM or DGNB certification ratings.
- Roof:Cladding on roofs provides primary weatherproofing, thermal insulation, and often integrates solar panels or green roof systems. Insulated metal panels are widely used for roofing industrial and commercial structures, enhancing energy performance and construction speed.
- Interior:Interior cladding provides aesthetic finishes, acoustic control, and surface protection within building spaces.
- Sound Barrier:Specialized cladding systems absorb or reflect noise, deployed around infrastructure projects or noisy industrial facilities.
Facade accounts for the largest share. Roof is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's rapid commercial real estate development drives significant demand for advanced cladding systems. Urbanization trends across India, coupled with rising energy efficiency mandates, shape material selection. This growth pattern is mirrored in other high-density global urban centers, influencing regional market dynamics.
India
India's burgeoning commercial real estate sector fuels demand for high-performance facades. The Bureau of Indian Standards (BIS) is tightening fire safety codes for high-rise structures, compelling material innovation. Metropolitan areas like Mumbai and Delhi are seeing a concentrated shift towards non-combustible cladding solutions for new developments.
Brazil
Brazil's urban expansion generates substantial volume demand for durable and cost-effective cladding. Government initiatives promoting sustainable construction influence material choices for new developments. Major cities such as São Paulo are adopting fiber cement and aluminum composite panels for large-scale commercial and residential projects.
Germany
Germany's stringent energy efficiency mandates accelerate the adoption of insulated panels and advanced rainscreen systems. The EU Green Deal heavily influences building envelope specifications for both new construction and retrofits. Urban centers like Berlin are a focus for energy upgrade mandates on aging buildings, creating demand for over-cladding solutions.
United States
Demand for resilient and fire-resistant cladding is driven by evolving building codes across the United States. Standards from the US National Fire Protection Association (NFPA) dictate material performance, particularly for commercial structures. High-growth regions, including Texas, increasingly specify metal cladding for its durability and aesthetic versatility in large projects.
Cladding Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in the cladding sector. The market exhibits a tiered structure, with large material manufacturers alongside specialized facade system integrators and fabricators. Strategic archetypes include vertically integrated solution providers offering complete building envelope systems and niche component suppliers focusing on specific material innovations. Capacity expansion to meet regional demand and strategic partnerships for project delivery remain dominant competitive moves across the industry.
Within the high-performance insulated panel archetype, Kingspan Group anchors its position through specialized offerings for commercial and industrial structures, emphasizing energy efficiency and rapid installation. Compagnie de Saint-Gobain SA exemplifies a diversified materials science approach, leveraging its broad portfolio across multiple cladding types for various end-user segments globally. Arconic Corporation occupies a position as a specialist in advanced aluminum composite materials, particularly for architectural facades requiring bespoke design, superior performance, and aesthetic flexibility in high-value commercial projects.
| Leading Market Players |
|---|
| Kingspan Group |
| Compagnie de Saint-Gobain SA |
| Arconic Corporation |
| Etex Group |
| Tata Steel Ltd |
| James Hardie Industries |
| Centria |
| SFS Group |
| Trespa International B.V. |
| Others |
Cost & Logistics Intelligence
Stricter fire safety standards, influenced by frameworks like the EU Green Deal and India's BIS, compel manufacturers to invest in certified non-combustible materials. This regulatory pressure elevates material costs and reinforces the value proposition of compliant cladding systems.
Pricing Analysis
Cost-down pressure on cladding contractors accelerates due to significant input cost volatility for materials like aluminum and polyethylene. Project-based contract pricing dominates large commercial installations, often incorporating clauses for material cost adjustments. Price differentiation stems from certification levels, such as CE marking or BIS standards, and the degree of customization for architectural facades. The residential segment exhibits the highest price sensitivity, while commercial developers prioritize certified performance and aesthetic value over initial cost.
Supply Chain Analysis
Single-source vulnerability sits with key raw material suppliers, particularly for specialized aluminum and polymer components. Geographic supply concentration for these critical inputs often centers on Asian manufacturing hubs, while advanced insulated panels originate from European specialists. The cladding market draws from raw materials like aluminum, polyethylene, cement, and cellulose fibers. Logistics chokepoints represent a structural risk for global project timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cladding market operates under significant supply constraints, with skilled labor shortages for complex rainscreen systems creating a capacity bottleneck. This scarcity of trained installers contributes to project delays and elevates overall installation costs.
For Market Incumbents: Cement market leadership by deepening vertical integration into specialized non-combustible material production. Invest proactively in digital fabrication technologies like BIM to streamline complex facade designs and mitigate skilled labor shortages. This defends against margin pressure from input cost volatility and strengthens compliance with evolving fire safety standards.
For New Entrants and Emerging Players: Begin with niche segments characterized by high growth and specific regulatory drivers, such as fiber cement in residential construction. Target the residential segment in rapidly urbanizing economies like India and Brazil, leveraging demand for durable and fire-resistant solutions. A go-to-market angle focused on certified sustainable materials can capture ESG-driven demand.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized manufacturers of certified non-combustible materials, given the intensifying regulatory landscape for fire safety and energy efficiency. This ensures robust long-term viability, driven by global urbanization. Target acquisition archetypes include firms with strong intellectual property in sustainable materials or advanced digital fabrication. Accelerated adoption rates of insulated panels in European retrofit markets signal strong underlying demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Non-Combustible Materials | Addresses increasing regulatory demand for fire-resistant facades in high-rise structures across India. |
| Digital Fabrication Integration | Streamlines complex facade designs through BIM, reducing project delays caused by skilled labor shortages. |
| Sustainable Material Development | Captures ESG-driven demand from architects for certified sustainable building products in European markets. |
| Modular Construction Partnerships | Creates high-efficiency channels for manufacturers by supplying pre-clad panels for modular building projects. |
| Certification Pathway Investment | Navigating lengthy fire and weather performance testing for CE marking reduces market entry hurdles for new products. |
Research Approach
Document review covered extensive industry reports, regulatory filings, and company disclosures, complemented by interviews with architects, project managers, material scientists, and procurement leads. Primary insights were validated against secondary data from BIS standards, EU Green Deal documents, and NFPA standards. This approach combined bottom-up data aggregation with top-down market sizing for comprehensive validation.
Volume and value projections were generated through quantitative models, analyzing market dynamics across the analysis window. Segmentation dimensions modeled included material type, installation type, end user, application, and regional regulatory clusters. Compound Annual Growth Rates were derived using regression analysis on historical data and projected trends. Key forecast inputs included construction spending forecasts and regulatory compliance timelines for fire safety.
Raw material price volatility, evolving building codes, and skilled labor availability are the dominant revision risks for market forecasts. Forecasts reflect assumptions regarding economic stability and technological progression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
North America Concrete Admixtures Market
Building Materials
North America Architectural Coatings Market
Building Materials
China Cement Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
North America Construction Aggregates Market
Building Materials
India Cement Market
Building Materials
Natural Stone Slab Market
Building Materials
Dutch Brick Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Cellular Concrete Market
Building Materials
Fire Resistant Mortar Market
Building Materials
France Architectural Coatings Market
Building Materials
Concrete and Cement Market
Building Materials
Construction Coatings Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Masonry Cement Market