
 North America Luxury Vinyl Tile (LVT) Market | 2026-2036
North America Luxury Vinyl Tile (LVT) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Luxury Vinyl Tile (LVT) Market Analytics
The gap between rigid core and flexible vinyl manufacturing is narrowing as extrusion lines adapt to hybrid formulations with mineral composite loading. Mohawk Industries leverages captive resin compounding to control input costs across its Calhoun, Georgia operations. Shaw Industries anchors its position through extensive distribution partnerships with national home improvement retailers. Mannington Mills differentiates via specialized print-layer technology that replicates natural stone and hardwood aesthetics.
Luxury Vinyl Tile comprises multi-layer synthetic flooring products built around a PVC or calcium carbonate composite core, topped with a photographic print film and wear-layer typically measured in mils thickness for durability rating. The primary commercial purpose is delivering water-resistant, dimensionally stable surfacing for high-traffic interior environments at lower installed cost than natural materials. Rigid Core SPC products dominate volume in commercial healthcare and education applications where dimensional stability under rolling loads matters most. Flexible vinyl maintains share in residential retrofit where subfloor irregularity forgiveness reduces preparation labor. Click-lock installation methods are gaining specification share among contractor end users seeking faster project completion with reduced adhesive dependency.
US EPA regulations on formaldehyde emissions from composite wood products extend compliance expectations to LVT adjacent categories, while California Air Resources Board (CARB) Phase 2 standards and FloorScore certification programs shape VOC thresholds for indoor air quality. The US Consumer Product Safety Commission maintains oversight on phthalate content in vinyl products targeting residential environments with child occupancy. Stakeholders must monitor evolving state-level extended producer responsibility legislation that could impose end-of-life collection obligations on manufacturers serving the Northeast and West Coast corridors.
Market Dynamics
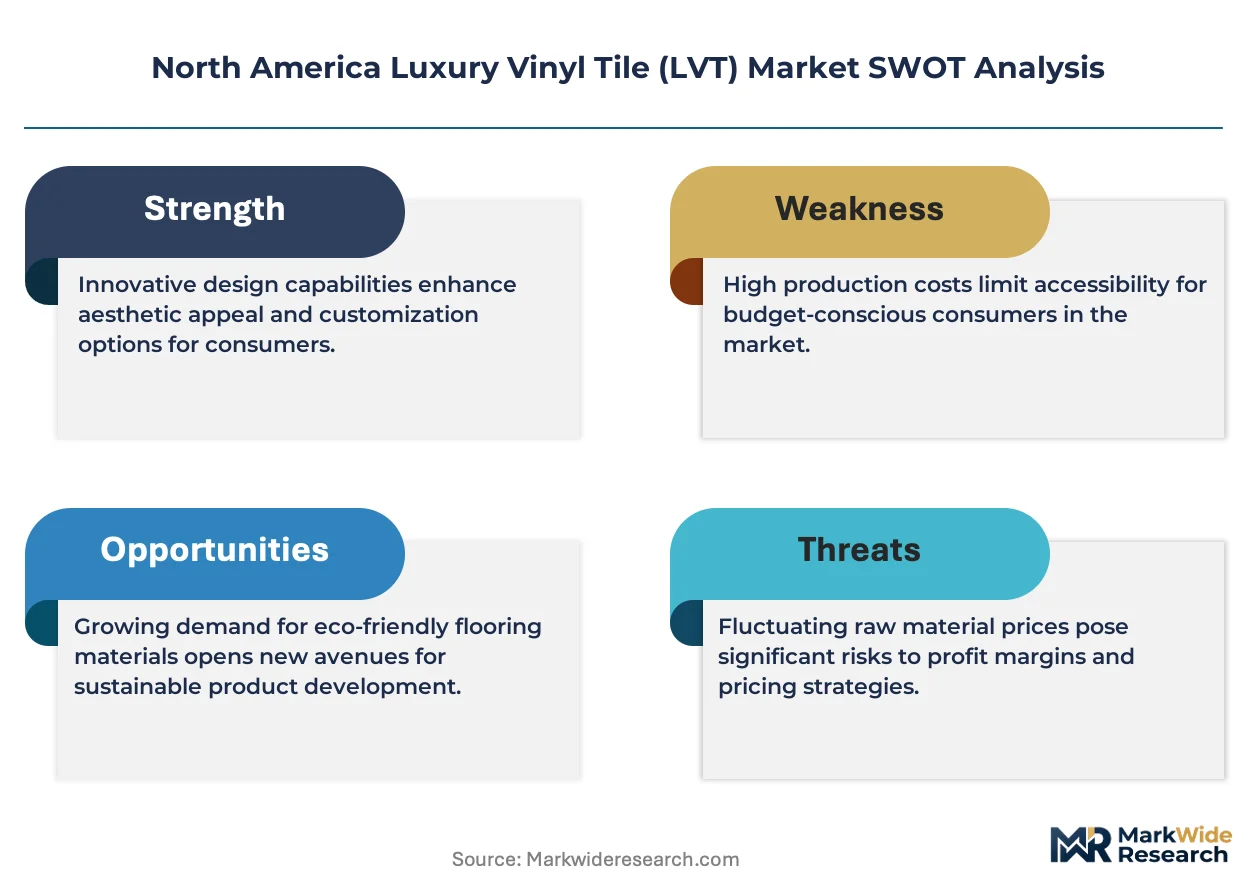
Extrusion technology convergence between rigid and flexible vinyl platforms is compressing manufacturing cost differentials across the North American LVT supply base, forcing producers to compete on installation speed and spec-grade certification rather than core material format alone.
Growth Catalysts
- CARB Phase 2 and FloorScore protocols:California's VOC emission standards and third-party certification programs create specification pull for compliant products in healthcare and education construction across the United States and Canada.
- Waterproof flooring retrofit demand:Residential renovation activity in moisture-prone Gulf Coast and Pacific Northwest submarkets drives replacement volume for failed hardwood and laminate installations.
- Click-lock mechanical fastening:Floating installation systems reduce adhesive costs and cure-time delays, accelerating contractor adoption in multi-family housing turnover projects.
Market Restraints
- Resin supply concentration:PVC and plasticizer input dependence on Gulf Coast petrochemical corridors exposes producers to hurricane disruption and force majeure pricing volatility.
- Phthalate content restrictions:US Consumer Product Safety Commission oversight on child-occupancy environments limits formulation flexibility for residential-targeted product lines.
- Engineered wood substitution:Waterproof laminate and hybrid rigid core alternatives capture specification share in mid-market residential segments price-sensitive to total installed cost.
Strategic Opportunities
- Extended producer responsibility legislation:Pending state-level end-of-life collection mandates in the Northeast and West Coast corridors create first-mover advantage for closed-loop recycling infrastructure investment.
- Healthcare acute care renovation:Infection control protocols in Canadian and US hospital systems favor seamless sheet vinyl and welded LVT installations with enhanced chemical resistance ratings.
- Digital print-layer convergence:High-definition scanning and ceramic-reactive ink systems enable rapid aesthetic refresh cycles without tooling changeover costs.
Industry Challenges
- FloorScore and GREENGUARD certification timelines:Third-party indoor air quality testing protocols extend product launch cycles by four to six months, compressing margin on trend-responsive collections.
- Subfloor preparation skill scarcity:Self-leveling compound application and moisture testing expertise gaps in contractor networks increase callback rates and installation warranty exposure.
Report Scope
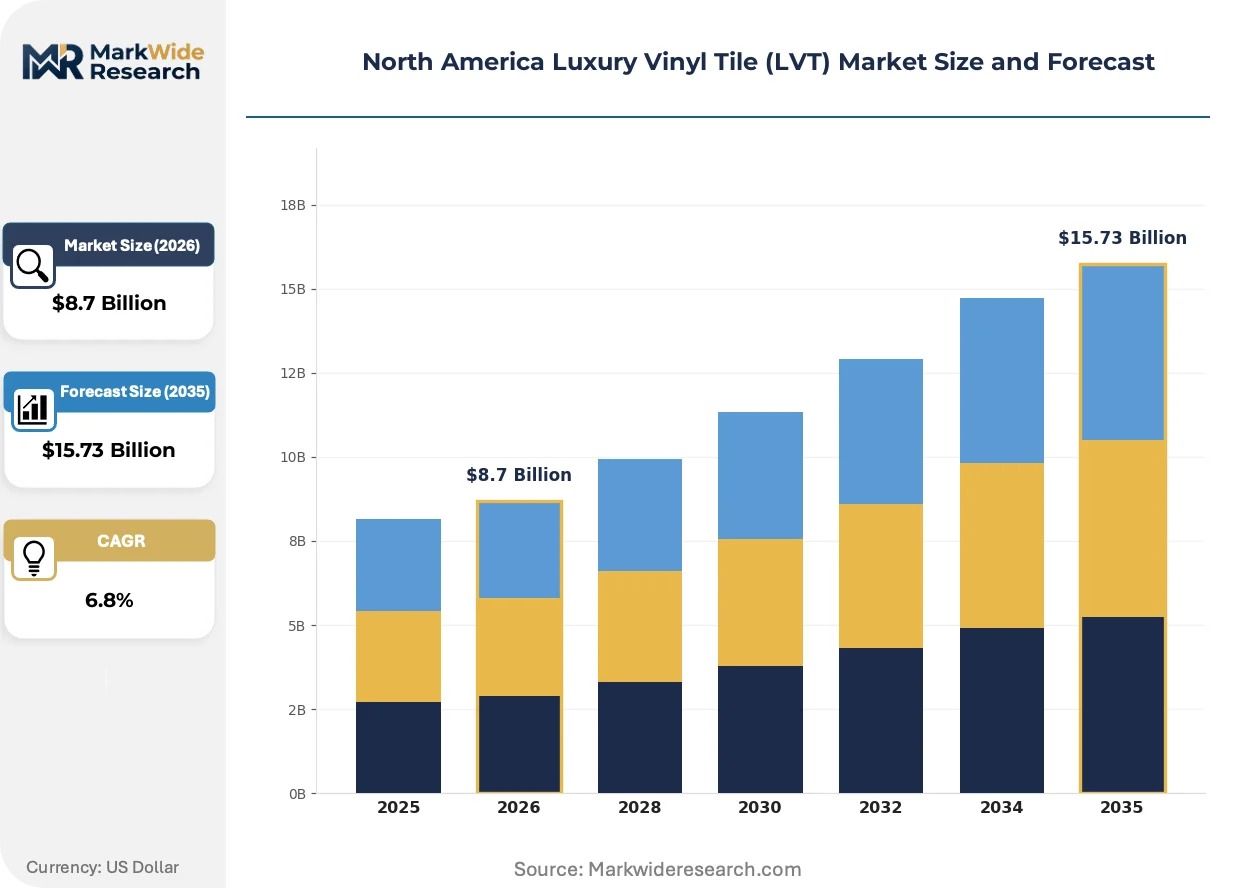
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Luxury Vinyl Tile (LVT) Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Core, Flexible Vinyl, WPC, SPC Application: Residential, Commercial, Healthcare, Education Installation Method: Glue-down, Click-lock, Loose lay, Nail-down End User: Contractors, Distributors, Retailers, Homeowners |
| Companies Covered | Mohawk Industries, Shaw Industries, Armstrong Flooring, Mannington Mills, Interface, Tarkett, LG Hausys, AHF Products, Congoleum, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Luxury Vinyl Tile (LVT) Market Evolving Landscape
Digital manufacturing workflows and regulatory compliance automation are reconfiguring how North American LVT producers manage product lifecycles from formulation through end-of-life recovery obligations.
Photorealistic print-layer technology is virtualizing natural material aesthetics at resolution thresholds indistinguishable from quarried stone or sawn hardwood. Hospitality and multi-family developers specify these surfaces for lobby and corridor applications where maintenance cost reduction outweighs authentic material premium. The technology is virtualizing traditional specifier relationships with stone and tile distributors by collapsing sample-to-order lead times from weeks to days.
California's Title 24 building energy standards now extend to flooring thermal mass contributions in commercial envelope calculations. Manufacturers must reformulate core densities and underlayment specifications to maintain compliance eligibility in the state's public procurement channels. Healthcare and education verticals in California, Oregon, and Washington face the tightest compliance windows as jurisdictions adopt CARB-aligned amendments.
Specification influence is migrating from distributor sales representatives to direct digital platforms where architects and facilities managers compare certified product databases. National home improvement retailers and commercial flooring dealers are consolidating inventory positions around top-performing SKUs with documented installation labor savings. This channel compression is most visible in the US Southeast, where large-format commercial projects demand rapid sample turnaround and just-in-time delivery coordination.
North America Luxury Vinyl Tile (LVT) Market Segmentation
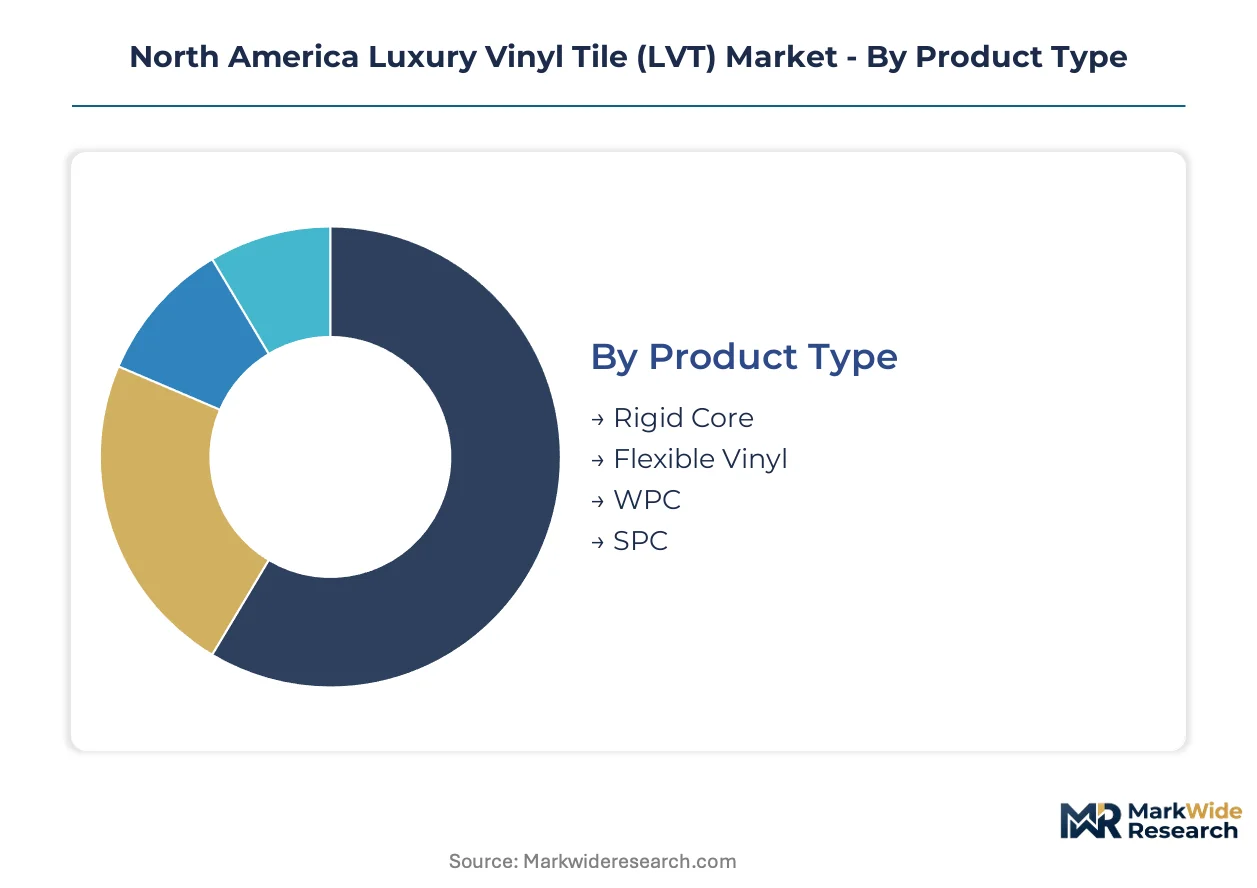
LVT purchasing cycles vary dramatically across product formats and end-use contexts. Rigid core specifications in commercial healthcare refresh every 12-15 years while residential flexible vinyl turns over in 7-10 year cycles driven by moisture failure and aesthetic fatigue.
Product Type:
Cycle times compress fastest for thin-gauge flexible products and extend longest for mineral-loaded rigid platforms where subfloor investment justifies extended service life.
- Rigid Core:Calcium carbonate composite cores above 4mm thickness deliver dimensional stability under rolling loads in acute care corridors and education facilities. US Southeast manufacturing clusters near resin suppliers shorten lead times for large-format commercial projects requiring rapid specification turnaround.
- SPC:Stone-polymer composite formulations dominate specification in multi-tenant office and retail environments where point-load resistance and click-lock speed reduce total installed cost. CARB Phase 2 compliance requirements in California public procurement channels favor SPC with documented FloorScore certification over uncertified alternatives.
- WPC:Wood-plastic composite cores with foamed polymer layers absorb subfloor irregularity in residential retrofit applications across moisture-prone Gulf Coast submarkets.
- Flexible Vinyl:Traditional PVC constructions with fiberglass reinforcement maintain specification in budget-conscious residential replacement where glue-down installation and pattern variety outweigh rigidity requirements.
SPC anchors the volume base while rigid core gains share at the steepest rate.
Application:
Cost tiers stratify sharply across application contexts, with healthcare and education commanding specification premiums for infection control and durability certifications absent in standard residential procurement.
- Healthcare:Seamless welded installations with enhanced chemical resistance ratings satisfy Joint Commission infection control protocols in US hospital renovation cycles. Canadian provincial health authorities specify these surfaces for acute care expansion projects in Ontario and British Columbia.
- Commercial:Multi-tenant office lobbies and retail corridors drive specification for photorealistic print-layer technology that replicates quarried stone at reduced maintenance burden. Property managers in Texas and Florida favor rapid-install click-lock systems to minimize tenant displacement during turnover.
- Residential:Single-family renovation and new construction across the US Southeast and Pacific Northwest prioritizes waterproof performance in kitchens, baths, and below-grade installations.
- Education:K-12 and university facilities balance durability requirements against constrained capital budgets, with specification gravitating toward mid-gauge rigid products that withstand chair caster traffic without premium healthcare-grade pricing.
Residential commands the widest volume base while healthcare climbs the fastest as acute care renovation backlogs clear post-pandemic.
Installation Method:
Customer type determines installation method selection, with contractors driving mechanical fastening adoption and distributors preserving glue-down volume through specification influence with facilities managers.
- Click-lock:Floating mechanical fastening systems eliminate adhesive cure times and enable same-day occupancy in multi-family housing turnover projects. Contractors in high-wage Northeast and West Coast corridors specify these systems to compress labor hours and reduce callback exposure.
- Glue-down:Full-spread adhesive installation maintains specification in healthcare and commercial environments where seam integrity and sound transmission ratings outweigh speed considerations. Distributor sales representatives in the Southeast anchor volume here through relationships with institutional facilities managers.
- Loose lay:Friction-fit systems with weighted edges or perimeter fastening target temporary installations and rental property refresh where minimal subfloor preparation reduces total project cost.
- Nail-down:Staple or nail fastening persists in limited residential applications where plywood subfloors and traditional carpenter trade practices dominate local contractor networks.
Glue-down anchors the volume base while click-lock expands most quickly as labor scarcity drives contractor preference for speed.
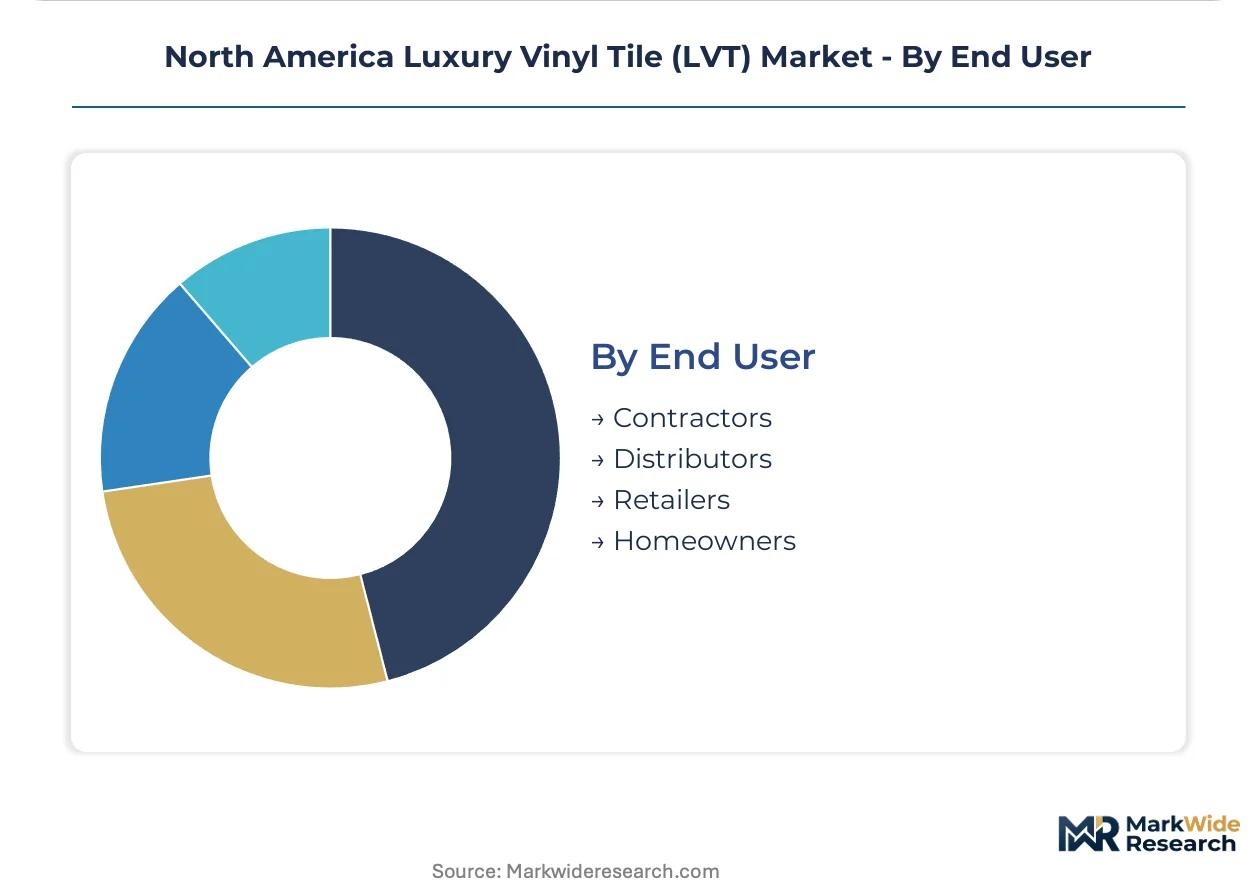
End User:
Supply concentration aligns with end-user channel power, with national home improvement retailers consolidating inventory around top-performing SKUs and contractors fragmenting demand across regional distributors.
- Contractors:Multi-family and commercial installation crews drive specification for rapid-install systems with documented labor savings. Their influence concentrates in Sun Belt metropolitan areas where construction velocity outpaces distributor technical support capacity.
- Distributors:Commercial flooring dealers maintain specification relationships with architects and facilities managers, particularly in healthcare and education verticals where certified product databases and sample turnaround speed determine selection.
- Retailers:National home improvement chains and specialty flooring stores capture residential replacement demand through in-stock inventory and consumer financing programs.
- Homeowners:Direct purchasers in renovation contexts increasingly research certified product databases and digital specification platforms before engaging installation services.
Distributors anchor the volume base while contractors gain influence at the steepest rate as installation labor emerges as the constraining variable in project timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian resin compounders supply formulation inputs to US Southeast extrusion clusters, creating a cross-border production corridor that shortens lead times for Gulf Coast commercial projects.
United States
Residential renovation in moisture-prone Gulf Coast and Pacific Northwest submarkets drives waterproof flooring replacement volume. EPA formaldehyde emission rules for composite wood products extend compliance expectations to adjacent LVT categories. Manufacturing concentrates in Georgia, where Calhoun-based operations leverage captive resin compounding to control input costs.
Canada
Provincial health authorities in Ontario and British Columbia specify seamless welded LVT for acute care expansion projects. Health Canada maintains oversight on phthalate content in vinyl products targeting residential environments with child occupancy. Quebec and Ontario host resin formulation facilities serving US Southeast extrusion demand.
Mexico
Cross-border manufacturing investment targets US retail channel supply with shorter delivery windows than Asian imports. Mexico's federal consumer protection agency enforces product safety standards aligned with US CPSC protocols. Nuevo León and Bajío Region industrial parks attract flooring component assembly for North American distribution.
North America Luxury Vinyl Tile (LVT) Market Competitive Landscape
On the supply side, the industry is consolidating around integrated resin-to-finished-product operations that compress cost differentials between rigid and flexible formats. Three archetypes dominate: diversified flooring conglomerates with captive chemical operations, specialized print-layer technology developers, and regional fabrication specialists serving contractor networks. Competitive moves center on extrusion line hybridization for mineral composite loading and distribution partnerships with national home improvement retailers.
Among diversified flooring conglomerates, Mohawk Industries and Shaw Industries exemplify integrated supply chain control, while Mannington Mills occupies a position as a specialized technology developer. These three entities represent the dominant competitive archetypes: scale-driven vertical integration, retail channel anchoring, and aesthetic differentiation through proprietary print systems.
| Leading Market Players |
|---|
| Mohawk Industries |
| Shaw Industries |
| Armstrong Flooring |
| Mannington Mills |
| Interface |
| Tarkett |
| LG Hausys |
| AHF Products |
| Congoleum |
| Others |
Value Network & Pricing Analysis
Gulf Coast petrochemical corridors concentrate PVC resin and plasticizer supply for North American LVT manufacturing, anchoring margin pools with integrated producers in Georgia and Texas who control captive compounding operations while independent extruders face raw material volatility.
Pricing Analysis
Next-generation rigid core SPC formulations command premium positioning against legacy flexible vinyl and first-generation WPC platforms. Three-tier pricing structure across premium, standard, and economy levels separates healthcare-grade certified products with FloorScore and GREENGUARD Gold from residential retrofit SKUs. Price differentiation rests on certification tier and wear-layer thickness specification. Cost compression in mid-gauge residential segments is intensifying because engineered wood waterproof alternatives capture specification share. Single-family renovation buyers exhibit highest price sensitivity while acute care facilities demonstrate lowest sensitivity due to infection control compliance requirements.
Supply Chain Analysis
Contract manufacturing concentration sits with integrated flooring conglomerates operating captive extrusion lines in Calhoun, Georgia and Dalton, Georgia corridors. Geographic supply concentration centers on the United States Southeast, Canada Quebec and Ontario resin formulation facilities, and Mexico Nuevo León assembly parks. Raw material dependencies draw from Gulf Coast PVC resin, Asian print film and wear-layer substrates, and domestic calcium carbonate mineral loading. Supply chain risk hinges on hurricane disruption exposure along Texas and Louisiana petrochemical infrastructure. Distribution runs through national home improvement retailers, commercial flooring dealers, and direct contractor supply relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American LVT represents early-cycle expansion anchored by waterproof flooring retrofit demand in moisture-prone residential submarkets where failed hardwood and laminate installations drive replacement volume.
For Market Incumbents: Insulate specification position by deepening backward integration into resin compounding and accelerating FloorScore certification timelines for trend-responsive collections. Threat exposure from engineered wood waterproof substitutes demands countering with enhanced click-lock speed claims and documented labor savings. Channel control through national retailer partnerships anchors volume defense. For New Entrants and Emerging Players: Build out regional fabrication capacity serving contractor networks in Sun Belt metropolitan areas where construction velocity outpaces distributor technical support. Healthcare acute care renovation in Ontario and British Columbia presents the most penetrable white-space target. Go-to-market execution through direct digital specification platforms bypasses incumbent distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabrication specialists possessing installed extrusion capacity but lacking captive resin supply. Long-term viability over the five-to-ten year window rests on closed-loop recycling infrastructure positioning ahead of extended producer responsibility mandates. Monitor state-level collection obligation legislation passage in Northeast and West Coast corridors as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Mohawk Industries' Calhoun operations demonstrate margin control through captive PVC formulation supply. |
| FloorScore Certification Acceleration | Third-party indoor air quality validation opens California public procurement channels for healthcare and education construction. |
| Click-Lock Installation System Expansion | Mechanical fastening reduces adhesive dependency and accelerates multi-family housing turnover project completion. |
| Closed-Loop Recycling Infrastructure | End-of-life collection capabilities position producers for pending extended producer responsibility legislation in coastal states. |
| Digital Print-Layer Technology Investment | High-definition scanning systems enable rapid aesthetic refresh without tooling changeover costs for hospitality specification. |
Research Methodology
A spread of perspectives from LVT plant managers, resin procurement leads at downstream extruders, commercial flooring distribution partners, and healthcare facilities directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with technical R&D directors and specification sales representatives at national home improvement retailers. Secondary validation drew from US EPA formaldehyde emission filings, California Air Resources Board regulatory updates, FloorScore certified product databases, and SEC 10-K disclosures from diversified flooring conglomerates. Bottom-up volume triangulation across product format, installation method, and end-use application intersected with top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling residential renovation cycles against extrusion line capacity expansion in the US Southeast. Segmentation dimensions included core material format, application vertical, installation system, and regional procurement channel. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity utilization trends. Industry-specific forecast inputs incorporated CARB Phase 2 compliance adoption curves and waterproof flooring penetration rates in Gulf Coast and Pacific Northwest submarkets.
Stress conditions across resin price volatility, hurricane disruption frequency, and engineered wood substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and contractor labor availability. Quarterly review of state-level extended producer responsibility legislative progress and FloorScore certification database expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
Angular Rubber Expansion Joints Market