
 Epoxy Grout Market | 2026-2036
Epoxy Grout Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Grout Market Analysis
Commercial flooring specification is pivoting toward chemical-resistant installations in food processing and pharmaceutical plants. LATICRETE International Inc. leverages its specialty installation systems to anchor premium project relationships across North America. Sika AG competes through integrated waterproofing and grouting portfolios that extend cross-selling opportunities in industrial builds. Mapei S.p.A. dominates Mediterranean and Middle Eastern supply channels through localized manufacturing scale and brand recognition.
Epoxy grout consists of epoxy resin and hardener combined with silica fillers to create a dense, chemically resistant joint filler that bonds aggressively to tile edges and substrate. Manufacturers formulate products with compressive strengths exceeding standard cement grout to withstand thermal cycling and aggressive cleaning protocols. Heavy-duty formulations command the strongest margin pools in industrial and pool applications where chemical exposure is routine. Flexible product variants are gaining specification share in high-rise commercial towers subject to structural movement. DIY end-user penetration remains limited by multi-component mixing complexity and shortened working time.
EPA VOC regulations constrain solvent content in U.S.-manufactured formulations, while REACH registration requirements in Europe govern epoxy resin constituent disclosure and hazard classification. OSHA workplace exposure limits further shape product handling protocols and contractor training requirements in American industrial settings. Stakeholders must monitor evolving low-VOC mandates and antimicrobial additive approvals across multiple jurisdictions to maintain specification eligibility.
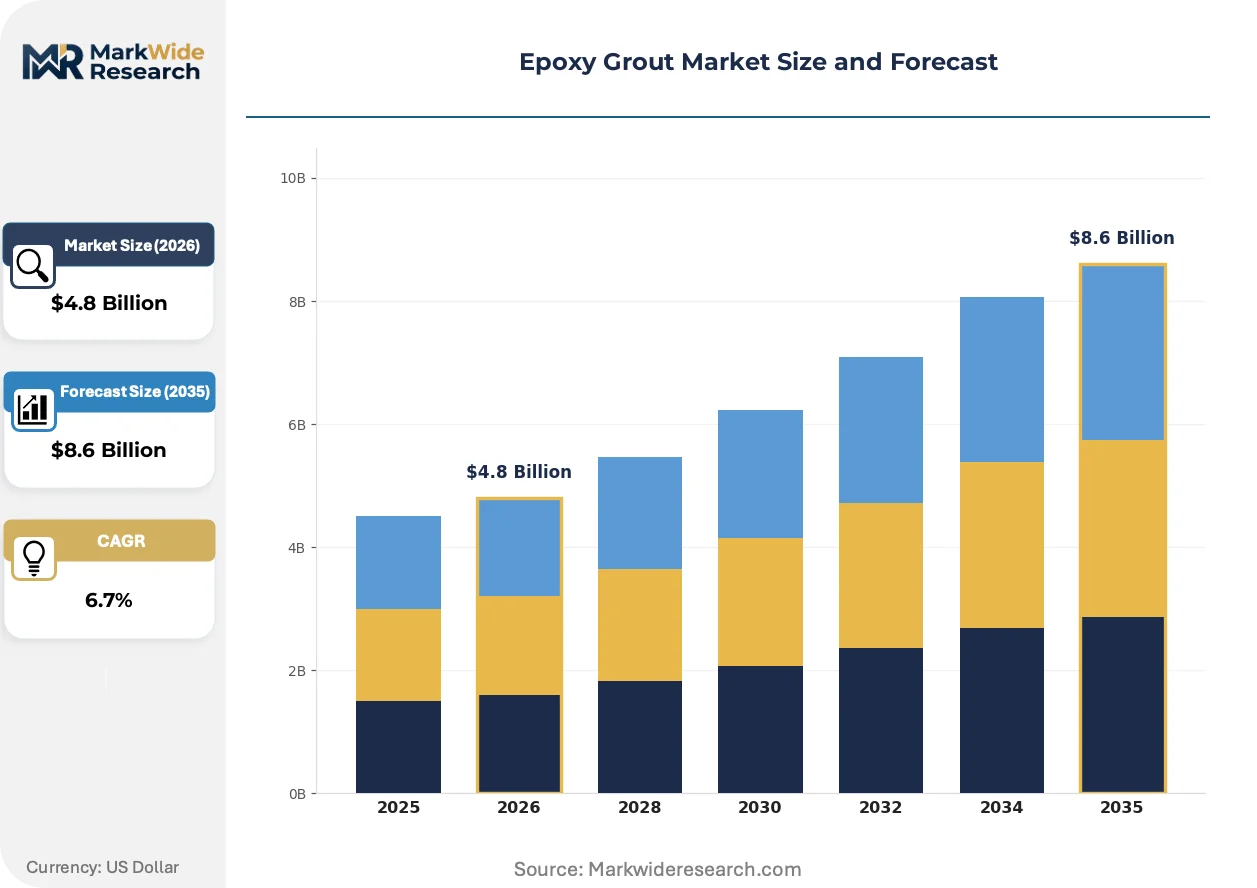
Market Dynamics
Commercial infrastructure renovation across hospitality and healthcare facilities is accelerating epoxy grout specification, while REACH compliance in Europe and evolving EPA VOC standards in North America are tightening formulation requirements and reshaping competitive positioning among manufacturers.
Growth Catalysts
- Renovation Wave in Hospitality:Post-pandemic facility upgrades in hotels and resorts are driving specification of chemical-resistant, stain-proof joint fillers for high-traffic flooring systems.
- REACH Registration Requirements:ECHA mandates for epoxy resin constituent disclosure are filtering out non-compliant suppliers and consolidating specification authority among registered formulators.
- Food Safety Protocols:USDA and FDA facility standards for food processing plants are mandating non-porous, antimicrobial grout systems that withstand aggressive sanitization cycles.
Market Restraints
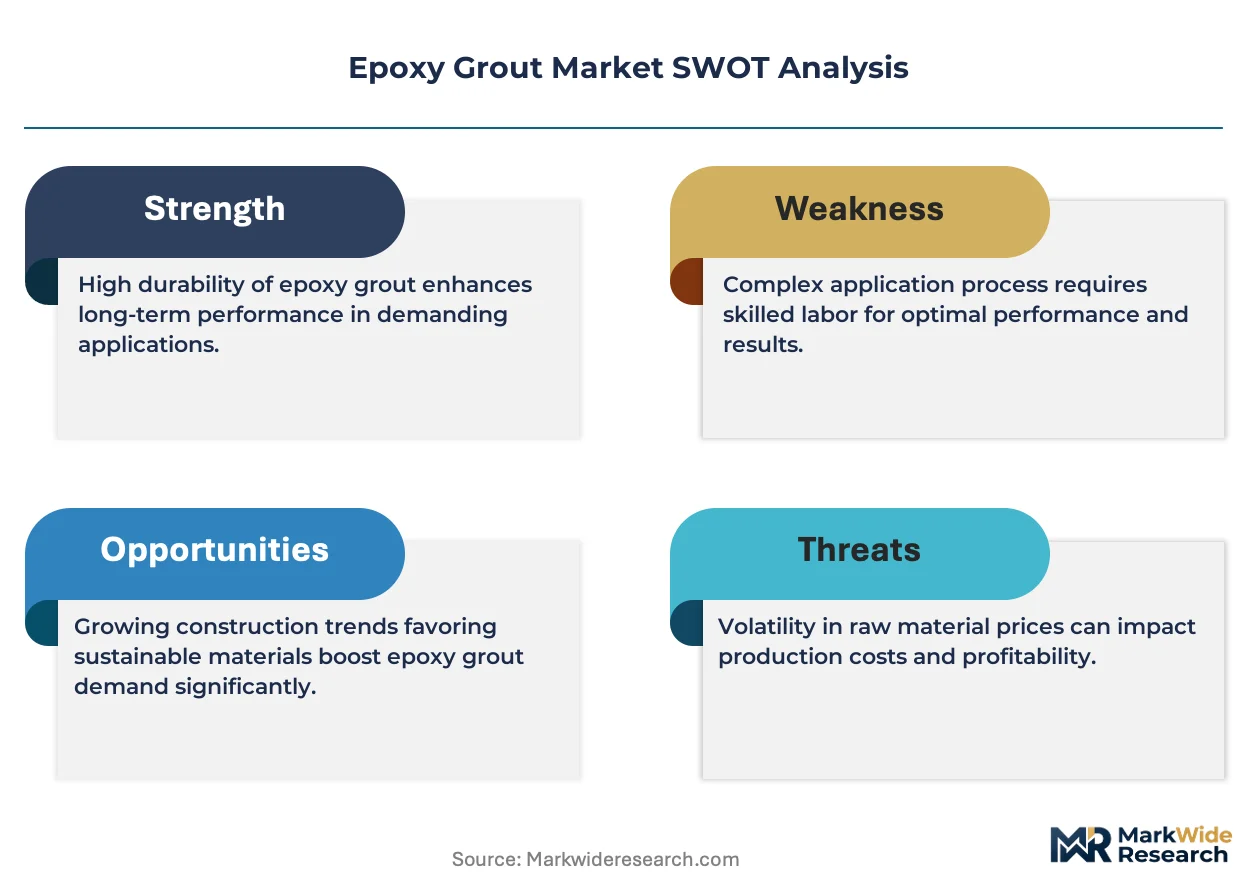
- Epoxy Resin Price Volatility:Bisphenol A and specialty hardener feedstock costs fluctuate with petrochemical cycles, compressing margin predictability for formulated products.
- DIY Penetration Ceiling:Multi-component mixing complexity and shortened working time create a structural barrier to residential consumer adoption, limiting volume expansion beyond professional channels.
- Cement Grout Substitution:Advanced polymer-modified cementitious systems offer adequate performance at lower installed cost for light-commercial applications.
Strategic Opportunities
- Modular Construction Integration:Prefabricated bathroom and kitchen pod manufacturers in Germany and the United States represent an underpenetrated specification channel for factory-applied epoxy grout systems.
- Antimicrobial Additive Approvals:EPA and BPR registrations for silver-ion and zinc-based antimicrobial chemistries create regulatory tailwinds for premium healthcare and pharmaceutical facility specifications.
- Flexible Formulation Development:High-rise commercial towers in earthquake-prone zones are creating demand for movement-accommodating grout variants that bridge performance gaps with sealant systems.
Industry Challenges
- Certified Installer Scarcity:Proper epoxy grout application demands skilled technicians trained in substrate preparation, mixing ratios, and timing protocols that differ substantially from cement grout methods.
- Multi-Jurisdiction Compliance Burden:Manufacturers must maintain parallel formulation portfolios to satisfy EPA VOC limits, REACH registration dossiers, and state-level California SCAQMD rules simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Grout Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, Quick-setting, Heavy-duty End User: Residential, Commercial, Industrial, DIY Application: Flooring, Wall Tiles, Countertops, Swimming Pools Form: Liquid, Paste, Powder, Pre-mixed |
| Companies Covered | Henkel AG & Co. KGaA, LATICRETE International Inc., Sika AG, Bostik, Saint-Gobain, Mapei S.p.A., Ardex Group, H.B. Fuller Company, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Grout Market Emerging Trajectories
Formulation chemistry is pivoting toward low-VOC and rapid-cure systems that compress installation timelines, while regulatory pressure and end-user specification preferences are reshaping how manufacturers prioritize R&D investment and commercialize new product generations.
Water-dispersible epoxy technology is consolidating specification share in commercial flooring applications where solvent-based systems previously dominated. Food processing plants and pharmaceutical cleanrooms in the United States are adopting these formulations to meet OSHA workplace exposure limits without sacrificing chemical resistance. The shift is compressing demand for traditional solvent-carrier products and forcing reformulation of legacy industrial-grade portfolios.
REACH authorization procedures for bisphenol A derivatives are tightening constituent disclosure requirements across European supply chains. ECHA's evolving hazard classification framework is pushing manufacturers toward alternative epoxy resin chemistries and comprehensive substance volume tracking. German and French industrial flooring contractors are now requiring full formulation transparency as a prequalification criterion for large-scale pharmaceutical and chemical plant tenders.
Specification authority is migrating from general contractors to specialized flooring consultants and facility maintenance directors who control long-term lifecycle cost decisions. This procurement pattern shift is elevating technical service capabilities and warranty terms over unit price in competitive evaluations. Healthcare systems in the United States and hospitality chains in the United Arab Emirates are consolidating vendor relationships with full-system providers who bundle grout, adhesive, and waterproofing products under single-source accountability structures.
Epoxy Grout Market Segmentation
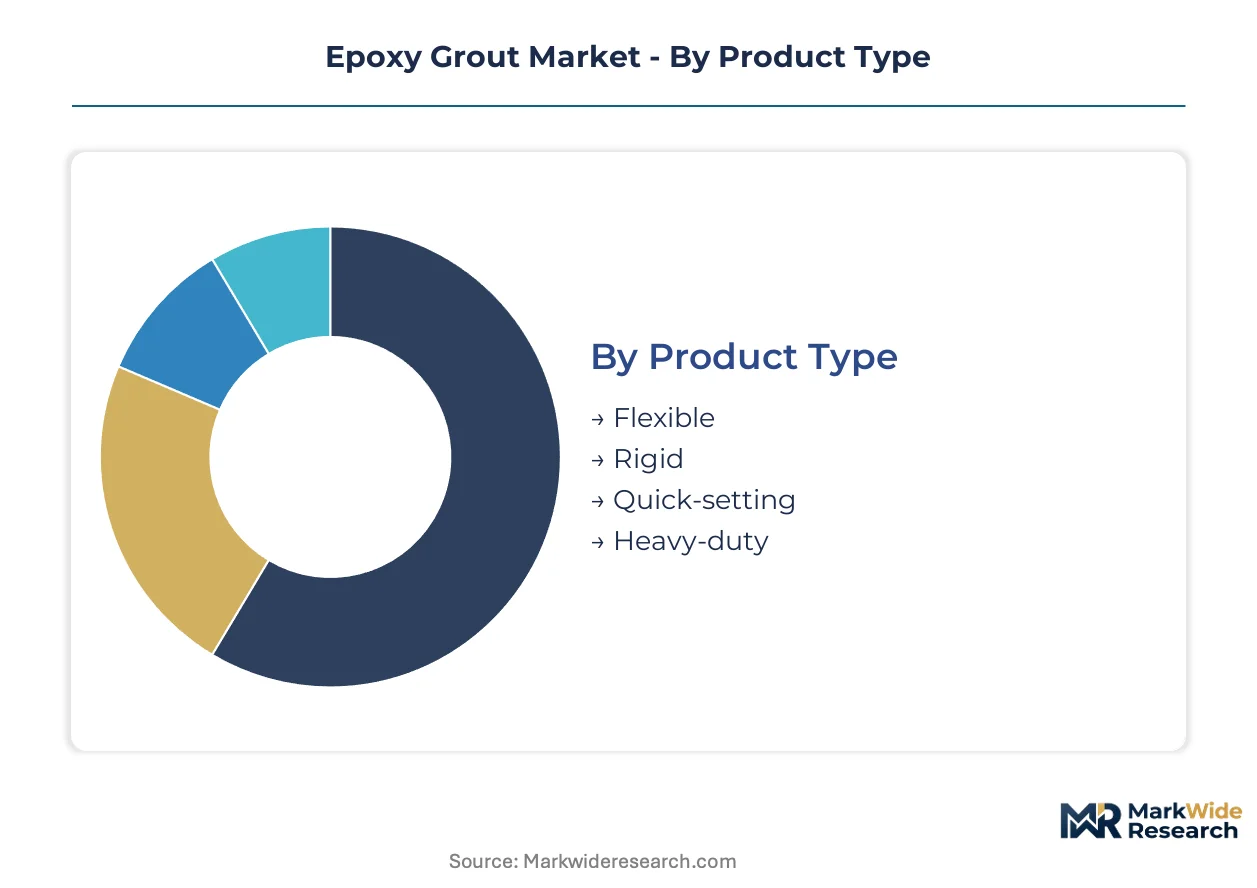
Epoxy grout specification varies sharply across installation contexts, with formulation chemistry and physical form determining suitability for structural movement tolerance, chemical exposure severity, and contractor skill levels. Upgrade cycles in commercial infrastructure and industrial facility modernization are redrawing segment boundaries as end-users prioritize lifecycle performance over first-cost procurement.
Product Type:
Facility renovation cycles and substrate condition assessments are driving specification shifts between movement-accommodating and high-strength formulations.
- Flexible:Modified resin chemistries incorporate elastomeric additives that accommodate thermal expansion and structural settling in high-rise towers and exterior facades. German and UAE commercial contractors specify these variants for podium-level retail and hospitality flooring subject to seismic movement zones.
- Rigid:Standard epoxy resin-hardener systems cure to glass-like density with compressive strengths exceeding conventional cement grout. Pharmaceutical cleanrooms and food processing plants across the United States specify rigid formulations for their impermeability to bacterial penetration and aggressive sanitization chemicals.
- Quick-setting:Accelerated cure catalysts compress return-to-service windows for maintenance shutdowns in 24-hour manufacturing operations.
- Heavy-duty:Silica-aggregate loading and enhanced cross-link density withstand thermal cycling in chemical plant trench drains and secondary containment areas.
Heavy-duty formulations sit at the top of the volume ranking, with flexible variants climbing the fastest as structural engineers specify movement-tolerant joint systems.
End User:
Professional installation requirements and performance warranties are concentrating demand in contractor-driven channels rather than consumer retail.
- Commercial:Hotels, hospitals, and retail chains specify epoxy grout through facilities management procurement frameworks that emphasize single-source accountability and extended warranty terms. LATICRETE and Sika compete for multi-site master agreements with U.S. hospitality chains undergoing post-pandemic renovation programs.
- Industrial:Food processing, pharmaceutical manufacturing, and chemical handling facilities mandate non-porous joint fillers that withstand OSHA-mandated cleaning protocols and FDA facility inspection standards. USDA facility registrations increasingly require documented grout specifications as part of hazard analysis protocols.
- Residential:High-end custom homes and luxury multi-family developments specify epoxy grout for wet-area durability, though volume remains constrained by certified installer availability.
- DIY:Multi-component mixing complexity and shortened working time limit penetration to niche enthusiast segments with prior epoxy handling experience.
Industrial end-use dominates current volume, with commercial renovation activity expanding most quickly as hospitality and healthcare systems accelerate deferred maintenance programs.
Application:
Exposure severity and cleaning chemical selection are determining formulation requirements across horizontal and vertical surfaces.
- Flooring:High-traffic commercial and industrial slabs subject to forklift traffic, thermal shock, and chemical spill exposure. German automotive manufacturing plants and U.S. beverage production facilities specify heavy-duty formulations with enhanced abrasion resistance.
- Swimming Pools:Continuous immersion in chlorinated water and freeze-thaw cycling demands specialized hydrolysis-resistant resin systems. Mediterranean and Middle Eastern pool construction specifies premium grades with documented long-term color stability.
- Wall Tiles:Vertical installations in commercial kitchens and laboratory spaces require non-sag paste consistency and rapid tack development.
- Countertops:Food preparation surfaces in restaurants and residential kitchens specify stain-resistant formulations with antimicrobial additive packages.
Flooring applications command the greatest volume share, with swimming pool specifications gaining share fastest in coastal resort and municipal recreation markets.
Form:
Supply chain logistics and on-site mixing infrastructure are shaping manufacturer decisions between factory-blended and field-proportioned delivery systems.
- Liquid:Two-component resin and hardener systems delivered in separate containers for precise on-site proportioning. Industrial contractors in the United States prefer liquid systems for large-scale warehouse flooring where batch sizes vary by project phase.
- Paste:Pre-thickened consistency eliminates sag in vertical applications and overhead tile installations. Mapei's paste formulations dominate Mediterranean commercial wall tile specifications through distributor-trained applicator networks.
- Powder:Dry-blended resin and filler systems require water addition on site, offering extended shelf life for remote project locations with irregular material delivery schedules.
- Pre-mixed:Factory-catalyzed single-component systems eliminate field proportioning errors but constrain working time and require cold-chain logistics for extended storage.
Liquid systems maintain the highest volume position, with pre-mixed formats climbing the fastest as modular construction manufacturers seek factory-applied consistency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redirecting formulation production toward jurisdictions with streamlined chemical registration frameworks. Manufacturers balance REACH compliance burdens in Europe against EPA VOC enforcement in North America while capturing growth in Middle Eastern commercial construction.
United States
Post-pandemic hospitality renovation and pharmaceutical facility expansion drive specification of chemical-resistant joint systems. EPA VOC regulations under the Clean Air Act constrain solvent content in manufactured formulations, pushing water-dispersible epoxy adoption. Texas and California industrial corridors concentrate demand from food processing plants and semiconductor fabrication facilities undergoing capacity upgrades.
Germany
Automotive manufacturing plant modernization and chemical processing facility upgrades sustain industrial-grade consumption. ECHA REACH authorization procedures for bisphenol A derivatives tighten constituent disclosure requirements across supply chains. The Rhine-Ruhr and Bavarian industrial clusters anchor specification activity for pharmaceutical cleanrooms and high-traffic commercial flooring systems.
China
Urban commercial real estate development and healthcare infrastructure expansion accelerate specification in high-rise towers and hospital complexes. GB standards for construction chemical emissions shape domestic formulation requirements alongside provincial environmental enforcement. Yangtze River Delta manufacturing zones concentrate production capacity serving both domestic projects and export markets across Southeast Asia.
United Arab Emirates
Hospitality resort construction and luxury residential development drive premium-grade consumption for swimming pools and wet-area applications. MOHAP facility standards for healthcare infrastructure mandate antimicrobial joint systems in hospital procurement frameworks. Dubai and Abu Dhabi commercial districts specify imported European formulations for high-visibility projects requiring documented color stability warranties.
Saudi Arabia
NEOM giga-project construction and Red Sea tourism development create specification channels for heavy-duty industrial and decorative applications. SFDA food facility registration requirements align with international standards for non-porous, sanitization-resistant joint fillers. Eastern Province petrochemical complexes and Riyadh commercial towers represent concentrated demand pockets for movement-accommodating and rigid formulations respectively.
Epoxy Grout Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system providers commanding premium positioning in commercial master agreements while regional formulators capture project-specific industrial specifications. The structure consolidates around three tiers: multinational adhesive and construction chemical conglomerates with integrated waterproofing portfolios; specialty flooring system providers with certified installer networks; and regional compounders serving price-sensitive public works tenders. Dominant competitive moves include geographic expansion through distributor acquisition and technology licensing partnerships that accelerate low-VOC formulation deployment.
Within the multinational tier, Sika AG, Mapei S.p.A., and LATICRETE International Inc. exemplify divergent strategic positioning. The Swiss conglomerate structure of Sika AG represents integrated construction chemical portfolios spanning waterproofing, grouting, and industrial flooring. Mapei S.p.A. occupies a position as a family-controlled Italian specialist with Mediterranean and Middle Eastern manufacturing scale. LATICRETE International Inc. anchors the North American specialty channel through specification relationships with hospitality and healthcare facility managers. These three entities collectively represent the competitive archetypes shaping procurement patterns across premium commercial and regulated industrial segments.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| LATICRETE International Inc. |
| Sika AG |
| Bostik |
| Saint-Gobain |
| Mapei S.p.A. |
| Ardex Group |
| H.B. Fuller Company |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Backward integration into bisphenol A and specialty hardener production anchors supply security for epoxy grout manufacturers while insulating premium formulation tiers from petrochemical feedstock volatility. This captive sourcing strategy concentrates pricing power among multinational chemical conglomerates that control resin production, leaving regional compounders exposed to margin compression during upstream cost spikes.
Pricing Analysis
Distributor margins of 15-25 percent separate factory gate pricing from installed project costs across commercial flooring channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EPA-registered antimicrobial formulations commanding substantial premiums over commodity industrial grades. Cost compression in economy tiers is intensifying because advanced polymer-modified cementitious systems offer adequate performance for light-commercial applications at lower installed cost. Industrial end-users demonstrate lowest price sensitivity due to lifecycle cost frameworks, while residential contractors remain most responsive to unit price competition.
Supply Chain Analysis
Freight costs from German and Chinese manufacturing hubs to Middle Eastern project sites add 8-12 percent to delivered material costs, compressing competitiveness for non-integrated suppliers. Raw material sourcing draws from epoxy resin production concentrated in China, Germany, and the United States, with silica filler supply anchored in domestic quarry operations. Single-source vulnerability in specialty hardener chemistry creates exposure to petrochemical cycle disruptions. Distribution runs through construction chemical distributors and direct specification relationships with flooring contractors, with master service agreements increasingly bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA antimicrobial additive registrations and REACH authorization milestones create specification barriers that consolidate demand among compliant formulators.
For Market Incumbents: Deepen certified installer network density in Texas and California industrial corridors to defend specification share against emerging water-dispersible epoxy specialists. Anchor backward integration into hardener chemistry to offset bisphenol A price volatility that threatens margin pools in heavy-duty formulations. Prioritize ECHA registration dossier maintenance as REACH authorization procedures filter non-compliant competitors from European pharmaceutical tenders. For New Entrants and Emerging Players: Flooring consultants and facility maintenance directors represent the most accessible specification authority channel for insurgent brands lacking multi-site master agreements. Modular construction manufacturers in Germany and the United States present underpenetrated white-space for factory-applied pre-mixed systems. Target antimicrobial additive registration as the primary go-to-market wedge, leveraging EPA registration timelines to establish credibility before pursuing industrial facility specifications. For Investors and Strategic Acquirers: Roll-up economics work for regional epoxy grout compounders because REACH compliance burdens and EPA registration costs create fixed-cost barriers that favor scaled platforms over fragmented local suppliers. Target acquisition archetypes include Mediterranean and Middle Eastern distributors with captive applicator training infrastructure and established relationships with hospitality procurement frameworks. Watch EPA antimicrobial additive approval velocity as the inflection signal for premium healthcare specification share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hardener Chemistry | Captive production of specialty curing agents insulates margin pools from petrochemical feedstock volatility cycles. |
| EPA Antimicrobial Additive Registration | Silver-ion and zinc-based chemistry approvals unlock premium healthcare and pharmaceutical facility specifications. |
| Certified Installer Network Expansion | Trained applicator density in industrial corridors defends specification share against water-dispersible epoxy substitutes. |
| REACH Registration Dossier Investment | ECHA-compliant formulation transparency secures prequalification for German and French pharmaceutical plant tenders. |
| Modular Construction Partnership Development | Factory-applied pre-mixed system integration captures specification share in prefabricated bathroom and kitchen pod manufacturing. |
Methodological Framework
Bottom-up commercial and industrial flooring modeling reconciled against top-down resin production and formulation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at food processing facilities, procurement leads at hospitality chains, flooring contractors, and technical R&D directors at construction chemical manufacturers were cross-validated against secondary sources including EPA registration databases, ECHA authorization dossiers, customs trade data, and SEC filings from publicly traded chemical conglomerates.
Input-output matrices map epoxy resin and hardener consumption through formulation tiers to end-use segments across the projection horizon. Segmentation dimensions include product type flexibility, end-use industry, application exposure severity, and regional regulatory cluster. CAGRs were derived from weighted average of demand elasticity coefficients and supply capacity expansion schedules, with inputs from OSHA workplace exposure limit evolution and USDA facility registration trend analysis.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization timelines for bisphenol A derivatives and EPA antimicrobial additive approval velocity. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
PU Waterstops Market
Building & Construction Materials
Europe Faucet Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
Branched Reinforced Fittings Market
Building & Construction Materials
Israel Ceramic Tiles Market