
 Prestressed Concrete (PC) Wire and Strand Market | 2026-2036
Prestressed Concrete (PC) Wire and Strand Market Size, Share, and Industry Trends Forecast 2026-2036
Prestressed Concrete (PC) Wire and Strand Market Intelligence
Project finance tied to build-operate-transfer highway contracts is reconfiguring capital deployment across the prestressed concrete supply chain. NV Bekaert SA leverages its European wire-drawing heritage to sustain premium-grade output for cable-stayed bridge tenders. Tata Steel Limited anchors South Asian project pipelines through integrated billet-to-strand capacity at its Jamshedpur complex.
Prestressed concrete wire and strand comprises high-carbon steel filaments cold-drawn to 1570–1860 MPa tensile strength, then stress-relieved or stabilized to maintain permanent elongation under sustained load; manufacturers wind individual wires into helical strand configurations or leave them as single wires for post-tensioning ducts and precast bed applications. Strand dominates volume throughput for long-span bridge cable systems where bundled 7-wire and 19-wire geometries deliver superior fatigue resistance. Wire competes in building slab post-tensioning where tighter duct curvature demands smaller diameters, while precast elements absorb growing share as offsite fabrication accelerates highway girder production.
ASTM A416 governs US strand mechanical properties, while EN 10138 and ISO 6934 shape European and export-market quality benchmarks; China's GB/T 5224 and India's IS 14268 impose additional national testing protocols that filter supplier eligibility on cross-border infrastructure bids. Japan's JIS G 3536 maintains distinct low-relaxation specifications for seismic-zone applications. Stakeholders must track which certification portfolios unlock specific national project pipelines as public procurement rules harden origin and testing requirements.
Market Dynamics
Bridge megaprojects across Southeast Asia are compressing procurement timelines and forcing strand suppliers to pre-certify under ASTM A416, EN 10138, and GB/T 5224 simultaneously to qualify for cross-border tenders.
Growth Catalysts
- Build-Operate-Transfer Contracts:Highway privatization in India and Indonesia locks in decade-long strand supply commitments, de-risking manufacturer capacity investments.
- Seismic Retrofit Mandates:Japan's METI enforcement of JIS G 3536 low-relaxation specifications for earthquake-prone zones sustains replacement demand for aging infrastructure.
- Offsite Precast Acceleration:Factory-cast bridge girders reduce on-site labor by 40%, concentrating strand procurement at fewer, larger precast yards with direct mill relationships.
Market Restraints
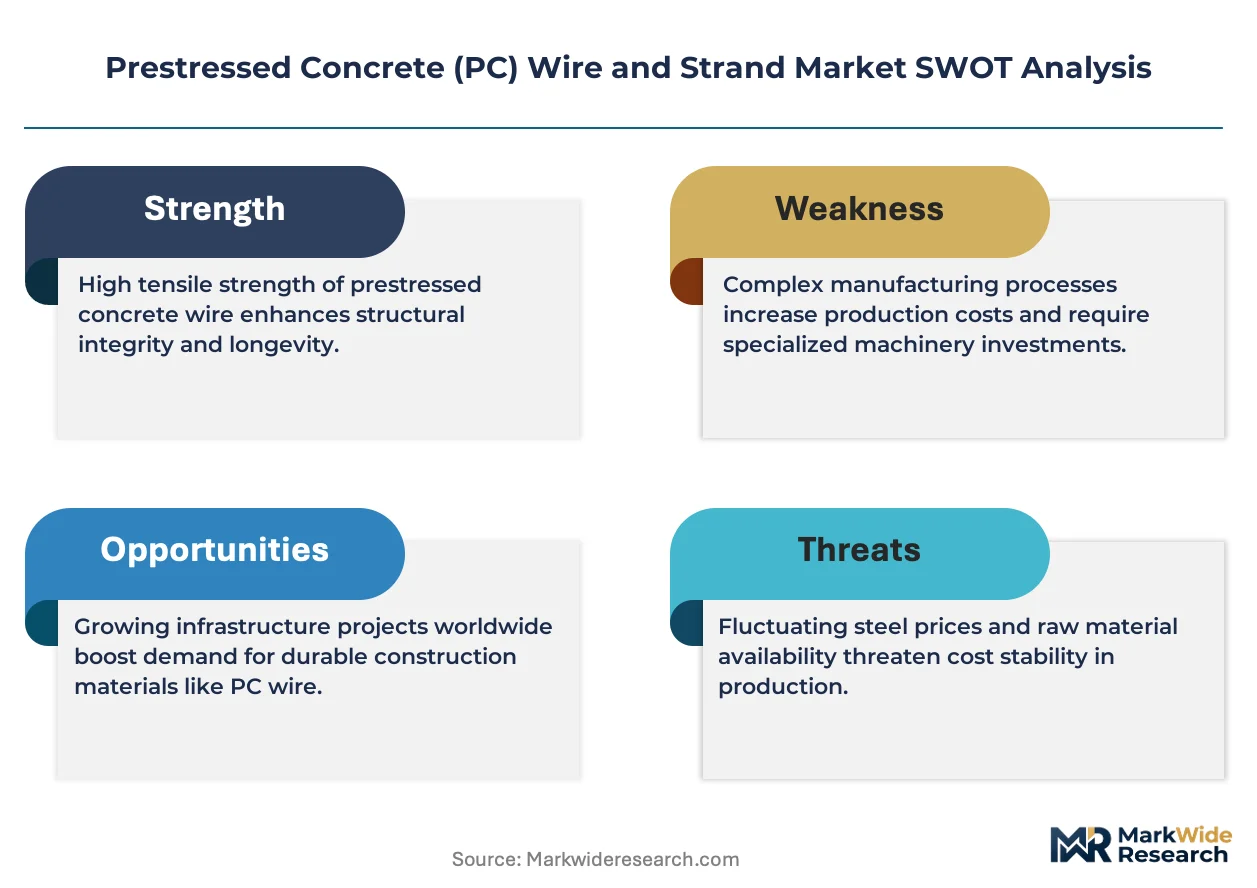
- Scrap-Steel Price Volatility:High-carbon wire rod feedstock tracks ferrous scrap indices, compressing mill margins when construction cycles dip.
- Drawing Capacity Concentration:Seven European wire-drawing groups control 60% of premium-grade strand output, creating bottleneck risk for cable-stayed bridge tenders.
- Epoxy-Coated Rebar Substitution:Corrosion-protection specifications in marine environments sometimes favor coated rebar over stainless-clad strand on cost grounds.
Strategic Opportunities
- Vietnam's Central Coast:The Van Phong trans-shipment port and North-South Expressway Phase 2 create uncontracted demand for 15.7mm and 15.2mm strand grades.
- Carbon-Embodied Procurement Rules:EU Green Deal construction thresholds favor mills with electric-arc furnace billet supply and ISO 14064-verified production.
- Digital Twin Integration:Strand tension-monitoring sensors paired with predictive maintenance platforms open recurring revenue streams beyond commodity supply.
Industry Challenges
- Multi-Certification Lead Times:Parallel ASTM A416, EN 10138, and IS 14268 testing extends qualification cycles to 14-18 months, freezing new entrants from urgent tenders.
- Post-Tensioning Specialist Shortage:Certified stressing crews for bonded and unbonded systems are scarce in emerging markets, delaying project handovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prestressed Concrete (PC) Wire and Strand Market |
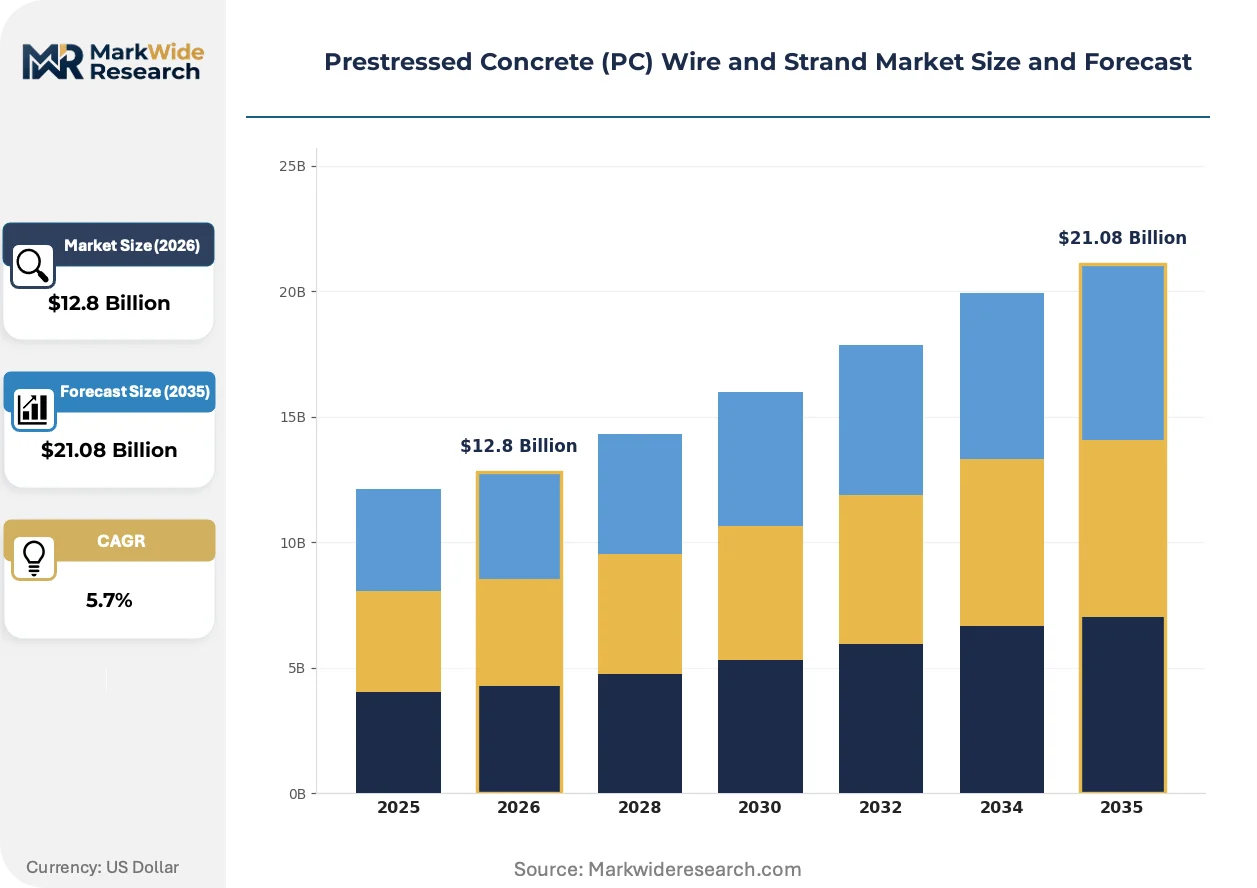
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire, Strand, Bar, Cable End User: Construction, Infrastructure, Precast Elements, Post-tensioning Application: Bridges, Buildings, Highways, Stadiums Distribution Channel: Wholesale, Retail, Direct Sales, Online |
| Companies Covered | JFE Steel Corporation, Kobe Steel, Ltd., Tata Steel Limited, Baoshan Iron & Steel Co., Ltd., Insteel Industries Inc., NV Bekaert SA, ArcelorMittal, FAPRICELA, Indústria de Trefilaria, SA, Nippon Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prestressed Concrete (PC) Wire and Strand Market Strategic Shifts & Innovations
Strand manufacturing is converging with sensor embedding and low-carbon metallurgy, reshaping how infrastructure owners specify, procure, and monitor prestressing systems over multi-decade asset lives.
Galvanized and waxed strand with factory-applied corrosion inhibitors is hybridizing with traditional bare-steel supply for marine and de-icing salt exposure. Port authorities in Rotterdam and Singapore specify these duplex systems for quay walls and container wharves. The technology is compressing the price premium between standard and high-durability grades as coating lines achieve scale.
REACH substance restrictions and the EU F-Gas Regulation are tightening traceability requirements for lubricants and drawing compounds used in cold-forming. Strand mills serving European export markets must reformulate process chemistry or risk batch rejection at customs. German bridge tenders now mandate full material passport documentation from billet origin through final spooling.
Owners are unbundling supply and installation contracts, forcing strand manufacturers to certify local stressing subcontractors or forfeit turnkey project eligibility. India's National Highways Authority and Indonesia's Waskita Karya have adopted this split-procurement model. The shift concentrates volume at mills with established regional service networks rather than lowest-unit-cost exporters.
Prestressed Concrete (PC) Wire and Strand Market Segmentation
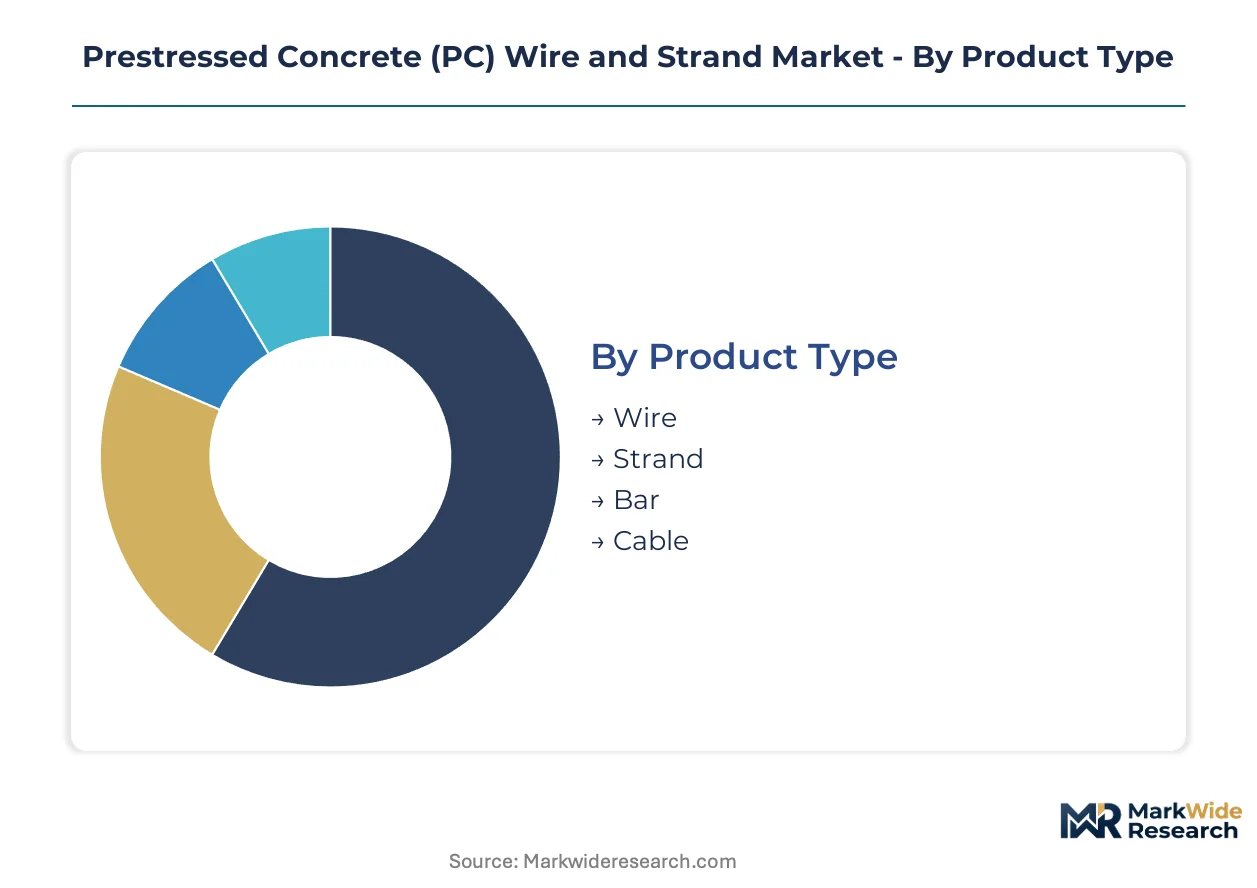
Segmentation in prestressed concrete wire and strand markets reveals how procurement cycles, certification requirements, and installation complexity vary sharply across product forms and end-use categories. Buyers structure supplier relationships differently depending on whether they need commodity wire for building slabs or engineered strand for cable-stayed bridge tenders.
Product Type:
Strand turns over fastest on long-term highway contracts while bar and cable systems lock in multi-year procurement cycles due to custom engineering and extended qualification timelines.
- Wire:Single high-carbon steel filaments cold-drawn to 1570–1860 MPa tensile strength serve post-tensioning ducts in building slabs where tighter curvature radii exclude larger diameters. India's coastal megaprojects specify wire for high-rise floor plates where duct congestion limits strand geometry.
- Strand:Helical 7-wire and 19-wire configurations dominate fatigue-critical applications including cable-stayed bridge main cables and external post-tensioning tendons. Southeast Asia's bridge megaprojects compress procurement timelines and force simultaneous ASTM A416, EN 10138, and GB/T 5224 pre-certification.
- Bar:Threaded prestressing bars anchor segmental bridge cantilevers and heavy-lift precast elements requiring adjustable tensioning.
- Cable:Bundled strand assemblies with corrosion-protection systems serve long-span suspension bridges and specialized structural stays.
Strand anchors the volume base while cable systems gain share at the steepest rate as owners specify turnkey stay-cable packages.
End User:
Cost tiers separate commodity construction supply from engineered infrastructure procurement, with certification depth and technical service intensity rising steeply across the spectrum.
- Construction:General building contractors source wire and strand through wholesale distributors for routine post-tensioning slabs and beams, prioritizing availability over mill-direct relationships.
- Infrastructure:Highway authorities and port operators specify mill-branded strand with full traceability documentation under EU Green Deal carbon-embodied thresholds. Rotterdam and Singapore port authorities mandate duplex corrosion-protection systems for marine exposure zones.
- Precast Elements:Factory-cast bridge girder yards concentrate procurement at fewer suppliers with direct billet-to-strand capacity, reducing on-site labor by 40% through offsite fabrication acceleration.
- Post-tensioning:Specialist contractors for bonded and unbonded systems face scarcity in emerging markets, delaying project handovers where certified stressing crews are unavailable.
Infrastructure commands the premium tier while precast elements expand most quickly as offsite fabrication displaces cast-in-place methods.
Application:
Volume concentration varies by asset life and seismic exposure, with replacement cycles shortest in de-icing salt environments and longest in controlled indoor structures.
- Bridges:Cable-stayed and suspension systems absorb the highest-specification strand grades with parallel multi-certification requirements. Japan's METI enforces JIS G 3536 low-relaxation specifications for seismic-zone bridge retrofits, sustaining replacement demand for aging infrastructure.
- Buildings:High-rise commercial towers drive wire demand for flat-slab post-tensioning where duct congestion favors smaller diameters over strand geometry.
- Highways:Build-operate-transfer contracts in India and Indonesia lock in decade-long strand supply commitments, de-risking manufacturer capacity investments through privatized toll-road pipelines.
- Stadiums:Long-span roof structures require specialized cable systems with architectural exposure finish requirements.
Highways anchor the volume base while bridges gain share at the steepest rate as Southeast Asian governments prioritize cross-border connectivity.
Distribution Channel:
Customer type and order scale determine channel selection, with direct relationships dominating large infrastructure and digital platforms penetrating small-contractor segments.
- Wholesale:Regional distributors stock standard wire and strand grades for construction contractors with intermittent, specification-flexible demand patterns.
- Retail:Limited penetration in this capital-goods category; small-quantity sales occur through construction supply yards for repair and maintenance applications.
- Direct Sales:Mill-direct relationships dominate infrastructure and precast yard procurement, with NV Bekaert SA and Tata Steel Limited anchoring South Asian project pipelines through integrated capacity.
- Online:Digital platforms emerge for standardized wire specifications in developed markets, though strand for engineered applications requires technical consultation that resists full digitization.
Direct sales anchors the volume base while online channels gain share at the steepest rate among small-contractor construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for specialty steel and Vietnam's North-South Expressway Phase 2 are redirecting procurement flows across the prestressed concrete supply chain. Government-backed infrastructure programs in Japan and Indonesia compress tender timelines. Certification requirements harden in Germany and the United Arab Emirates.
India
The National Highways Authority's build-operate-transfer pipeline locks in decade-long strand commitments for the Delhi-Mumbai Industrial Corridor and coastal megaprojects. BIS enforces IS 14268 testing protocols that filter supplier eligibility on cross-border bids. Tata Steel's integrated billet-to-strand complex at Jamshedpur anchors South Asian supply.
Vietnam
The Van Phong trans-shipment port and North-South Expressway Phase 2 generate uncontracted demand for 15.2mm and 15.7mm strand grades. Ministry of Transport procurement rules mandate simultaneous ASTM A416 and EN 10138 pre-certification for bridge tenders. Ho Chi Minh City-based precast yards concentrate procurement at mills with direct regional service networks.
Japan
METI enforcement of JIS G 3536 low-relaxation specifications sustains replacement demand for seismic-zone bridge retrofits. The regulator mandates distinct mechanical properties for earthquake-prone infrastructure. Osaka-Kobe industrial corridor fabricators supply domestic cable-stayed projects with premium-grade stabilized strand.
Germany
EU Green Deal construction thresholds favor mills with electric-arc furnace billet supply and ISO 14064-verified production. REACH substance restrictions tighten traceability for lubricants used in cold-forming. Düsseldorf-Ruhr wire-drawing clusters control premium-grade output for cable-stayed bridge tenders across Europe.
United Arab Emirates
Port authorities in Dubai and Abu Dhabi specify duplex corrosion-protection systems for quay walls and container wharves. MOHAP-aligned procurement rules harden origin requirements for marine exposure zones. Jebel Ali industrial zone precast yards absorb growing strand volumes as offsite fabrication accelerates.
Prestressed Concrete (PC) Wire and Strand Market Key Industry Players
On the supply side, the industry is consolidating around integrated steel majors and specialized wire-drawing groups with multi-certification portfolios. Seven European wire-drawing groups control the majority of premium-grade strand output for fatigue-critical applications. Two strategic archetypes dominate: billet-integrated mills with captive feedstock and specialist strand fabricators with regional service networks. Capacity expansion and backward integration into high-carbon wire rod supply represent the primary competitive moves.
Among Japanese integrated steel producers, JFE Steel Corporation and Kobe Steel, Ltd. exemplify the premium-tier archetype with JIS G 3536 low-relaxation capabilities. NV Bekaert SA occupies a position within the specialized wire-drawing tier, leveraging European heritage for cable-stayed bridge tenders. Tata Steel Limited anchors the billet-integrated model through its Jamshedpur complex, representing South Asian supply concentration.
| Leading Market Players |
|---|
| JFE Steel Corporation |
| Kobe Steel, Ltd. |
| Tata Steel Limited |
| Baoshan Iron & Steel Co., Ltd. |
| Insteel Industries Inc. |
| NV Bekaert SA |
| ArcelorMittal |
| FAPRICELA, Indústria de Trefilaria, SA |
| Nippon Steel Corporation |
| Others |
Cost & Logistics Intelligence
Scrap-steel price volatility in high-carbon wire rod feedstock compresses mill margins unevenly across certification tiers, widening spreads between ASTM A416-qualified premium strand and unbranded construction-grade wire while forcing procurement offices toward long-term offtake contracts with billet-integrated suppliers.
Pricing Analysis
Certification level under ASTM A416, EN 10138, and JIS G 3536 creates the primary spread between premium fatigue-resistant strand and commodity construction wire. Three-tier pricing structure across premium, standard, and economy levels reflects multi-certification lead times and testing depth. Cost compression in standard-grade supply intensifies as Chinese mills expand GB/T 5224 output for Southeast Asian bridge tenders. General building contractors through wholesale distributors exhibit highest price sensitivity, while highway authorities with build-operate-transfer contracts prioritize traceability over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from European wire-drawing groups lock in precast yard loyalty against Asian mill competition. Production concentrates in Belgium, India, and Japan, with seven European groups controlling premium-grade strand output for cable-stayed applications. Feedstock draws from electric-arc furnace billet and high-carbon wire rod supply. Single-source vulnerability runs through concentrated drawing capacity for 15.2mm and 15.7mm bridge strand grades. Distribution runs through mill-direct relationships for infrastructure and precast segments, with wholesale distributors serving intermittent construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as India's National Highways Authority and Indonesia's Waskita Karya consolidate procurement through build-operate-transfer contracts, fragmenting supplier access for unintegrated mills.
For Market Incumbents: Insulate premium positioning through captive high-carbon wire rod supply and simultaneous ASTM A416, EN 10138, and GB/T 5224 pre-certification to capture compressed Southeast Asian bridge tender timelines. Backward integration into electric-arc furnace billet production defends margin structure against scrap-price volatility. JIS G 3536 low-relaxation capability locks in Japanese seismic retrofit replacement cycles. For New Entrants and Emerging Players: Pursue Vietnam's North-South Expressway Phase 2 and Van Phong port corridor where uncontracted demand for 15.2mm strand outruns established supplier certification capacity. Specialist stressing subcontractor certification offers service-layer entry before mill-scale investment. Partner with Ho Chi Minh City precast yards to bypass direct infrastructure tender barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors billet-integrated mills with multi-certification portfolios over standalone wire-drawing specialists. Long-term viability rests on carbon-embodied procurement alignment with EU Green Deal thresholds. Mills with ISO 14064-verified production and electric-arc furnace supply represent acquisition targets. Watch for REACH substance enforcement tightening lubricant traceability as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Certification Pre-Qualification | Parallel ASTM A416, EN 10138, and GB/T 5224 testing unlocks Vietnam and Indonesia bridge tenders. |
| Backward Integration into Billet Supply | Captive high-carbon wire rod production buffers margin compression from ferrous scrap volatility. |
| Carbon-Verification Investment | ISO 14064-aligned output qualifies for EU Green Deal construction thresholds in German tenders. |
| Regional Stressing Network Buildout | Certified subcontractor relationships satisfy India's split-procurement model for turnkey eligibility. |
| Duplex Corrosion-Protection Scale-Up | Galvanized-waxed strand coating lines capture Rotterdam and Singapore port authority specifications. |
Research Approach
Cross-validation between trade association capacity data and customs shipment records anchors the qualitative findings from primary engagement with bridge procurement officers, precast yard operations managers, wire-drawing plant engineers, and post-tensioning specialist contractors. Secondary sources include ASTM and EN standard documentation, BIS and METI regulatory filings, SEC 10-K disclosures from listed steel producers, and project development databases for Southeast Asian infrastructure pipelines. Bottom-up strand consumption estimates from individual bridge and highway projects triangulate against top-down steel industry shipment data.
Calibration against historical certification timeline patterns and scrap-steel price elasticity informs the analytical framework across the projection horizon. Segmentation dimensions span product form, end-use category, application type, and distribution channel, with additional modeling of certification-grade tier and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs include build-operate-transfer contract pipeline visibility and seismic retrofit mandate enforcement schedules.
Sensitivities concentrate around multi-certification lead time extensions, scrap-steel price spike magnitude, and REACH substance restriction scope expansion. Forecasts embed assumptions on infrastructure privatization continuity and carbon-embodied procurement threshold adoption. Macroeconomic construction cycle deviation, regulatory enforcement intensity variation, or metallurgical sensor technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
PU Waterstops Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
GCC Ceramic Tiles Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
Asia-Pacific Ready-Mix Concrete Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Blanket Insulation Market