
 Pipe Hanger Market | 2026-2036
Pipe Hanger Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Hanger Market Analytics
Modular prefabrication of mechanical rooms is reconfiguring how pipe hanger assemblies are specified, with contractors now ordering pre-engineered support kits rather than field-fabricating individual components. Eaton (B-Line) leverages its integrated electrical and mechanical infrastructure portfolio to bundle hanger systems with cable management for data center clients. LISEGA SE anchors its position through deep specialization in constant-load spring hangers for thermal power plants. Anvil International competes across commodity and engineered tiers with broad distribution through industrial supply houses.
Pipe hangers are load-bearing devices designed to suspend, guide, or anchor piping systems while accommodating thermal expansion, vibration, and seismic forces, typically fabricated from carbon steel, stainless steel, or engineered polymers with load ratings from 50 to 100,000 pounds. Their primary purpose is to maintain pipe alignment and structural integrity across commercial, industrial, and infrastructure applications. Rigid hangers dominate in plumbing and standard HVAC installations where thermal movement is minimal and cost sensitivity is acute. Spring hangers command premium positioning in power generation and petrochemical settings where thermal cycling demands dynamic load compensation. Stainless steel material selection is gaining share in wastewater management and coastal HVAC applications where chloride exposure accelerates carbon steel corrosion.
OSHA fall-protection standards and the International Plumbing Code shape installation practices for suspended and ceiling-mounted systems in US commercial construction. The EU Construction Products Regulation and CE marking requirements govern structural steel hanger performance declarations for European infrastructure tenders. EPA stormwater and corrosion-control mandates indirectly drive material specification toward coated and alloy hangers in US wastewater applications. Stakeholders must monitor how evolving seismic design codes in California and Japan redefine load-rating thresholds for critical facility installations.
Market Dynamics
Modular prefabrication of mechanical rooms is compressing specification cycles, forcing contractors to abandon field-fabricated hangers for pre-engineered support kits that arrive ready for drop-in installation. This structural shift toward offsite assembly is redistributing margin from installation labor to manufacturing precision.
Growth Catalysts
- EU F-Gas Regulation:Mandates for low-global-warming-potential refrigerants in commercial HVAC systems are accelerating demand for vibration-isolated hanger hardware that protects sensitive refrigerant lines from fatigue failure.
- Coastal HVAC retrofit wave:Chloride-induced corrosion in Florida, California, and Gulf Coast states is driving specification of stainless steel hangers where carbon steel previously dominated.
- Seismic code tightening:California's updated structural safety requirements for critical facilities are elevating load-rating thresholds and expanding the addressable market for engineered spring hangers.
Market Restraints
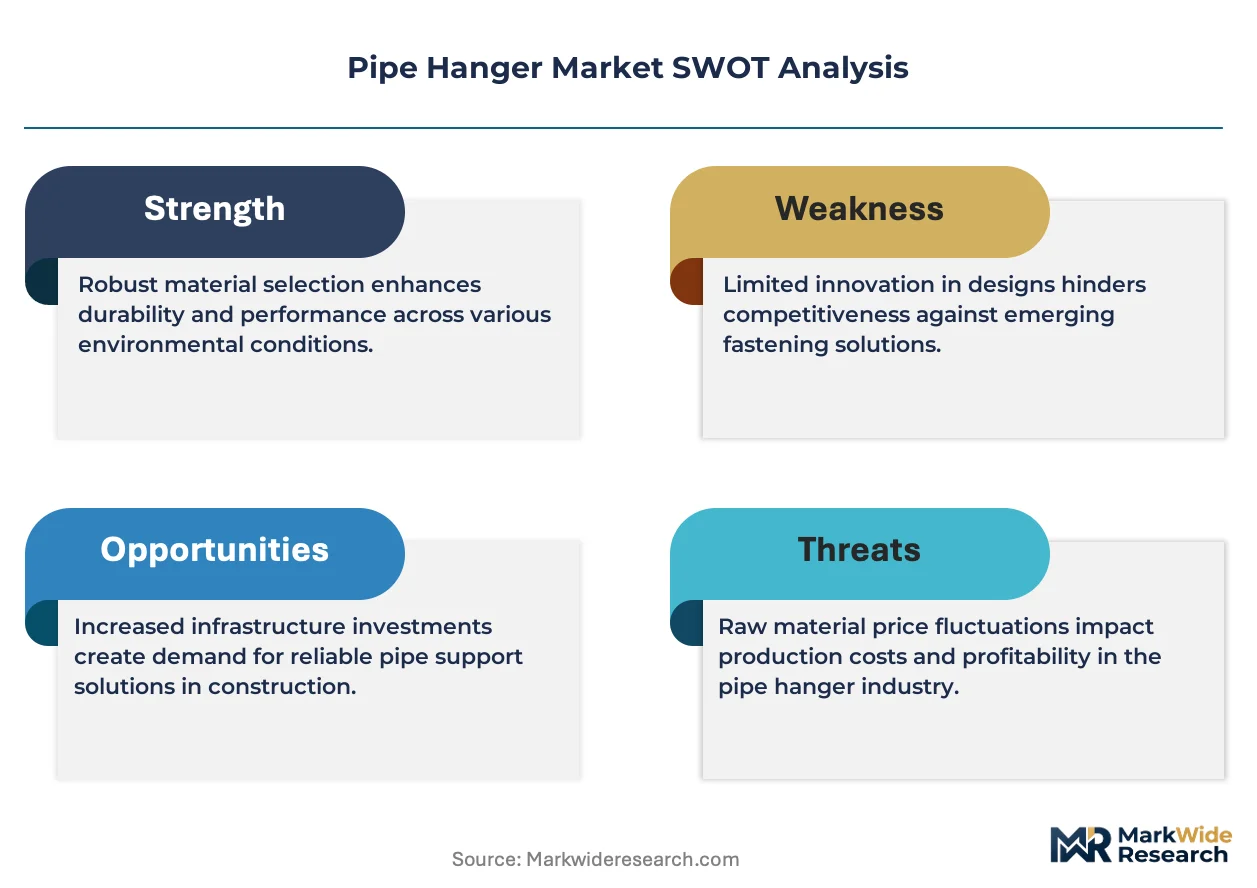
- Steel price volatility:Fluctuations in hot-rolled coil and stainless scrap input costs compress fabricator margins and destabilize project bidding.
- Commodity hanger oversupply:Concentrated production of low-cost rigid hangers in certain Asian manufacturing zones is depressing pricing power for standard product lines.
- Polymer substitution ceiling:Engineered polymer hangers face load-rating limitations above 10,000 pounds that restrict penetration into heavy industrial applications.
Strategic Opportunities
- Data center construction surge:Hyperscale facility builds in Northern Virginia, Frankfurt, and Singapore are creating demand for integrated mechanical-electrical support systems that bundle pipe hangers with cable management infrastructure.
- Wastewater infrastructure renewal:EPA corrosion-control mandates are opening specification pathways for coated and alloy hangers in municipal treatment plant upgrades.
- Spring hanger retrofit backlog:Aging thermal power plants across the US Midwest and Germany require replacement of constant-load spring assemblies, creating a service-attached revenue stream.
Industry Challenges
- Seismic certification complexity:Obtaining ICC-ESR or OSHPD approval for new hanger designs requires 18-24 month test cycles that delay product launches.
- Skilled installer shortage:Pipefitting trades face demographic contraction in North America and Western Europe, constraining field execution capacity for complex spring hanger installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Hanger Market |
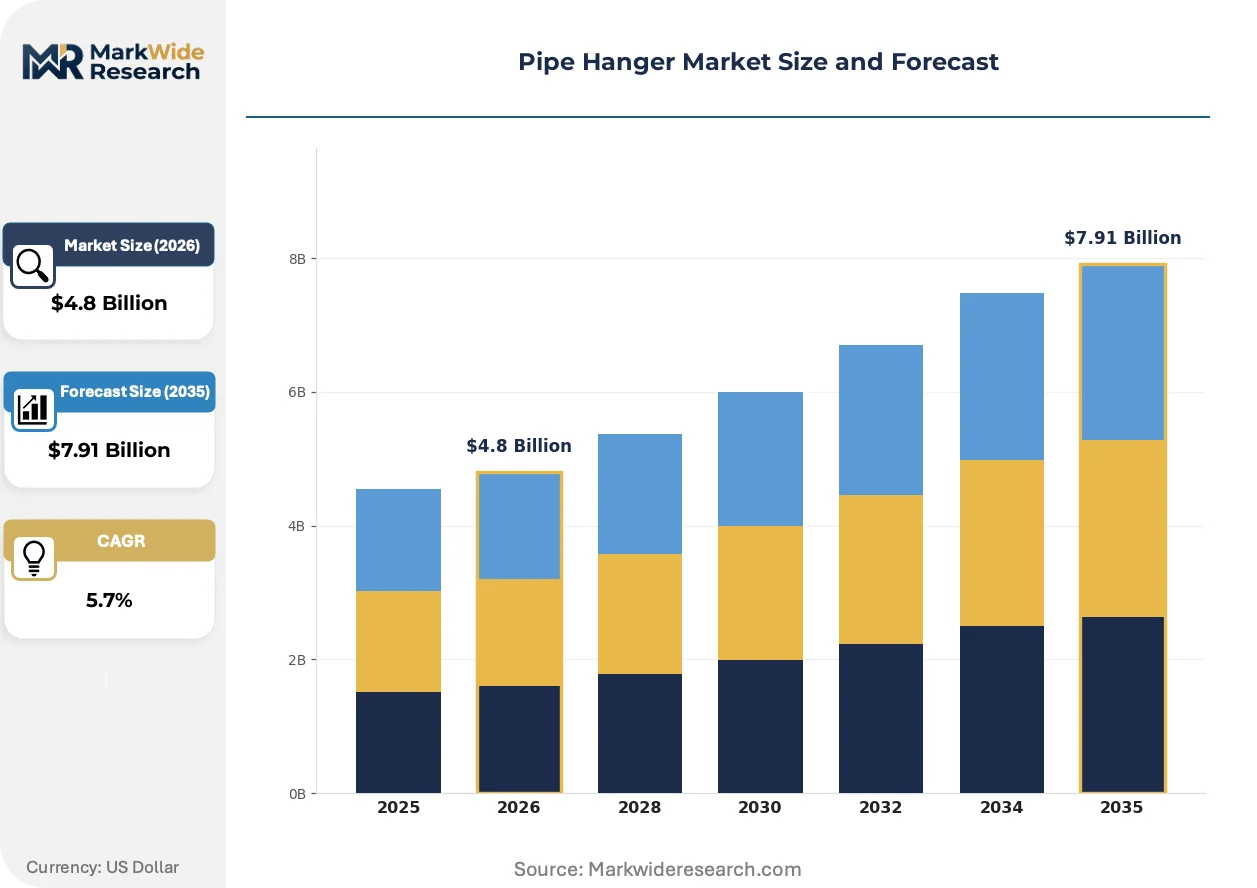
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Hangers, Rigid Hangers, Adjustable Hangers, Strut Hangars Material: Steel, Stainless Steel, Plastic, Alloy Application: Heating Systems, Plumbing, HVAC, Wastewater Management Installation Type: Suspended, Wall-mounted, Ceiling-mounted, Floor-mounted |
| Companies Covered | Eaton (B-Line), LISEGA SE, Anvil International, Globe Pipe Hanger Products, Hill & Smith Holdings, Piping Technology & Products, Rilco Manufacturing Company, PHD Manufacturing, Witzenmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Hanger Market Evolving Landscape
Digital specification tools and predictive load-modeling software are displacing manual engineering calculations, compressing design cycles from weeks to days. Material science advances and regulatory pressure on refrigerant systems are simultaneously reshaping product portfolios and procurement criteria.
Composite-reinforced polymer hangers with embedded fiber sensors are rendering obsolete traditional inspection-dependent maintenance schedules for critical piping. Offshore petrochemical operators in the North Sea and Gulf of Mexico are piloting these smart hangers for real-time load monitoring. The technology is rendering obsolete the historical reliance on visual inspection and scheduled replacement cycles.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is mandating hardware compatibility with lower-pressure, higher-volume refrigerant lines. Heating system contractors across Germany, France, and the Netherlands are retrofitting support infrastructure to accommodate larger-diameter piping. Vibration-isolated hanger specifications are expanding fastest in supermarket and cold-storage applications where CO2 transcritical systems dominate new builds.
Mechanical contractors are consolidating supplier relationships around single-source pre-engineered support kit providers. General contractors on data center and healthcare projects are eliminating fragmented procurement of individual hanger components in favor of bundled mechanical room packages. This concentration is most visible in Texas, Arizona, and Northern Virginia where hyperscale construction timelines compress vendor qualification windows to 30 days or less.
Pipe Hanger Market Segmentation
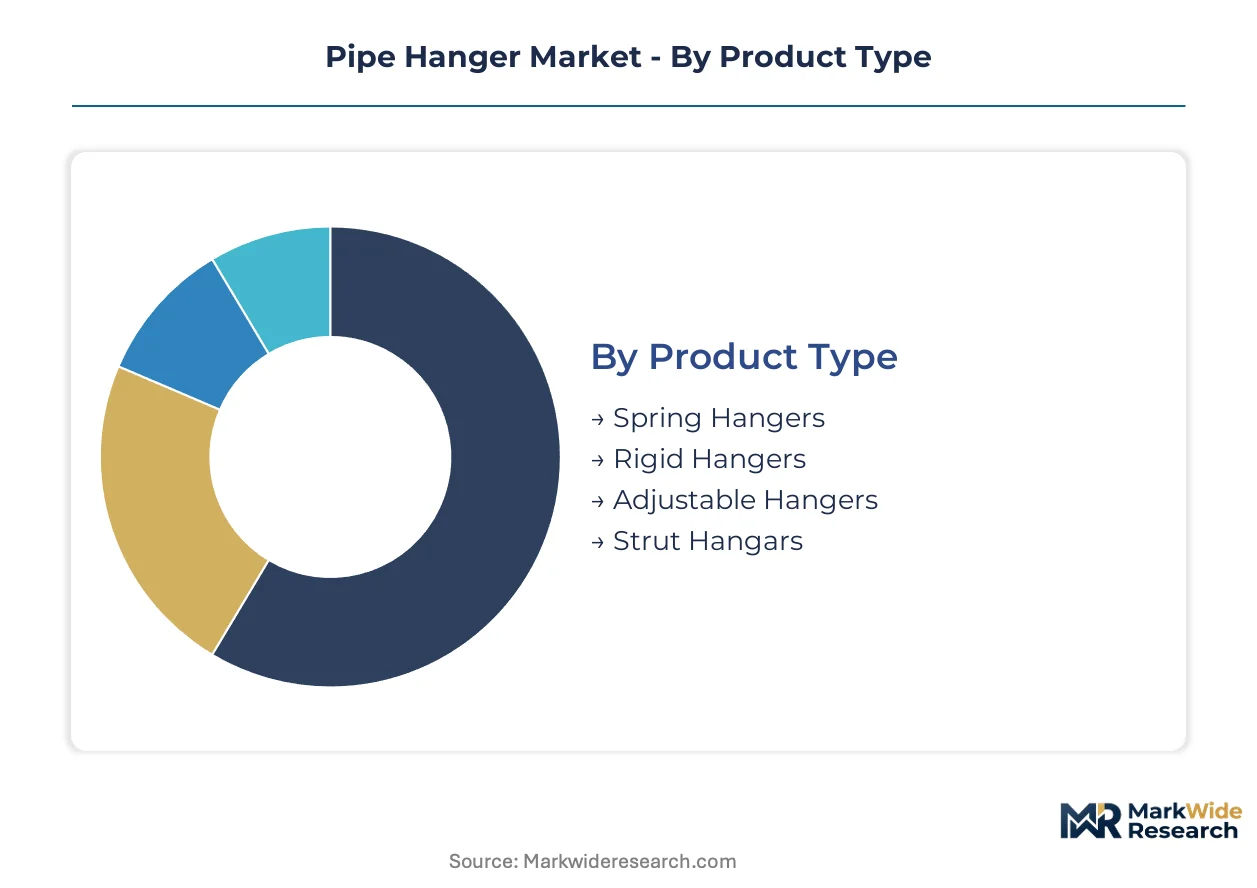
Pipe hanger specification diverges sharply across thermal cycling intensity, corrosion exposure, and seismic loading requirements. Contractors align product selection with project risk profiles rather than defaulting to lowest-cost alternatives.
Product Type:
Cost tier separates commodity rigid hardware from engineered dynamic support systems with load-compensation mechanisms.
- Spring Hangers:These constant-load and variable-spring assemblies accommodate thermal expansion through calibrated coil mechanisms rated to 100,000 pounds. Demand concentrates in German thermal power plants and US Midwest utilities where aging infrastructure requires replacement of fatigue-degraded constant-load assemblies. The EU F-Gas Regulation's refrigerant line retrofit mandates are accelerating specification of vibration-isolated spring hardware for sensitive CO2 systems.
- Rigid Hangers:Fixed-support devices fabricated from carbon steel or iron provide static load bearing without movement accommodation. Plumbing contractors in Florida and California specify these for standard drainage lines where thermal movement is minimal and cost sensitivity dominates procurement decisions.
- Adjustable Hangers:Threaded rod and clevis assemblies permit field height modification during installation. These dominate commercial HVAC rough-in work where ceiling plenum conditions vary unpredictably.
- Strut Hangers:Channel-based support systems integrate with modular framing for multi-line pipe racks. Data center contractors in Northern Virginia bundle these with cable management infrastructure for mechanical room prefabrication.
Spring hangers command the established base in heavy industrial procurement. The steepest expansion runs through rigid hangers as coastal corrosion drives stainless steel substitution in standard HVAC applications.
Material:
Application environment dictates material selection, with chloride exposure and seismic risk elevating alloy specifications above commodity carbon steel.
- Steel:Hot-rolled and cold-formed carbon steel dominates standard commercial construction through cost efficiency and established fabrication infrastructure. General contractors specify these for interior plumbing and dry-environment HVAC where corrosion risk is minimal.
- Stainless Steel:Austenitic grades 304 and 316 resist chloride-induced pitting in wastewater treatment plants and coastal HVAC installations. Municipal procurement in Florida and California now mandates these for outdoor and below-grade applications.
- Plastic:Glass-reinforced polymer hangers serve light-duty plumbing and corrosive chemical drainage where metallic corrosion accelerates failure. Load ratings above 10,000 pounds restrict penetration into industrial process piping.
- Alloy:Specialized formulations including galvanized and epoxy-coated steel bridge cost and corrosion resistance for moderate exposure conditions. EPA stormwater mandates are elevating specification in US municipal infrastructure.
Steel maintains volume leadership across standard construction. Stainless steel is climbing fastest as coastal retrofit programs and wastewater corrosion mandates reshape material procurement.
Application:
End-use thermal cycling intensity and regulatory exposure separate commodity plumbing from engineered power generation specification.
- Heating Systems:Boiler and furnace piping demands vibration-isolated support to protect soldered and press-fit connections from mechanical fatigue. Residential and light commercial contractors specify spring-isolated hangers for hydronic distribution headers.
- Plumbing:Drainage, waste, and vent systems utilize rigid hangers with minimal dynamic loading requirements. This segment concentrates in multi-family residential and standard commercial construction with compressed procurement cycles.
- HVAC:Refrigerant lines and chilled water distribution require load-rated support with thermal movement accommodation. The EU F-Gas Regulation's low-GWP refrigerant transition is expanding hanger specifications for larger-diameter CO2 and ammonia lines.
- Wastewater Management:Municipal treatment plants and industrial effluent systems demand corrosion-resistant alloys and coated hangers. EPA corrosion-control mandates are accelerating specification of stainless and specialty alloy hardware in US facility upgrades.
HVAC commands the established specification base. Wastewater management is gaining share fastest as infrastructure renewal programs and environmental compliance tighten material requirements.
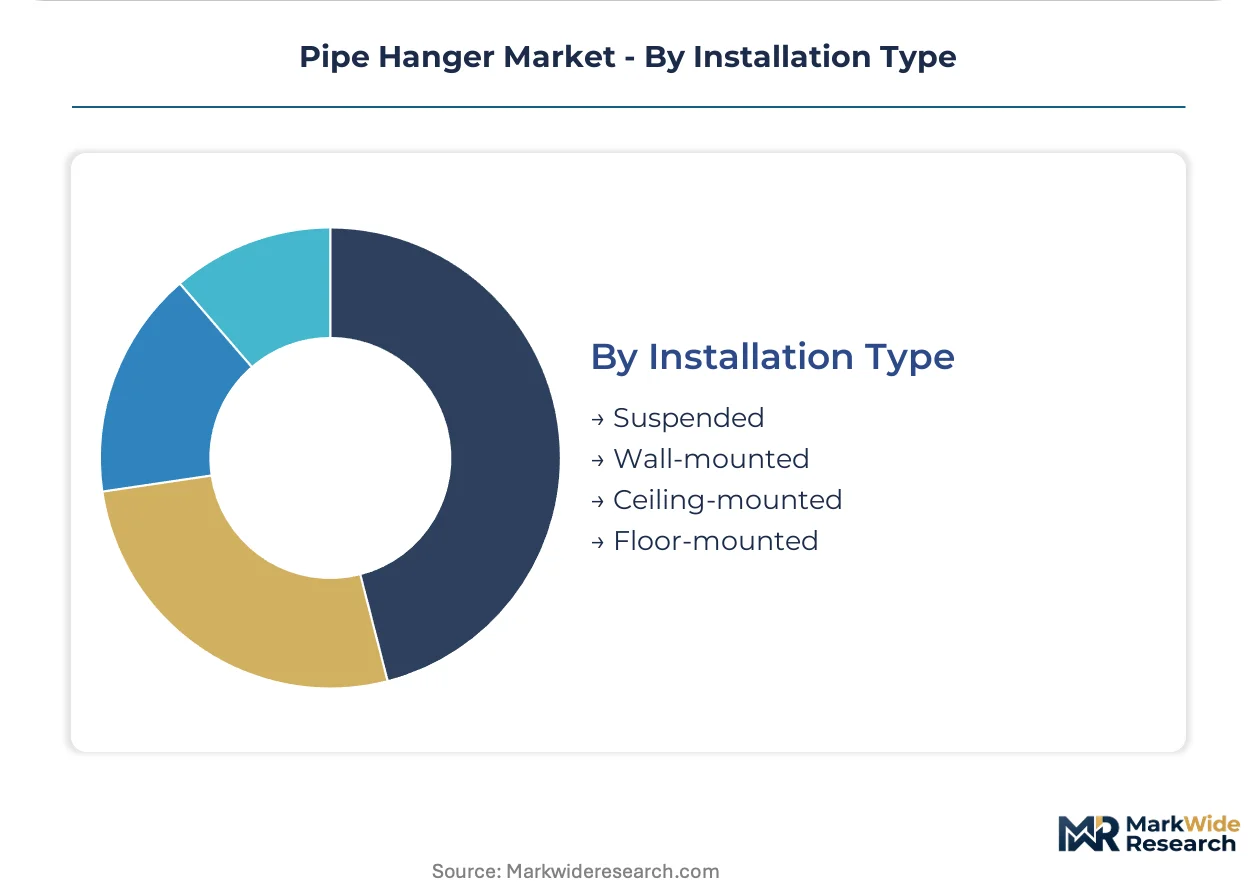
Installation Type:
Structural attachment geometry determines load path engineering and seismic certification requirements.
- Suspended:Rod-hung assemblies from overhead structure dominate commercial building mechanical rooms and ceiling plenums. OSHA fall-protection standards govern installation practices in US commercial construction.
- Wall-mounted:Bracket and clamp systems secure horizontal piping runs along building envelopes and shaft walls. These concentrate in industrial process piping and exterior mechanical installations.
- Ceiling-mounted:Direct-to-deck fasteners and structural attachments serve high-bay manufacturing and warehouse facilities with exposed overhead structure. Seismic bracing requirements elevate engineering scrutiny in California critical facilities.
- Floor-mounted:Pipe stands and base supports anchor large-diameter and high-load piping where overhead suspension is impractical. Power plant boiler feed lines and petrochemical process headers utilize these for concentrated load distribution.
Suspended installation commands the established base in commercial building stock. Ceiling-mounted specification is expanding most quickly as seismic code tightening elevates engineered attachment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power plant operators, data center developers, and municipal wastewater authorities concentrate procurement across five national markets where infrastructure codes and corrosion exposure dictate material specification.
United States
Data center construction in Northern Virginia and seismic upgrades across California drive specification of engineered spring hangers and stainless steel rigid assemblies. EPA corrosion-control mandates for wastewater treatment plants elevate alloy procurement in Florida and Gulf Coast states. Chicago anchors Midwest demand through aging thermal power plant retrofit programs.
Germany
Thermal power plant maintenance and EU F-Gas Regulation compliance accelerate replacement of constant-load spring hangers and vibration-isolated refrigerant line supports. LISEGA SE and Witzenmann anchor a dense engineering cluster serving chemical and energy infrastructure. The Rhine-Ruhr industrial corridor concentrates specification for petrochemical process piping.
China
Hyperscale data center builds in Beijing-Tianjin-Hebei and Yangtze River Delta cities compress procurement cycles for pre-engineered support kits. National GB standards for seismic design elevate load-rating requirements in critical facilities. Shenzhen manufacturing zones supply commodity rigid hangers for domestic construction and export markets.
Japan
Updated seismic design codes following recent structural safety reviews expand demand for certified spring hangers in Tokyo and Osaka critical infrastructure. METI efficiency standards for commercial buildings drive HVAC system retrofits requiring vibration-isolated refrigerant line supports. Nagoya industrial corridors maintain specification for heavy-load process piping hardware.
India
Municipal wastewater infrastructure expansion under national cleanliness programs elevates stainless steel hanger procurement in Maharashtra and Gujarat. Commercial HVAC installation accelerates in Bangalore and Hyderabad technology corridors. Central Electricity Authority grid reliability mandates support power plant piping upgrade programs.
Pipe Hanger Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions defined by load-rating capability and certification depth. The vendor base separates into three strategic archetypes: integrated infrastructure conglomerates bundling mechanical-electrical systems, dedicated spring hanger engineers serving power generation, and commodity fabricators competing on carbon steel volume. Dominant competitive moves include consolidation of supplier relationships by mechanical contractors and backward integration into pre-engineered kit manufacturing.
Among Germany-based engineering specialists, LISEGA SE and Witzenmann exemplify the deep-specialization archetype in constant-load spring technology. Eaton (B-Line) occupies a position as an integrated infrastructure provider leveraging electrical-mechanical bundling for data center and commercial clients. Anvil International represents the broad-portfolio competitor spanning commodity rigid hangers through engineered dynamic supports.
| Leading Market Players |
|---|
| Eaton (B-Line) |
| LISEGA SE |
| Anvil International |
| Globe Pipe Hanger Products |
| Hill & Smith Holdings |
| Piping Technology & Products |
| Rilco Manufacturing Company |
| PHD Manufacturing |
| Witzenmann |
| Others |
Value Network & Pricing Analysis
Shenzhen's concentrated fabrication capacity for commodity rigid hangers exerts gravitational pull on global spot pricing, compressing margins for carbon steel fabricators in North America and Europe while amplifying procurement leverage for large mechanical contractors.
Pricing Analysis
Cost-plus contracts with hot-rolled coil indexation dominate procurement for engineered spring hangers serving power generation clients. Three-tier pricing structure across premium, standard, and economy levels separates seismic-certified constant-load assemblies from commodity rigid hardware and import-grade carbon steel clevis hangers. Price differentiation hinges on ICC-ESR certification tier and volume scale, with bulk purchasers of pre-engineered support kits commanding favorable terms. Cost compression in standard rigid hangers is intensifying because concentrated Asian manufacturing capacity floods export markets. Plumbing contractors in Florida and California exhibit acute price sensitivity, while data center developers prioritize performance over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard operating practice among distributors serving mechanical contractors, with 90-day cycles now routine for qualified buyers. Manufacturing concentrates in China, India, and Germany, with Shenzhen and Ningbo anchoring commodity rigid hanger output while LISEGA SE and Witzenmann retain engineered spring assembly production in Germany. Raw material inputs draw from hot-rolled carbon steel coil, austenitic stainless steel scrap, and glass-reinforced polymer resins. Single-source vulnerability around specialized constant-load spring mechanisms sourced from German engineering clusters presents structural risk. Distribution runs through industrial supply houses and direct contractor relationships, with pre-engineered kit bundling displacing fragmented component procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified seismic engineering capability and ICC-ESR approval pathways constitute the critical scarcity in this market, constraining expansion by fabricators lacking test infrastructure or regulatory relationships.
For Market Incumbents: Build certification moats by accelerating ICC-ESR and OSHPD approval pipelines for next-generation vibration-isolated hanger designs. Expand captive testing laboratory capacity to compress 18-24 month certification cycles. Defend against polymer substitution threats by elevating load ratings on composite-reinforced offerings. Channel control through exclusive pre-engineered kit partnerships with top-10 mechanical contractors anchors recurring revenue streams. For New Entrants and Emerging Players: Pursue white-space opportunities in smart hanger systems with embedded fiber sensors for offshore petrochemical monitoring applications. Target municipal wastewater infrastructure renewal in Florida and California where EPA corrosion-control mandates open specification pathways for stainless steel and coated alloy entrants. Penetrate through aftermarket service contracts for aging constant-load spring replacement in US Midwest thermal power plants rather than competing on original equipment specification. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-maintenance play because thermal power plant retrofit backlogs and coastal HVAC corrosion cycles generate sustained replacement demand regardless of new construction cyclicality. Acquisition targets should display vertical integration into pre-engineered kit manufacturing and established contractor bundling relationships. Monitor seismic code adoption velocity in California and Japan as the critical inflection signal for engineered hanger demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Certification Acceleration | ICC-ESR approval compression from 24 to 12 months captures specification windows on California critical facilities. |
| Pre-Engineered Kit Manufacturing | Backward integration into modular mechanical room packages secures contractor consolidation trends in Northern Virginia data center construction. |
| Smart Hanger Sensor Integration | Embedded fiber load-monitoring technology displaces scheduled inspection cycles for North Sea offshore operators. |
| Stainless Steel Capacity Expansion | Domestic 316-grade fabrication capability hedges against chloride-driven coastal HVAC retrofit demand surges. |
| Aftermarket Service Contracting | Constant-load spring replacement programs in German thermal power plants generate recurring revenue independent of new build cycles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with mechanical contractors, power plant maintenance directors, municipal wastewater procurement officers, and HVAC specification engineers. Secondary validation drew from EPA corrosion-control mandate filings, EU F-Gas Regulation implementation reports, ICC-ESR certification databases, and industrial supply house transaction records. Bottom-up project pipeline enumeration triangulated against top-down construction spend forecasts to anchor volume estimates.
Calibration against historical specification patterns and verified installation data refined the analytical framework across the analysis window. Segmentation modeling incorporated product type, material grade, application thermal cycling intensity, and regional regulatory cluster dimensions. CAGRs were derived from regression analysis of correlated construction and infrastructure maintenance indicators, with specific inputs including data center capex disclosures and thermal power plant retirement schedules.
Sensitivities concentrate around steel price volatility, seismic code adoption timing, and EU refrigerant transition velocity. Forecasts reflect documented assumptions regarding contractor prefabrication adoption rates and skilled installer availability. Macroeconomic construction downturns, accelerated polymer substitution breakthroughs, or regulatory delays in seismic certification requirements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Limestone Aggregates Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Construction Sustainable Materials Market