
 Global Wooden Formwork Systems Market | 2026-2036
Global Wooden Formwork Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wooden Formwork Systems Market Foresight
The gap between premium engineered formwork and commodity timber products is expanding across construction supply chains. Doka leverages its vertical integration to control laminated veneer lumber quality from forest to site. PERI sustains technology leadership through proprietary panel-locking systems that reduce labor hours on complex geometries.
Wooden formwork systems are temporary molds fabricated from timber, plywood, or engineered wood composites, typically rated for 50-200 reuse cycles depending on surface treatment and framing design; they shape poured concrete until it achieves structural strength. Panel formwork dominates commercial building applications where standardized wall sections justify capital investment in reusable systems, while customized formwork commands premium pricing in institutional facilities with non-standard architectural elements. Traditional timber technology still anchors infrastructure projects in cost-sensitive markets, though laminated veneer lumber is displacing solid sawn timber in markets where transport weight and dimensional stability carry value.
REACH in Europe restricts preservative chemistry in export-grade plywood, while China's GB standards mandate load-testing protocols for finger-jointed structural members. The US EPA and OSHA jointly influence jobsite exposure limits for formaldehyde emissions from blockboard adhesives, pushing suppliers toward low-emission binders. Stakeholders must monitor how building code harmonization between ISO timber standards and national regulations reshapes cross-border equipment certification requirements.
Market Dynamics
REACH compliance costs and laminated veneer lumber supply constraints are compressing margins for commodity plywood suppliers while rewarding engineered wood specialists with captive forestry assets.
Growth Catalysts
- Urbanization in emerging economies:Residential tower construction in India and Brazil consumes prefabricated panel systems as labor costs rise. Municipal housing mandates in São Paulo and Mumbai specify reusable formwork for projects exceeding 15 stories.
- EU Green Deal traceability requirements:Chain-of-custody certification for timber imports is redirecting procurement toward FSC-compliant Baltic and Nordic suppliers. Construction firms in Germany and France now require digital material passports for concrete formwork.
- Engineered wood performance advantages:Laminated veneer lumber delivers dimensional stability across humidity cycles that degrade solid sawn timber. Infrastructure contractors in Southeast Asia specify LVL for bridge piers where precision tolerances govern structural integrity.
Market Restraints
- Baltic birch plywood supply concentration:Russian forest access restrictions have compressed available veneer feedstock for high-cycle formwork surfaces. Finnish and Estonian mills now control 70% of export-grade marine plywood capacity.
- Steel and aluminum formwork substitution:Modular metal systems achieve 500+ reuse cycles versus 50-200 for timber. Chinese state-owned contractors in high-rise commercial segments are standardizing on aluminum table-form systems.
- Preservative chemistry restrictions:REACH Annex XVII limits on creosote and CCA treatments are forcing reformulation of tropical hardwood alternatives. Export-oriented plywood mills face 18-month re-certification timelines for EU market access.
Strategic Opportunities
- Modular housing in Vietnam and Indonesia:Prefabricated concrete component factories require standardized formwork systems with rapid-change panel interfaces. Domestic timber processing clusters near Ho Chi Minh City and Jakarta lack engineered wood finishing capacity.
- US Inflation Reduction Act green construction incentives:Tax credits for low-carbon building materials are creating preference for mass timber formwork with verified embodied carbon calculations. General contractors in California and Washington state are piloting digital carbon tracking for temporary works.
- Rental and service model expansion:Equipment leasing platforms are bundling formwork supply with logistics and on-site technical support. This model penetrates mid-tier contractors in Poland and Czech Republic who lack capital for owned inventory.
Industry Challenges
- Skilled carpentry workforce scarcity:Traditional timber formwork assembly requires craft knowledge that construction training programs no longer emphasize. German and Austrian vocational pipelines produce fewer qualified formwork technicians annually.
- ISO timber standard harmonization delays:Divergent load-testing protocols between European EN codes and Chinese GB standards complicate cross-border equipment certification. Manufacturers serving multiple markets face redundant engineering validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wooden Formwork Systems Market |
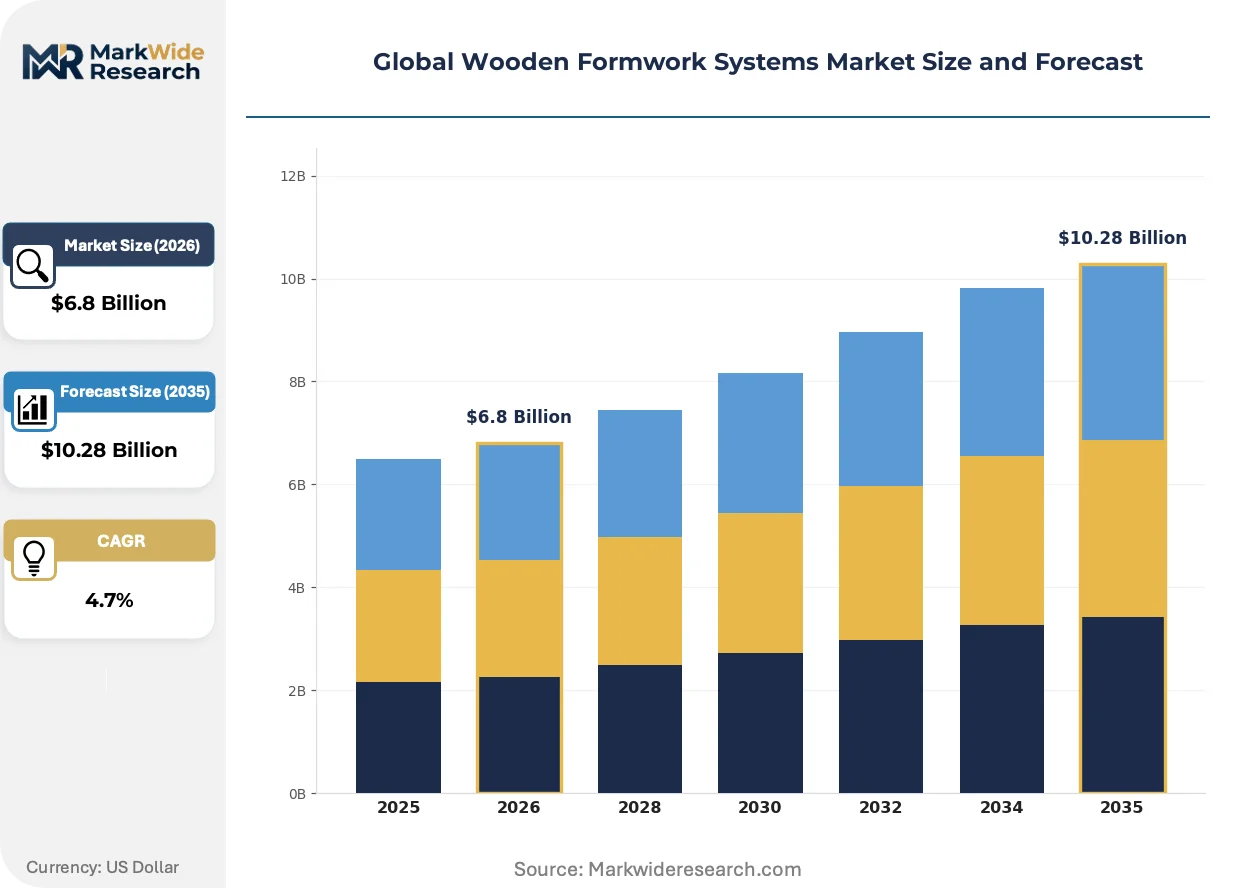
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Formwork, Beam Formwork, Slab Formwork, Column Formwork, Customized Formwork Technology: Traditional Timber, Laminated Veneer Lumber, Plywood, Finger Jointed Timber, Blockboard Application: Residential Construction, Commercial Buildings, Infrastructure Projects, Institutional Facilities End User: General Contractors, Formwork Suppliers, Construction Companies, Engineering Firms |
| Companies Covered | Doka, PERI, ULMA, Acrow, The Heico Companies LLC, Outinord, MFE Formwork Technology Sdn.Bhd, Urtim Formwork and Scaffolding Systems, Waco International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wooden Formwork Systems Market Shifts & Advancements
Digital fabrication and regulatory chemistry constraints are transforming how formwork systems are designed, certified, and deployed across project sites.
Robotic CNC milling of engineered wood formwork components is automating panel production for complex architectural geometries. Bridge and stadium contractors in Switzerland and Japan are adopting machine-cut LVL elements that reduce on-site adjustment labor by half. This automation compresses project timelines for institutional clients with non-standard concrete finishes.
REACH authorization requirements for formaldehyde-emitting adhesives are accelerating migration to bio-based binders in plywood manufacturing. Finnish chemical suppliers have commercialized lignin-derived resins that meet EN 13986 structural standards without petrochemical inputs. Panel producers serving Nordic markets are retrofitting press lines to handle these alternative curing chemistries.
Buyers are consolidating procurement through integrated construction service platforms that bundle formwork with concrete supply and pumping logistics. Mid-size contractors in Australia and South Korea are abandoning traditional equipment distributors for direct mill relationships with technical support attachments. This channel compression is most visible in commercial high-rise segments where project timelines penalize coordination friction between multiple vendors.
Global Wooden Formwork Systems Market Segmentation
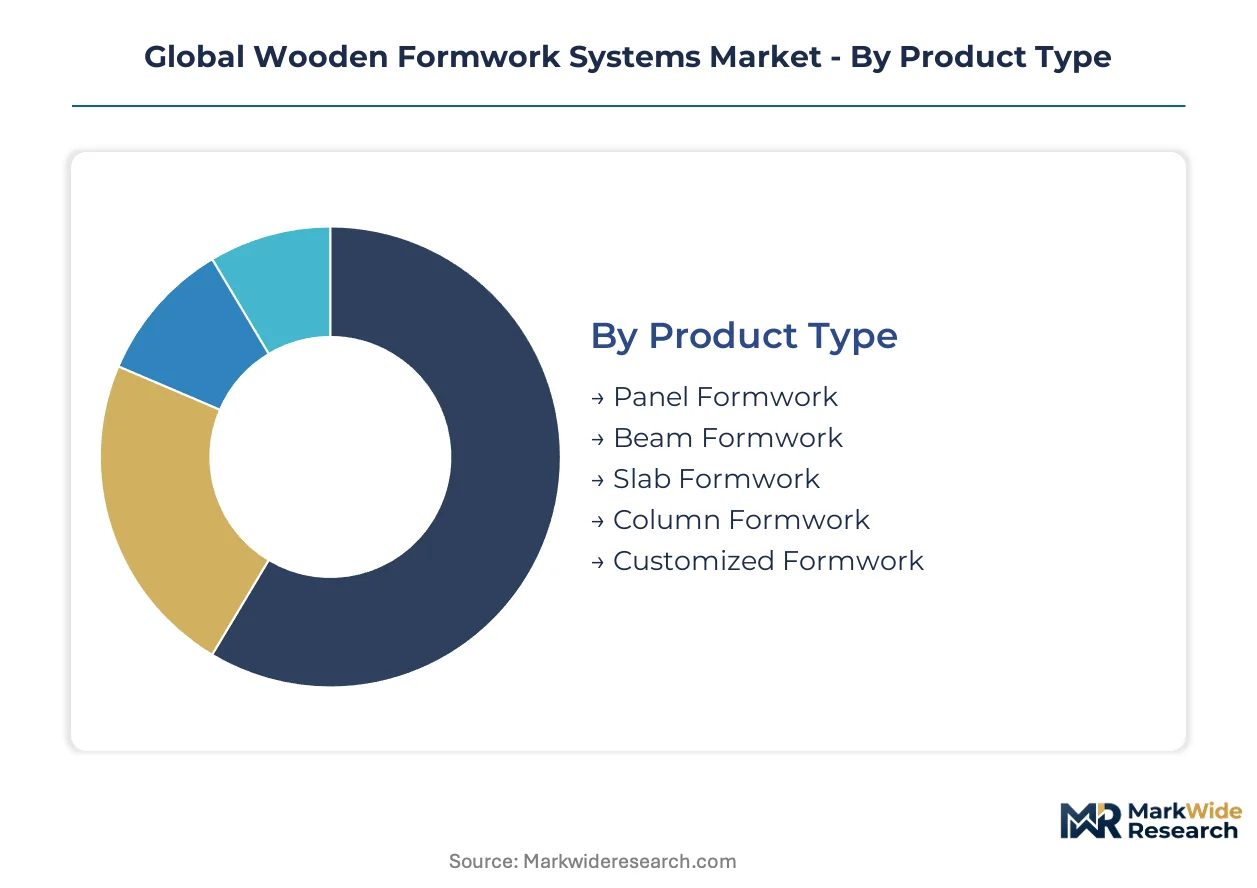
Segmentation in wooden formwork systems reveals how procurement patterns split between capital-intensive reusable systems and project-specific fabricated molds. Understanding these divides exposes where margin pools concentrate and which technology transitions reshape supplier economics.
Product Type:
Customization versus standardization tension runs deepest here, with reusable panel systems commanding premium pricing against single-use fabricated solutions.
- Panel Formwork:Modular plywood or engineered wood panels with steel or aluminum framing, rated for 100-200 reuse cycles with proper surface treatment. Demand concentrates in German and French commercial high-rise construction where municipal codes mandate reusable systems for projects exceeding 12 stories.
- Customized Formwork:Site-fabricated timber molds engineered for non-standard geometries, typically achieving 15-50 cycles depending on complexity. Institutional clients in Switzerland and Japan specify these for stadium and museum projects where architectural concrete finishes require unique shapes.
- Beam Formwork:Timber or LVL joist systems supporting horizontal concrete members.
- Slab Formwork:Table or prop-based systems for floor deck pours.
- Column Formwork:Circular or rectangular molds for vertical structural elements.
Leading the category by volume: Panel Formwork. Expanding most quickly: Customized Formwork.
Technology:
Cost tier stratification separates commodity timber from engineered alternatives where dimensional stability justifies material premiums.
- Laminated Veneer Lumber:Rotary-peeled veneer layers bonded with phenolic resins, delivering uniform strength and moisture resistance across 50-100 cycles. Infrastructure contractors in Vietnam and Indonesia specify LVL for bridge piers where precision tolerances govern structural integrity.
- Traditional Timber:Solid sawn lumber from softwood species, still anchoring cost-sensitive markets despite dimensional variability. Brazilian and Indian residential contractors rely on pine and eucalyptus framing for low-rise housing where labor costs offset material inefficiency.
- Plywood:Cross-laminated veneer construction for high-cycle surface applications.
- Finger Jointed Timber:Spliced short lumber sections for extended spans.
- Blockboard:Core-veneer construction with edge-glued strips for dimensional stability.
Volume leader: Traditional Timber. Steepest expansion trajectory: Laminated Veneer Lumber.
Application:
Customer type divides this category, with speculative developers driving standardization against institutional owners demanding bespoke solutions.
- Residential Construction:Tower and mid-rise housing projects consuming prefabricated panel systems as labor costs rise. Municipal housing mandates in São Paulo and Mumbai specify reusable formwork for projects exceeding 15 stories.
- Infrastructure Projects:Bridges, tunnels, and dams where precision tolerances and heavy load cycles dominate material selection. Southeast Asian state contractors specify engineered wood for marine exposure conditions.
- Commercial Buildings:Office and retail developments with repetitive floor plates.
- Institutional Facilities:Schools, hospitals, and government buildings with extended design lifecycles.
Dominant by volume: Residential Construction. Gaining share fastest: Infrastructure Projects.
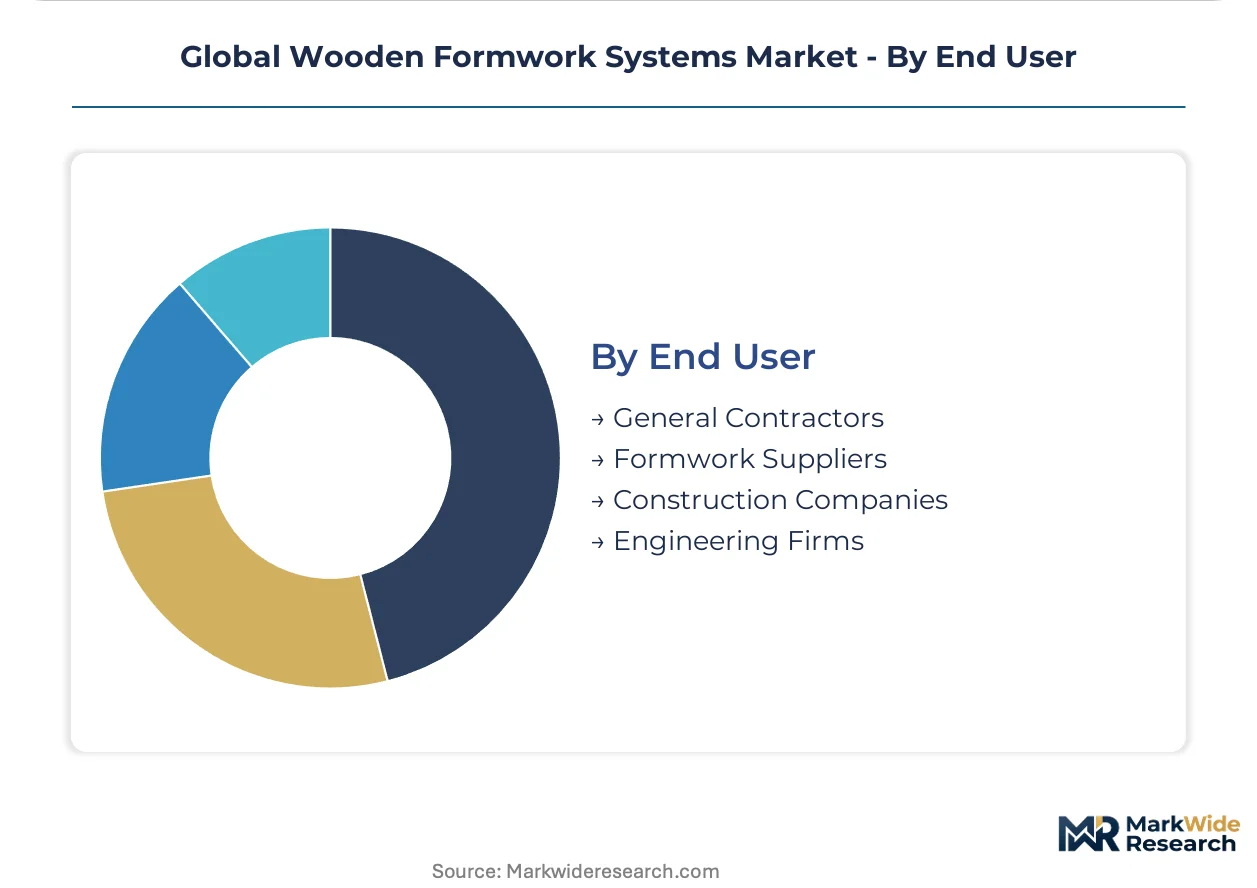
End User:
Supply concentration patterns differentiate capital-owners from rental-dependent buyers across this category.
- General Contractors:Prime construction firms owning or leasing formwork inventory, bundling temporary works into lump-sum bids. Mid-tier Polish and Czech contractors lack capital for owned inventory, driving rental platform penetration.
- Formwork Suppliers:Specialized equipment lessors providing technical support and logistics. Australian and South Korean platforms now bundle formwork with concrete supply and pumping logistics.
- Construction Companies:Integrated builders with in-house fabrication capacity.
- Engineering Firms:Design consultants specifying formwork performance requirements.
Category volume leader: General Contractors. Climbing the fastest: Formwork Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors residential tower construction in Brazil where municipal housing mandates specify reusable formwork for projects exceeding 15 stories. Chinese contractors in Shanghai and Beijing are standardizing on aluminum table-form systems for high-rise commercial segments. German construction firms now require digital material passports for concrete formwork under EU Green Deal traceability requirements.
China
State-owned contractors in Beijing and Shanghai drive standardization toward metal alternatives, though provincial infrastructure projects in Sichuan and Chongqing still specify engineered wood for bridge piers. GB standards mandate load-testing protocols for finger-jointed structural members. Domestic timber processing clusters near Guangzhou lack engineered wood finishing capacity for prefabricated concrete component factories.
Germany
Commercial high-rise construction in Frankfurt and Munich concentrates demand for panel systems rated for 100-200 reuse cycles. REACH and EU Green Deal regulations push chain-of-custody certification toward FSC-compliant Baltic and Nordic suppliers. Bavarian vocational pipelines produce fewer qualified formwork technicians annually, compressing skilled labor availability.
India
Residential tower construction in Mumbai and Delhi-NCR consumes prefabricated panel systems as labor costs rise. Municipal housing mandates in Mumbai specify reusable formwork for projects exceeding 15 stories. Domestic timber framing for low-rise housing in Bangalore and Hyderabad relies on pine and eucalyptus where labor costs offset material inefficiency.
Brazil
São Paulo municipal housing mandates specify reusable formwork for projects exceeding 15 stories, driving panel system adoption. Brazilian residential contractors rely on pine and eucalyptus framing for low-rise housing. Timber processing capacity concentrates in Paraná and Santa Catarina states, though engineered wood finishing remains underdeveloped.
United States
General contractors in California and Washington state pilot digital carbon tracking for temporary works under Inflation Reduction Act green construction incentives. Tax credits for low-carbon building materials create preference for mass timber formwork with verified embodied carbon calculations. Pacific Northwest timber clusters supply laminated veneer lumber for infrastructure precision tolerances.
Global Wooden Formwork Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. Vertically integrated specialists with captive forestry assets capture margin pools in engineered wood segments while commodity plywood suppliers face compressed returns. Three archetypes dominate: integrated equipment lessors bundling logistics and technical support, engineered wood specialists controlling laminated veneer lumber quality from forest to site, and regional timber fabricators serving cost-sensitive infrastructure markets. Consolidation is accelerating through rental platform expansion and backward integration into veneer feedstock.
Among Austrian and German integrated formwork specialists, Doka GmbH and PERI GmbH exemplify the capital-intensive tier with in-house production of laminated veneer lumber and proprietary panel-locking systems. ULMA Construcción Polska S.A. anchors the southern European equipment leasing vector. These three entities represent divergent strategic postures: captive supply chain control, technology-driven labor reduction, and rental-platform geographic expansion.
| Leading Market Players |
|---|
| Doka |
| PERI |
| ULMA |
| Acrow |
| The Heico Companies LLC |
| Outinord |
| MFE Formwork Technology Sdn.Bhd |
| Urtim Formwork and Scaffolding Systems |
| Waco International |
| Others |
Supply & Pricing Matrix
Municipal housing mandates in São Paulo and Mumbai specifying reusable formwork for projects exceeding 15 stories are compressing procurement timelines and forcing Baltic and Nordic suppliers to prioritize FSC-certified veneer feedstock, which elevates material costs for commodity plywood while rewarding engineered wood specialists with captive forestry assets.
Pricing Analysis
Reuse-cycle throughput anchors value-based pricing in wooden formwork systems. Three-tier pricing structure across premium, standard, and economy levels separates panel systems rated for 100-200 cycles from customized timber molds achieving 15-50 cycles and traditional solid sawn lumber for single-use applications. Cost compression in commodity plywood intensifies because REACH compliance expenses and Russian forest access restrictions have compressed available Baltic birch veneer feedstock. Residential contractors in Brazil and India exhibit highest price sensitivity, while German commercial developers absorbing EU Green Deal traceability premiums demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from German and French construction firms now mandate FSC-compliant Baltic and Nordic suppliers alongside secondary Southeast Asian feedstock channels. Laminated veneer lumber production draws from Finnish and Estonian mill capacity, phenolic resin binders, and rotary-peeled softwood veneer. Single-source vulnerability concentrates in Baltic birch plywood where Russian forest access restrictions have shifted 70 percent of export-grade marine plywood capacity to Finnish and Estonian control. Distribution runs through integrated construction service platforms bundling formwork with concrete supply and pumping logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Baltic birch plywood supply concentration represents the binding capacity constraint, with Finnish and Estonian mills controlling dominant export-grade marine plywood capacity and propping pricing power for engineered wood specialists against margin-compressed commodity suppliers.
For Market Incumbents: To counter aluminum table-form substitution in Chinese high-rise commercial segments, Doka and PERI should deepen backward integration into captive laminated veneer lumber supply from Baltic forestry assets while accelerating proprietary panel-locking system R&D to defend labor-hour reduction advantages on complex geometries. For New Entrants and Emerging Players: Robotic CNC milling capabilities for machine-cut LVL elements represent the most penetrable technology wedge, targeting Swiss and Japanese stadium contractors demanding precision tolerances for non-standard architectural concrete finishes with direct mill relationships bypassing traditional equipment distributors. For Investors and Strategic Acquirers: The window for entry favors engineered wood specialists with FSC chain-of-custody certification and digital material passport capabilities. Long-term viability hinges on 5-10 year EU Green Deal compliance positioning. The signal to monitor is accelerated rental platform consolidation in Poland and Czech Republic mid-tier contractor segments.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Forestry Asset Acquisition | Finnish and Estonian veneer feedstock control secures REACH-compliant supply for EU market access. |
| Robotic CNC Milling Deployment | Swiss and Japanese bridge contractors adopt machine-cut LVL to halve on-site adjustment labor. |
| Digital Material Passport Integration | German construction firms now require verified chain-of-custody documentation under EU Green Deal. |
| Rental Platform Geographic Expansion | Polish and Czech mid-tier contractors lack capital for owned inventory, driving leasing penetration. |
| Bio-Based Binder Retrofit | Finnish chemical suppliers commercialize lignin-derived resins meeting EN 13986 without petrochemicals. |
Research Methodology
Trade association filings, customs and import-export databases, and timber certification registries formed the secondary backbone, supplemented by primary interviews with formwork equipment lessors, laminated veneer lumber mill operators, municipal housing authority procurement directors, and general contractor project managers. Bottom-up and top-down triangulation validated volume estimates across product type, technology, application, and end user segmentation dimensions.
Bottom-up modeling anchored individual country-level demand assessments while top-down cross-checks applied macro construction spend correlations. Segmentation dimensions modeled include panel versus customized formwork types, laminated veneer lumber versus traditional timber technologies, residential versus infrastructure applications, and general contractor versus formwork supplier end users. CAGRs were derived from weighted average growth across these segments, incorporating urbanization rate trajectories, municipal housing mandate adoption curves, and engineered wood displacement patterns for solid sawn timber.
Several conditions sit outside the modeled scope, including unforeseen tariff escalations on Baltic plywood imports, abrupt REACH chemistry restriction amendments, and Chinese state contractor procurement shifts toward aluminum systems. Deviation in Baltic birch veneer feedstock availability or EU Green Deal traceability enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Wood Truss Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
North America Wood Based Panel Market
Building & Construction Materials
Glass Curtain Wall Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
Acoustic Plasterboard Market