
 Vitrified Tiles Market | 2026-2036
Vitrified Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Vitrified Tiles Market Intelligence
The scarcity of skilled labor for advanced tile installation is unwinding traditional distribution models, forcing a shift toward specialized training programs and simpler installation systems. Mohawk Industries leverages its extensive distribution network in North America to manage this complexity and educate contractors. In contrast, Kajaria Ceramics dominates the Indian market through deep relationships with local property developers. RAK Ceramics sustains its global position through large-scale manufacturing capacity serving major projects across the Middle East and Europe.
Vitrified tiles are a type of ceramic tile characterized by extremely low porosity, achieved through a high-temperature fusion process called vitrification. This manufacturing method imparts superior strength, abrasion resistance, and imperviousness to water, making the tiles suitable for demanding environments. Full body vitrified tiles command a premium due to their durability in high-traffic applications like airports and commercial complexes. Glazed porcelain tiles offer the widest aesthetic range, making them a preferred choice for interior designers working on hospitality and retail projects.
Product quality and market access are governed by a matrix of international standards. Compliance with ISO 13006 provides a baseline for global trade, while region-specific regulations like the EU's CE marking for construction products and India's BIS certification dictate market entry. These frameworks increasingly incorporate sustainability metrics, influencing material sourcing and production processes. Key strategic decisions for manufacturers now center on balancing investments in localized production against the economies of scale from centralized manufacturing hubs.
Market Dynamics
The vitrified tiles market is defined by the tension between rapid aesthetic innovation, enabled by digital printing, and the operational constraints of a fragmented, skill-dependent installation ecosystem. This dynamic shapes competition, distribution models, and investment priorities across the industry.
Growth Catalysts
- Government Housing Initiatives:Large-scale public housing programs, particularly in India under its national housing schemes, create consistent, high-volume demand for durable and cost-effective flooring solutions like vitrified tiles.
- Advanced Manufacturing Technology:Innovations in digital printing and vitrification processes allow manufacturers to produce tiles with superior design versatility and technical performance, unlocking new applications in premium commercial spaces.
- Infrastructure Expansion:Significant public and private investment in new airports, railway stations, and shopping malls across the Middle East and Asia requires flooring materials that can withstand extreme foot traffic.
Market Restraints
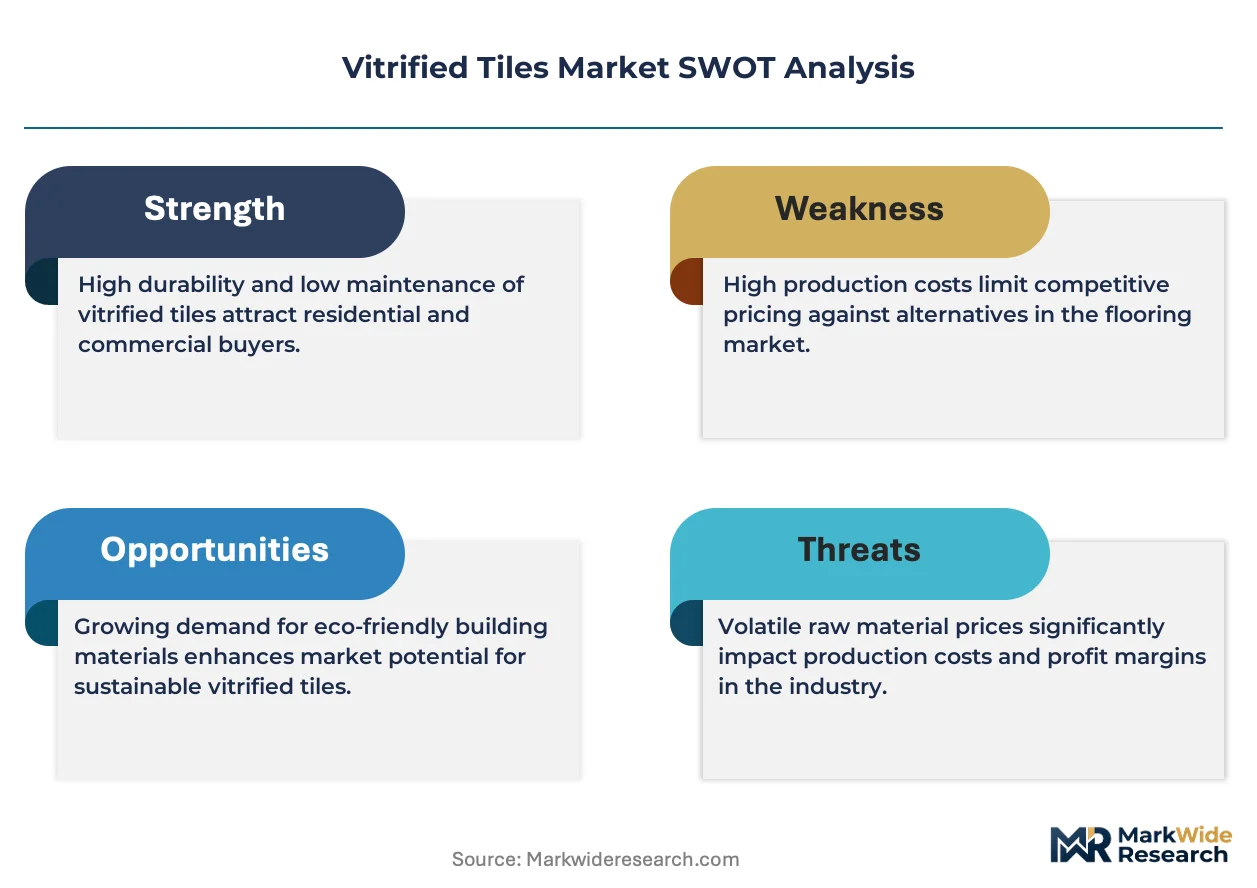
- Energy Price Volatility:The vitrification process is highly energy-intensive, making tile manufacturers' production costs and margins directly vulnerable to fluctuations in natural gas and electricity prices.
- Installation Skill Gap:The growing prevalence of large-format and technically complex tiles outpaces the availability of trained installers, leading to project delays and increased labor costs for property developers.
- High Logistics Costs:The weight and fragility of vitrified tiles result in substantial transportation, handling, and breakage expenses, which can erode profitability on long-distance and international shipments.
Strategic Opportunities
- Sustainable Product Lines:Developing tiles with high recycled content or produced via low-energy processes can capture demand from projects pursuing green building certifications like LEED and BREEAM.
- Functional Surface Coatings:Integrating value-added properties such as anti-microbial, anti-slip, or photocatalytic self-cleaning glazes creates premium product categories for healthcare, hospitality, and public facilities.
- Modular Installation Systems:The development of simplified, interlocking, or groutless tile systems can address installation bottlenecks and expand market reach into the residential renovation and do-it-yourself (DIY) segments.
Industry Challenges
- Regulatory Compliance Burden:Manufacturers face significant administrative overhead in managing a complex web of certifications, including the global ISO 13006 standard, the EU's CE marking, and India's BIS requirements.
- Intensive Capital Investment:Modernizing production lines with larger presses, high-definition digital printers, and energy-efficient kilns requires substantial capital expenditure, posing a barrier for smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitrified Tiles Market |
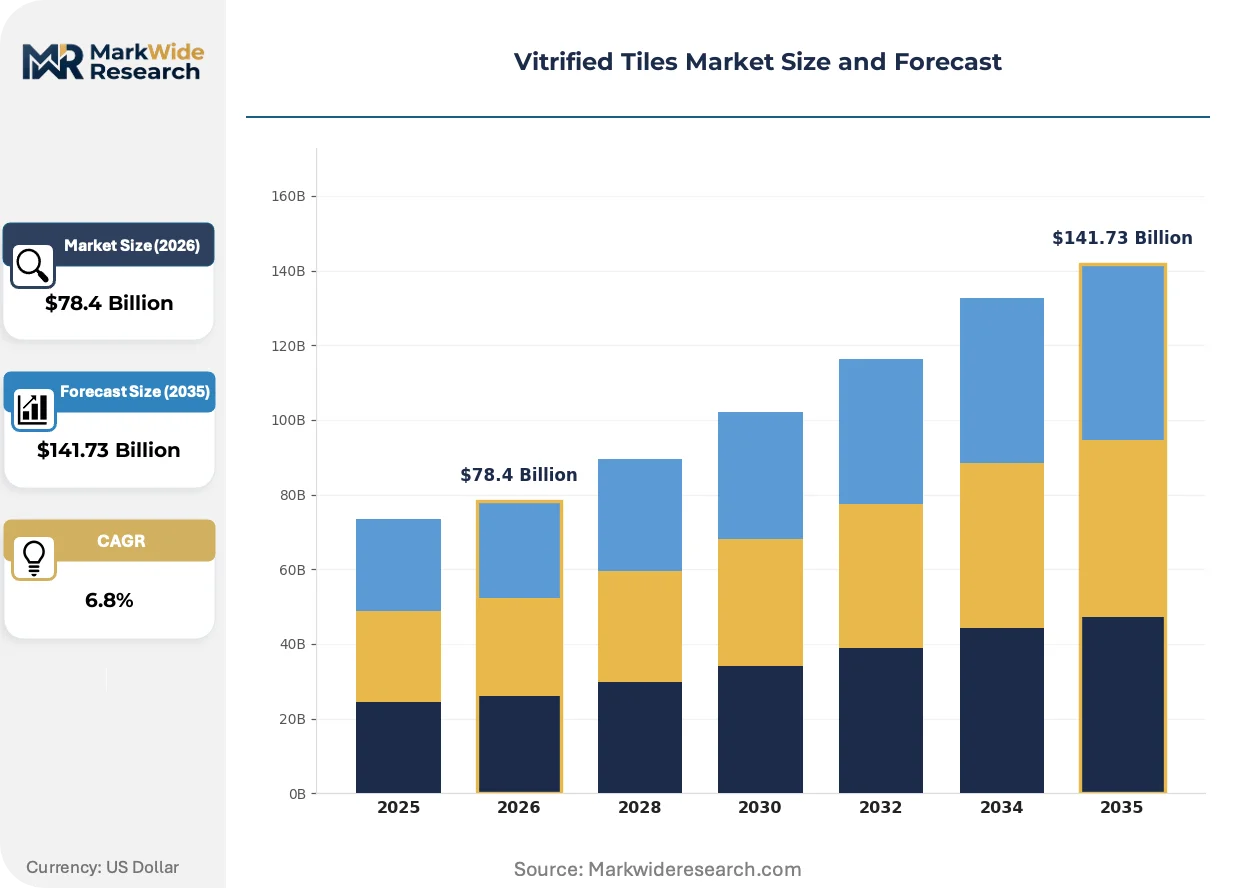
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Charged, Full Body, Glazed Porcelain, Soluble Salt, Sintered Application: Commercial Complexes, Airports, Educational Institutes, Hospitality, Public Infrastructure Installation Type: Dry Lay, Wet Lay, Adhesive Bonding, Floating, Interlocking End User: Property Developers, Construction Contractors, Interior Designers, Facility Managers |
| Companies Covered | Grupo Lamosa, Somany Ceramics, Mohawk Industries, Porcelanosa Grupo, Crossville Inc., RAK Ceramics, SCG Ceramics, Florim Ceramiche, Kajaria Ceramics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitrified Tiles Market Strategic Shifts & Innovations
The industrialization of aesthetics and performance is central to the vitrified tile market. Digital technologies are enabling mass customization and hyper-realistic designs, while sustainability mandates are forcing fundamental shifts in material science and production processes to meet new regulatory and consumer expectations.
Large-format slab tiles, with dimensions exceeding a meter, offer seamless and monolithic surface finishes. Architectural and design firms are rapidly adopting these slabs for wall cladding, countertops, and flooring in high-end commercial and hospitality projects. The adoption of these giant formats is displacing traditional 600x600mm tiles in premium applications, necessitating new handling equipment and specialized installation expertise on job sites.
Sustainability mandates are becoming a primary non-tariff barrier to trade, particularly in developed markets. The European Union's CE marking for construction products, increasingly linked to environmental performance data, compels manufacturers to document their product's life-cycle impact. Exporters targeting Europe are most affected, prompting investment in obtaining Environmental Product Declarations (EPDs) to prove compliance and maintain market access.
Specification-driven purchasing is altering traditional sales channels, especially in commercial construction. Instead of relying solely on distributors, manufacturers now engage directly with architects and interior designers early in the project lifecycle to have their products specified. This trend is most visible in North America and Europe, where design firms hold significant influence over material selection for large-scale hospitality, retail, and corporate projects.
Vitrified Tiles Market Segmentation
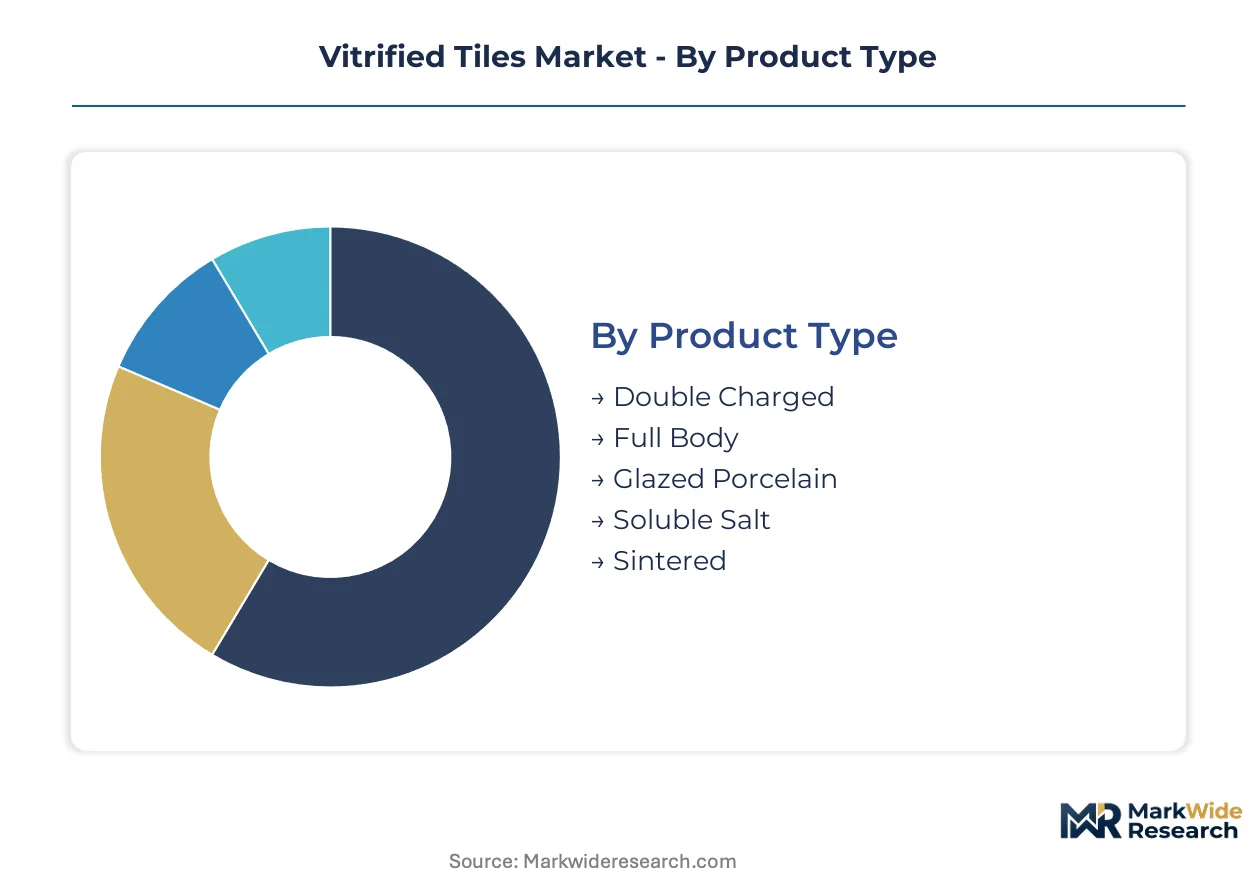
Understanding the segmentation of the vitrified tiles market is crucial for manufacturers to tailor product development and market entry strategies. Each segment presents unique material demands, installation complexities, and end-user expectations that influence product specifications and distribution channels.
Product Type:
Product substitution pressure is most evident in this category, as advancements in one tile type can directly impact the demand for another. Digital printing innovations, for instance, allow glazed porcelain to mimic natural stone, challenging traditional aesthetic choices.
- Full Body:These tiles feature uniform composition throughout their thickness, providing superior durability and resistance to wear, making them ideal for high-traffic environments. Demand concentrates in commercial complexes and public infrastructure projects in India and the Middle East, where longevity is paramount.
- Glazed Porcelain:Characterized by an impervious glaze layer over a porcelain body, these tiles offer extensive aesthetic versatility and are highly customizable through digital printing technology. Interior designers in hospitality and retail projects across Europe and North America frequently specify these for their design flexibility.
- Double Charged:These tiles are created by fusing two layers of vitrified material, providing enhanced wear resistance compared to basic vitrified tiles.
- Soluble Salt:Produced by infusing soluble salts into the tile surface, these offer a polished look but are generally less durable than full body or glazed options.
- Sintered:These tiles are formed from a mixture of natural minerals and clays, pressed and fired at high temperatures to create an extremely dense and non-porous material.
Double Charged retains significant volume leadership, while Glazed Porcelain holds the steepest expansion curve.
Application:
Market volume concentrates significantly within specific application sectors, influencing production scale and product characteristics. Projects requiring large quantities of standardized, durable flooring drive demand for specific vitrified tile types.
- Commercial Complexes:These applications require tiles that combine aesthetic appeal with high durability to withstand heavy foot traffic and frequent cleaning. Office buildings and shopping malls in rapidly urbanizing Asian markets frequently utilize vitrified tiles for their robust performance.
- Public Infrastructure:Airports, railway stations, and government buildings demand tiles with extreme abrasion resistance and low maintenance, suitable for continuous public use. Government-led projects in India and the Middle East consistently generate high-volume demand for these applications.
- Airports:These facilities require tiles capable of enduring extremely heavy foot traffic and luggage cart movement, prioritizing durability and slip resistance.
- Educational Institutes:Schools and universities need hard-wearing, easy-to-clean tiles that can withstand constant student activity and spills.
- Hospitality:Hotels and restaurants prioritize aesthetic appeal and stain resistance, often opting for glazed porcelain tiles that offer design flexibility.
Commercial Complexes generate the largest demand, with Public Infrastructure gaining share fastest.
Installation Type:
The complexity and skill requirements associated with different installation types significantly impact labor costs and project timelines. The availability of trained installers often dictates the feasibility of certain tile formats and installation methods.
- Wet Lay:This traditional method involves setting tiles in a cement-based mortar bed, requiring significant drying time and skilled labor. Cost-sensitive residential projects often employ this method due to its material economy.
- Adhesive Bonding:Modern tile adhesives provide strong, flexible bonds suitable for large-format and thin tiles, reducing drying times and enhancing performance. Commercial projects and premium residential installations increasingly rely on advanced adhesive systems.
- Dry Lay:This method uses pedestals or a sand bed, allowing for easier access to underfloor utilities and often used for outdoor applications or raised floors.
- Floating:Tiles are installed without being permanently adhered to the subfloor, common for some laminate or engineered flooring, but less so for traditional vitrified tiles.
- Interlocking:These systems feature tiles designed to mechanically lock together, simplifying installation and reducing the need for grout, appealing to DIY segments.
Wet Lay maintains its traditional market presence, while Adhesive Bonding is expanding most quickly.
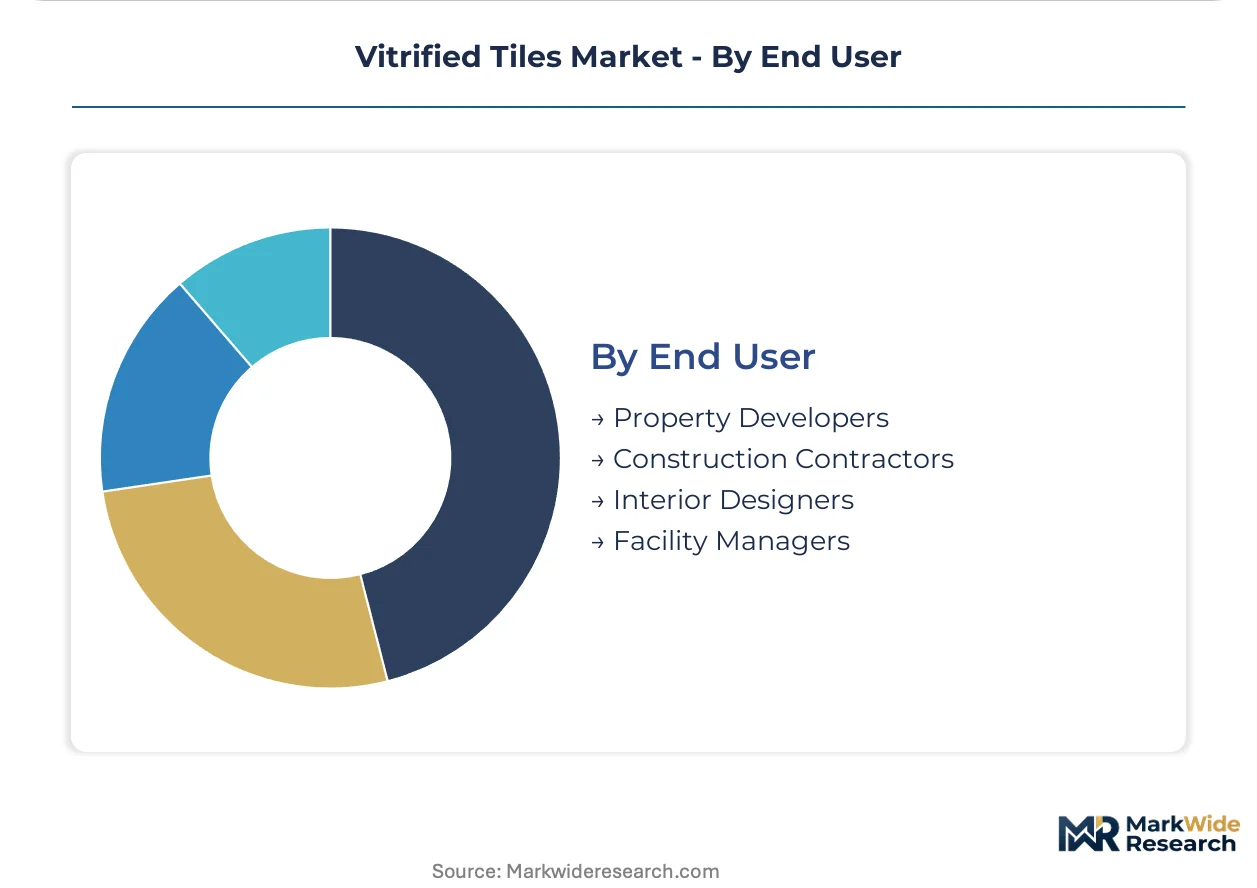
End User:
Procurement patterns vary considerably among end-user segments, influencing sales channels and product specifications. Engaging directly with architects and interior designers is now a critical sales strategy for manufacturers.
- Property Developers:These entities make bulk purchasing decisions for large-scale residential and commercial projects, focusing on cost-effectiveness, durability, and aesthetic consistency. Major housing initiatives in India represent a significant demand source for developers.
- Construction Contractors:Responsible for project execution, contractors prioritize ease of installation, material availability, and compliance with project specifications. They manage the on-site application of vitrified tiles across diverse projects.
- Interior Designers:These professionals influence material selection based on aesthetic vision, functional requirements, and client preferences, particularly for hospitality and high-end residential spaces.
- Facility Managers:Focused on long-term maintenance and operational costs, facility managers prioritize durable, easy-to-clean, and slip-resistant tile solutions for existing buildings.
Property Developers represent the largest purchasing segment, with Interior Designers increasingly influencing material choice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification provides a baseline for product quality in a market driven by significant urbanization. Government-led housing initiatives consistently generate high-volume demand for durable vitrified tiles. This demand concentration positions India as a pivotal market for manufacturers.
India
India's national housing schemes fuel consistent demand for vitrified tiles, particularly for cost-effective and durable flooring solutions. The BIS certification ensures product quality and market entry for manufacturers. Gujarat, home to the Morbi cluster, remains a significant production hub, supplying both domestic projects and international markets.
United Arab Emirates
Major infrastructure projects in the United Arab Emirates require robust flooring materials capable of withstanding extreme foot traffic. MOHAP regulations guide construction standards, while increasing sustainability mandates influence material selection. Dubai and Abu Dhabi lead in large-scale project procurement, driving demand for high-performance vitrified tiles.
Germany
The European Union's CE marking mandates environmental performance data for construction products in Germany, influencing material sourcing and production processes. Demand stems from premium commercial spaces and residential renovations, with a focus on sustainable product lines. Bavaria and North Rhine-Westphalia exhibit strong adoption of high-performance and aesthetically versatile vitrified tiles.
United States
Commercial construction in the United States drives the adoption of advanced tile systems, including large-format slab tiles for seamless surface finishes. ASTM standards ensure material quality and performance for various applications. Texas and California represent significant markets, with design firms increasingly specifying vitrified tiles for high-end hospitality and retail projects.
China
China's rapid urbanization continues to create substantial demand for vitrified tiles across residential and public infrastructure projects. GB standards regulate product quality and performance, while dual carbon goals increasingly influence manufacturing practices. Guangdong and Fujian provinces host massive manufacturing capacities, catering to vast domestic consumption and export markets.
Vitrified Tiles Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the vitrified tiles market. The industry exhibits a tiered structure, with global players focusing on innovation and regional specialists optimizing for local supply chains. Strategic archetypes include large-scale integrated manufacturers, design-focused premium brands, and cost-efficient volume producers. Companies frequently engage in capacity expansion and strategic partnerships to secure market share and deepen market access.
Among global manufacturers, Mohawk Industries and RAK Ceramics exemplify distinct strategic approaches within the vitrified tiles market. US-based Mohawk Industries leverages its extensive North American distribution network, focusing on contractor education to manage the complexities of advanced tile installation. UAE-based RAK Ceramics sustains its global position through large-scale manufacturing capacity, effectively serving major construction projects across the Middle East and European regions. India-based Kajaria Ceramics anchors its significant market share through deep relationships with local property developers, particularly in the consistent demand generated by national housing schemes. These players demonstrate the varied strategies employed to navigate market dynamics.
| Leading Market Players |
|---|
| Grupo Lamosa |
| Somany Ceramics |
| Mohawk Industries |
| Porcelanosa Grupo |
| Crossville Inc. |
| RAK Ceramics |
| SCG Ceramics |
| Florim Ceramiche |
| Kajaria Ceramics |
| Others |
Cost & Logistics Intelligence
Digital printing innovations, allowing glazed porcelain to mimic natural stone, are simultaneously reshaping supply geography towards specialized manufacturing hubs and impacting pricing economics by intensifying aesthetic competition. This dynamic influences material sourcing and production investments.
Pricing Analysis
Significant geographic price spreads exist for vitrified tiles, driven by regional demand and local production costs. Pricing stratifies across premium, standard, and economy tiers, influenced by quality grade, design complexity from digital printing, and compliance with certifications like EU's CE marking. Energy price volatility and high logistics costs create persistent pricing pressure. Property developers exhibit the highest price sensitivity, while interior designers prioritize aesthetic versatility.
Supply Chain Analysis
The vitrified tiles supply chain leans towards strategic stockpiling in major production hubs, balancing economies of scale with high logistics costs. Geographic supply concentrates heavily in India, China, and the UAE, drawing from abundant raw materials like clay and feldspar. Energy price volatility for natural gas poses a critical structural risk to manufacturing margins. Distribution runs through established networks, increasingly augmented by direct manufacturer engagement with architects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vitrified tiles market is increasingly constrained by the scarcity of skilled labor for advanced installation techniques, particularly for large-format tiles. This capability gap influences project feasibility and market expansion.
For Market Incumbents: Compound investments in installer training programs and modular installation systems to mitigate the growing installation skill gap. Leverage existing extensive distribution networks to educate contractors on new product formats and techniques. Prioritize R&D into simplified, interlocking tile systems to counter high logistics costs associated with fragility. Localized production investments can further protect market share against regional competitors.
For New Entrants and Emerging Players: Simplified installation solutions represent a significant service-layer gap where incumbents under-serve the residential renovation market. Target the DIY segment in North America and Europe with interlocking or groutless tile systems. Develop specialized functional surface coatings like anti-microbial glazes for niche healthcare and hospitality applications. Utilize direct-to-consumer online channels to bypass traditional distribution complexities.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with advanced digital printing capabilities or those leading in sustainable product development for long-term growth. Seek out firms with strong localized production facilities in urbanization-driven markets like India or the UAE. The market remains viable over the next decade due to persistent demand for durable, aesthetic surfaces. Watch for increased adoption rates of modular installation systems as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | This move capitalizes on consistent demand from government housing initiatives in India. |
| Green Manufacturing Transition | This initiative ensures compliance with EU CE marking and sustainability mandates in Europe. |
| Product Line Diversification | Developing functional surface coatings creates premium categories for healthcare and hospitality. |
| Digital Printing Investment | This enhances aesthetic versatility and mass customization for interior designers. |
| Installer Training Programs | Addressing the installation skill gap improves project timelines and reduces labor costs. |
Research Approach
Findings reconcile primary fieldwork against secondary review of international standards, regional regulations, and industry trade publications. We conducted interviews with property developers, construction contractors, interior designers, and facility managers across key markets. This approach employed both bottom-up market sizing and top-down validation. Data triangulation confirmed market dynamics and competitive landscapes.
Product type, application, installation type, end user, and regional regulatory environment constituted the core segmentation dimensions modeled. Compound Annual Growth Rates were derived through regression analysis and scenario modeling over the projection horizon. Key inputs included construction spending forecasts for commercial complexes and urbanization rates in emerging markets. Energy price projections also informed cost structure analysis.
Forecasts assume regulatory continuity in EU CE marking and India's BIS certification; material policy shifts would require re-modeling. Unforeseen energy price spikes or major geopolitical shifts impacting trade routes represent significant risk factors. Revision becomes warranted when installation technology adoption crosses critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Construction Sustainable Materials Market
Building & Construction Materials
Bamboo Engineered Wood Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Indonesia Ceramic Tiles Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
Composite Roof Shingle Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Construction Sealants Market