
 North America Steel Rebar Market | 2026-2036
North America Steel Rebar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Steel Rebar Market Intelligence
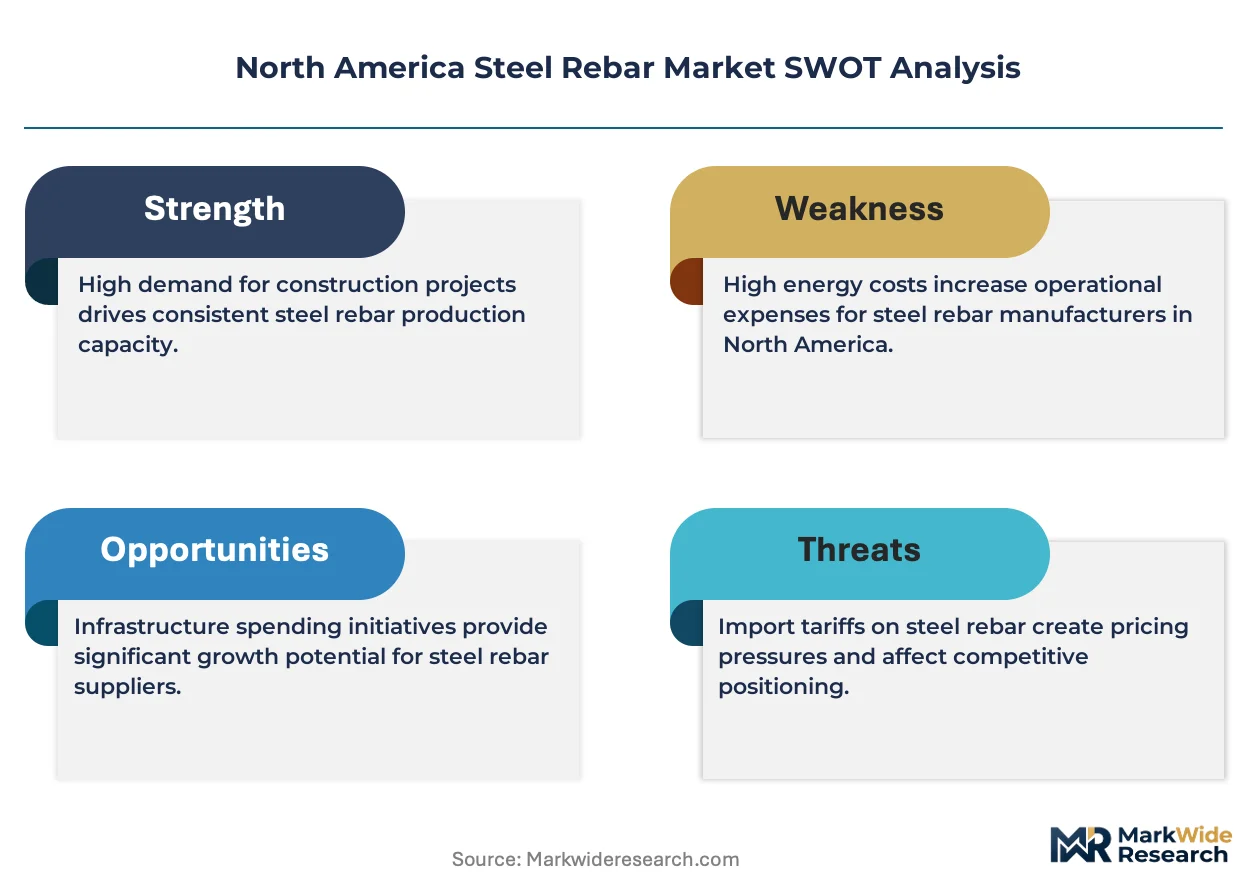
A shift from multi-source procurement to long-term partnerships with integrated domestic mills is realigning supply chain dynamics for large contractors. This trend favors scaled producers like Nucor Corporation, which leverages its electric arc furnace network for lower-emissions steel. Commercial Metals Company competes through its vertically integrated model of recycling, melting, and fabrication. Gerdau sustains its market position with a broad geographic footprint across the United States and Canada.
Steel rebar is a hot-rolled steel bar used as a tension device in reinforced concrete structures. These products, often specified to standards like ASTM A615 Grade 60, impart tensile strength to concrete, which is strong in compression but weak in tension. The infrastructure end-user segment constitutes the largest share of consumption, driven by public works. Within product types, epoxy-coated rebar sees significant use in bridges and marine environments for its corrosion resistance.
Market access and product specifications in the United States are heavily influenced by ASTM International standards for material properties. Federal projects often mandate compliance with Buy America provisions, favoring domestic steel producers. In Canada, national and provincial building codes govern rebar use in construction. Mill certification and material traceability are becoming critical decision factors for buyers navigating these complex sourcing requirements.
Market Dynamics
The convergence of domestic sourcing mandates and decarbonization goals is the central force shaping the North America steel rebar market. Public infrastructure investment, particularly through the US Infrastructure Investment and Jobs Act, is concentrating demand toward domestic, lower-emission electric arc furnace production.
Growth Catalysts
- Infrastructure Funding:Federally funded programs in the United States for highway, bridge, and water system renewal create sustained, large-volume demand for rebar, with specific requirements for domestically produced steel under Buy America provisions.
- Industrial Nearshoring:A trend of reshoring manufacturing activity stimulates new factory and warehouse construction, particularly in industrial corridors in northern Mexico and the US Southeast, driving demand for structural reinforcement.
- Resilient Construction Codes:Stricter building codes in coastal and seismic zones in the US and Canada mandate enhanced structural reinforcement, increasing the volume and specification grade of rebar required per project.
Market Restraints
- Input Cost Volatility:Mill profitability is sensitive to price fluctuations in key inputs like ferrous scrap and electricity, which are the primary cost components for the dominant electric arc furnace production method.
- Logistical Constraints:Limited railcar and flatbed truck capacity creates delivery bottlenecks and elevates freight costs, particularly for projects in remote or congested urban areas, impacting project timelines and budgets.
- Alternative Material Incursion:In specific applications like chemically corrosive environments or non-magnetic structures, glass fiber reinforced polymer (GFRP) rebar presents a niche substitution threat to traditional and epoxy-coated steel.
Strategic Opportunities
- Higher-Strength Steel Grades:Promoting the adoption of higher-strength rebar, such as ASTM A1035, offers opportunities to reduce material volume and project weight, creating value for engineers designing complex, high-performance structures.
- Digital Fabrication Integration:Offering services that integrate rebar detailing and fabrication directly with a project's Building Information Modeling (BIM) platform can create significant workflow efficiencies for large contractors.
- Green Building Certifications:Documenting the lower embodied carbon of EAF-produced rebar can secure preferential status with developers and public agencies targeting sustainability certifications like LEED for new construction projects.
Industry Challenges
- Skilled Labor Deficiencies:A persistent shortage of certified ironworkers and rebar fabricators across North America constrains the capacity to execute complex reinforcement projects, leading to labor cost inflation and potential delays.
- Traceability and Compliance Burden:The rigorous material traceability and mill certification paperwork required for federally funded projects in the US and Canada creates a significant administrative burden for suppliers and contractors.
- Capital Investment Cycles:The high capital expenditure required to build new melt shops or upgrade existing furnaces to improve efficiency and lower emissions presents a significant barrier to entry and a challenge for smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Steel Rebar Market |
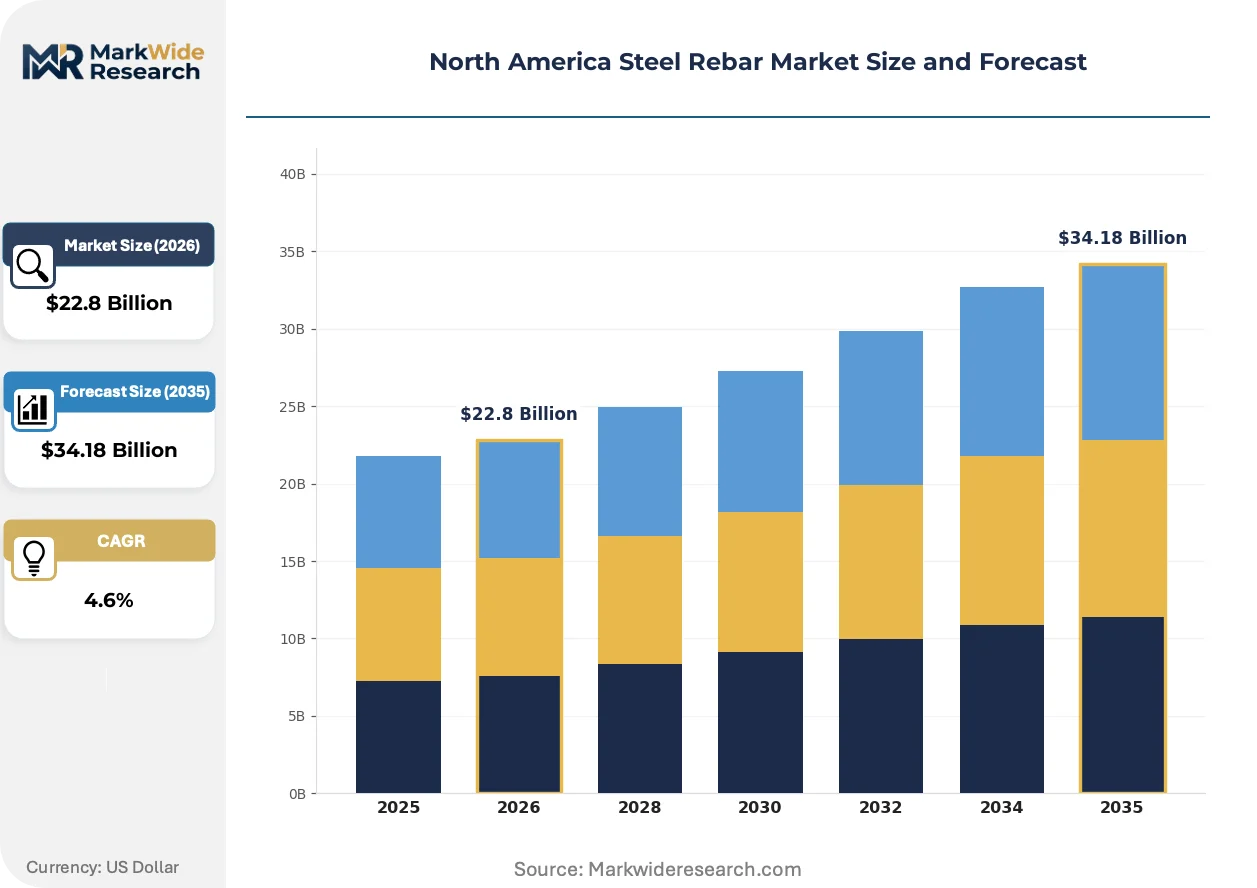
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $34.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy-Coated, Black Bar, Galvanized, Stainless Steel End User: Construction, Infrastructure, Commercial, Residential Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers Size: Standard Size, Custom Lengths, Small Diameter, Large Diameter |
| Companies Covered | Commercial Metals Company, Nippon Steel Corporation, Nucor Corporation, Schnitzer Steel Industries, EVRAZ North America, ArcelorMittal, Steel Dynamics, Liberty Steel USA, Gerdau, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Steel Rebar Market Strategic Shifts & Innovations
Supply chain resilience and product sustainability are the defining themes driving innovation in the North America steel rebar market. These twin pressures are altering material specifications, sourcing logic, and the integration of digital tools from the mill to the job site.
Higher-strength rebar grades are gaining traction in structural engineering. These advanced alloys, such as Grade 80 and Grade 100, allow for less steel tonnage to achieve required tensile strength. This technology is absorbing design share from standard Grade 60 products in high-rise commercial buildings and complex bridge projects, compressing overall material volume.
Buy America provisions within US federal legislation are reshaping supply chain strategies. This regulatory framework effectively creates a protected market for steel melted and fabricated within the United States for all federally funded infrastructure work. This is forcing a re-evaluation of import reliance, with public works contractors now prioritizing long-term agreements with certified domestic mills.
Sourcing behavior is evolving from project-specific transactional bids toward strategic, long-term partnerships between large contractors and integrated mills. This shift disrupts the traditional role of regional distributors who compete on spot availability. The trend is most pronounced in the US Southeast, where a high concentration of large, multi-year infrastructure projects makes stable, predictable supply a critical factor for contractors.
North America Steel Rebar Market Segmentation
The North America steel rebar market segmentation provides a granular view of product characteristics, end-user applications, and supply chain dynamics. Understanding these distinct categories helps stakeholders identify demand concentrations and strategic growth avenues. This detailed analysis supports targeted product development and market access strategies.
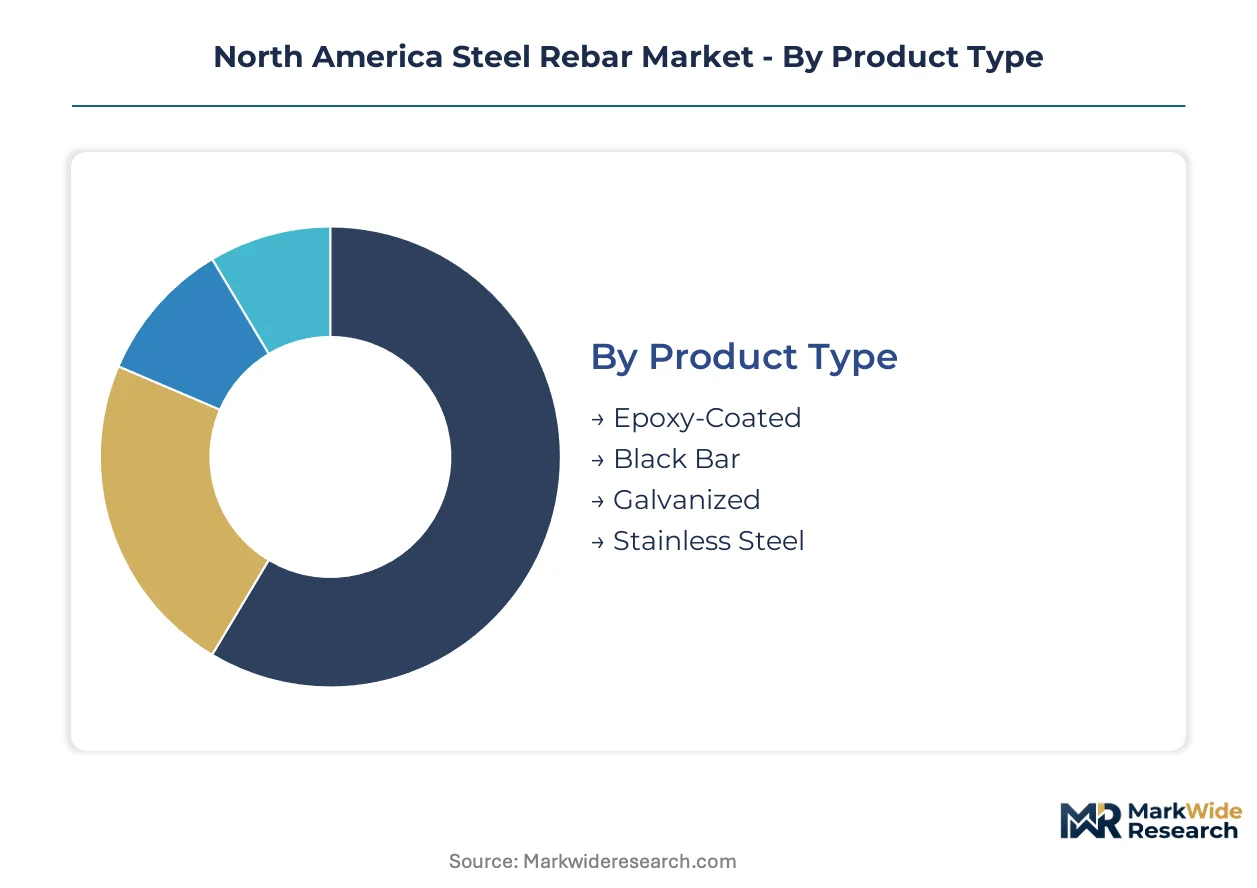
Product Type:
The steel rebar market in North America experiences demand driven by the continuous need for structural upgrades and replacements, influencing material choices across various product types.
- Epoxy-Coated:This rebar features a protective polymer coating applied to its surface, enhancing corrosion resistance in harsh environments. Demand concentrates in US federal infrastructure projects, particularly bridges and marine structures, where extended service life is critical.
- Black Bar:Standard hot-rolled steel rebar, typically specified to ASTM A615 Grade 60, provides fundamental tensile strength in concrete. Its widespread use in general construction and residential projects across the US and Canada makes it the highest volume product type.
- Galvanized:Zinc-coated rebar offers enhanced corrosion protection in specific applications, often utilized in projects requiring moderate resistance to corrosive elements.
- Stainless Steel:This high-alloy rebar provides superior corrosion resistance and non-magnetic properties, finding niche applications in highly aggressive chemical environments or sensitive scientific facilities.
Volume placements concentrate in Black Bar; the faster expansion belongs to Epoxy-Coated.
End User:
Rebar consumption patterns in North America are fundamentally shaped by the diverse requirements of various end-user applications, each demanding specific product attributes and volumes.
- Infrastructure:This segment encompasses public works projects like highways, bridges, dams, and water treatment facilities, representing the largest share of rebar consumption. US federal funding initiatives, particularly the Infrastructure Investment and Jobs Act, drive significant demand for domestically produced steel.
- Construction:This broad category includes both commercial and residential building activities, forming a substantial and consistent demand base for steel rebar. Growth in urban development and industrial nearshoring in the US Southeast fuels this segment's requirements.
- Commercial:Rebar demand from this segment stems from office buildings, retail centers, and industrial facilities, requiring structural reinforcement for large-scale developments.
- Residential:This segment includes single-family homes and multi-unit dwellings, where rebar provides foundational and structural integrity, particularly in seismic zones or for concrete slabs.
The market's largest share comes from Infrastructure, while Construction exhibits strong growth potential.
Distribution Channel:
Supply concentration within the North American market dictates how steel rebar reaches end-users, with channels optimized for volume, speed, or specialized project requirements.
- Direct Sales:Large integrated mills often engage in direct sales to major contractors or for significant infrastructure projects, fostering long-term partnerships and ensuring consistent supply. This channel is critical for projects with stringent specifications and high volume demands.
- Distributors:Regional distributors play a vital role in providing rebar to smaller contractors and for projects requiring varied quantities or quick turnaround. They manage inventory and offer localized delivery, especially for non-federally funded work in Canada and Mexico.
- Online Retail:This emerging channel caters to smaller orders and niche markets, offering convenience for project managers sourcing specific rebar types or accessories.
- Wholesalers:These entities typically purchase rebar in bulk from mills and resell to distributors or larger fabricators, serving as an intermediate link in the supply chain for various project sizes.
Dominant volume flows through Direct Sales, with Distributors offering crucial regional market access.
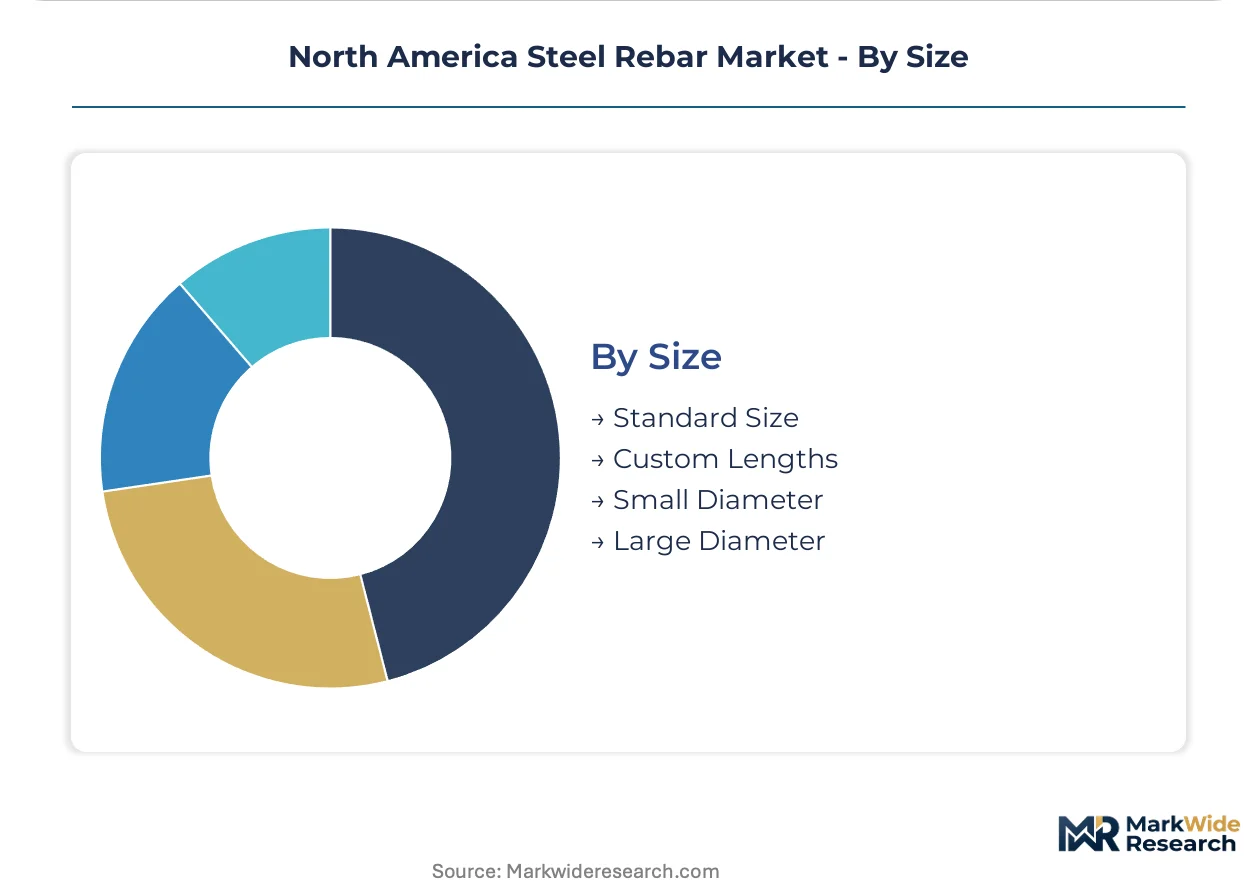
Size:
The volume of rebar required for projects across North America varies significantly, leading to distinct market segments based on rebar dimensions and fabrication needs.
- Standard Size:This segment includes commonly available rebar diameters and lengths, such as #4, #5, and #6 bars, widely used in residential and general commercial construction. These sizes meet the bulk of everyday structural reinforcement needs across the US and Canada.
- Custom Lengths:Fabricated rebar cut to precise project specifications, reducing on-site waste and labor, represents a growing segment. This is particularly valuable for complex high-rise structures and advanced infrastructure designs in urban centers.
- Small Diameter:Rebar with smaller cross-sections, like #3 or #4, is often used in lighter concrete elements, precast applications, or for stirrups and ties in larger structures.
- Large Diameter:Heavier rebar, such as #10 or #11, is critical for massive concrete foundations, bridge piers, and high-load bearing structures, providing maximum tensile reinforcement.
The majority of projects utilize Standard Size, while Custom Lengths address niche, high-performance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The steel rebar market in North America is significantly influenced by the abundant availability of ferrous scrap, a primary input for electric arc furnaces. This dynamic supports robust production across the United States, Canada, and Mexico. Infrastructure investment and industrial nearshoring drive demand in these key geographies.
United States
Demand for rebar in the United States is primarily driven by extensive public works projects, including highway and bridge repair. The US Infrastructure Investment and Jobs Act mandates the use of domestically produced steel, channeling significant demand to local mills. Key manufacturing and infrastructure hubs across the US Southeast, such as Atlanta and Charlotte, are experiencing concentrated demand for structural reinforcement.
Canada
Canada's rebar consumption is shaped by national and provincial building codes, alongside sustained urban development and residential construction. Health Canada regulations influence material specifications for certain public structures, ensuring safety and durability. Major urban centers like Toronto and Vancouver continue to anchor significant construction activity, requiring consistent rebar supply for high-rise and commercial projects.
Mexico
Mexico experiences substantial rebar demand from industrial nearshoring trends, which stimulate new factory and warehouse construction. Trade agreements like USMCA influence sourcing strategies, favoring regional supply chains for construction materials. The industrial corridors of Northern Mexico, particularly around Monterrey and Tijuana, are seeing rapid expansion of manufacturing facilities, boosting rebar consumption.
US Southeast
The US Southeast region benefits from a surge in manufacturing and warehouse construction, propelled by industrial nearshoring and population growth. State-level economic development incentives attract large-scale projects, increasing demand for structural steel. Cities like Austin and Raleigh are becoming significant hubs for new industrial and commercial developments, requiring substantial rebar volumes.
Northern Mexico
Northern Mexico's rebar market is directly impacted by cross-border trade facilities and the expansion of the automotive and electronics manufacturing sectors. Special economic zones and favorable investment policies encourage foreign direct investment in industrial infrastructure. The border cities of Ciudad Juarez and Reynosa are experiencing concentrated construction of production plants and logistics centers, driving rebar demand.
North America Steel Rebar Market Key Industry Players
Capacity expansion dominates the current landscape as producers respond to heightened infrastructure demand and domestic sourcing mandates across North America. The market exhibits a tiered structure, with large integrated mills competing alongside specialized fabricators and regional distributors. Scaled producers and vertically integrated firms represent key strategic archetypes, focusing on efficiency and supply chain control. Long-term partnerships with major contractors are a prevalent competitive move, ensuring consistent supply for large-scale projects.
At the scale-driven end, Nucor Corporation exemplifies a major producer leveraging its extensive electric arc furnace network for lower-emissions steel production, particularly attractive to projects with sustainability goals. Commercial Metals Company occupies a vertically integrated position, controlling recycling, melting, and fabrication processes, which provides supply chain stability and cost control. Gerdau, with its broad geographic footprint across the United States and Canada, anchors a diversified market presence, enabling it to serve a wide range of regional projects and customer segments. These firms collectively represent the competitive dynamics influenced by domestic sourcing mandates and demand for consistent, high-volume supply.
| Leading Market Players |
|---|
| Commercial Metals Company |
| Nippon Steel Corporation |
| Nucor Corporation |
| Schnitzer Steel Industries |
| EVRAZ North America |
| ArcelorMittal |
| Steel Dynamics |
| Liberty Steel USA |
| Gerdau |
| Others |
Cost & Logistics Intelligence
US federal infrastructure projects drive significant demand, concentrating procurement towards long-term contracts with domestic mills. This shift influences pricing dynamics, favoring stability over spot market volatility for large-volume purchases.
Pricing Analysis
Bundling of mill certifications and material traceability with rebar orders influences pricing structures. The market primarily operates on a hybrid model combining contract-based long-term offtake for large projects and transactional spot pricing for smaller, regional needs. Price differentiation stems from product specification (e.g., ASTM A1035 vs. A615 Grade 60) and the cost of last-mile delivery to remote sites. Pricing pressure often stems from input cost volatility in ferrous scrap and electricity. Residential and smaller commercial contractors typically exhibit higher price sensitivity compared to large infrastructure developers.
Supply Chain Analysis
Reverse logistics for steel rebar primarily involves scrap collection and recycling, feeding back into electric arc furnace production. Geographic supply concentration centers in the United States, Canada, and Mexico due to domestic production mandates. The industry relies on ferrous scrap and electricity as primary raw material and energy inputs. Logistics chokepoints, particularly limited railcar and flatbed truck capacity, present a structural supply chain risk. Distribution runs through direct sales channels for major contractors and regional distributors providing localized inventory and delivery services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America steel rebar market operates under significant supply constraints. Skilled labor deficiencies in fabrication and limited logistics capacity for delivery are propping up project costs.
For Market Incumbents:Anticipate continued demand for domestically produced, lower-emission rebar. Expand electric arc furnace capacity in high-growth regions like the US Southeast and northern Mexico to meet sustained infrastructure investment. Deepen vertical integration into fabrication services to control quality and project timelines, mitigating skilled labor deficiencies. Invest in digital fabrication integration to streamline workflows and reduce on-site waste, countering alternative material incursions.
For New Entrants and Emerging Players:Begin with specialized product offerings targeting niche applications or underserved geographies. Focus on higher-strength steel grades like ASTM A1035 for complex engineering projects, offering material volume reduction benefits. Target regions with high construction activity but less integrated supply chains, such as specific industrial corridors in northern Mexico. Leverage rapid delivery models for smaller commercial and residential projects, providing agility against larger incumbents.
For Investors and Strategic Acquirers:The window for entry favors strategic acquisitions of well-positioned regional fabricators or EAF producers. Focus on companies with strong domestic mill certifications and established long-term contractor relationships. The market offers sustained demand over the coming decade due to ongoing infrastructure renewal and industrial nearshoring trends. Monitor shifts in federal funding allocation and new melt shop announcements as key inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in EAF Production | Increases domestic supply of lower-emission steel to meet Buy America mandates and sustainability goals. |
| Digital Fabrication Integration | Enhances workflow efficiency for contractors and reduces on-site material waste in complex projects. |
| Long-term Supply Agreements | Secures stable material access for major infrastructure projects, mitigating price volatility and supply risk. |
| Higher-Strength Steel Grade Development | Offers engineers material volume reduction and weight savings for high-performance structural designs. |
| Logistics Network Optimization | Addresses delivery bottlenecks and reduces freight costs, improving project timelines and budget adherence. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. The study integrated insights from primary interviews with project engineers, procurement managers at large contractors, mill operations directors, and rebar fabricators. This approach ensured a robust understanding of market dynamics, triangulating quantitative data with qualitative stakeholder perspectives from both bottom-up and top-down perspectives.
The analytical framework reconciled multiple data streams, integrating historical demand, supply-side capacity, and regulatory impacts across the analysis window. Segmentation dimensions modeled included product type, end-user, distribution channel, rebar size, and regional infrastructure spending. Compound Annual Growth Rates were derived from a weighted average of historical growth trends and projected future demand drivers, using infrastructure spending forecasts, EAF production capacity, and construction permit volumes as key inputs.
Geopolitical events impacting raw material costs, shifts in federal infrastructure funding, and unforeseen logistical disruptions are the dominant revision risks for future projections. Forecasts reflect assumptions regarding current policy environments and technological adoption rates. Practitioners should monitor changes in government spending, scrap metal prices, and key transportation indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Middle-East and Africa Gypsum Board Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
Slimline Aluminum Window System Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Global Wood Cement Boards Market